
 Industrial Mezzanines Market | 2026-2036
Industrial Mezzanines Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Mezzanines Market Intelligence
Heavy-duty load-rated specifications is reorganizing competitive dynamics among industrial mezzanine fabricators. Mecalux leverages integrated rack-and-platform engineering across European and North American distribution networks. SSI Schäfer sustains automation-ready mezzanine configurations that accommodate robotic picking systems. Jungheinrich AG anchors its position through material-handling ecosystem bundling with elevated storage platforms.
An industrial mezzanine is a semi-permanent elevated platform structure, typically fabricated from structural steel with 125 psf to 250 psf live-load ratings, designed to create intermediate floor levels within existing warehouse or manufacturing volumes without building expansion. Its primary purpose is to multiply usable square footage vertically while preserving ground-level workflow continuity. Engineered systems command premium positioning due to seismic and dynamic-load certification requirements in high-throughput distribution environments. Modular mezzanines compete on deployment velocity, with standardized bolt-together frames reducing installation cycles versus welded alternatives. Steel dominates material selection for load-bearing columns and decking substrates, though aluminum gains specification in clean-room pharmaceutical and electronics OEM settings where corrosion resistance and reduced dead load matter.
OSHA walking-working surface standards, ANSI MH28.3 mezzanine design guidelines, and IBC seismic provisions govern structural design, guardrail integrity, and stair access configurations across US installations. European markets operate under EN 15512 rack standards and CE-marked structural compliance through ECHA material safety declarations. Stakeholders must monitor evolving fire-code interpretations regarding mezzanine sprinkler coverage and egress path requirements as jurisdictions tighten enforcement on multi-level occupancy classifications.
Market Dynamics
Modular bolt-together fabrication is displacing welded construction across warehouse and distribution center specifications, compressing installation timelines from weeks to days while forcing legacy fabricators to retool production lines or cede mid-market volume to standardized system suppliers.
Growth Catalysts
- E-commerce fulfillment densification:Third-party logistics operators in Texas, California, and Illinois are specifying multi-tier mezzanine configurations to maximize cube utilization within existing building envelopes.
- OSHA walking-working surface mandates:Tighter guardrail and stair access requirements are accelerating replacement cycles for pre-2017 installations across US manufacturing and warehousing facilities.
- Steel decking automation:Robotic welding and CNC punching of structural components is reducing per-square-foot fabrication costs for standardized frame modules.
Market Restraints
- Structural steel price volatility:Hot-rolled coil and wide-flange beam input costs fluctuate with scrap metal and energy pricing, compressing fabricator margins on fixed-price contracts.
- Seismic engineering concentration:Certified structural engineers capable of IBC Chapter 16 compliance are concentrated in California, Texas, and Illinois, creating bottlenecks for complex installations elsewhere.
- Permanent building alternative:Tilt-up concrete construction competes for multi-level expansion projects where lease terms exceed fifteen years and capital budgets permit ground-up development.
Strategic Opportunities
- Pharmaceutical clean-room specification:Aluminum-framed mezzanine systems with powder-coated finishes are penetrating FDA-regulated aseptic processing facilities where corrosion resistance and washdown compatibility matter.
- Automation-ready platform design:Integration of robotic picking system foundations and power/data raceways into mezzanine substructures creates attach rate for material-handling OEMs.
- IRA clean energy manufacturing:Battery cell and solar module production facilities qualify for federal tax credits that subsidize vertical expansion infrastructure including elevated work platforms.
Industry Challenges
- Multi-jurisdictional fire code interpretation:Sprinkler coverage requirements and egress path classifications vary across municipal authorities, delaying permit approval for multi-level occupancy designs.
- Structural engineer talent scarcity:Firms capable of dynamic load analysis for automated storage and retrieval system integration command premium fees and extended lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Mezzanines Market |
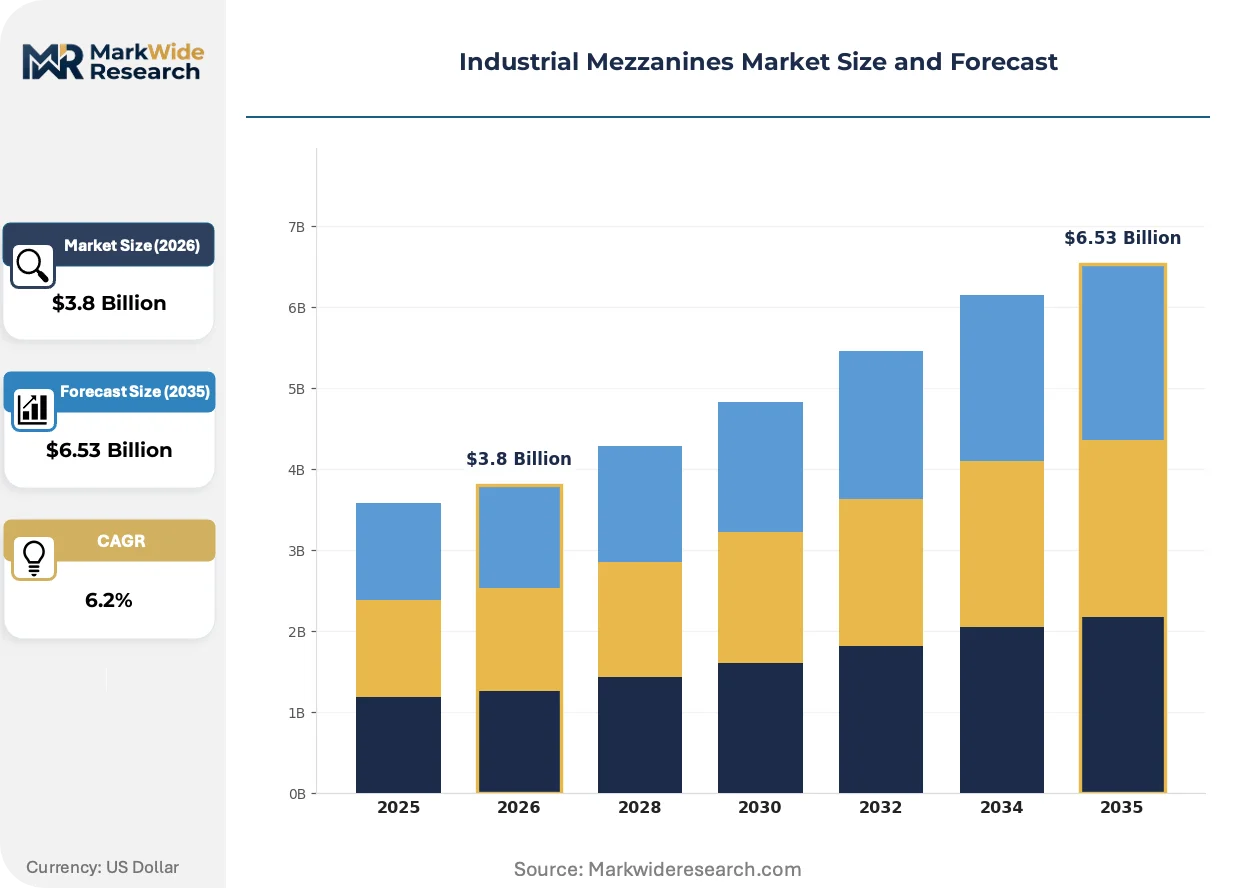
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Mezzanines, Engineered Systems, Buy-Standard Mezzanines, Custom Mezzanines Material Type: Steel, Aluminum, Fiberglass, Composite, Stainless Steel Application: Warehousing, Manufacturing Facilities, Distribution Centers, Packaging Units, Cold Storage End User Industry: Automotive OEMs, Electronics OEMs, Food & Beverage Plants, Pharmaceuticals, Textile Production |
| Companies Covered | Mecalux, SSI Schäfer, Jungheinrich AG, Stanley Black & Decker, Interlake Mecalux, Schaefer Systems International, Inc., MiTek Mezzanine Systems, Gonvarri Material Handling, Steel King Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Mezzanines Market Strategic Shifts & Innovations
Three forces are reshaping how elevated platform systems are engineered, procured, and deployed: aluminum alloys penetrating corrosion-sensitive environments, seismic and dynamic-load certification tightening specification thresholds, and buyer procurement models compressing vendor selection cycles.
Aluminum structural framing is fragmenting traditional steel dominance in pharmaceutical, electronics, and food processing installations where reduced dead load and washdown compatibility justify material cost premiums. Clean-room OEMs in California and Massachusetts are specifying anodized aluminum columns and decking substrates to eliminate rust particulate contamination. This shift is fragmenting the supplier base, as aluminum fabrication requires distinct welding certifications and extrusion sourcing relationships that incumbent steel specialists lack.
OSHA's updated walking-working surface standards and ANSI MH28.3 design guidelines are mandating higher guardrail load ratings and integrated stair access configurations across US installations. Fabricators must now engineer systems for 200-pound concentrated loads at top rails and midrails, eliminating lighter-duty designs from compliant bids. Distribution centers in Texas and Illinois are responding by bundling mezzanine procurement with third-party structural certification services to accelerate permit approval.
Buyers are compressing vendor qualification timelines through pre-engineered system catalogs with validated load tables and standardized connection details. E-commerce fulfillment operators are bypassing traditional design-build contracts in favor of configured-to-order platforms with guaranteed seismic performance ratings. This pattern is most visible among third-party logistics providers operating multi-site networks where replication speed outweighs customization flexibility.
Industrial Mezzanines Market Segmentation
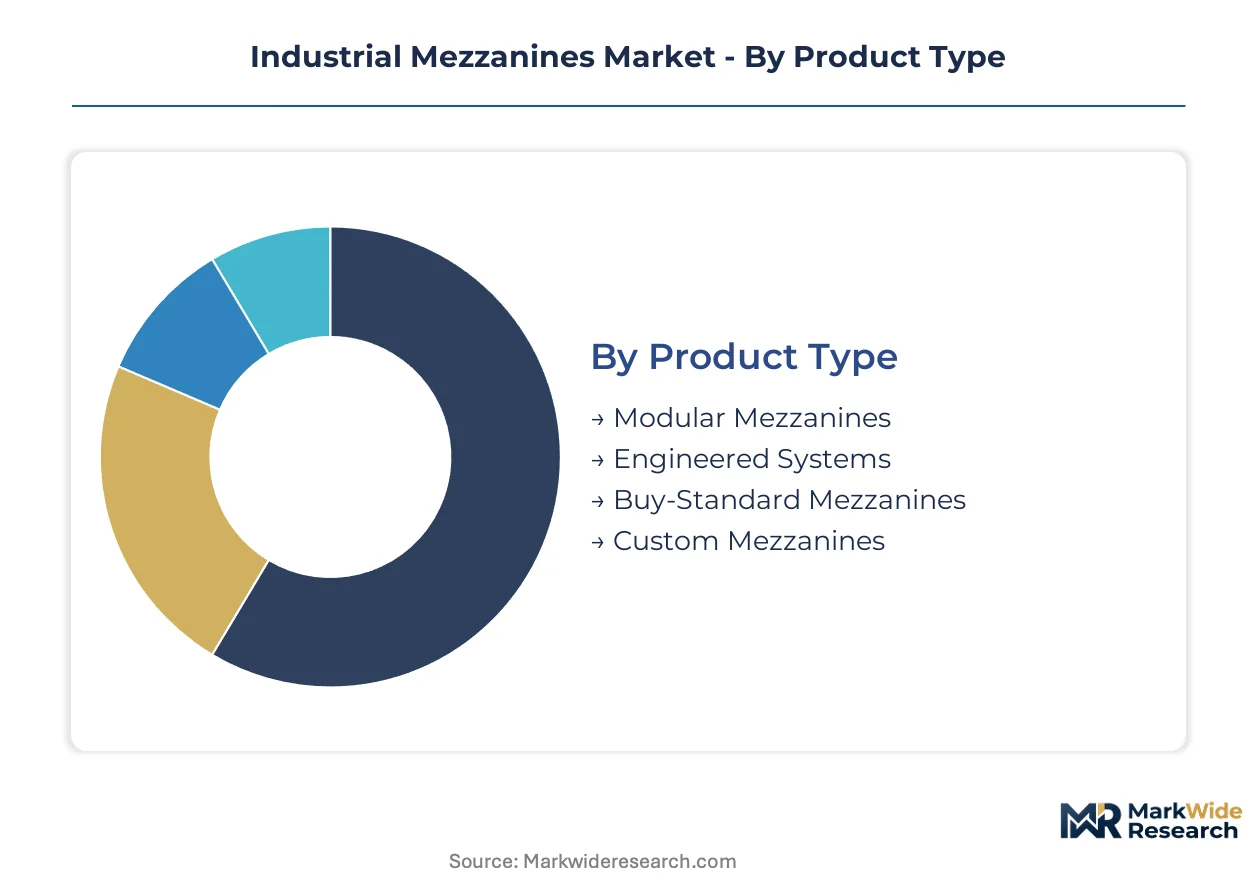
Industrial mezzanine procurement patterns diverge sharply across product architecture, material specification, and end-use intensity. Buyers in high-throughput distribution and regulated manufacturing environments weight seismic certification, washdown compatibility, and automation integration differently, fragmenting vendor positioning and margin capture across segment boundaries.
Product Type:
Margin pools concentrate in engineered systems where structural certification and dynamic-load analysis command premium pricing, while modular platforms compete on deployment velocity and replication economics.
- Modular Mezzanines:Standardized bolt-together frames with pre-engineered connection details compress installation cycles from weeks to days. Third-party logistics operators in Texas and California specify these for multi-site network rollouts where speed-to-occupancy outweighs customization flexibility.
- Engineered Systems:Custom structural steel platforms with IBC Chapter 16 seismic compliance and ASCE 7 dynamic-load certification. Certified structural engineers in Illinois and Texas command fees exceeding standard design-build contracts for complex automated storage integration.
- Buy-Standard Mezzanines:Catalog-configured platforms with validated load tables for rapid procurement. E-commerce fulfillment centers bypass traditional bidding processes through pre-approved vendor lists.
- Custom Mezzanines:Application-specific designs accommodating irregular column spacing or integrated conveyor foundations. Pharmaceutical clean-room OEMs in Massachusetts specify anodized finishes and sealed joints for aseptic processing environments.
Engineered systems hold installed capacity. Modular mezzanines are rotating up the share rankings.
Material Type:
Cost tier stratification separates commodity steel from corrosion-resistant alloys where FDA and USDA washdown mandates justify material premiums.
- Steel:Hot-rolled wide-flange columns and open-web steel decking dominate load-bearing specifications. Structural steel price volatility tied to scrap metal and energy markets compresses fabricator margins on fixed-price contracts.
- Aluminum:Extruded structural framing with anodized or powder-coated finishes penetrates electronics and pharmaceutical installations. Reduced dead load and rust particulate elimination command 40-60% material cost premiums over steel equivalents.
- Fiberglass:Pultruded profiles with electrical non-conductivity for utility and chemical processing environments. Niche specification where spark resistance and chemical corrosion matter.
- Composite:Hybrid material systems combining fiber-reinforced polymers with metal connection hardware. Emerging specification for weight-sensitive retrofits in aged industrial buildings.
- Stainless Steel:304 and 316-grade structural members for food processing and pharmaceutical aseptic zones. USDA and FDA sanitary design guidelines mandate washdown-compatible substrates.
Steel dominates volume shipments. Aluminum is climbing the fastest among corrosion-sensitive applications.
Application:
Customer type intensity varies by operational throughput, with distribution centers demanding automation-ready substructures and cold storage requiring thermal bridge mitigation.
- Warehousing:Multi-tier elevated platforms for pallet storage and case-pick operations. OSHA walking-working surface mandates accelerate replacement cycles for pre-2017 guardrail installations.
- Manufacturing Facilities:Production mezzanines integrating assembly lines, quality stations, and tool cribs. Automotive OEMs in Michigan and Ohio specify heavy-duty 250 psf live-load ratings for concentrated equipment footprints.
- Distribution Centers:Automation-ready platforms with embedded power raceways and robotic picking foundations. Third-party logistics corridors in Illinois and California drive specification for seismic-certified multi-level configurations.
- Packaging Units:Elevated work platforms for case erection, void fill, and manifesting operations. Lower load requirements permit lighter-gauge decking and reduced structural engineering costs.
- Cold Storage:Thermally broken connections and insulated decking substrates to minimize condensation. Refrigerated facilities in Wisconsin and Pennsylvania prioritize thermal performance over standard steel specifications.
Distribution centers anchor current demand. Cold storage is expanding most quickly among temperature-controlled supply chain investments.
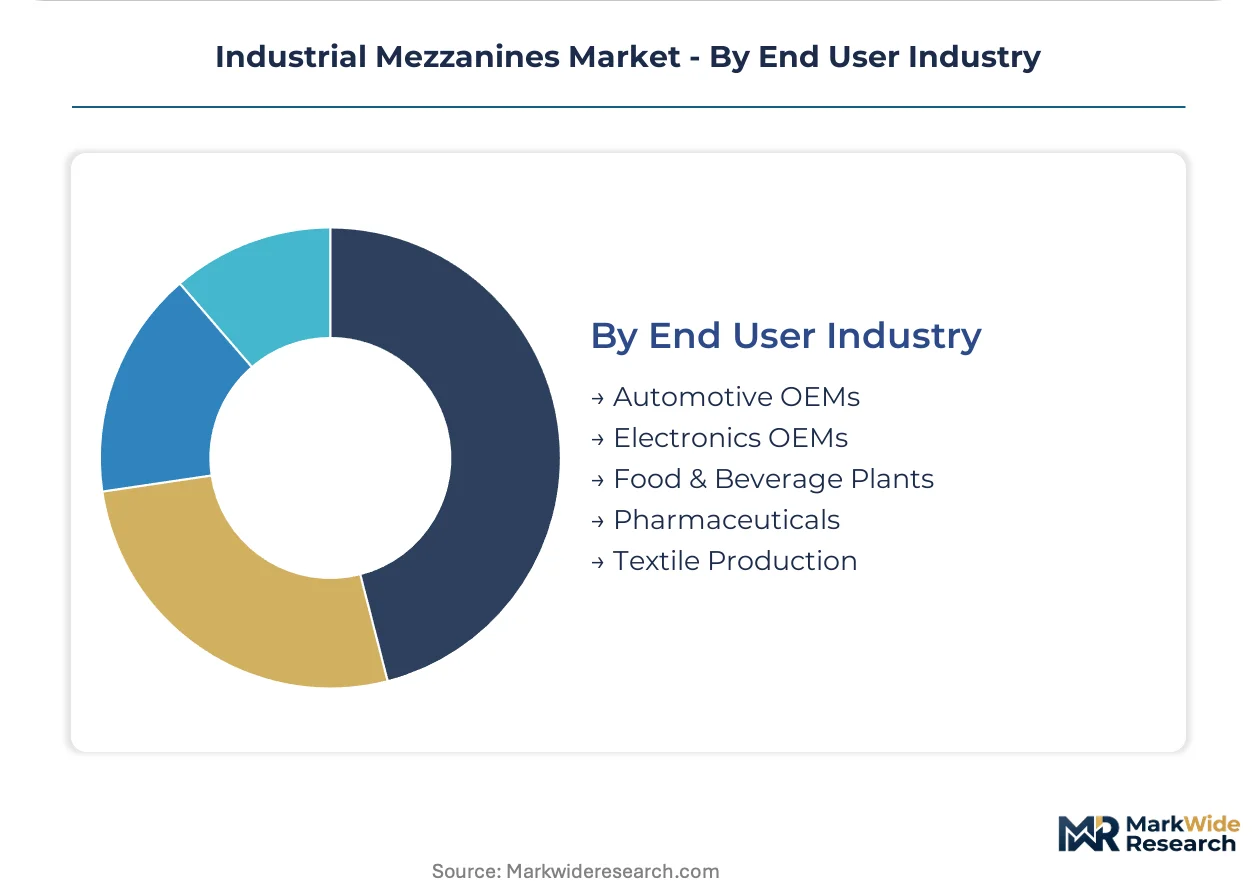
End User Industry:
Maturity differentiation separates regulated pharmaceutical environments with FDA validation requirements from automotive volume plays with standardized specifications.
- Automotive OEMs:Heavy-duty platforms supporting stamping dies, welding cells, and subassembly conveyors. Just-in-time production schedules demand rapid-install modular systems with minimal floor disruption.
- Electronics OEMs:Clean-room-compatible aluminum framing with electrostatic discharge grounding. California and Massachusetts facilities specify anodized finishes to eliminate particulate contamination.
- Food & Beverage Plants:USDA-compliant stainless steel or aluminum systems with sloped decking for drainage. Washdown compatibility and sanitary design override initial cost considerations.
- Pharmaceuticals:FDA-regulated aseptic processing mezzanines with cGMP documentation and material traceability. Certificate of analysis requirements for structural steel and aluminum extrusions extend procurement cycles.
- Textile Production:Elevated platforms for loom maintenance access and yarn storage. Lower regulatory burden permits standard steel specifications with basic OSHA compliance.
Automotive OEMs hold legacy installed base. Pharmaceuticals is gaining share fastest on clean-room infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in structural steel mezzanine components favor domestic fabrication hubs serving regional logistics corridors. Net importers cluster in markets lacking certified seismic engineering capacity. Trade balances shift with raw material cost differentials and lead-time pressures from e-commerce fulfillment buildouts.
United States
Third-party logistics operators in Texas, California, and Illinois drive specification for multi-tier configurations maximizing cube utilization within existing envelopes. OSHA walking-working surface mandates accelerate replacement cycles for pre-2017 guardrail installations. Chicago-area fabricators report bottlenecks from concentrated demand for IBC Chapter 16 seismic certification.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify heavy-duty platforms supporting stamping dies and subassembly conveyors. CE marking under EN 15512 rack standards governs structural compliance through ECHA material safety declarations. Stuttgart industrial parks anchor automated storage integration projects requiring dynamic-load engineering.
China
Battery cell and solar module production facilities qualify for federal tax credits subsidizing vertical expansion infrastructure. GB standards and MIIT industrial policy shape domestic specification thresholds. Yangtze River Delta logistics hubs concentrate demand for rapid-install modular systems serving cross-border e-commerce fulfillment.
Japan
Electronics OEMs in Kanto and Kansai regions specify clean-room-compatible aluminum framing with electrostatic discharge grounding. METI industrial efficiency programs incentivize vertical space utilization in aging manufacturing facilities. Nagoya automotive clusters drive specification for just-in-time production platforms with minimal floor disruption.
India
Third-party logistics corridors in Maharashtra and Karnataka specify modular bolt-together frames for multi-site network rollouts. BIS structural standards and state-level industrial corridor programs accelerate warehouse densification. Mumbai-Pune logistics belt reports rising demand for automation-ready platforms with embedded power raceways.
Industrial Mezzanines Market Key Industry Players
Concentration sits with integrated material-handling specialists and dedicated structural fabricators competing across distinct value tiers. The vendor base separates into seismic-certified engineered system providers, velocity-focused modular suppliers, and automation-ready platform integrators. Strategic moves center on backward integration into steel fabrication capacity and geographic expansion through distribution partnerships serving multi-site logistics networks.
Among European-anchored material-handling conglomerates, Mecalux and SSI Schäfer occupy positions spanning engineered rack-and-platform integration. Jungheinrich AG represents the bundling archetype, combining elevated storage platforms with captive material-handling equipment lines. These three exemplify how ecosystem breadth commands specification influence in automated distribution environments.
| Leading Market Players |
|---|
| Mecalux |
| SSI Schäfer |
| Jungheinrich AG |
| Stanley Black & Decker |
| Interlake Mecalux |
| Schaefer Systems International, Inc. |
| MiTek Mezzanine Systems |
| Gonvarri Material Handling |
| Steel King Industries |
| Others |
Cost & Logistics Intelligence
Fixed-price contracts with steel price escalation clauses dominate procurement between fabricators and third-party logistics operators, locking in supply access for multi-site rollouts while transferring raw material volatility risk to buyers through indexed adjustments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on seismic certification grade and automation-readiness bundling. Cost compression in standard modular tiers is intensifying because steel input volatility compresses fabricator margins on non-escalated contracts. Third-party logistics operators in Texas and California show highest price sensitivity, while pharmaceutical clean-room OEMs in Massachusetts accept 40-60% material premiums for aluminum specifications.
Supply Chain Analysis
Inventory cycles for wide-flange beams and structural decking have compressed from twelve weeks to six weeks as e-commerce fulfillment buildouts accelerate procurement velocity. Supply concentrates in the United States, China, and Germany for fabricated structural components. Raw material dependencies center on hot-rolled steel coil, aluminum extrusions, and powder-coating chemicals. Single-source vulnerability sits with certified seismic engineering capacity concentrated in California, Texas, and Illinois. Distribution runs through regional fabricator hubs serving logistics corridors with direct-to-site installation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as warehouse vacancy rates tighten and e-commerce fulfillment densification resumes capital deployment. The replacement cycle for pre-2017 OSHA non-compliant installations provides additional demand visibility.
For Market Incumbents: Consolidate seismic engineering talent pools in Chicago and Dallas through acquisition or exclusive contracting arrangements to bottleneck competitor access to IBC Chapter 16 certification capacity. Deepen backward integration into robotic welding and CNC punching equipment to capture fabrication cost compression from steel decking automation. Defend against modular bolt-together specialists by embedding power and data raceways as standard platform features. For New Entrants and Emerging Players: Post-installation structural certification services represent an under-served layer where incumbent fabricators cede margin to third-party engineers. Target cold storage applications in Wisconsin and Pennsylvania with thermally broken connection systems as the most penetrable segment lacking incumbent specialization. Deploy direct sales teams to battery cell and solar module production facilities qualifying for IRA clean energy tax credits. For Investors and Strategic Acquirers: Capital is best deployed toward aluminum fabrication specialists with FDA-validated clean-room track records and anodizing capability. Long-term viability over a five-to-ten year horizon favors vendors with automation-ready platform engineering and captive relationships with material-handling OEMs. Monitor OSHA enforcement intensity on multi-level occupancy egress classifications as the signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Captures margin from robotic welding automation and insulates against hot-rolled coil price volatility. |
| Seismic Certification Service Expansion | Creates attach revenue from IBC Chapter 16 compliance bottlenecks in Texas and Illinois logistics corridors. |
| Aluminum Clean-Room Platform Development | Penetrates FDA-regulated pharmaceutical facilities in Massachusetts and California with corrosion-resistant specifications. |
| Automation-Ready Substructure Engineering | Bundles robotic picking foundations and power raceways to lock in material-handling OEM specification influence. |
| Multi-Site Logistics Network Partnerships | Secures replication contracts with third-party operators rolling out standardized modular configurations across Texas and California. |
Research Approach
Findings reconcile primary fieldwork against secondary review of OSHA regulatory filings, ANSI MH28.3 design guideline updates, and customs trade data for structural steel imports. Primary interviews engaged plant engineers at automotive OEMs, procurement directors at third-party logistics operators, structural certification specialists, and aftermarket service heads at material-handling distributors. Secondary validation drew from SEC 10-K disclosures of publicly traded fabricators, IBC seismic provision amendments, and e-commerce fulfillment center development permits. Bottom-up volume estimates from installation project tracking triangulate against top-down spending analysis from logistics capital expenditure surveys.
Segmentation dimensions modeled include product architecture type, material specification tier, application intensity, and end-user industry regulatory environment across the projection horizon. CAGRs derive from curve-fitting historical installation volumes against macro drivers including warehouse vacancy rates, e-commerce penetration, and OSHA enforcement intensity. Industry-specific forecast inputs incorporate structural steel price index trajectories and certified engineer availability by state licensing jurisdiction.
Forecasts assume regulatory continuity in OSHA walking-working surface standards and IBC seismic provisions; material policy shifts would require re-modeling permit approval timelines and replacement cycle acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market