
 Portable Forklift Ramps Market | 2026-2036
Portable Forklift Ramps Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Forklift Ramps Market Analytics
Third-party logistics providers are rotating toward higher-capacity portable forklift ramps as e-commerce fulfillment networks expand their dockless loading operations. Bluff Manufacturing leverages in-house aluminum fabrication to sustain pricing discipline across North American distribution channels. Dura-Ramp anchors its position through specialized steel ramp designs engineered for construction site mobility. Copperloy differentiates via integrated safety rail systems that address elevated OSHA compliance thresholds.
Portable forklift ramps are mobile inclined surfaces, typically fabricated from aluminum extrusions or welded steel plate with serrated grating surfaces, designed to bridge height differentials between ground level and truck beds or loading docks for powered industrial truck access. Multi-fold aluminum variants lead volume shipments due to their favorable strength-to-weight ratio and field-portability, while steel configurations retain dominance in permanent-yard installations where static load ratings exceed fifteen thousand pounds. Composite material ramps represent the fastest-growing segment as chemical-resistant formulations penetrate food processing and pharmaceutical warehousing applications where corrosion control governs capital planning.
OSHA standards for powered industrial trucks, ASTM F1637 walkway surface specifications, and ISO 12100 machinery safety principles collectively govern ramp design validation and field deployment protocols across US and European jurisdictions. Compliance with these frameworks determines market access, as uncertified imports face exclusion from municipal procurement contracts and corporate safety audits. Stakeholders must monitor evolving load-rating harmonization between OSHA and EU machinery directives to anticipate redesign cycles and certification cost impacts.
Market Dynamics
OSHA load-rating mandates and ASTM F1637 walkway specifications are compressing procurement timelines as third-party logistics providers accelerate dockless loading infrastructure deployment across e-commerce fulfillment networks.
Growth Catalysts
- Aluminum extrusion advances:Higher-capacity aluminum alloys enable 15,000-pound static ratings at reduced unit weights, expanding field-portability for rapid deployment scenarios.
- OSHA compliance thresholds:Elevated powered industrial truck safety standards mandate integrated safety rail systems, driving replacement cycles in existing yard operations.
- US Southeast manufacturing corridor:Concentrated warehouse construction around Atlanta and Charleston generates sustained demand for mobile loading solutions without permanent dock infrastructure.
Market Restraints
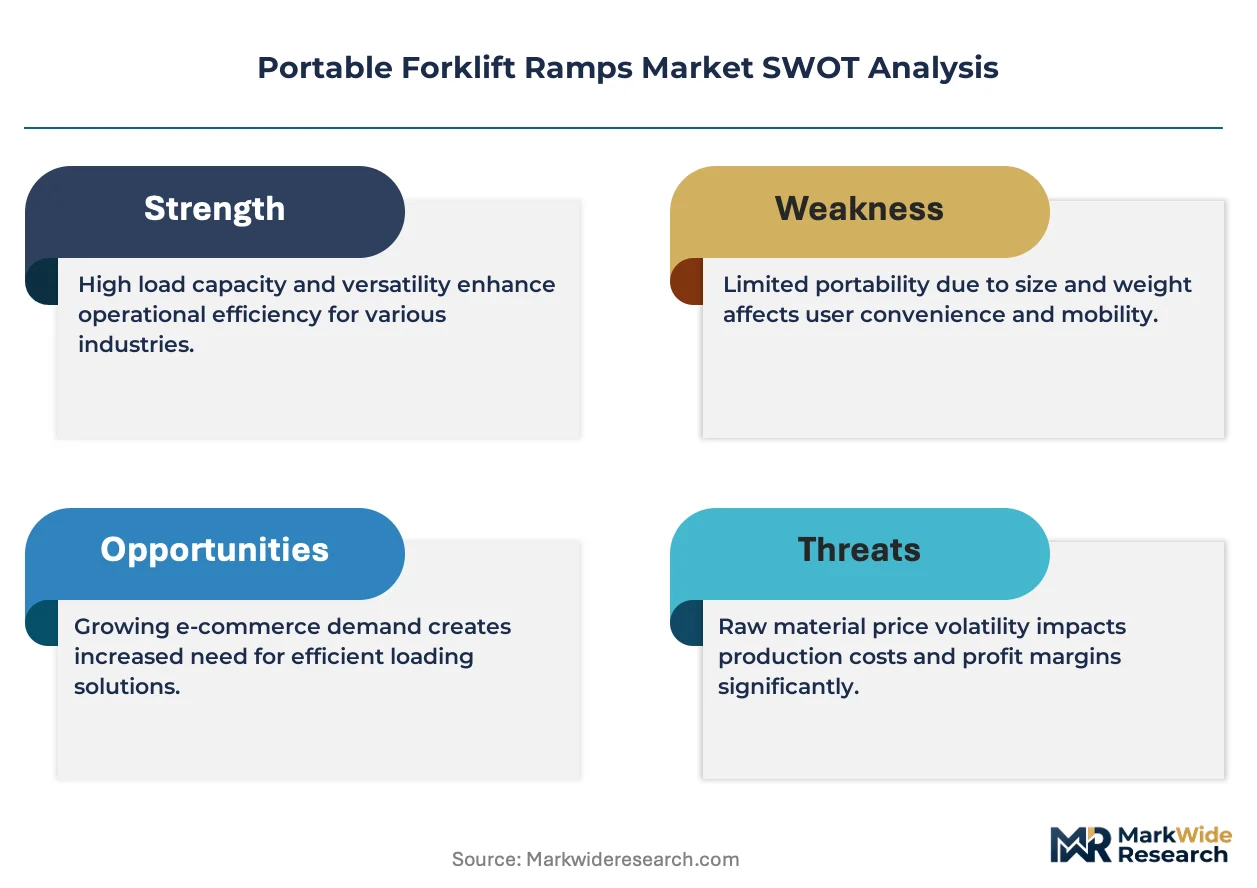
- Aluminum price volatility:LME aluminum futures fluctuations compress fabrication margins and destabilize long-term contract pricing for ramp manufacturers.
- Import certification barriers:Uncertified Asian manufacturers face automatic exclusion from municipal procurement contracts requiring ASTM validation documentation.
- Steel substitution in permanent installations:Static yard applications above fifteen thousand pounds favor welded steel plate with serrated grating despite mobility trade-offs.
Strategic Opportunities
- Composite material penetration:Chemical-resistant formulations address corrosion control requirements in food processing and pharmaceutical warehousing applications.
- German industrial cluster expansion:EU machinery directive harmonization with OSHA standards creates unified certification pathways for transatlantic product lines.
- Rental channel development:Short-term deployment models for seasonal peak operations reduce capital barriers for mid-market logistics operators.
Industry Challenges
- Welding certification scarcity:Qualified aluminum TIG welders command premium wages, constraining production scaling for multi-fold ramp fabricators.
- ISO 12100 documentation burden:Machinery safety principle compliance extends product development cycles by four to six months for new ramp configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Forklift Ramps Market |
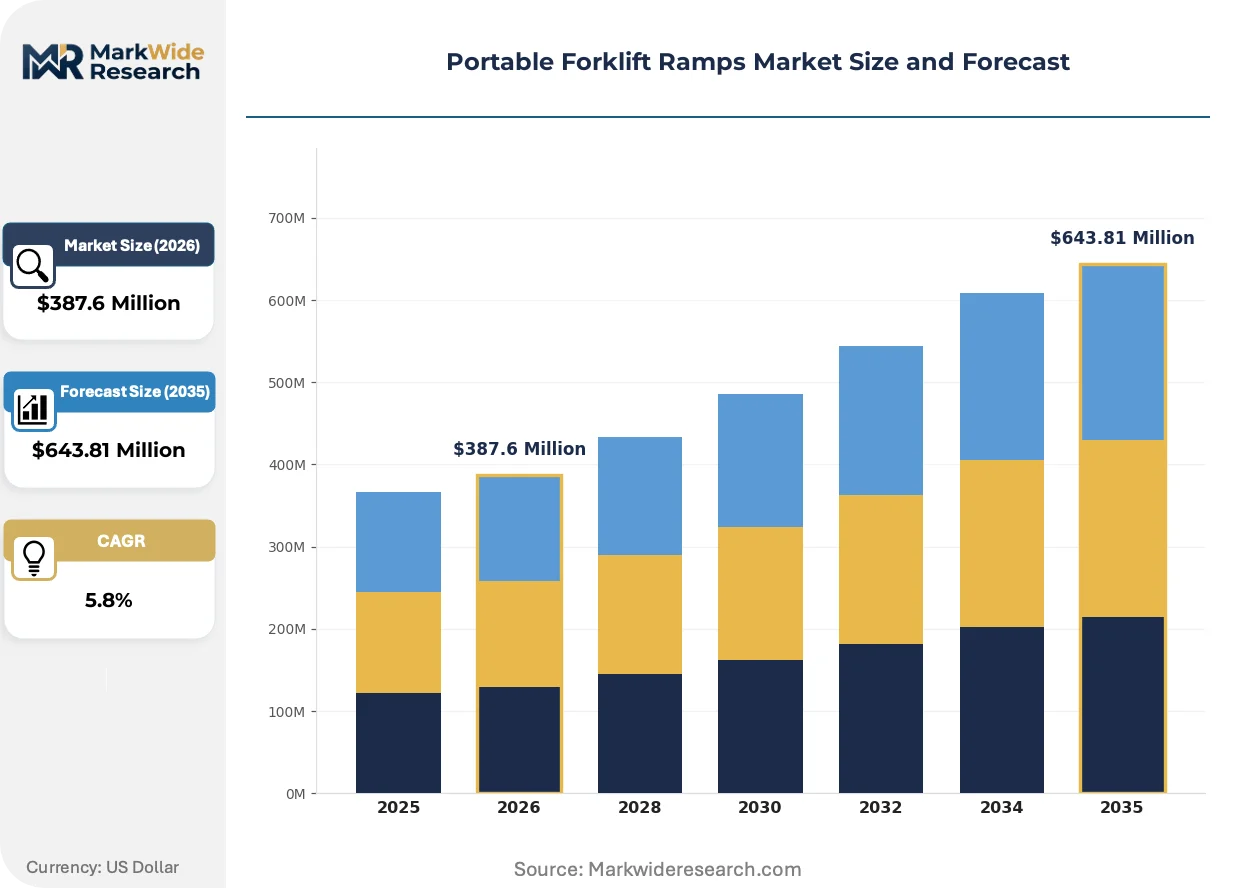
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single-Fold, Multi-Fold, Bi-Fold, Tri-Fold Material: Aluminum, Steel, Composite, Rubber Weight Capacity: 500 lbs, 1000 lbs, 1500 lbs, 2000 lbs Application: Construction, Warehousing, Retail, Logistics |
| Companies Covered | Bluff Manufacturing, Dura-Ramp, Handi-Ramp, Vestil Manufacturing Corporation, Copperloy, Titan Ramps, SafeRack, WM Manufacturing, Marshall Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Forklift Ramps Market Evolving Landscape
Material science advances and regulatory harmonization are compressing traditional product lifecycles while opening new application verticals previously served by permanent infrastructure.
Composite polymer formulations reinforced with glass fiber are decomposing the historical aluminum-steel duopoly in corrosive environments. Pharmaceutical warehouses near Boston and San Diego have adopted these units for chemical washdown protocols. The technology is decomposing price premiums previously commanded by stainless steel alternatives in regulated environments.
ASTM F1637 walkway surface specifications are tightening traction coefficient requirements for serrated grating designs. Ramp fabricators must retool stamping dies and recertify existing product lines to maintain market access. Food processing facilities in Wisconsin and dairy operations in Vermont face the most immediate compliance deadlines due to state-level inspection intensity.
Third-party logistics providers now specify outcome-based maintenance agreements rather than capital purchase models. Equipment lessors bundle inspection, recertification, and replacement services into per-load pricing. This restructuring is most advanced among e-commerce fulfillment operators in the Dallas-Fort Worth metroplex seeking to minimize fixed asset exposure.
Portable Forklift Ramps Market Segmentation
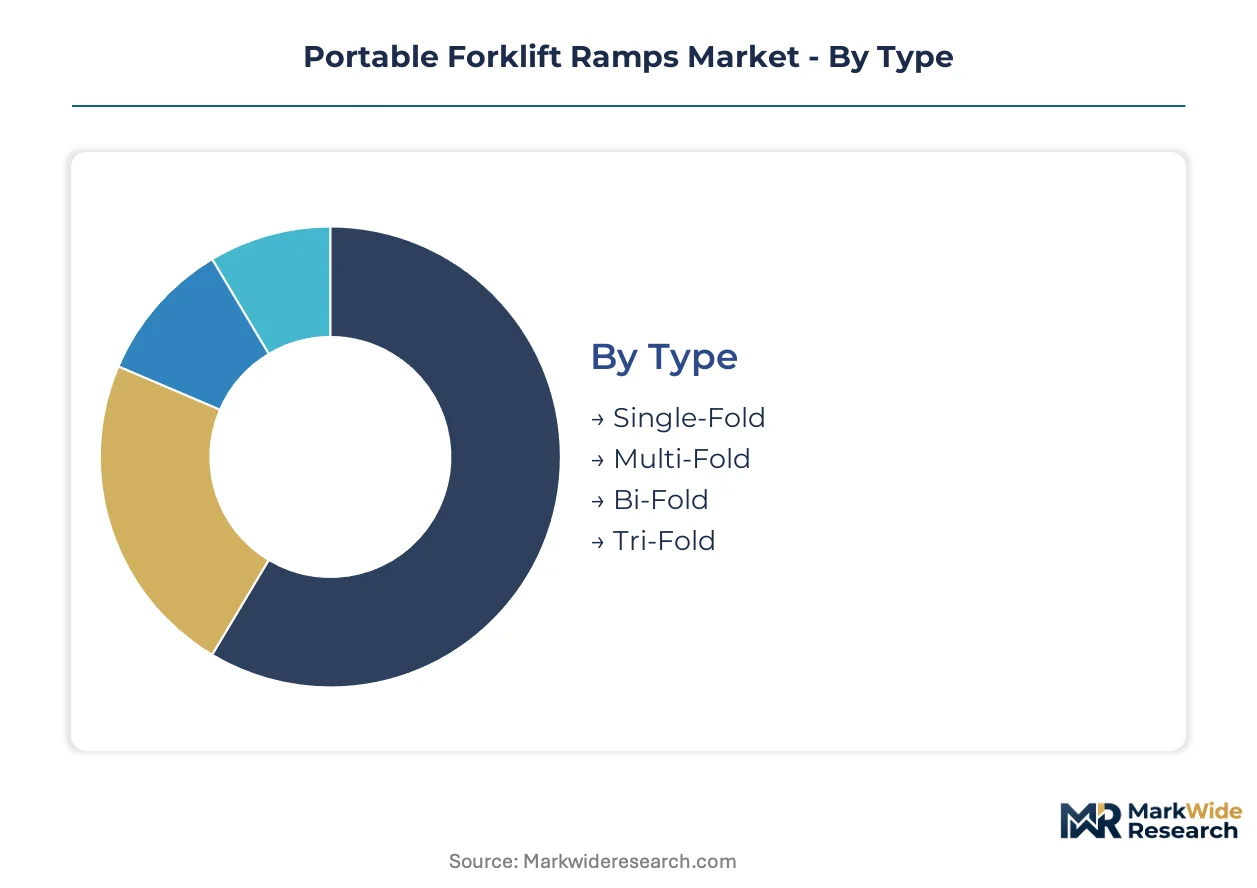
Portable forklift ramps segment across four interlocking dimensions that determine procurement pathways, compliance requirements, and channel economics. Understanding how type, material, capacity, and application intersect reveals where margin concentrates and where specification wars reshape competitive positioning.
Type:
Channel mix varies sharply by fold configuration, with multi-fold units dominating rental fleets and single-fold variants anchoring direct sales to permanent yard operators.
- Multi-Fold:Aluminum extrusion construction enables field-portability for rapid deployment scenarios. Third-party logistics providers in the Dallas-Fort Worth metroplex specify these for seasonal peak operations where dockless loading infrastructure must relocate weekly.
- Single-Fold:Welded steel plate with serrated grating delivers static load ratings exceeding fifteen thousand pounds. Construction sites across the US Southeast manufacturing corridor favor these for permanent yard installations where mobility trade-offs are acceptable.
- Bi-Fold:Intermediate portability suits mid-market warehousing operators seeking balance between deployment speed and load capacity.
- Tri-Fold:Compact stowage dimensions appeal to urban logistics fleets with constrained equipment storage footprints.
By volume, Multi-Fold leads. By expansion trajectory, Tri-Fold is climbing the fastest as last-mile delivery density intensifies.
Material:
Cost tiers stratify procurement decisions, with aluminum commanding premium positioning and composite formulations disrupting corrosion-sensitive applications.
- Aluminum:Higher-capacity alloys achieve favorable strength-to-weight ratios through precision extrusion. German industrial clusters specify these for EU machinery directive compliance where transatlantic certification harmonization reduces documentation burden.
- Composite:Glass-fiber-reinforced polymer formulations resist chemical washdown protocols. Pharmaceutical warehouses near Boston and San Diego have adopted these units, displacing stainless steel alternatives in regulated environments.
- Steel:Welded plate construction dominates static applications above fifteen thousand pounds where unit weight matters less than capital cost.
- Rubber:Vibration-dampening properties serve specialized food processing facilities with delicate cargo handling requirements.
Steel captures the largest shipment volumes. Composite materials are gaining share fastest as corrosion control governs capital planning in pharmaceutical and food processing verticals.
Weight Capacity:
Customer type determines capacity specification, with enterprise logistics networks clustering at upper thresholds and independent operators populating lower tiers.
- 2000 lbs:Heavy-duty ratings support palletized freight operations in high-throughput e-commerce fulfillment networks. OSHA load-rating mandates are compressing procurement timelines as these specifications become baseline for municipal contracts.
- 1500 lbs:Mid-capacity units balance acquisition cost against operational flexibility for regional distribution centers.
- 1000 lbs:Entry-level specification serves retail backroom operations with intermittent forklift deployment.
- 500 lbs:Light-duty applications include hand truck and manual pallet jack access where powered industrial truck requirements do not apply.
1500 lbs and 2000 lbs specifications together dominate revenue. The 2000 lbs tier is expanding most quickly as warehouse throughput requirements intensify.
Application:
Geography shapes application demand, with construction concentrating in the US Southeast and logistics clustering around German industrial corridors and Atlanta-Charleston warehouse construction zones.
- Logistics:Third-party logistics providers drive specification intensity for dockless loading operations. E-commerce fulfillment networks require rapid-deployment ramps that bridge height differentials without permanent infrastructure.
- Warehousing:Permanent installations favor steel configurations where static load ratings and durability outweigh portability requirements.
- Construction:Site mobility demands multi-fold aluminum units that relocate daily across project phases. ASTM F1637 walkway specifications govern traction requirements for these temporary deployments.
- Retail:Backroom receiving operations with intermittent use patterns prioritize compact storage and lower acquisition cost over maximum load capacity.
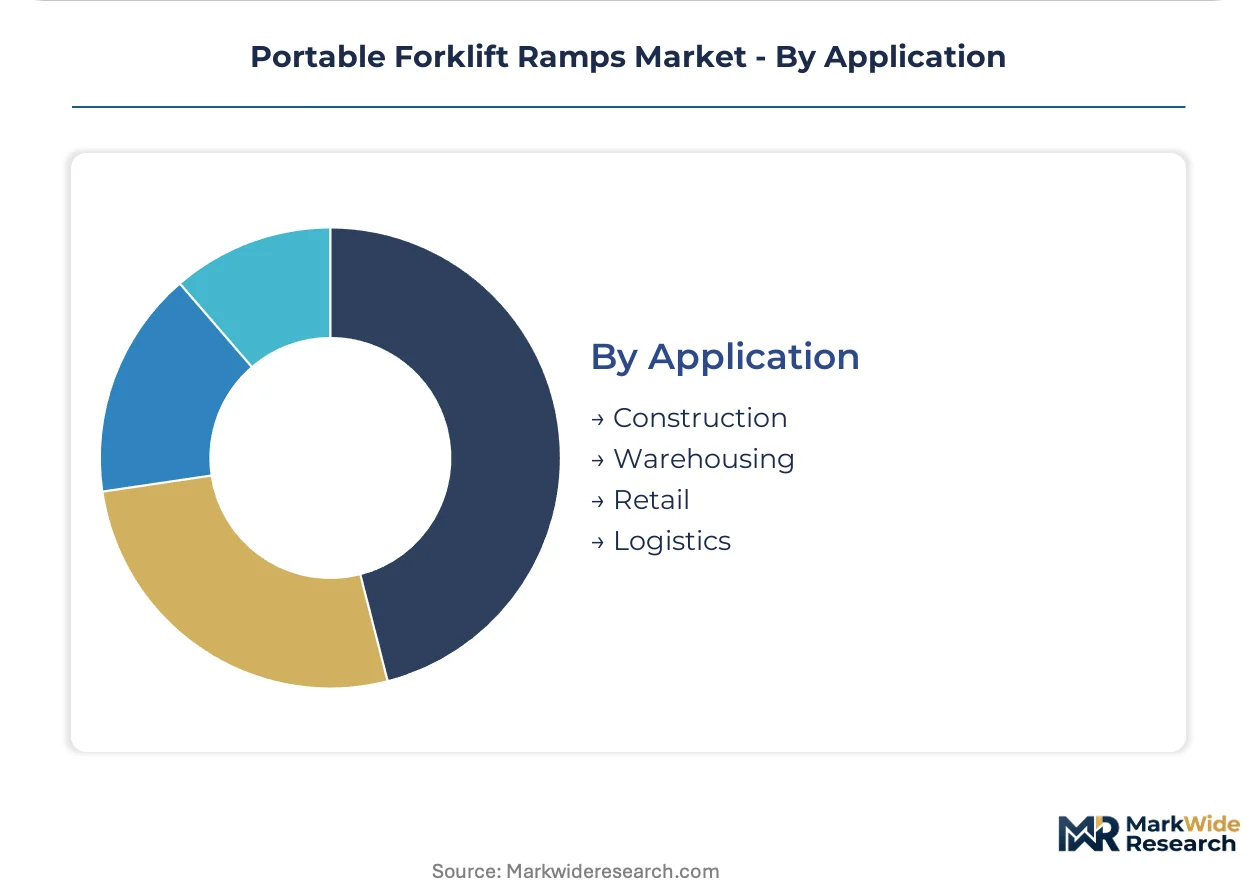
Logistics generates the highest unit volumes. Construction is climbing the fastest as infrastructure investment accelerates in the US Southeast manufacturing corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters export aluminum extrusion expertise to North American logistics networks, while US Southeast manufacturing corridors absorb mobile loading infrastructure for dockless fulfillment operations.
United States
OSHA load-rating mandates compress procurement timelines for third-party logistics providers expanding e-commerce fulfillment networks. The Department of Labor enforces powered industrial truck safety standards that mandate integrated safety rail systems. Warehouse construction concentrates around Atlanta and Charleston, where rapid-deployment ramps bridge height differentials without permanent dock infrastructure.
Germany
EU machinery directive harmonization with OSHA standards creates unified certification pathways for transatlantic product lines. The country's national industrial safety regulator enforces ISO 12100 machinery safety principles that govern ramp design validation. Industrial clusters in North Rhine-Westphalia and Bavaria generate sustained demand for aluminum units serving automotive and chemical logistics corridors.
China
Domestic e-commerce fulfillment networks drive specification intensity for multi-fold aluminum variants with favorable strength-to-weight ratios. The national standardization administration enforces GB standards for industrial equipment safety that increasingly align with ASTM specifications. Manufacturing zones in the Yangtze River Delta produce ramp components for export markets facing ASTM F1637 walkway surface certification requirements.
Canada
Cross-border logistics integration with US distribution networks sustains demand for mobile loading solutions compliant with both OSHA and provincial occupational safety frameworks. Health Canada coordinates with Transport Canada on equipment safety standards for intermodal freight operations. Industrial corridors in Ontario and Quebec serve as secondary distribution nodes for Great Lakes manufacturing supply chains.
Mexico
Nearshoring manufacturing relocation from Asia generates construction site mobility requirements for temporary loading infrastructure. The federal labor authority enforces occupational safety standards for powered industrial trucks in maquiladora operations. Industrial parks in Nuevo León and the Bajío Region absorb multi-fold aluminum units for project-phase logistics without permanent yard installations.
Portable Forklift Ramps Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and fabrication capacity dimensions. The vendor base stratifies into three tiers: premium fabricators with in-house aluminum extrusion capabilities, mid-market steel specialists serving permanent installations, and import-dependent distributors facing ASTM validation barriers. Strategic archetypes include integrated manufacturers controlling upstream alloy supply, regional fabricators leveraging welding certification scarcity for pricing power, and rental-channel operators bundling maintenance into outcome-based agreements. Dominant competitive moves encompass backward integration into aluminum extrusion and geographic expansion through municipal procurement contract capture.
Specialists in integrated safety rail systems include Copperloy and SafeRack, which occupy positions within the premium-compliance tier where OSHA threshold adherence determines market access. Among steel-focused fabricators, Dura-Ramp exemplifies the construction-site mobility archetype through welded plate configurations. Bluff Manufacturing anchors the integrated-manufacturer category with apparent in-house fabrication capabilities. These three company structures represent distinct competitive positioning vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Bluff Manufacturing |
| Dura-Ramp |
| Handi-Ramp |
| Vestil Manufacturing Corporation |
| Copperloy |
| Titan Ramps |
| SafeRack |
| WM Manufacturing |
| Marshall Industrial |
| Others |
Value Network & Pricing Analysis
Composite polymer formulations displacing aluminum and steel in corrosive environments simultaneously redistribute manufacturing geography toward specialized polymer compounders and compress price premiums previously commanded by stainless steel alternatives, reshaping procurement economics for pharmaceutical and food processing buyers.
Pricing Analysis
Technology-generation pricing gaps separate legacy steel configurations from aluminum extrusion advances and emerging composite formulations. Three-tier pricing structure across premium aluminum units with integrated safety rails, mid-market steel ramps for permanent installations, and economy-grade imports facing ASTM certification barriers determines procurement pathways. Cost compression in the economy tier intensifies because uncertified Asian manufacturers face automatic exclusion from municipal contracts. Third-party logistics providers show lowest price sensitivity due to outcome-based maintenance agreements, while independent retail operators populate the most price-sensitive segment.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta manufacturing zones through Los Angeles and Charleston ports influence landed cost structures for aluminum extrusion components. Supply concentrates in China for fabricated components, the United States for integrated safety rail assembly, and Germany for precision alloy processing. Raw material dependencies center on LME-traded aluminum ingot, steel plate from domestic mills, and glass-fiber-reinforced polymer resins. Single-source vulnerability in qualified aluminum TIG welding certification constrains production scaling. Distribution runs through direct OEM sales for permanent installations and rental fleet operators for seasonal deployment scenarios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable forklift ramps occupy an early-cycle expansion position as dockless loading infrastructure penetration accelerates across e-commerce fulfillment networks, with OSHA compliance thresholds driving replacement demand in existing yard operations.
For Market Incumbents: Compound certification advantages by accelerating ASTM F1637 recertification cycles before state-level inspection deadlines in Wisconsin and Vermont tighten. Backward integration into aluminum extrusion capacity insulates margin structures from LME price volatility. The threat of composite material substitution in pharmaceutical verticals demands R&D investment in corrosion-resistant formulations to defend positioning. For New Entrants and Emerging Players: Lead with rental-channel bundling models targeting mid-market logistics operators in the Dallas-Fort Worth metroplex seeking to minimize fixed asset exposure. White-space opportunities concentrate in seasonal peak operations, urban logistics fleets with constrained storage footprints, and nearshoring construction sites in Nuevo León. A go-to-market angle emphasizing per-load pricing with integrated inspection and recertification services bypasses capital purchase barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial equipment lessors seeking exit liquidity as outcome-based maintenance models mature. Long-term viability over the next decade hinges on regulatory harmonization between OSHA and EU machinery directives creating unified certification pathways. The acquisition target archetype comprises regional fabricators with welding certification scarcity leverage and municipal contract capture. Watch for inflection signals in aluminum futures stabilization and EU machinery directive implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | In-house alloy processing insulates Bluff Manufacturing from LME volatility and sustains pricing discipline. |
| Composite Material R&D Investment | Glass-fiber-reinforced formulations penetrate pharmaceutical warehouses near Boston displacing stainless steel alternatives. |
| Rental Channel Development | Per-load pricing models reduce capital barriers for mid-market logistics operators in seasonal peak operations. |
| ASTM F1637 Recertification Acceleration | Preemptive compliance with tightening traction coefficient requirements secures municipal procurement access. |
| German Industrial Cluster Expansion | EU machinery directive harmonization creates unified certification pathways for transatlantic product lines. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews captured perspectives from maintenance directors at third-party logistics providers, plant engineers specifying dockless loading infrastructure, OEM procurement teams at aluminum extrusion fabricators, aftermarket service heads managing rental fleets, and safety compliance officers interpreting OSHA load-rating mandates. Secondary sources included customs and trade data tracking aluminum and steel component flows, SEC 10-K filings from listed industrial equipment manufacturers, ASTM and ISO standard documentation, and municipal procurement contract databases. Bottom-up shipment estimates triangulated against top-down market sizing derived from warehouse construction permits and e-commerce fulfillment network expansion announcements.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across fold configuration, material composition, weight capacity tier, and application vertical. CAGRs were derived from regression analysis of historical shipment data against warehouse construction intensity indices and powered industrial truck fleet expansion rates. Industry-specific inputs included OSHA enforcement action frequencies, LME aluminum futures curves, and EU machinery directive implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce fulfillment network expansion, aluminum price stabilization, or regulatory harmonization progress would require recalibration. Forecasts reflect documented assumptions regarding OSHA compliance threshold evolution and composite material adoption curves in regulated environments. Recalibration cycles align with material shifts in warehouse construction permitting data and ASTM standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Dust Extractors Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Sorting Equipment Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Modular Conveyor System Market