
 Freeze and Thaw Systems Market | 2026-2036
Freeze and Thaw Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze and Thaw Systems Market Analysis
The FDA's updated guidance on cell therapy manufacturing is pivoting the cost-of-entry calculus for freeze and thaw equipment vendors. Thermo Fisher Scientific leverages its distribution breadth across North American biopharma clusters to sustain installed-base loyalty. Sartorius anchors European demand through specialized single-use compatibility in its controlled-rate freezer portfolio. Danaher Corporation competes by integrating freeze-thaw workflows with broader bioprocess automation platforms.
Freeze and thaw systems encompass thermal management equipment engineered to execute controlled temperature reduction and elevation cycles, typically spanning -196°C liquid nitrogen immersion to +37°C thaw profiles, preserving cellular viability for biologics manufacturing and clinical applications. Ultra-low temperature freezers dominate current revenue owing to entrenched demand from vaccine storage networks, while cryopreservation technology segments are expanding fastest as cell therapy developers adopt programmable rate-controlled freezing to meet release specifications. Bioprocessing applications command premium pricing due to GMP validation burdens, whereas research institution demand for benchtop units remains price-sensitive and fragmented.
The FDA enforces current Good Manufacturing Practice standards that mandate documented thermal mapping and qualification protocols for equipment used in commercial cell therapy production. EMA's ATMP regulation framework in Europe imposes comparable traceability requirements, pushing vendors toward integrated data-logging architectures. China's NMPA has aligned biologics equipment standards with international ICH guidelines, reducing market access friction for qualified suppliers. Stakeholders must monitor how evolving pharmacopeial standards for cryopreserved starting materials reshape equipment specification sheets and service contract structures.
Market Dynamics
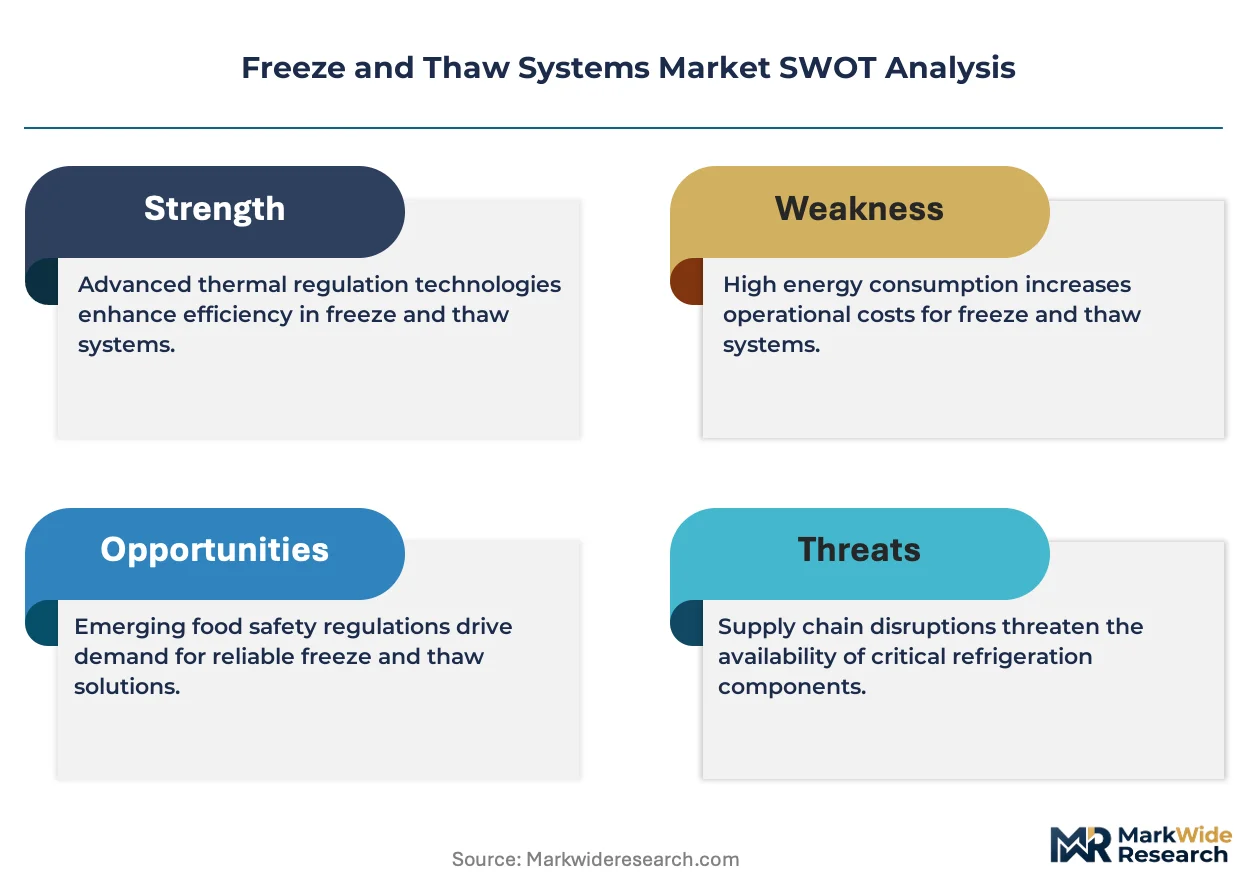
The FDA's tightened cell therapy manufacturing guidance is forcing biopharmaceutical manufacturers to revalidate legacy freeze-thaw equipment, compressing replacement cycles and elevating qualification costs across installed bases.
Growth Catalysts
- ATMP Regulation Framework:EMA's Advanced Therapy Medicinal Products requirements mandate traceable cold-chain documentation, compelling European bioprocessors to upgrade to integrated data-logging freeze-thaw systems.
- Cell Therapy Manufacturing:Commercial-scale allogeneic cell therapy production requires controlled-rate freezing to preserve post-thaw viability, driving demand for programmable rate-controlled equipment.
- Liquid Nitrogen Infrastructure:Cryogenic supply network expansion across Germany, the United States, and China reduces operational barriers for ultra-low temperature system deployment.
Market Restraints
- Stainless Steel Supply Concentration:Specialized cryogenic-grade stainless steel sourcing concentrates among German and Japanese metallurgical suppliers, exposing equipment manufacturers to input cost volatility and lead time extension.
- Validation Burden:FDA current Good Manufacturing Practice thermal mapping protocols require 12-18 month qualification timelines for commercial cell therapy applications, extending sales-to-revenue recognition cycles.
- Mechanical Freezer Substitution:Stirling engine-based mechanical ultra-low temperature systems compete with liquid nitrogen immersion for certain biologics storage applications, pressuring traditional cryogenic equipment pricing.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO's alignment with ICH Q5A viral safety guidelines and the PLI scheme's biopharma incentives position Indian contract manufacturing organizations as emerging freeze-thaw equipment buyers.
- Single-Use Integration:Convergence of disposable bag assemblies with controlled-rate freezing technology eliminates cross-contamination risks in multi-product cell therapy facilities.
- Service Contract Unbundling:Predictive maintenance subscriptions and remote thermal monitoring services create recurring revenue streams beyond capital equipment sales.
Industry Challenges
- Cryobiology Expertise Scarcity:Qualified thermal validation engineers and cryopreservation protocol specialists remain concentrated among legacy biopharma clusters in Boston and Basel, constraining facility commissioning timelines.
- Legacy System Integration:GMP-qualified freeze-thaw equipment must interface with established manufacturing execution systems and building management systems, multiplying commissioning complexity.
- Harmonized Standard Delays:Divergent pharmacopeial requirements between USP, EP, and ChP for cryopreserved starting materials force manufacturers to maintain jurisdiction-specific qualification dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze and Thaw Systems Market |
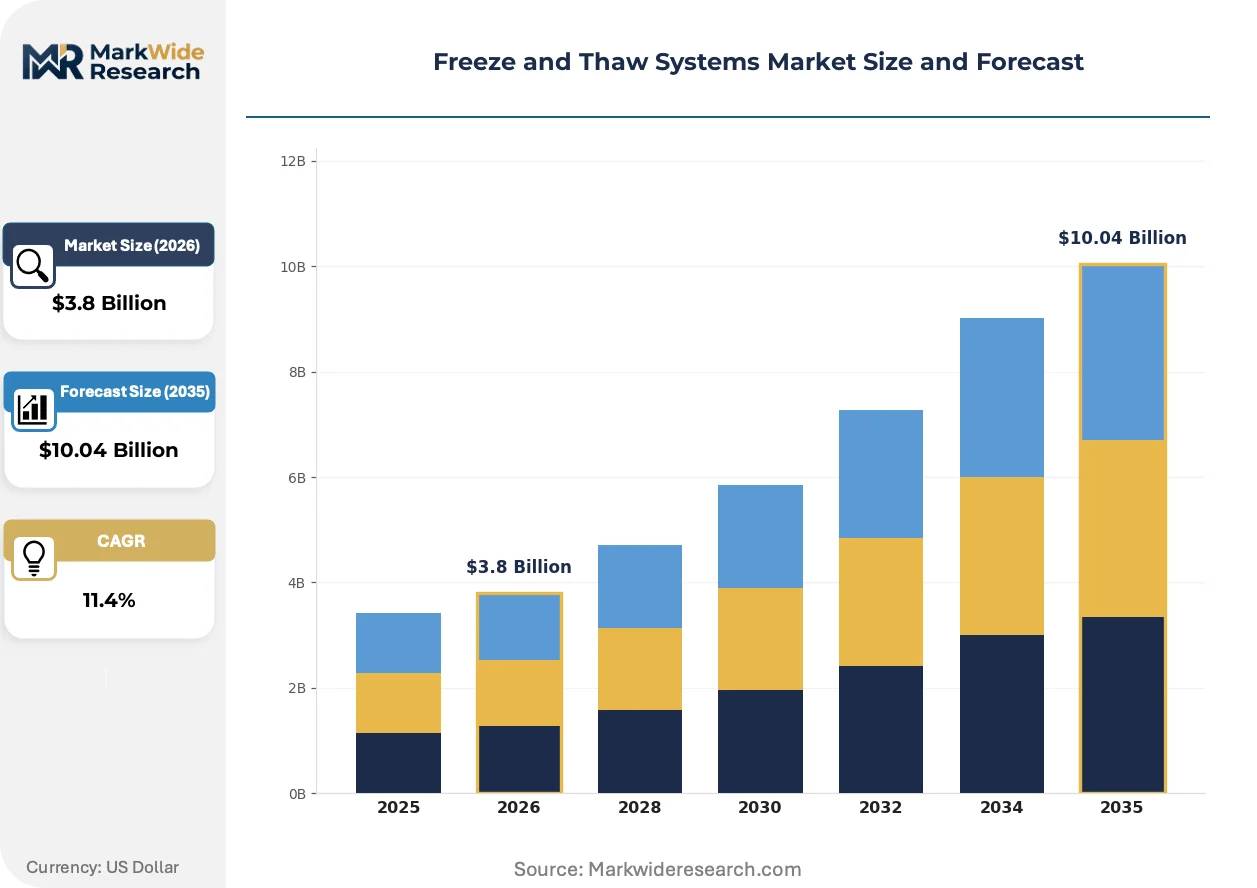
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Freezers, Ultra-Low Temperature Freezers, Controlled Rate Freezers, Mobile Freezers End User: Biopharmaceuticals, Research Institutions, Laboratories, Hospitals Application: Cell Preservation, Vaccine Storage, Bioprocessing, Tissue Engineering Technology: Refrigeration, Cryopreservation, Liquid Nitrogen Systems, Thermal Systems |
| Companies Covered | Danaher Corporation, Eppendorf SE, Thermo Fisher Scientific, Farrar Scientific, BioCision, Sartorius, Avantor, HOF Enterprise, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze and Thaw Systems Market Emerging Trajectories
Equipment architectures are pivoting from standalone thermal units to integrated bioprocess nodes, driven by cell therapy manufacturing scale-up and regulatory data integrity mandates.
Automated controlled-rate freezing systems are automating protocol execution previously requiring manual intervention, reducing operator-induced variability in critical cell therapy manufacturing steps. Gene therapy developers and CDMOs in the United States and Germany are adopting these platforms for commercial release batches. The technology is automating compliance documentation, compressing batch release timelines from weeks to days.
REACH restrictions on fluorinated greenhouse gases are phasing out certain hydrofluorocarbon refrigerants used in mechanical ultra-low temperature freezers, compelling equipment redesign toward natural refrigerant alternatives or liquid nitrogen architectures. European biobanks and pharmaceutical storage facilities face retrofit decisions as F-Gas Regulation quotas tighten. Cell therapy developers are responding by specifying nitrogen-based systems to eliminate refrigerant compliance exposure.
After-sales service unbundling is separating thermal qualification, preventive maintenance, and emergency response into discrete contractual modules, allowing biopharmaceutical buyers to match service expenditure to facility maturity. Equipment vendors are displacing bundled multi-year contracts with menu-based service tiers. This pattern is most visible among emerging cell therapy developers in the United States seeking to preserve cash during pre-revenue phases.
Freeze and Thaw Systems Market Segmentation
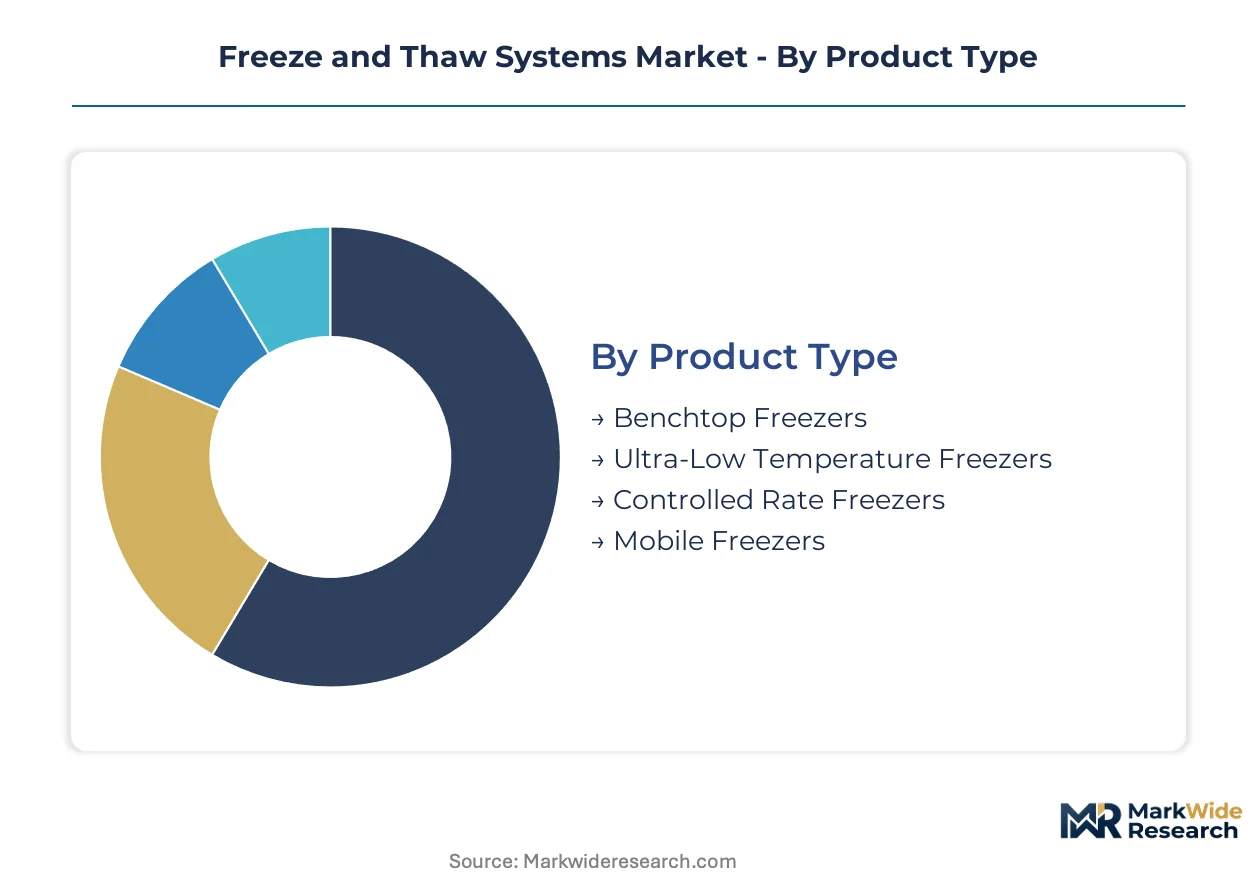
Freeze and thaw system procurement decisions pivot on validation burden, thermal precision requirements, and integration complexity with existing bioprocess infrastructure. Equipment specification sheets diverge sharply between GMP-qualified commercial manufacturing and research-grade benchtop applications.
Product Type:
Capital allocation intensity and facility footprint constraints shape buyer selection across freezer architectures.
- Ultra-Low Temperature Freezers:These systems maintain -80°C to -150°C operating ranges through cascade refrigeration or liquid nitrogen backup, serving as the backbone of vaccine distribution networks and biorepository operations. Demand concentrates in the United States and Germany where CDC and PEI cold-chain mandates require redundant thermal storage for pandemic preparedness stockpiles.
- Controlled Rate Freezers:Programmable thermal profiling equipment executes precise cooling curves from ambient to -196°C, critical for preserving post-thaw cell viability in commercial cell therapy release batches. Cell therapy developers in Boston and Basel clusters specify these units to meet FDA and Swissmedic ATMP manufacturing guidance.
- Benchtop Freezers:Compact units occupying under 10 square feet serve academic laboratories and early-stage discovery operations with limited infrastructure budgets.
- Mobile Freezers:Transportable liquid nitrogen dewar systems enable point-of-care cell therapy administration and clinical trial material distribution without fixed infrastructure.
Ultra-Low Temperature Freezers lead on installed base scale; Controlled Rate Freezers lead on momentum as cell therapy manufacturing expands.
End User:
Regulatory compliance tier and batch volume requirements stratify equipment specifications across customer categories.
- Biopharmaceuticals:Commercial manufacturers operate under FDA current Good Manufacturing Practice and EMA ATMP frameworks requiring 21 CFR Part 11-compliant data logging, thermal mapping qualification, and preventive maintenance documentation. Allogeneic cell therapy producers in the United States and Germany command premium pricing for integrated bioprocess node configurations.
- Research Institutions:Universities and government laboratories prioritize acquisition cost and flexibility over validation rigor, driving demand for configurable benchtop units with interchangeable sample racks.
- Laboratories:Contract research organizations and quality control facilities balance throughput requirements with space constraints in multi-tenant facilities.
- Hospitals:Clinical cell therapy programs and cord blood banking operations require bedside-accessible thawing equipment with rapid recovery protocols.
Biopharmaceuticals capture the highest equipment value per installation; Research Institutions represent the broadest addressable base.
Application:
Biological material stability requirements and release specification stringency determine thermal protocol complexity.
- Cell Preservation:Hematopoietic stem cells, CAR-T therapies, and induced pluripotent stem cells demand controlled-rate freezing with programmable cryoprotectant equilibration phases to maintain membrane integrity. EMA's ATMP traceability requirements push European facilities toward automated systems with integrated chain-of-custody documentation.
- Vaccine Storage:mRNA and viral vector vaccines require ultra-low temperature maintenance from manufacture through administration, with CDC and WHO performance standards dictating temperature excursion limits.
- Bioprocessing:Media, reagents, and active pharmaceutical ingredients require scalable freeze-thaw cycles compatible with single-use bioreactor workflows.
- Tissue Engineering:Decellularized scaffolds and organoid constructs impose specialized thermal stress limits during preservation and revival protocols.
Vaccine Storage leads on installed base scale; Cell Preservation leads on technology upgrade intensity.
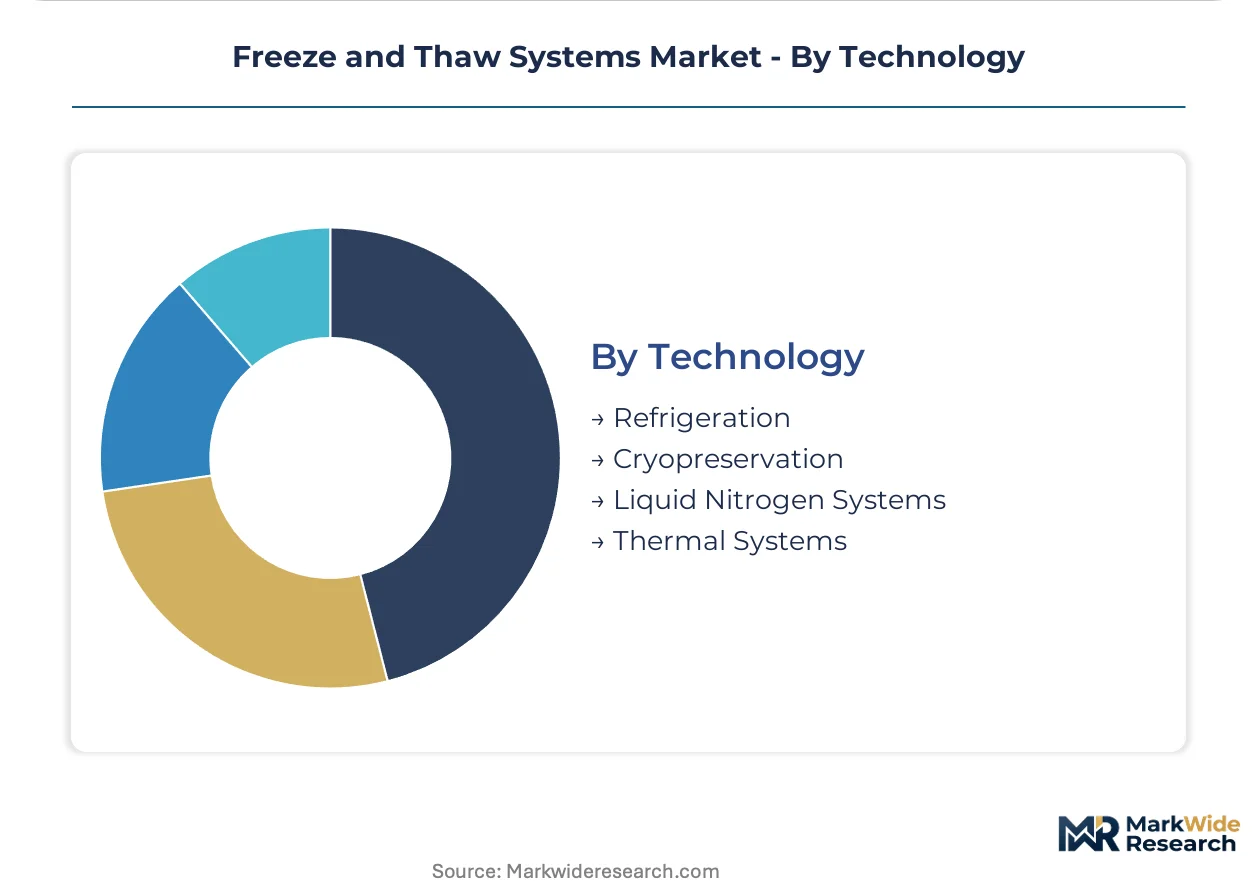
Technology:
Energy infrastructure availability and refrigerant regulatory exposure drive architectural selection between mechanical and cryogenic approaches.
- Cryopreservation:Programmable rate-controlled systems using liquid nitrogen vapor phase achieve -1°C to -50°C per minute cooling rates essential for cell therapy viability specifications. REACH F-Gas Regulation restrictions in Europe accelerate displacement of mechanical alternatives toward nitrogen-based architectures.
- Liquid Nitrogen Systems:Immersion and vapor-phase storage eliminates compressor maintenance and refrigerant compliance burdens, favored by biobanks in Germany and China where cryogenic supply networks have achieved density.
- Refrigeration:Cascade compressor systems using hydrocarbon or hydrofluorocarbon refrigerants dominate vaccine storage applications with moderate temperature requirements.
- Thermal Systems:Active heating and cooling modules for controlled thawing complement freezing infrastructure in integrated bioprocess workflows.
Liquid Nitrogen Systems lead on reliability perception; Cryopreservation leads on clinical specification alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freeze and thaw systems manufacturing originated in post-war German precision engineering clusters before migrating to North American biotech corridors during the 1990s recombinant protein boom. Today's demand geography reflects this bifurcated heritage: German engineering standards anchor European procurement specifications while FDA validation protocols dominate North American purchasing decisions.
United States
Commercial allogeneic cell therapy manufacturing in Boston and San Francisco drives demand for programmable rate-controlled freezing equipment. FDA's updated cell therapy guidance mandates 21 CFR Part 11-compliant thermal documentation, compressing replacement cycles for legacy units. The National Institute of Standards and Technology maintains cryogenic temperature calibration standards that equipment vendors must reference for GMP qualification.
Germany
EMA's ATMP traceability requirements push bioprocessors toward integrated data-logging architectures. REACH F-Gas Regulation quotas accelerate displacement of mechanical refrigeration toward liquid nitrogen vapor-phase systems. The Rhine-Main biotech corridor hosts Europe's densest concentration of contract cell therapy manufacturers specifying German-engineered controlled-rate freezers.
China
NMPA alignment with ICH Q5A guidelines reduces market access friction for qualified international suppliers. Yangtze River Delta biologics clusters in Shanghai and Suzhou are commissioning commercial-scale cryopreservation infrastructure for CAR-T manufacturing. State-backed biopharma investment funds prioritize domestic equipment sourcing for strategic supply security.
India
CDSCO's ICH harmonization and PLI scheme biopharma incentives position contract manufacturing organizations as emerging equipment buyers. Hyderabad and Bengaluru biotech parks are adding GMP-qualified freeze-thaw capacity for export-oriented biologics production. Domestic stainless steel fabrication capabilities reduce lead times for cryogenic-grade vessel construction.
Switzerland
Swissmedic ATMP manufacturing guidance matches FDA stringency, sustaining premium equipment specifications across Basel's pharmaceutical cluster. Precision engineering heritage supports specialized controlled-rate freezer component manufacturing. The country's biologics export orientation demands equipment qualified for dual US-European release standards.
Freeze and Thaw Systems Market Vendor Landscape
The competitive structure tilts toward diversified life science conglomerates with installed-base service networks. Three archetypes dominate: integrated bioprocess platform vendors, specialized thermal equipment fabricators, and consumables-anchored system suppliers. Consolidation pressure intensifies as cell therapy manufacturers demand single-source accountability for validation documentation. Strategic moves center on service contract unbundling and predictive maintenance subscription models rather than pure equipment sales.
Among diversified life science conglomerates, Danaher Corporation, Thermo Fisher Scientific, and Sartorius occupy positions spanning bioprocess automation to thermal management. These entities exemplify the platform-integration archetype, leveraging distribution breadth across North American and European biopharma clusters. Specialized thermal equipment fabricators including Farrar Scientific and HOF Enterprise represent engineering-focused alternatives for facilities requiring customized cryogenic protocols. Eppendorf SE and Merck KGaA anchor the consumables-integrated tier, where disposable bag assemblies converge with controlled-rate freezing hardware.
| Leading Market Players |
|---|
| Danaher Corporation |
| Eppendorf SE |
| Thermo Fisher Scientific |
| Farrar Scientific |
| BioCision |
| Sartorius |
| Avantor |
| HOF Enterprise |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
GMP validation tier bifurcation separates FDA-qualified commercial installations from research-grade benchtop units, with this divergence manifesting in both pricing architecture and supply chain configuration. Premium-tier controlled-rate freezers command three-to-fourfold acquisition multiples over standard laboratory units, while cryogenic-grade stainless steel sourcing concentrates among German and Japanese metallurgical suppliers, tethering equipment cost structures to specialized alloy availability.
Pricing Analysis
The bundled-versus-unbundled service split now defines competitive positioning across the freeze and thaw equipment landscape. Equipment vendors are displacing traditional multi-year bundled contracts with menu-based service tiers spanning thermal qualification, predictive maintenance, and remote monitoring subscriptions. Price differentiation hinges on 21 CFR Part 11 data integrity certification and integrated bioprocess automation compatibility, with FDA validation burden compressing margins for legacy mechanical refrigeration architectures. Research institutions exhibit acute price sensitivity, whereas allogeneic cell therapy manufacturers prioritize qualification speed over acquisition cost.
Supply Chain Analysis
Freight cost escalation for cryogenic vessel transport is amplifying regional fabrication advantages across the freeze and thaw equipment supply chain. Specialized manufacturing concentrates in Germany, the United States, and China, with cryogenic-grade stainless steel and precision temperature control modules drawing from Japanese and German component suppliers. Single-source vulnerability in specialized alloy sourcing exposes equipment fabricators to input cost volatility. Distribution runs through direct sales forces for GMP-qualified commercial installations and distributor networks for research-grade benchtop units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA's tightened cell therapy manufacturing guidance forcing biopharmaceutical manufacturers to revalidate legacy equipment and compress replacement cycles.
For Market Incumbents: Acquire cryobiology protocol expertise and thermal validation engineering capabilities to defend installed-base positions against emerging automation specialists. Incumbents should deepen backward integration into cryogenic-grade stainless steel sourcing to mitigate German and Japanese supplier concentration risk, while expanding predictive maintenance subscription penetration to offset capital equipment pricing softness in research segments. For New Entrants and Emerging Players: Enter via unbundled thermal qualification services and remote monitoring platforms targeting pre-revenue cell therapy developers in the United States seeking to preserve cash during facility commissioning. White-space opportunities concentrate in Indian contract manufacturing organizations responding to CDSCO's ICH harmonization and PLI scheme incentives, with menu-based service tiers offering lower customer acquisition friction than full equipment sales. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized thermal equipment fabricators possessing cryogenic protocol customization capabilities and established relationships with Basel and Boston biopharma clusters. Long-term viability favors vendors integrating disposable bag assemblies with controlled-rate freezing hardware, as single-use convergence eliminates cross-contamination risks in multi-product cell therapy facilities. Watch for REACH F-Gas Regulation quota tightening as inflection indicator accelerating displacement of mechanical refrigeration toward liquid nitrogen architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Unbundling | Menu-based thermal qualification tiers match expenditure to facility maturity stages. |
| Single-Use Integration | Disposable bag convergence with controlled-rate freezing eliminates cross-contamination exposure. |
| Predictive Maintenance Subscription | Remote thermal monitoring creates recurring revenue beyond capital equipment transactions. |
| Backward Integration into Alloys | In-house cryogenic-grade stainless steel sourcing reduces German-Japanese supplier dependency. |
| Automated Compliance Documentation | 21 CFR Part 11-integrated systems compress batch release timelines from weeks to days. |
Methodological Framework
Direct dialogue with bioprocess automation engineers, thermal validation specialists, cell therapy manufacturing directors, and GMP facility commissioning managers grounded qualitative findings, cross-referenced against FDA guidance documents, EMA ATMP submissions, 21 CFR Part 11 audit records, and cryogenic equipment qualification protocols. Bottom-up equipment shipment analysis and top-down biopharmaceutical capital expenditure tracking were triangulated to validate market sizing.
Segment-level projections across product type, end user, application, and technology dimensions were generated through the analysis window, with CAGRs derived from equipment replacement cycle compression, regulatory validation burden escalation, and cell therapy manufacturing scale-up trajectories. Cryogenic infrastructure investment pipelines, CDMO capacity expansion announcements, and pharmacopeial standard evolution provided industry-specific forecast inputs.
Inputs from regulatory filing databases and equipment vendor service contract disclosures were available through the study window; gaps in pre-revenue cell therapy developer capital planning introduce uncertainty bands around near-term demand trajectories. Forecasts reflect assumptions regarding FDA enforcement consistency, REACH F-Gas Regulation implementation timing, and cryogenic supply network density evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Marine HVAC Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
Spray Booth Ventilation System Market