
 Industrial Boiler Market | 2026-2036
Industrial Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Boiler Market Analysis
Stainless steel is realigning boiler fabrication economics as manufacturers phase out carbon steel pressure vessels to meet stricter corrosion-resistance specifications. Babcock & Wilcox Enterprises leverages its North American installed base to sustain aftermarket service revenue streams. Siemens competes through digital twin integration for predictive maintenance across European utility fleets. Dongfang Electric Corporation anchors its position with ultra-supercritical boiler technology leadership in Asian power markets.
An industrial boiler is a closed vessel generating steam or hot water through combustion, electric resistance, or waste heat recovery, typically operating at pressures from 15 to 3,200 psi and temperatures exceeding 300°F to drive mechanical processes or district heating networks. Water-tube designs dominate utility-scale installations where higher pressures and outputs are required, while fire-tube configurations retain cost advantages in smaller manufacturing settings. Natural gas-fired units lead fuel-type demand in regions with pipeline infrastructure, though hydrogen-ready burner retrofits represent the fastest-growing engineering segment as facilities prepare for fuel-switching mandates.
The EPA enforces New Source Performance Standards under the Clean Air Act that limit nitrogen oxide and particulate emissions from industrial boilers, compelling facility operators toward low-NOx burners or fuel conversions. China's Ministry of Ecology and Environment applies GB 13271 emission standards that force coal-fired boiler retirements in urban clusters. The EU F-Gas Regulation and Industrial Emissions Directive together restrict fluorinated greenhouse gases and mandate Best Available Techniques for combustion efficiency. Stakeholders must weigh stranded-asset risk against the capital requirements of hydrogen-compatible boiler architectures as regulatory timelines compress.
Market Dynamics
The EPA's Maximum Achievable Control Technology standards are compressing capital cycles for fossil-fuel boiler operators, forcing premature asset retirement decisions before depreciation schedules conclude. This regulatory compression is restructuring competitive positioning toward hydrogen-ready architectures and ultra-supercritical steam systems.
Growth Catalysts
- Dual carbon mandates:China's state-backed industrial zones mandate boiler upgrades under national carbon neutrality targets, creating replacement demand for high-efficiency units.
- Corrosion-resistant materials:Stainless steel pressure vessels are displacing carbon steel fabrication to meet stricter durability specifications in chemical processing environments.
- Digital twin integration:Predictive maintenance platforms are reducing unplanned downtime across European utility fleets, extending asset service lives.
Market Restraints
- Chromium-nickel alloy volatility:Stainless steel input costs fluctuate with mining supply concentration in South Africa and Indonesia, squeezing fabrication margins.
- Stranded-asset risk:The EU F-Gas Regulation and Industrial Emissions Directive accelerate obsolescence timelines for conventional combustion units.
- Hydrogen infrastructure gaps:Pipeline delivery networks remain underdeveloped outside Germany and the Netherlands, limiting fuel-switching feasibility.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for capital goods manufacturing attract boiler component localization investments.
- Waste heat recovery:Steel and cement plants are retrofitting exhaust-capture systems to meet ISO 50001 energy management standards.
- Aftermarket service unbundling:Independent predictive maintenance providers are penetrating North American installed bases previously captive to OEM service contracts.
Industry Challenges
- Welder certification bottlenecks:ASME Section IX qualified pressure vessel welders face acute shortages across Midwest US manufacturing corridors.
- Legacy control system integration:Hydrogen-ready burner retrofits require incompatible DCS architecture upgrades at petrochemical complexes.
- CE marking timeline compression:The EU Machinery Directive's updated conformity assessment procedures extend certification cycles for modular boiler skids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Boiler Market |
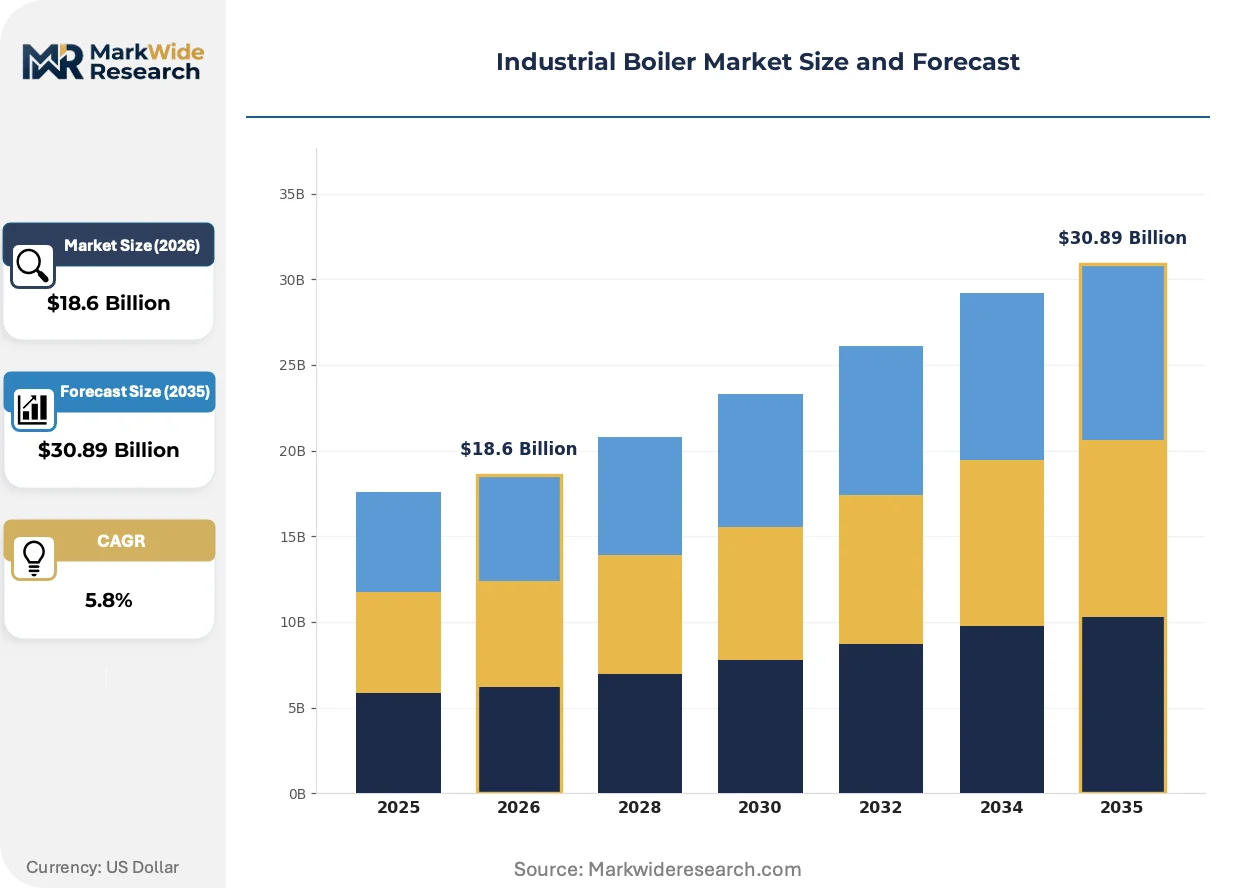
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-tube Boiler, Water-tube Boiler, Electric Boiler, Combination Boiler, Waste Heat Boiler Fuel Type: Natural Gas, Oil-fired, Coal-fired, Biomass, Electric, Hydrogen Application: Power Generation, Textile Manufacturing, Chemical Processing, Food Processing, Paper Production, Metal Processing End User Industry: Manufacturing Plants, Power Plants, Refineries, Pulp & Paper Mills, Pharmaceutical Facilities, Food & Beverage Facilities |
| Companies Covered | Babcock & Wilcox Enterprises, Siemens, Mitsubishi Heavy Industries, Dongfang Electric Corporation, Thermax Limited, IHI Corporation, Cleaver-Brooks, Bosch Industriekessel, Forbes Marshall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Boiler Market Emerging Trajectories
Boiler engineering is converging around three vectors: materials science advancement, emissions compliance automation, and service model unbundling. Each vector is compressing traditional equipment lifecycle economics.
Advanced refractory ceramics with silicon carbide matrices are rewriting thermal efficiency benchmarks for ultra-supercritical steam generators. Power utilities in South Korea and Japan are deploying these linings to extend maintenance intervals beyond 36 months. The technology is compressing competitive differentiation around heat-rate performance rather than unit capital cost.
The EU F-Gas Regulation's phasedown schedule for fluorinated greenhouse gases is forcing refrigerant-based heat recovery system redesigns. Industrial operators must retrofit or replace vapor-compression heat pumps with absorption alternatives. Food processing facilities in Germany and the Netherlands face the most compressed compliance timelines due to earlier national implementation dates.
Performance-based service contracts are displacing time-and-material maintenance agreements across North American chemical processing clusters. Facility operators now transfer availability risk to OEM service providers through guaranteed steam-output agreements. This shift is most visible in Texas and Louisiana Gulf Coast refineries where unplanned downtime costs exceed $2 million per day.
Industrial Boiler Market Segmentation
Boiler procurement patterns diverge sharply between capital-intensive utility operators and cost-sensitive manufacturing facilities. Understanding these segment boundaries clarifies why technology roadmaps, fuel strategies, and service expectations fracture across customer categories.
Product Type:
Volume concentrates in mature pressure vessel designs, while premium capture shifts toward emissions-compliant and hybrid configurations.
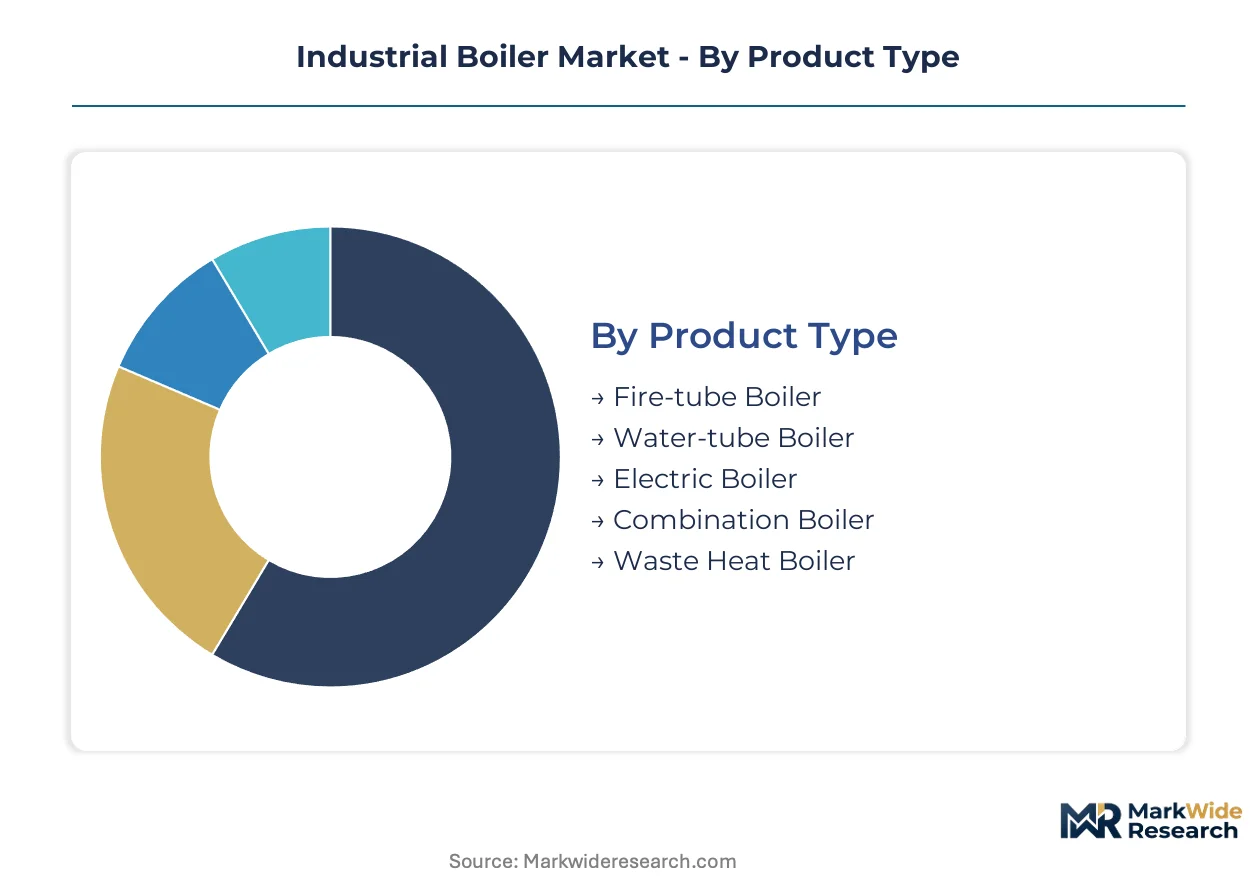
- Water-tube Boiler:High-pressure steam generators circulate water through tubes heated externally by combustion gases. Demand clusters in utility-scale power plants across China and India where ultra-supercritical steam conditions require this architecture. The design commands fabrication premiums due to ASME Section I certification complexity and specialized welder requirements.
- Fire-tube Boiler:Combustion gases pass through tubes immersed in a water shell, creating lower-pressure steam suitable for manufacturing processes. Smaller chemical processors in Texas and Louisiana favor these units for their lower capital outlay and simpler maintenance protocols. The segment faces margin compression as stainless steel pressure vessel costs escalate.
- Electric Boiler:Resistance heating elements generate steam without combustion emissions, enabling zero-direct-emission operation where grid electricity is available. Pharmaceutical cleanrooms in Germany and the Netherlands specify these for process purity requirements.
- Combination Boiler:Dual-fuel architectures switch between natural gas and backup oil firing to ensure steam continuity during pipeline disruptions. Hospital and district heating operators in Japan deploy these for energy security compliance.
- Waste Heat Boiler:Exhaust gas recovery systems capture thermal energy from steel, cement, and refinery processes. Indian steel producers retrofit these under ISO 50001 energy management mandates to reduce imported fuel dependence.
Today's leader: Water-tube designs anchor utility procurement. Tomorrow's challenger: Waste heat recovery climbs the fastest as fuel costs harden.
Fuel Type:
Application context determines fuel selection more than thermal efficiency metrics, with infrastructure availability and regulatory timelines overriding pure engineering optimization.
- Natural Gas:Cleanest combustion profile among fossil options with established pipeline networks across North America and Europe. Gulf Coast refineries and chemical clusters specify these for NOx compliance under EPA Maximum Achievable Control Technology standards.
- Hydrogen:Zero-carbon combustion product positions this as the long-term replacement for natural gas in EU jurisdictions. Dutch and German industrial zones pilot hydrogen-ready burner retrofits ahead of anticipated fuel-switching mandates.
- Oil-fired:Liquid fuel storage enables operation in regions lacking pipeline infrastructure or as backup for critical processes. Remote mining operations in Western Australia and Canadian oil sands rely on these for energy autonomy.
- Coal-fired:Lowest fuel cost per BTU retains relevance in markets with domestic coal reserves. China's Ministry of Ecology and Environment forces urban retirements while permitting continued operation in designated industrial corridors.
- Biomass:Agricultural and forestry residue combustion qualifies for renewable energy incentives in Nordic countries. Swedish district heating networks integrate these for carbon-neutral baseload supply.
- Electric:Grid-powered generation eliminates stack emissions at point of use, valued in urban air quality management zones. Swiss pharmaceutical manufacturers specify these to meet cantonal environmental ordinances.
Natural gas dominates current procurement volumes. Hydrogen configurations represent the steepest expansion trajectory as EU F-Gas Regulation timelines compress.
Application:
Process steam requirements vary by temperature, pressure, purity, and reliability needs, fragmenting supplier specialization across industrial verticals.
- Chemical Processing:Continuous high-pressure steam for reactor heating and distillation columns demands 99.9% availability. BASF and Dow facilities in Ludwigshafen and Freeport specify redundant boiler configurations with predictive maintenance contracts.
- Power Generation:Utility-scale steam turbines require supercritical conditions above 3,200 psi. State Power Investment Corporation deploys ultra-supercritical units in Chinese coastal provinces for efficiency gains.
- Food Processing:Sanitary steam for sterilization and cooking requires culinary-grade water treatment. Nestlé and Unilever plants in Switzerland and the Netherlands specify stainless steel construction for corrosion resistance.
- Textile Manufacturing:Dyeing and finishing operations consume large steam volumes at moderate pressures. Bangladesh and Vietnam garment clusters prioritize low capital cost over thermal efficiency.
- Paper Production:Kraft pulping and drying sections integrate boilers with recovery systems for black liquor combustion. Finnish and Swedish mills lead in energy self-sufficiency through this integration.
- Metal Processing:Rolling mill heating and surface treatment require rapid steam response to batch schedules. German automotive steel suppliers specify quick-start boilers for demand fluctuation.
Chemical processing commands the highest specification intensity. Power generation offers the largest unit scale.
End User Industry:
Ownership structure and operational expertise shape procurement—merchant operators favor performance contracts while integrated manufacturers prioritize capital control.
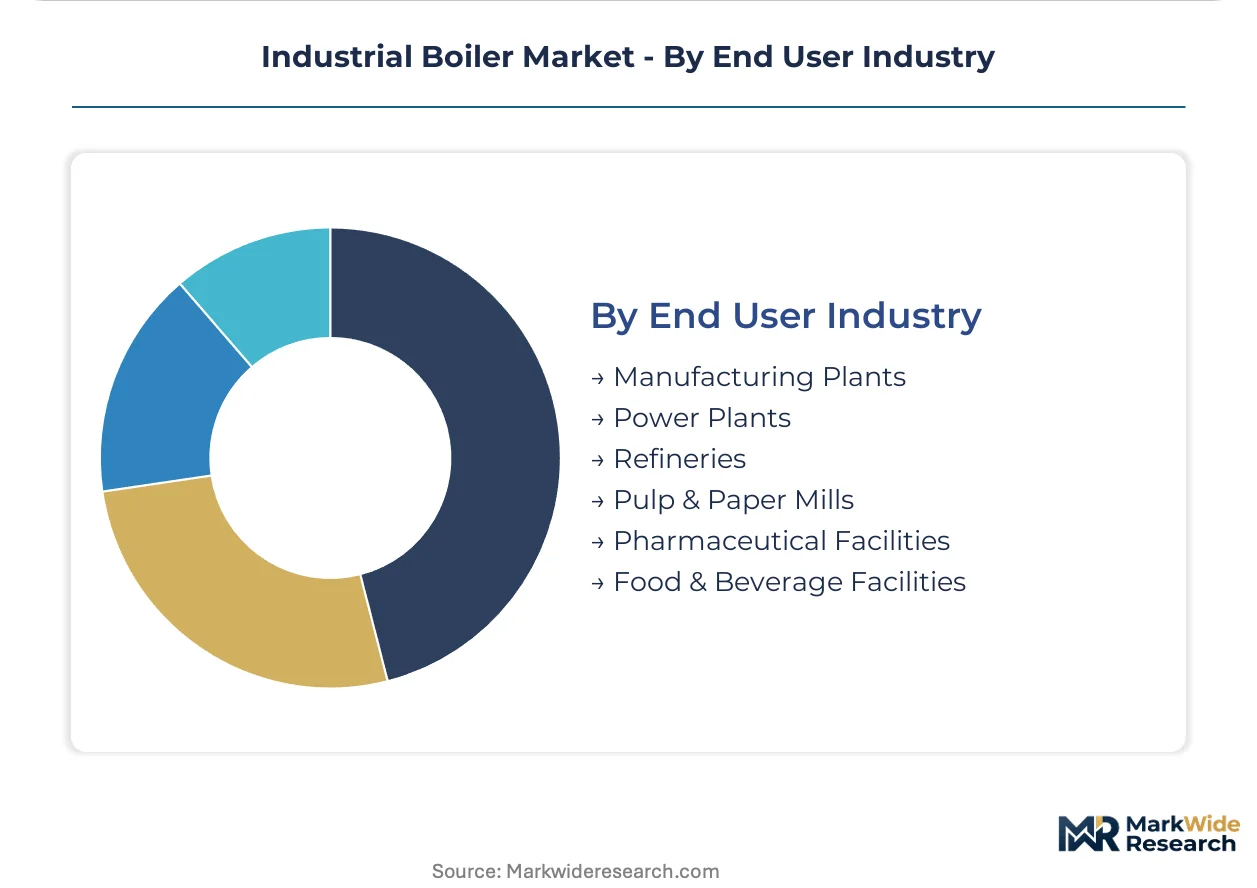
- Refineries:Complex steam networks support hydrocracking, distillation, and sulfur recovery with multiple pressure headers. Reliance Industries and Saudi Aramco facilities operate captive boiler fleets with in-house engineering capabilities.
- Power Plants:Independent power producers and utilities prioritize heat rate performance over capital cost. NTPC and Taipower specify ultra-supercritical technology for coal units and combined-cycle configurations for gas.
- Manufacturing Plants:Diverse process steam needs across automotive, electronics, and machinery sectors favor modular, skid-mounted solutions. Foxconn and TSMC facilities in Taiwan specify rapid-deployment units for capacity scaling.
- Pulp & Paper Mills:Chemical recovery boilers integrate with kraft pulping for energy self-sufficiency. International Paper and Stora Enso operate among the most efficient biomass-integrated steam systems.
- Pharmaceutical Facilities:FDA and EMA compliance mandates clean steam generation with documented purity validation. Roche and Novartis sites in Basel specify electric boilers for batch process control.
- Food & Beverage Facilities:Brewery pasteurization and dairy sterilization require culinary steam with strict chemical limits. Anheuser-Busch InBev and Danone plants specify stainless steel construction and automated water treatment.
Refineries and power plants anchor premium technology adoption. Pharmaceutical and food facilities drive specification intensity for purity compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed industrial zones anchor boiler replacement demand under dual carbon mandates, while regulatory compression in Europe and North America accelerates technology transitions toward hydrogen-ready architectures.
China
State Power Investment Corporation deploys ultra-supercritical units across coastal provinces to displace aging coal-fired capacity. The Ministry of Ecology and Environment enforces GB 13271 emission standards that mandate urban boiler retirements. Yangtze River Delta manufacturing clusters absorb the bulk of high-efficiency water-tube installations.
United States
Gulf Coast refineries and petrochemical complexes drive demand for low-NOx natural gas systems under EPA Maximum Achievable Control Technology compliance. The EPA enforces New Source Performance Standards that limit nitrogen oxide emissions from industrial combustion. Texas and Louisiana chemical processing corridors concentrate aftermarket service contract activity.
Germany
Dutch and German industrial zones pilot hydrogen-ready burner retrofits ahead of anticipated fuel-switching mandates. The EU F-Gas Regulation and Industrial Emissions Directive restrict fluorinated greenhouse gases and mandate Best Available Techniques. Ruhr Valley manufacturing facilities face compressed compliance timelines for absorption heat pump integration.
India
Steel producers retrofit waste heat recovery systems under ISO 50001 energy management mandates to reduce imported fuel dependence. The Production-Linked Incentive scheme for capital goods manufacturing attracts boiler component localization investments. Maharashtra and Gujarat industrial corridors concentrate fabrication capacity expansion.
Japan
Power utilities deploy advanced refractory ceramics with silicon carbide matrices to extend maintenance intervals beyond 36 months. METI oversees industrial efficiency standards that accelerate ultra-supercritical adoption. Kansai and Chubu regions concentrate hospital and district heating operators deploying combination boilers for energy security compliance.
Industrial Boiler Market Vendor Landscape
Technology licensing dominates the current landscape as fabricators seek rapid access to ultra-supercritical and hydrogen-ready architectures without captive R&D investment. The vendor base splits between integrated power equipment conglomerates and specialized pressure vessel fabricators. Three archetypes define competitive positioning: state-affiliated energy technology groups, European industrial automation specialists, and regional boiler engineering houses. M&A activity concentrates on aftermarket service capability acquisition, while strategic partnerships bridge hydrogen infrastructure gaps.
Among Asia-Pacific-based conglomerates, Mitsubishi Heavy Industries and IHI Corporation exemplify the integrated power equipment archetype with cross-border project execution capabilities. Siemens occupies a position within the European automation tier, leveraging digital twin integration for predictive maintenance platforms. Dongfang Electric Corporation anchors the state-affiliated technology group segment with concentrated ultra-supercritical expertise in domestic and export power markets.
| Leading Market Players |
|---|
| Babcock & Wilcox Enterprises |
| Siemens |
| Mitsubishi Heavy Industries |
| Dongfang Electric Corporation |
| Thermax Limited |
| IHI Corporation |
| Cleaver-Brooks |
| Bosch Industriekessel |
| Forbes Marshall |
| Others |
Supply Flow & Price Mechanics
ASME Section IX qualified pressure vessel welders in the US Midwest create labor-cost differentials that widen pricing-tier spreads between premium certified fabricators and economy-grade regional suppliers. Stainless steel input volatility from South African and Indonesian mining concentration further compresses margins at the standard tier while elevating premiums for corrosion-resistant specifications.
Pricing Analysis
Input-cost pass-through from chromium-nickel alloy markets shapes tiered pricing across fabrication grades. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified utility-scale builders from regional fabricators serving manufacturing plants. Cost compression in the standard tier intensifies because stainless steel pressure vessel specifications escalate faster than contract escalation clauses allow. Chemical processing operators in Texas and Louisiana Gulf Coast corridors show least price sensitivity due to unplanned downtime costs exceeding $2 million per day, while Bangladesh and Vietnam textile clusters prioritize capital outlay over thermal efficiency.
Supply Chain Analysis
Single-source vulnerability sits with South African and Indonesian chromium-nickel mining concentration that feeds stainless steel production. Fabrication capacity clusters in China, India, and Germany with specialized pressure vessel welding expertise. Raw material dependencies center on silicon carbide refractories, ASME-certified steel plate, and hydrogen-ready burner components. Tariff exposure on alloy imports threatens margin stability for North American fabricators. Distribution runs through OEM-direct contracts for utility-scale projects and regional distributor networks for manufacturing facility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial boiler market functions as a regulatory compounder where EPA Maximum Achievable Control Technology standards and China's GB 13271 emission mandates force premature asset replacement ahead of depreciation schedules.
For Market Incumbents: Hedge stranded-asset exposure by accelerating hydrogen-ready burner architecture development before EU fuel-switching mandates harden. Acquire independent predictive maintenance providers penetrating North American installed bases to recapture aftermarket revenue streams threatened by service contract unbundling. Deepen backward integration into stainless steel pressure vessel fabrication to offset South African and Indonesian alloy supply volatility. For New Entrants and Emerging Players: Begin with India's Production-Linked Incentive scheme for capital goods manufacturing to localize boiler component fabrication under import substitution incentives. Target waste heat recovery retrofits in Maharashtra and Gujarat steel corridors where ISO 50001 energy management mandates drive demand. Deploy modular skid-mounted solutions for Foxconn and TSMC-style rapid-deployment capacity scaling in electronics manufacturing clusters. For Investors and Strategic Acquirers: Power equipment conglomerates are the most active acquirer in this space, consolidating aftermarket service capabilities to capture lifetime value from installed ultra-supercritical fleets. Long-term viability hinges on hydrogen infrastructure maturation timelines and regulatory compression pacing. Watch German and Dutch industrial zone hydrogen pilot programs as the inflection signal for fuel-switching mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive chromium-nickel sourcing insulates margins from South African mining volatility. |
| Hydrogen-Ready Burner Development | Anticipates EU F-Gas Regulation fuel-switching mandates in German industrial zones. |
| Digital Twin Platform Deployment | Siemens-style predictive maintenance extends asset service lives across European utility fleets. |
| Aftermarket Service Acquisition | Recaptures revenue streams threatened by independent predictive maintenance providers. |
| Modular Skid Manufacturing Scale-Up | Meets Foxconn and TSMC rapid-deployment requirements in electronics manufacturing corridors. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combine with secondary validation from EPA enforcement databases, ASME certification registries, SEC 10-K filings, and customs trade data. Triangulation across these sources ensures demand estimates align with fabrication capacity disclosures.
Input-output matrix framing maps fuel-type demand against regional infrastructure availability and regulatory compliance timelines. Segmentation dimensions span product architecture, fuel source, application vertical, and end-user industry ownership structure. CAGRs derive from unit shipment trajectories reconciled against average selling price movements across the projection horizon. Hydrogen pipeline development milestones and dual carbon mandate implementation pacing inform scenario-weighted outputs.
Several conditions sit outside the modeled scope, including breakthrough nuclear small modular reactor displacement of industrial steam demand and unanticipated suspension of EPA enforcement discretion. Forecasts reflect documented assumptions about regulatory timeline adherence and alloy supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
China HVAC Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Heating and Cooling Market
HVAC Equipment
HVAC Air Quality Monitoring Market