
 Global Chilled Beam System Market | 2026-2036
Global Chilled Beam System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chilled Beam System Market Intelligence
The EU Green Deal and its building renovation targets is consolidating specification authority around low-energy HVAC architectures across European commercial stock. FläktGroup leverages its pan-European manufacturing footprint to dominate active chilled beam tenders in Scandinavian public sector projects. Lindab anchors its position through backward integration into galvanized ducting and diffuser fabrication. TROX GmbH specializes in laboratory-critical environments where containment and thermal stability override first-cost considerations.
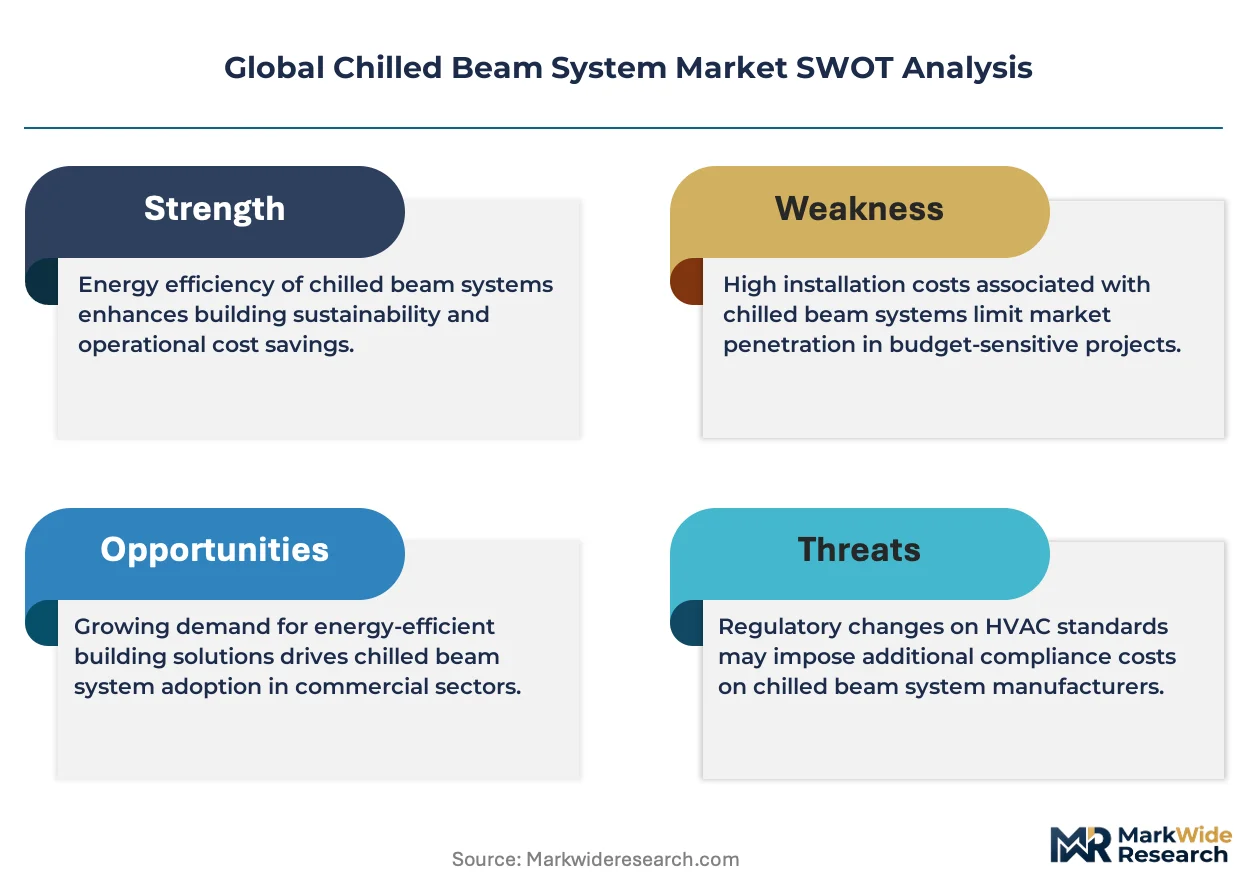
A chilled beam system is a hydronic terminal unit that circulates tempered water through a finned heat exchanger to provide sensible cooling or heating via natural or forced convection, typically operating with supply water temperatures between 14°C and 17°C to prevent surface condensation. Its primary commercial purpose is to decouple ventilation from thermal conditioning, enabling downsized air handling plant and substantial fan energy reduction. Active chilled beams lead specification volumes in Northern European office retrofits due to their higher cooling capacity density, while passive configurations occupy the premium residential and heritage building niche where ductwork intrusion is structurally constrained. Integrated sensors and modulating valve technology segments are recording the fastest specification growth as building management systems mandate zone-level telemetry compliance.
EMA efficiency benchmarks, REACH material restrictions on copper alloy coatings, and CE marking under the MDR-aligned pressure equipment directive collectively elevate compliance costs for non-European suppliers seeking continental project access. The EPA's phasedown of hydrofluorocarbon refrigerants under the American Innovation and Manufacturing Act is redirecting U.S. federal and institutional procurement toward water-based alternatives in new construction and major renovation schedules. Stakeholders must monitor how evolving F-Gas Regulation quotas and emerging state-level building performance standards reshape competitive qualification thresholds across multiple procurement jurisdictions.
Market Dynamics
The EU F-Gas Regulation's phasedown schedule is compressing specification windows for hydronic alternatives, forcing HVAC contractors across Northern Europe to requalify installation crews for water-based radiant systems ahead of refrigerant-dependent equipment obsolescence.
Growth Catalysts
- EU Green Deal building renovation targets:Mandatory energy performance upgrades across German and Dutch commercial stock are specifying active chilled beams for simultaneous thermal conditioning and ventilation decoupling.
- Healthcare infrastructure expansion:Singapore's hospital construction pipeline and NHS England estate modernization programs are consolidating demand for laboratory-grade climate stability.
- Dual-carbon policy alignment:China's MEE efficiency benchmarks for public buildings are redirecting municipal procurement toward low-exergy cooling architectures in Yangtze River Delta commercial developments.
Market Restraints
- Copper price volatility:Finned heat exchanger fabrication depends on copper alloy feedstock subject to LME trading swings, compressing margin buffers for mid-tier system integrators.
- Specialized installation labor scarcity:Certified hydronic commissioning engineers concentrate in Nordic markets, creating bottleneck risk for GCC tower rollouts.
- REACH material compliance:ECHA restrictions on hexavalent chromium surface treatments for galvanized ducting are extending supplier qualification timelines by 8-14 months.
Strategic Opportunities
- Indian commercial real estate:BIS energy code enforcement in Bangalore and Hyderabad IT corridors remains underpenetrated by European chilled beam suppliers despite cooling degree-day expansion.
- Sensor-BMS convergence:Integration of zone-level CO2 and temperature telemetry with BACnet protocols is automating demand-controlled ventilation in Scandinavian retrofit corridors.
- US federal procurement pivot:EPA AIM Act implementation is redirecting GSA and VA hospital construction schedules toward water-based alternatives before 2027 refrigerant quota cuts.
Industry Challenges
- Hydronic commissioning expertise gap:Precision balancing of 14-17°C supply water temperatures requires skills distinct from conventional DX system installation, extending project handover timelines.
- Legacy building structural constraints:Passive beam installation in UK heritage stock encounters listed building consent friction where ceiling soffit modification triggers Historic England review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chilled Beam System Market |
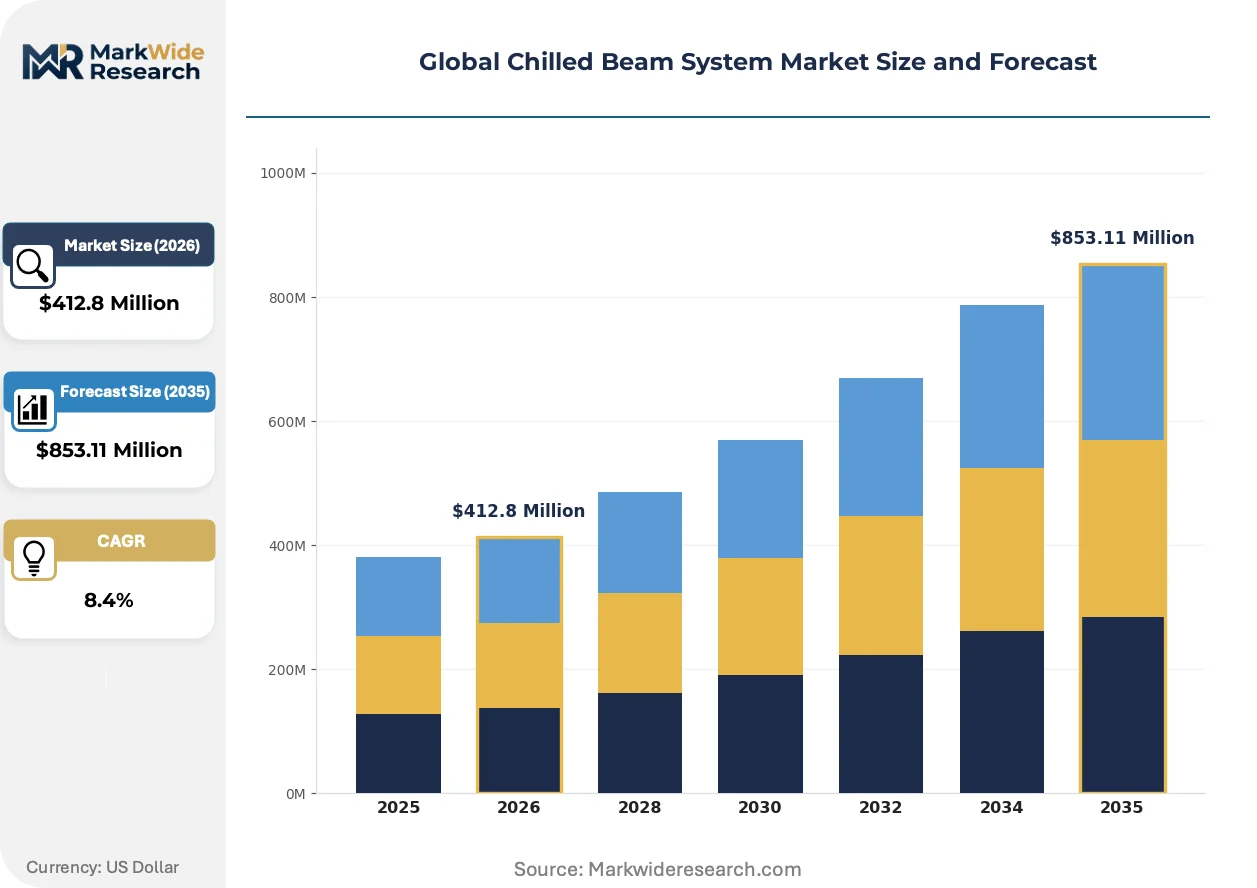
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $853.11 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Chilled Beams, Passive Chilled Beams, Customized Units, Linear Beams Technology: Thermal Comfort Controls, Hydronic Systems, Integrated Sensors, Modulating Valves Application: Commercial Buildings, Educational Institutions, Government Facilities, Data Centers, Cultural Centers End User: Architectural Firms, HVAC Contractors, Facility Managers, Property Developers |
| Companies Covered | FläktGroup, Halton Group, Lindab, TROX GmbH, Price Industries, Swegon Group AB, Systemair AB, Johnson Controls, Climate Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chilled Beam System Market Strategic Shifts & Innovations
Specification authority is migrating from mechanical contractors to building management system integrators as zone-level telemetry becomes a procurement gate. Three developments are compressing competitive qualification thresholds.
Modulating valve technology paired with predictive control algorithms is automating condensation risk management in variable-load environments. German university hospital estates are specifying these packages for operating theatre suites where thermal stability overrides energy optimization. The technology is compressing commissioning timelines from six weeks to ten days while reducing warranty callback rates.
REACH-aligned material substitution is forcing copper-aluminum alloy reformulation across heat exchanger supply chains. ECHA's 2024 restriction proposals on nickel release rates are accelerating ceramic coating pilot programs at Finnish and Swedish fabrication facilities. Laboratory-critical segments in Switzerland and Austria are qualifying these surfaces first due to Swissmedic contamination protocols.
Buyer concentration among Nordic facilities management conglomerates is consolidating tender participation requirements. Stockholm-based FM providers now mandate ISO 50001 energy management certification and five-year predictive maintenance data packages as baseline bid qualifications. Danish and Norwegian public sector frameworks are adopting these standards through 2026-2027 procurement cycles.
Global Chilled Beam System Market Segmentation
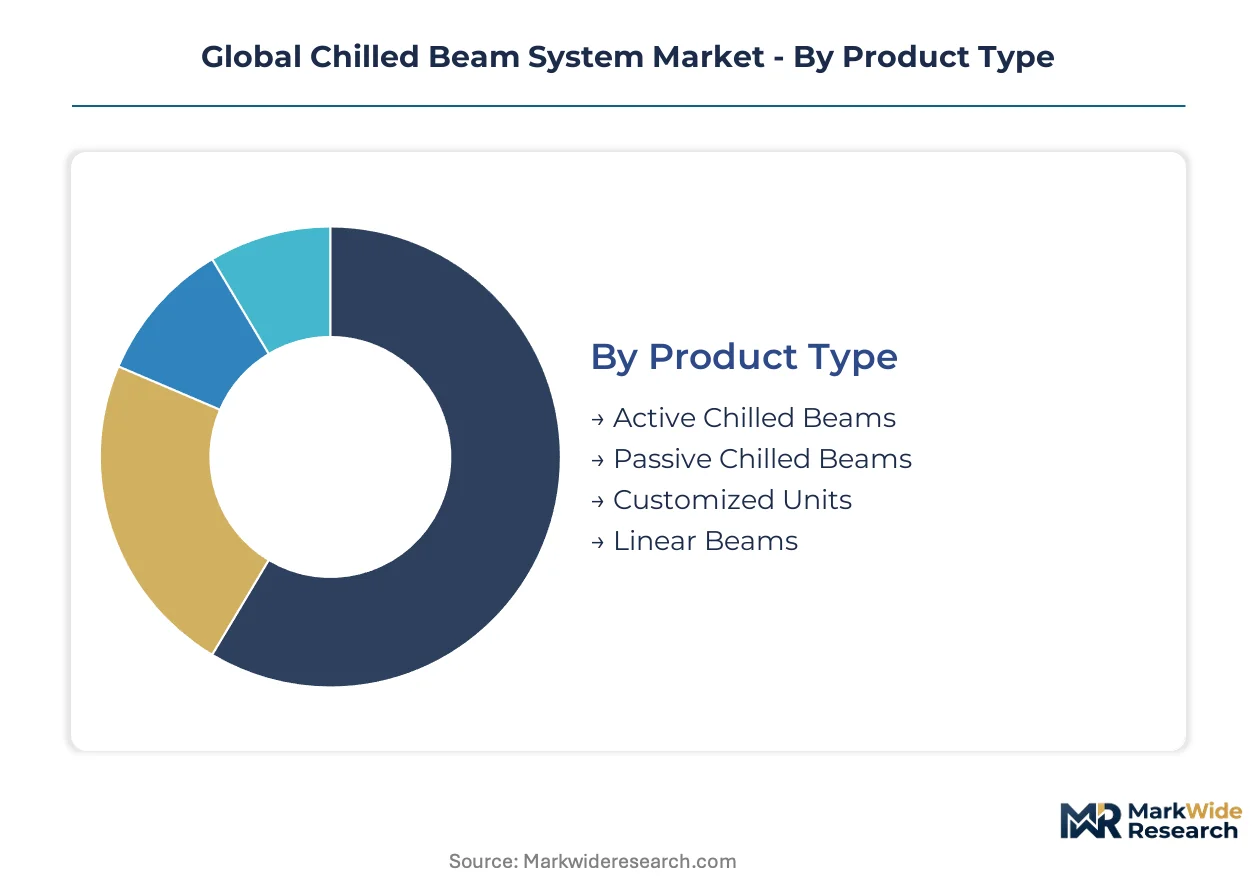
Segmentation reveals how capital deployment, specification authority, and installation complexity vary across chilled beam configurations. Understanding these distinctions enables suppliers to align product development with procurement gatekeepers and project risk profiles.
Product Type:
Capital intensity varies sharply between active and passive configurations, with active systems demanding integrated air handling infrastructure and precision commissioning.
- Active Chilled Beams:These units combine primary air supply with hydronic heat exchange, requiring ductwork integration and higher mechanical plant investment. Demand concentrates in German and Dutch office retrofits where EU Green Deal renovation targets mandate simultaneous ventilation downsizing and thermal conditioning upgrades.
- Passive Chilled Beams:Relying solely on natural convection from ceiling-mounted heat exchangers, these systems eliminate ductwork entirely. UK heritage building projects specify passive configurations where Historic England consent processes prohibit structural ceiling modifications.
- Customized Units:Bespoke fabrication for laboratory-critical environments in Swiss hospital estates commands premium engineering margins.
- Linear Beams:Architectural integration for open-plan commercial towers in Singapore and Dubai prioritizes aesthetic continuity over thermal density.
Active chilled beams absorb the bulk of installed capacity; passive chilled beams are expanding most quickly in constrained retrofit corridors.
Technology:
Specification authority is migrating toward building management system integrators as zone-level telemetry becomes a procurement requirement across Nordic public sector frameworks.
- Thermal Comfort Controls:PID-based algorithms manage supply water temperature modulation to prevent surface condensation in variable-load environments. German university hospital estates specify these packages for operating theatre suites where Swissmedic contamination protocols override energy optimization priorities.
- Hydronic Systems:Circulation networks operating at 14-17°C supply temperatures form the core infrastructure for water-based radiant cooling architectures. REACH material restrictions on copper alloy coatings are extending supplier qualification timelines for heat exchanger fabrication.
- Integrated Sensors:Zone-level CO2 and temperature telemetry with BACnet protocol integration automates demand-controlled ventilation in Scandinavian retrofit corridors.
- Modulating Valves:Predictive control algorithms compress commissioning timelines from six weeks to ten days while reducing warranty callback rates in Finnish healthcare estates.
Hydronic systems anchor current specification volumes; integrated sensors are climbing the fastest as FM providers mandate five-year predictive maintenance data packages.
Application:
Project scale and performance requirements create distinct procurement channels, with laboratory-critical segments overriding first-cost considerations.
- Commercial Buildings:Northern European office stock dominates active beam deployment, with Stockholm-based FM conglomerates consolidating tender participation requirements through ISO 50001 certification mandates.
- Educational Institutions:University estates in Denmark and Norway are adopting Nordic public sector procurement standards for energy management compliance through 2026-2027 cycles.
- Government Facilities:NHS England estate modernization programs specify laboratory-grade climate stability for administrative and clinical spaces.
- Data Centers:Singapore's tropical climate and high cooling degree-day profiles create specialized load profiles for precision hydronic conditioning.
- Cultural Centers:Austrian museum estates qualify ceramic-coated heat exchanger surfaces first due to contamination-sensitive artifact preservation protocols.
Commercial buildings retain the largest installed base; data centers are gaining share fastest as tropical markets expand precision cooling infrastructure.
End User:
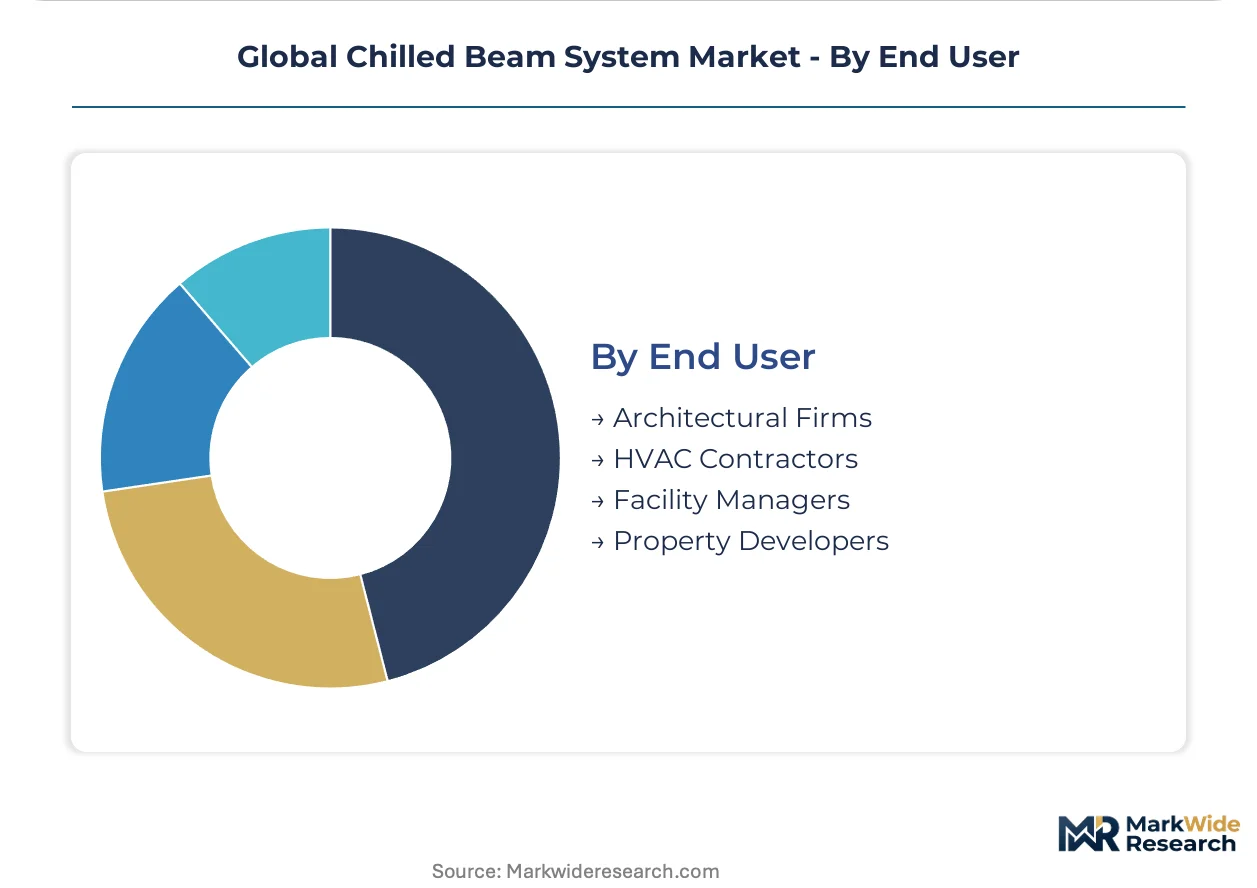
Specification authority fragmentation creates competing channel strategies, with architectural influence strongest in premium segments and contractor control dominating volume deployment.
- Architectural Firms:Design-phase specification for Gulf Cooperation Council commercial towers prioritizes linear beam aesthetic integration.
- HVAC Contractors:Northern European installation crews require requalification for water-based radiant systems ahead of refrigerant-dependent equipment obsolescence under F-Gas Regulation phasedown schedules.
- Facility Managers:Stockholm-based FM providers now mandate predictive maintenance data packages as baseline bid qualifications.
- Property Developers:Bangalore and Hyderabad IT corridor projects remain underpenetrated by European suppliers despite BIS energy code enforcement expansion.
HVAC contractors control the majority of volume procurement; facility managers are consolidating specification authority fastest through framework agreement concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm anchors specification authority for chilled beam systems, with Nordic facilities management conglomerates consolidating tender participation requirements across Northern European procurement frameworks.
Germany
EU Green Deal building renovation targets mandate energy performance upgrades across commercial stock. The F-Gas Regulation phasedown compresses specification windows for hydronic alternatives. Frankfurt and Munich office retrofits specify active chilled beams for simultaneous ventilation downsizing and thermal conditioning upgrades.
United Kingdom
NHS England estate modernization programs consolidate demand for laboratory-grade climate stability. Historic England review cycles create friction for passive beam installation in heritage stock where ceiling soffit modification triggers consent processes. London commercial towers and Cambridge research parks dominate specification volumes.
Singapore
Hospital construction pipelines and tropical cooling degree-day profiles create specialized load profiles for precision hydronic conditioning. The Building and Construction Authority enforces stringent energy codes for commercial developments. Marina Bay and Jurong Lake District tower rollouts concentrate specification activity.
United States
EPA AIM Act implementation redirects GSA and VA hospital construction schedules toward water-based alternatives. State-level building performance standards reshape competitive qualification thresholds across multiple procurement jurisdictions. Federal and institutional procurement in Washington D.C. and Boston medical districts pivots before 2027 refrigerant quota cuts.
Sweden
Public sector procurement frameworks mandate ISO 50001 energy management certification for baseline bid qualifications. Stockholm-based FM providers require five-year predictive maintenance data packages. Gothenburg and Malmö university estates adopt Nordic procurement standards through 2026-2027 cycles.
Global Chilled Beam System Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification and commissioning capability dimensions. The vendor base stratifies between pan-European manufacturing footprints and regional fabrication specialists. Three archetypes dominate: integrated HVAC conglomerates with backward control over ducting supply, laboratory-critical environment specialists, and sensor-BMS convergence technology providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as refrigerant phasedown schedules compress installation crew requalification timelines.
Among Nordic-based fabricators, FläktGroup, Lindab, and TROX GmbH occupy distinct positioning vectors. FläktGroup exemplifies the pan-European manufacturing archetype with specification authority in Scandinavian public sector projects. Lindab represents backward integration into galvanized ducting and diffuser fabrication. TROX GmbH anchors the laboratory-critical environment tier where containment and thermal stability override first-cost considerations in Swissmedic-regulated segments.
| Leading Market Players |
|---|
| FläktGroup |
| Halton Group |
| Lindab |
| TROX GmbH |
| Price Industries |
| Swegon Group AB |
| Systemair AB |
| Johnson Controls |
| Climate Technologies |
| Others |
Cost & Logistics Intelligence
Backward integration into galvanized ducting and diffuser fabrication anchors Lindab's supply position while compressing competitor margin buffers through captive cost control. This upstream control over critical HVAC components translates directly into pricing power across Nordic public sector tenders where REACH material compliance extends rival qualification timelines.
Pricing Analysis
Commissioning reliability serves as the dominant value-based pricing anchor, with German university hospital estates paying substantial premiums for predictive control algorithms that compress handover timelines. Three-tier pricing structure across premium, standard, and economy levels separates laboratory-critical Swissmedic-regulated segments from volume office retrofit deployments. Cost compression in mid-tier system integrator offerings is intensifying because copper LME trading swings erode fabrication margins. Healthcare infrastructure buyers exhibit the lowest price sensitivity due to thermal stability mandates, while GCC commercial developers drive hardest bargain on first-cost negotiations.
Supply Chain Analysis
Dual-sourcing requirements from Stockholm-based FM conglomerates now mandate ISO 50001-certified fabricators maintain qualified secondary heat exchanger suppliers across Finland, Sweden, and Germany. Finned heat exchanger production draws from copper alloy feedstock, ceramic coating pilot programs, and REACH-compliant galvanized ducting. Single-source vulnerability concentrates around Nordic-certified hydronic commissioning engineers, creating bottleneck exposure for rapid GCC tower rollouts. Distribution runs through pan-European manufacturing footprints serving Scandinavian retrofit corridors and Gulf Cooperation Council commercial developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phasedown schedules are forcing refrigerant-dependent equipment suppliers into distressed repositioning, consolidating viable participants around water-based radiant cooling architectures.
For Market Incumbents: Deploy predictive maintenance data packaging as the priority defensive lever. FläktGroup should deepen backward integration into sensor-BMS convergence technology to outpace TROX GmbH in laboratory-critical tenders. REACH-aligned material substitution investments protect against ECHA restriction proposals that would disqualify legacy coating formulations from Swiss hospital estates. Capacity addition in Finnish fabrication facilities secures ceramic-coated heat exchanger qualification timelines ahead of nickel release rate enforcement. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian commercial real estate offers the most penetrable white-space target. Bangalore and Hyderabad IT corridors remain underpenetrated by European suppliers despite BIS energy code enforcement expansion. A joint-venture route with established Nordic FM providers accelerates ISO 50001 certification access without standalone qualification investment. For Investors and Strategic Acquirers: Exit pathways concentrate in sensor-integrated hydronic specialists with BACnet protocol competencies and five-year predictive maintenance contract backlogs. Long-term viability favors fabricators with laboratory-critical environment credentials and pan-European manufacturing footprints capable of serving multiple regulatory jurisdictions. Watch for F-Gas Regulation quota compression velocity as the inflection signal indicating accelerated displacement timelines for refrigerant-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Pilot Program | ECHA nickel release restrictions accelerate Finnish and Swedish qualification timelines for Swissmedic-regulated segments. |
| Sensor-BMS Convergence Partnership | Stockholm FM conglomerates mandate zone-level telemetry compliance through BACnet protocol integration. |
| Backward Integration into Ducting | Lindab's captive galvanized supply compresses rival margins across EU Green Deal renovation tenders. |
| Hydronic Commissioning Certification | F-Gas Regulation phasedown forces contractor requalification for water-based radiant system installation. |
| ISO 50001 Certification Investment | Danish and Norwegian public sector frameworks adopt energy management mandates through procurement cycles. |
Research Approach
Independent corroboration across HVAC contractor interviews, facilities management procurement leads, and building management system integrators underwrites the qualitative findings. Primary fieldwork captured perspectives from hydronic commissioning engineers, architectural specification consultants, and regulatory affairs specialists across German, Swedish, and Singaporean project clusters. Secondary validation drew from EU F-Gas Regulation implementation trackers, ECHA restriction proposal databases, and NHS England estate modernization procurement disclosures. Bottom-up project pipeline analysis triangulated against top-down regulatory impact assessments.
Comparable-period anchoring referenced historical installation volumes across pre- and post-EU Green Deal announcement windows to establish baseline trajectory parameters. The analytical framework modeled product type, application, technology, and end-user dimensions throughout the forecast period. CAGRs were derived from segment-level deployment rates cross-referenced with regulatory phasedown schedules and copper price volatility bands. Chilled beam capacity utilization rates and REACH compliance cost inflation served as industry-specific forecast inputs.
Inputs from ECHA regulatory filings and Nordic FM framework agreements were available through the study window; gaps in real-time copper alloy spot pricing introduce uncertainty bands around fabrication margin assumptions. Deviation in F-Gas Regulation quota allocation velocity or ECHA restriction enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Aeration System Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
Cold Insulation Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Commercial Kitchen Ventilation System Market