
 UK Commercial Boiler Market | 2026-2036
UK Commercial Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
UK Commercial Boiler Market Analysis
Installer and M&E contractor networks is reconfiguring how commercial boilers reach end users across Britain. Worcester Bosch leverages its nationwide branch presence to sustain strong specification rates in education and healthcare projects. Viessmann competes through hydrogen-ready engineering and controls integration that appeals to facilities managers planning heating transitions. Cochran Limited anchors its position in heavy industrial applications where steam output requirements exceed standard commercial ranges.
A commercial boiler is a pressurized vessel designed to heat water or generate steam for space heating, hot water supply, or industrial process applications, typically operating at outputs from 50 kW to several megawatts with combustion efficiencies now commonly exceeding 90% in condensing configurations. These systems serve hotels, factories, schools, and retail complexes where reliable thermal delivery supports operations and occupant comfort. Condensing product types now lead value contribution as Part L compliance mandates higher efficiency thresholds across new and replacement installations. Natural gas fuel types still dominate installed volume, though biomass and electric segments are gaining specification share in carbon reduction-focused developments. Modular system configurations are expanding fastest among end users seeking redundancy and load-matching flexibility in multi-zone properties.
The Building Regulations Part L, the Boiler Upgrade Scheme administered by Ofgem, and BEIS carbon budgeting frameworks collectively reshape product eligibility and procurement criteria across the UK. Installers must navigate MCS certification requirements and tightening emissions standards that disqualify non-condensing units from new commercial builds. Stakeholders should monitor hydrogen blending trials and grid decarbonization timelines to align capital planning with evolving fuel infrastructure.
Market Dynamics
The UK Commercial Boiler Market is restructuring around regulatory enforcement velocity rather than pure replacement cycles. Part L Building Regulations and the Boiler Upgrade Scheme are compressing specification timelines and disqualifying legacy technologies from new capital flows.
Growth Catalysts
- Part L compliance mandates:Tightening efficiency thresholds in England and Wales are forcing non-condensing inventory out of new commercial builds. Installers report specification lock-in for 90%+ efficiency units.
- Hospitality sector infrastructure refresh:Hotel operators across London, Manchester and Birmingham are replacing aging heating systems ahead of carbon reporting deadlines. This vertical accounts for disproportionate replacement volume.
- Hydrogen-ready engineering:Boiler manufacturers embedding 20% hydrogen blend compatibility are capturing facilities managers planning heating transitions. This technical pathway de-risks capital commitments against fuel uncertainty.
Market Restraints
- Copper and steel input volatility:Heat exchanger fabrication costs swing with commodity markets. Manufacturers struggle to pass through material spikes in fixed-price public sector contracts.
- Installer certification scarcity:MCS accreditation requirements for low-carbon technologies are creating bottlenecks. Qualified technician availability constrains deployment velocity in Scotland and Northern England.
- Electrification substitution:Commercial heat pumps are displacing gas boilers in sub-100kW applications where grid capacity permits. This technology is capturing specification share in new build offices.
Strategic Opportunities
- Wales and Northern England underpenetration:Regulatory enforcement intensity lags London and the South East. Early compliance positioning in Cardiff, Leeds and Newcastle secures specification relationships ahead of tightening.
- Modular system configurations:Load-matching flexibility for multi-zone properties is expanding fastest among retail and healthcare estates. Redundancy requirements in critical facilities favor this architecture.
- Boiler Upgrade Scheme extension:Ofgem-administered grants for low-carbon heat are accelerating payback calculations. Facilities managers are advancing replacement timelines to capture subsidy windows.
Industry Challenges
- MCS certification timeline compression:Installer accreditation for heat pump and hybrid systems requires retraining investment. Contractors face capacity constraints while demand for qualified labor spikes.
- Legacy control integration complexity:New condensing and hydrogen-ready units must interface with existing BMS infrastructure. Commissioning delays erode margin on retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Commercial Boiler Market |
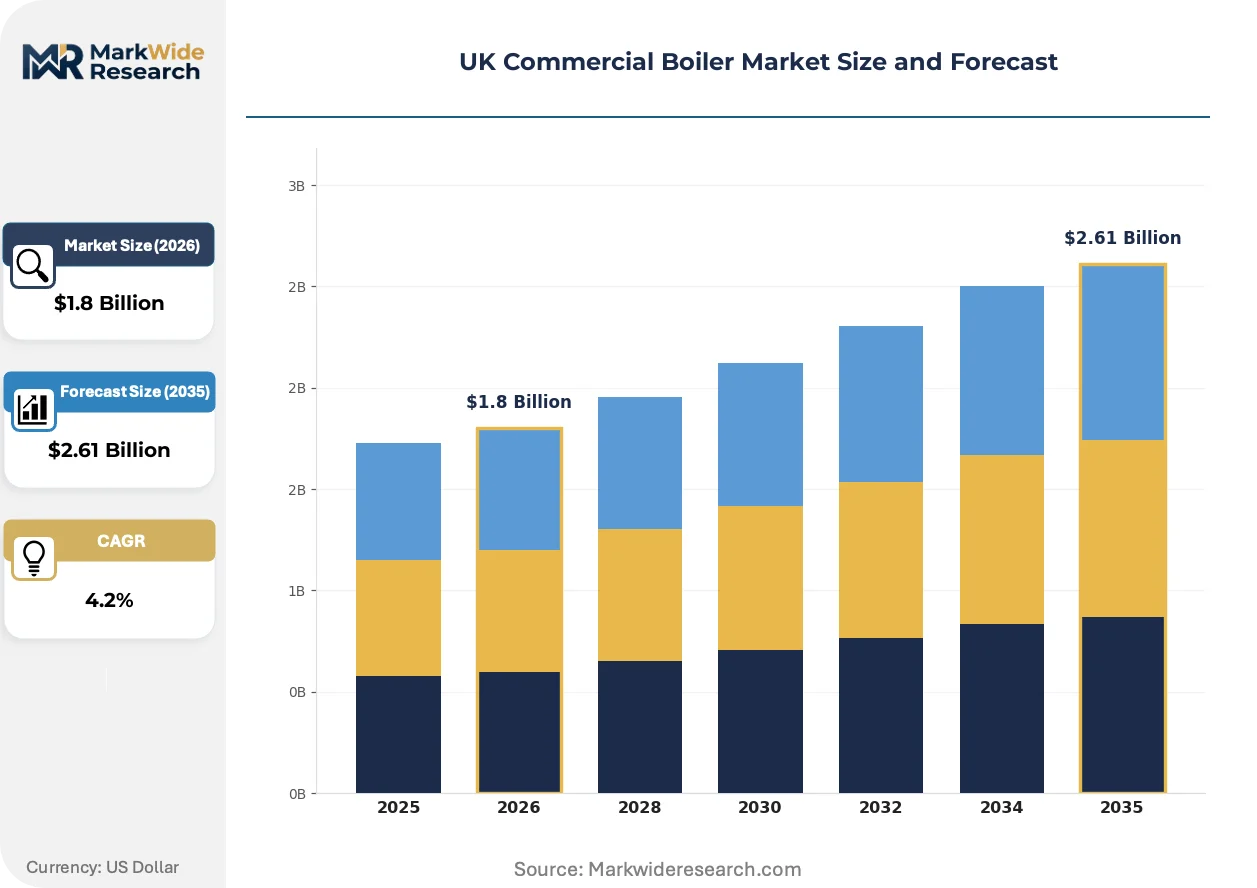
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condensing, Non-Condensing, Combination, System End User: Hospitality, Manufacturing, Education, Retail Fuel Type: Natural Gas, Oil, Biomass, Electric System Configuration: Modular, Single Unit, Dual Fuel, Cascade |
| Companies Covered | Fulton Boiler Company, Worcester Bosch, Bosch Thermotechnology, A.O. Smith Corporation, Viessmann, Cochran Limited, Vaillant Group, Babcock & Wilcox Enterprises, Cleaver-Brooks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Commercial Boiler Market Emerging Trajectories
Digitalization is penetrating combustion control and predictive maintenance functions. Three distinct vectors are compressing traditional equipment-service boundaries and rewiring buyer-supplier relationships across Britain.
Advanced burner management systems are virtualizing combustion tuning and fault diagnostics. Facilities managers in London healthcare estates are deploying these platforms to reduce unplanned downtime. Remote monitoring capability is virtualizing the traditional emergency callout model and compressing service contract structures toward performance guarantees.
BEIS carbon budgeting frameworks are tightening capital allocation criteria for public sector heating. Government estates must now justify gas boiler procurement against electrification alternatives. NHS trusts and universities are responding with hybrid system specifications that preserve hydrogen transition optionality.
Specification authority is migrating from installers to M&E consultants with energy modeling capability. Tier-one contractors are disintermediating traditional merchant distribution for direct manufacturer relationships. This pattern concentrates most visibly in South East commercial developments where Part L enforcement is strictest and consultant specification rates are highest.
UK Commercial Boiler Market Segmentation
Service contract structures and commissioning complexity vary sharply across boiler configurations in Britain. Specification choices cascade through maintenance obligations, spare parts logistics, and technician certification requirements that shape lifetime cost economics.
Product Type:
After-sales intensity escalates with combustion efficiency ratings and condensate management demands across these product architectures.
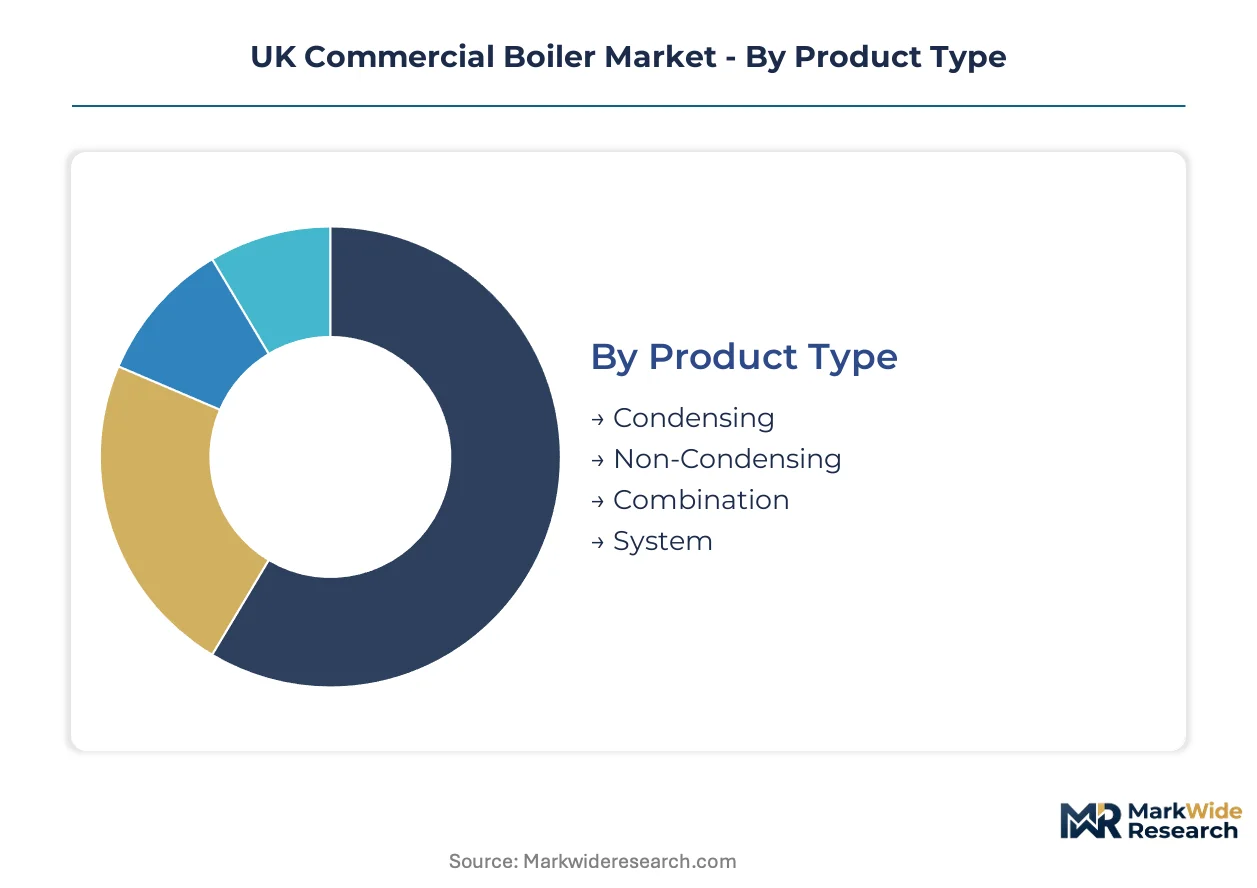
- Condensing:Heat recovery from flue gases via secondary heat exchangers extracts latent energy to push thermal efficiency past 90%. London hotel operators and NHS trusts specify these units to satisfy Part L compliance mandates in new builds and major refurbishments. Service intervals concentrate on condensate drainage integrity and acidic effluent neutralization systems.
- Non-Condensing:Conventional atmospheric combustion designs persist in legacy industrial estates where replacement cycles lag regulatory enforcement. These units carry lower capital cost but face exclusion from new commercial construction under tightening efficiency thresholds. Maintenance focuses on burner tuning and heat exchanger descaling rather than condensate handling.
- Combination:Integrated domestic hot water generation eliminates separate cylinder requirements in smaller commercial footprints. Retail units and boutique hotels across Manchester and Birmingham favor this space-efficient configuration. Service complexity rises from dual-function controls and diverter valve reliability.
- System:Heat-only designs paired with separate storage cylinders dominate larger commercial estates with variable hot water demand profiles. University campuses and manufacturing facilities specify these for load-matching flexibility. Commissioning demands extensive hydraulic balancing across multi-zone distribution networks.
Condensing holds the largest share; momentum sits with Combination configurations in space-constrained urban developments.
End User:
Capital allocation cycles and carbon reporting deadlines create divergent replacement velocities across these verticals.
- Hospitality:Hotel operators face guest comfort penalties from heating failures and rising energy disclosure requirements. London, Edinburgh, and Brighton properties are advancing replacement timelines to capture Boiler Upgrade Scheme subsidies before window closures. Seasonal occupancy fluctuations drive specification toward modular redundancy.
- Manufacturing:Process steam and space heating demands in food processing and textile production require high-duty-cycle reliability. Yorkshire and Midlands industrial clusters maintain non-condensing inventory longer due to continuous operation constraints. Maintenance contracts emphasize uptime guarantees and rapid emergency response.
- Education:School estates operate under constrained capital budgets with summer shutdown windows for installation. Academy trusts and local authorities are consolidating procurement through framework agreements. Specification authority is migrating toward M&E consultants with lifecycle cost modeling capability.
- Retail:Multi-site operators with standardized estate portfolios favor repeatable specifications across locations. Shopping centers and supermarket chains prioritize rapid installation to minimize trading disruption. Service contracts emphasize predictive maintenance to avoid peak-period failures.
Hospitality commands replacement volume intensity; Education is expanding most quickly as academy trusts consolidate heating upgrades.
Fuel Type:
Grid decarbonization timelines and infrastructure availability constrain fuel switching economics across British commercial estates.
- Natural Gas:Mains distribution coverage and established servicing networks sustain dominance in urban commercial centers. Hydrogen-ready burner engineering is preserving specification share against electrification pressure. Facilities managers in London and the South East are prioritizing 20% blend compatibility for transition optionality.
- Oil:Rural and off-grid commercial properties in Cornwall, Wales, and Scottish Highlands retain liquid fuel dependency. Storage tank regulations and carbon levies are compressing this segment toward biomass substitution. Service requirements concentrate on tank integrity testing and fuel quality management.
- Biomass:Wood pellet and chip combustion systems qualify for renewable heat incentives in carbon reduction-focused developments. Agricultural estates and rural hotels are deploying these where fuel supply chains are secure. MCS certification requirements for installers create deployment bottlenecks in Northern England.
- Electric:Resistance and electrode boiler technologies are displacing gas in sub-100kW applications where grid capacity permits. New build offices in Bristol and Cambridge are specifying electric as direct electrification accelerates. Operating cost exposure to wholesale electricity pricing constrains adoption in heat-intensive applications.
Natural Gas retains installed base dominance; Electric is climbing the fastest in grid-connected new construction.
System Configuration:
Redundancy architecture and load-matching sophistication determine capital intensity and operational flexibility trade-offs.
- Modular:Multiple smaller units operating in sequence match variable demand while preserving backup capacity. Healthcare estates and critical facilities across England specify these for N+1 redundancy requirements. Controls integration enables automatic staging and isolation of individual modules for maintenance.
- Single Unit:Centralized high-output designs minimize capital outlay in smaller commercial footprints with predictable demand profiles. Independent hotels and standalone retail units favor this simplicity. Failure risk concentrates in single points without backup capacity.
- Dual Fuel:Burner systems capable of switching between natural gas and oil provide supply security and tariff optimization. Industrial estates with interruptible gas contracts deploy these for operational continuity. Combustion tuning complexity raises commissioning and maintenance costs.
- Cascade:Linked multiple boilers operating as unified systems optimize efficiency across load ranges in large commercial complexes. University campuses and distribution centers specify these for operational flexibility. Hydraulic design and controls integration demand specialized engineering.
Modular captures specification momentum in critical facilities; Single Unit retains volume share in smaller commercial installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London and the South East command specification premiums 15-20% above Northern England replacement rates, reflecting enforcement intensity divergence across England's building control jurisdictions.
London and South East
Commercial property density and Part L enforcement intensity concentrate demand in the capital corridor. The Boiler Upgrade Scheme administered by Ofgem accelerates hospitality sector replacements ahead of subsidy window closures. Canary Wharf and Gatwick corridor hotels are advancing hydrogen-ready specifications to preserve fuel transition optionality.
Midlands
Manufacturing estates in Birmingham and Leicester sustain non-condensing inventory longer due to continuous operation constraints. BEIS carbon budgeting frameworks are tightening procurement criteria for public sector heating. University campuses across Coventry and Nottingham are consolidating framework agreements with M&E consultants.
North England
Leeds and Manchester commercial developments lag London enforcement timelines by 18-24 months. MCS certification scarcity for heat pump installers creates deployment bottlenecks in Yorkshire. Retail operators in Newcastle are standardizing modular configurations across multi-site portfolios.
Scotland
Edinburgh hospitality operators face guest comfort penalties from aging heating failures. Scottish Building Standards tightening efficiency thresholds are compressing specification timelines. Aberdeen industrial clusters maintain dual-fuel burners for supply security against interruptible gas contracts.
Wales
Cardiff commercial property stock shows regulatory underpenetration relative to English enforcement intensity. Rural off-grid properties in North Wales retain oil dependency with biomass substitution emerging. Swansea healthcare estates are specifying modular redundancy for critical facility uptime guarantees.
UK Commercial Boiler Market Vendor Landscape
Full-line manufacturers and application-specific specialists split the market across specification tiers. The vendor base concentrates around three strategic archetypes: nationwide branch-network operators, hydrogen-ready engineering specialists, and heavy industrial steam-system fabricators. Consolidation pressure is accelerating through framework agreement consolidation and direct manufacturer-M&E consultant relationships.
Within the nationwide branch-network tier, Worcester Bosch leverages its specification presence across education and healthcare projects. Viessmann occupies a position among hydrogen-ready engineering specialists targeting facilities managers planning heating transitions. Cochran Limited anchors the heavy industrial segment where steam output requirements exceed standard commercial ranges. These three exemplify how technical differentiation and distribution architecture determine competitive positioning across Britain's fragmented procurement landscape.
| Leading Market Players |
|---|
| Fulton Boiler Company |
| Worcester Bosch |
| Bosch Thermotechnology |
| A.O. Smith Corporation |
| Viessmann |
| Cochran Limited |
| Vaillant Group |
| Babcock & Wilcox Enterprises |
| Cleaver-Brooks |
| Others |
Supply Flow & Price Mechanics
West Midlands manufacturing clusters anchor heat exchanger fabrication capacity for the UK commercial boiler trade, with foundry output fluctuations transmitting directly into downstream pricing power for condensing unit assemblers. Copper and steel input volatility from global commodity exchanges compresses margin structures across fixed-price public sector contracts, forcing manufacturers to absorb material spikes or renegotiate framework terms.
Pricing Analysis
Configured-to-order pricing commands a 15-25% premium over standard catalog specifications for hydrogen-ready burner systems with BMS integration. Project-based contracting dominates public sector procurement through framework agreements, while spot purchasing persists in emergency replacement scenarios. Price differentiation hinges on MCS certification tier and after-sales service bundling, with accredited installers capturing margin premiums. Cost compression in economy-tier non-condensing units is intensifying as electrification substitutes erode specification share. Education sector buyers exhibit highest price sensitivity due to constrained capital budgets, whereas NHS trusts prioritize lifecycle cost modeling over upfront expenditure.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier-financing arrangements between major manufacturers and M&E contractors, with supply-chain finance facilities bridging working capital gaps for tier-two fabricators. Heat exchanger production draws from Germany, Italy, and domestic West Midlands foundries. Burner management systems and control electronics rest on semiconductor supply from Taiwan and South Korea. Single-source vulnerability concentrates in specialized hydrogen-ready burner engineering from German engineering houses. Distribution runs through merchant distribution networks in England, with direct manufacturer-to-consultant relationships gaining share in South East developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK commercial boiler trade is restructuring around technician certification scarcity, with MCS-accredited installer availability constraining deployment velocity for low-carbon technologies across Northern England and Scotland. Capital allocation now favors players controlling accredited labor pools or captive training pipelines.
For Market Incumbents: Pre-empt electrification substitution by embedding hydrogen-ready engineering across standard product lines rather than premium tiers alone. Secure backward integration into heat exchanger fabrication through foundry partnerships in the West Midlands to defend margin position against copper volatility. Channel control through direct M&E consultant relationships in London and South East developments protects specification rates against disintermediation. For New Entrants and Emerging Players: Pursue Wales and Northern England commercial developments where regulatory enforcement intensity lags London by 18-24 months, creating specification relationship windows ahead of Part L tightening. Target modular system configurations in retail and healthcare estates seeking redundancy without incumbent service contract lock-in. A go-to-market angle emphasizing rapid commissioning and legacy BMS integration capability addresses the control complexity pain point eroding retrofit margins. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hydrogen-ready engineering specialists with demonstrated 20% blend compatibility and controls integration platforms over pure-play condensing manufacturers. Long-term viability across the analysis window hinges on fuel transition optionality preservation and service contract recurring revenue depth. Acquisition targets should demonstrate captive MCS training capacity or exclusive distribution relationships with installer networks. The signal to watch is Boiler Upgrade Scheme extension announcements, which would accelerate replacement timelines and compress valuation multiples for installation-heavy assets.| Strategic Initiative | Industry Significance |
|---|---|
| MCS Certification Investment | Captures scarce installer capacity and qualifies products for Ofgem-administered subsidy programs. |
| Hydrogen-Ready Product Line Extension | Preserves specification share against electrification pressure in BEIS carbon budgeting frameworks. |
| Direct M&E Consultant Relationships | Bypasses merchant distribution concentration in South East Part L enforcement corridors. |
| Modular System Configuration Development | Addresses N+1 redundancy requirements in NHS trusts and critical healthcare facilities. |
| Foundry Partnership or Backward Integration | Defends margin position against copper and steel commodity volatility in heat exchanger supply. |
Methodological Framework
Operator-level perspectives from M&E contractors, facilities managers at NHS trusts and university estates, merchant distribution branch managers, and commissioning engineers anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation from BEIS policy documentation, Ofgem Boiler Upgrade Scheme administrative data, and Part L Building Regulations compliance filings. Customs records for heat exchanger and burner component imports, alongside SEC filings for listed parent entities of major manufacturers, provided trade flow and financial performance context. Bottom-up installation volume estimates from regional building control authorities triangulated against top-down manufacturer shipment disclosures.
Scenario-bracketing around hydrogen blending timelines and electrification substitution rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type architecture, fuel source transition pathways, system configuration redundancy levels, and end-user vertical capital allocation cycles. CAGRs derived from installed base turnover analysis and replacement velocity projections by building stock vintage. Industry-specific forecast inputs encompass Part L enforcement intensity differentials across English regions and MCS certification pipeline constraints.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by European manufacturers or accelerated Boiler Upgrade Scheme subsidy windows would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Cold Insulation Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
HVAC Blower and Fan Systems Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Roof Insulation Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Residential Hydronic Underfloor Heating Market