
 US Commercial HVAC Rooftop Units Market | 2026-2036
US Commercial HVAC Rooftop Units Market Size, Share, and Industry Trends Forecast 2026-2036
US Commercial HVAC Rooftop Units Market Insights
Modular bundled configurations is consolidating buyer preference across the US commercial rooftop unit sector. Carrier leverages its manufacturing scale to dominate large-format packaged installations for big-box retail. Trane Technologies anchors its position through deep channel control and specification-grade engineering for institutional clients. Daikin Industries competes on variable refrigerant flow integration within rooftop platforms.
US commercial HVAC rooftop units are self-contained heating, ventilation, and air conditioning systems mounted on building roofs, typically ranging from three to 150 tons cooling capacity with gas-electric, electric-electric, or heat pump configurations. These units serve the primary purpose of climate control for low-rise commercial structures where interior mechanical room space is limited or unavailable. Packaged units lead the product type landscape due to their installation simplicity and maintenance accessibility, while heat pumps represent the fastest-growing segment as electrification mandates intensify across jurisdictions. End-user demand from educational institutions generates stable replacement cycles, whereas office buildings concentrate margin pools through premium efficiency specifications and smart building integration requirements.
The Department of Energy enforces minimum energy conservation standards under 10 CFR Part 431 that directly dictate rooftop unit efficiency thresholds and phase-out timelines for non-compliant equipment. EPA's Energy Star certification program shapes procurement preferences among institutional buyers and corporate sustainability officers. ASHRAE Standard 90.1 provides the technical baseline that most state and local building codes adopt, creating a fragmented but upward-ratcheting compliance landscape. Stakeholders must monitor state-level stretch codes in California and New York that exceed federal minimums, as these jurisdictions often prefigure national standard revisions by several adoption cycles.
Market Dynamics
Electrification mandates under the Department of Energy's 10 CFR Part 431 are compressing replacement cycles and forcing manufacturers to redesign core refrigeration architectures ahead of 2028 compliance deadlines.
Growth Catalysts
- Texas commercial construction:Sun Belt building permits for retail and warehousing are generating concentrated demand for 20-50 ton packaged systems with gas-electric configurations.
- ASHRAE Standard 90.1 adoption:State-level stretch codes in California and New York are ratcheting minimum efficiency thresholds above federal baselines, accelerating equipment turnover in institutional portfolios.
- Heat pump technology:Cold-climate heat pump variants are expanding addressable market share in northern states previously dominated by gas heating.
Market Restraints
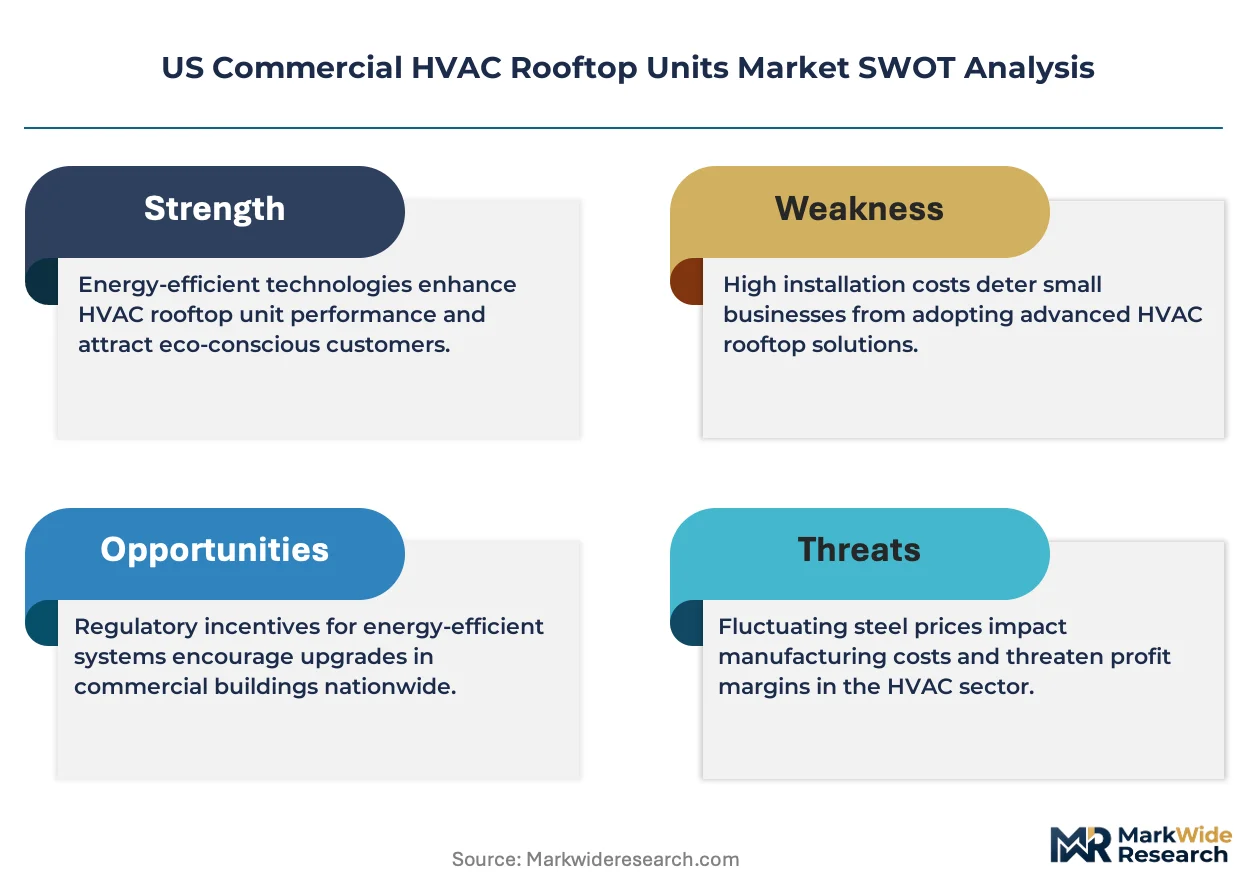
- Copper and aluminum volatility:Coil material costs represent 15-20% of bill-of-materials exposure, compressing margins when commodity markets spike.
- Compressor supply concentration:Domestic production of large-scroll compressors depends on a limited supplier base concentrated in Midwest manufacturing corridors.
- Refrigerant transition friction:EPA phasedown schedules for HFCs under AIM Act timelines are creating inventory management complexity for distributors holding mixed refrigerant stocks.
Strategic Opportunities
- Arizona data center cooling:Hyperscale facility construction in Phoenix and Tucson corridors is generating demand for high-tonnage rooftop units with economizer integration.
- Energy Star procurement preference:Corporate sustainability officers are mandating certified equipment in lease negotiations, creating specification lock-in advantages for qualified products.
- VRF-rooftop hybridization:Variable refrigerant flow integration with packaged platforms is opening premium positioning in multi-tenant office renovations.
Industry Challenges
- Controls engineering scarcity:Building automation system integration expertise is concentrated among a shrinking pool of field technicians, constraining smart-ready deployment velocity.
- Legacy refrigerant reclamation:Contractor compliance with EPA Section 608 technician certification requirements is creating bottlenecks during peak replacement seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Commercial HVAC Rooftop Units Market |
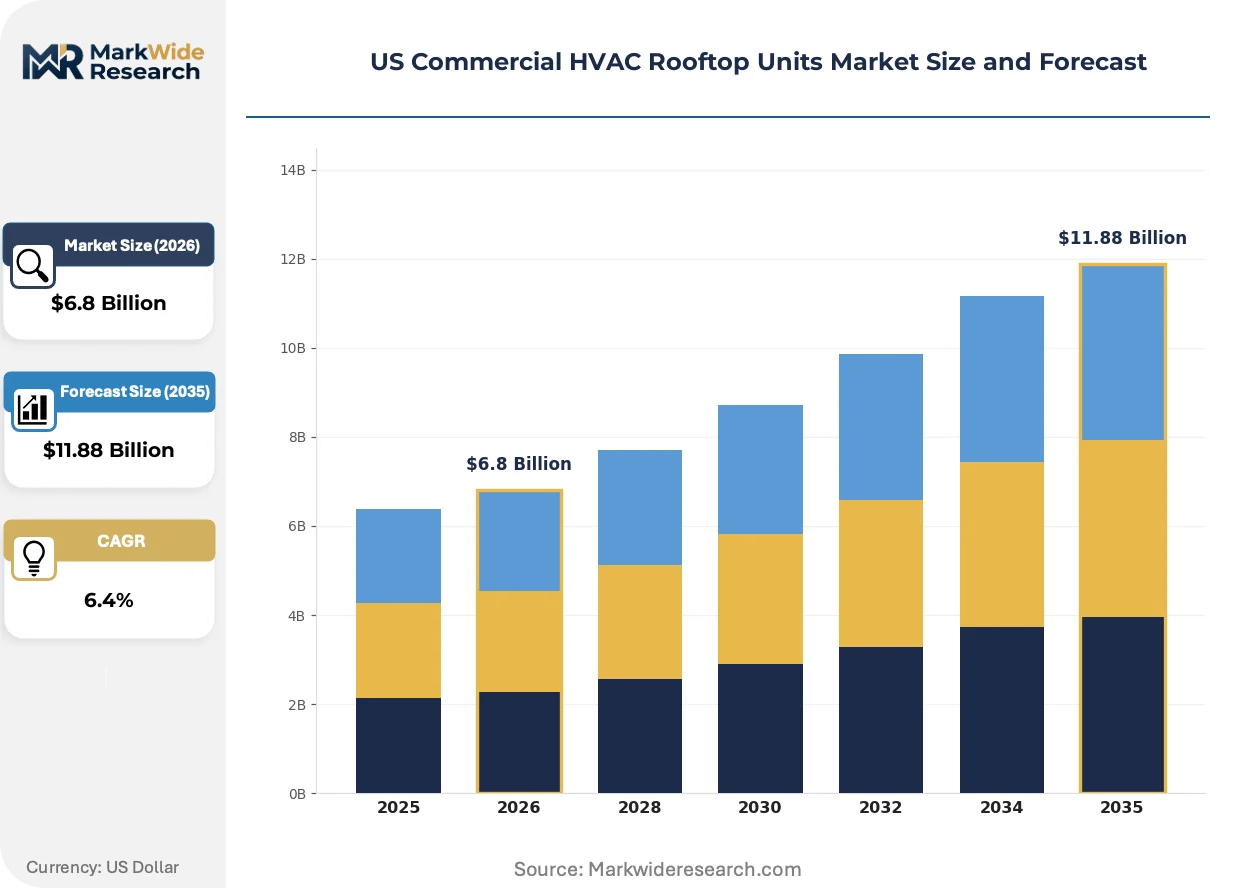
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packaged Units, Split Systems, Heat Pumps, Chillers End User: Office Buildings, Retail Spaces, Hospitality, Educational Institutions Installation Type: New Construction, Retrofit, Replacement, Modular Energy Efficiency Rating: SEER, EER, HSPF, Energy Star |
| Companies Covered | Lennox International, Rheem Manufacturing, Carrier, Bosch Thermotechnology, LG Electronics, Trane Technologies, Daikin Industries, AAON, Johnson Controls, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Commercial HVAC Rooftop Units Market Trends and Innovations
Digital twin simulation and predictive maintenance algorithms are rewriting how facility managers evaluate lifecycle costs, compressing the traditional 15-20 year replacement horizon for commercial rooftop assets.
Variable-speed compressor technology is converging with building automation protocols to enable real-time load matching. Big-box retail chains are retrofitting existing packaged units with variable frequency drives to avoid full system replacement. This convergence is compressing the performance gap between premium and standard equipment tiers, forcing manufacturers to differentiate on software integration rather than hardware efficiency alone.
EPA's phasedown of HFC production under AIM Act authority is accelerating refrigerant transition timelines. Equipment manufacturers must certify new low-GWP alternatives through AHRI performance testing protocols before 2027. California's Air Resources Board is enforcing stricter leak detection requirements than federal minimums, pushing distributors in Los Angeles and San Diego markets to invest in recovery equipment ahead of national adoption curves.
Third-party energy service companies are capturing maintenance contracts previously held by original equipment manufacturers. Institutional buyers in Florida and Texas are unbundling equipment purchase from service agreements, favoring independent contractors with multi-brand certification. This fragmentation is most visible in K-12 school districts, where procurement officers prioritize local service response times over factory-authorized dealer networks.
US Commercial HVAC Rooftop Units Market Segmentation
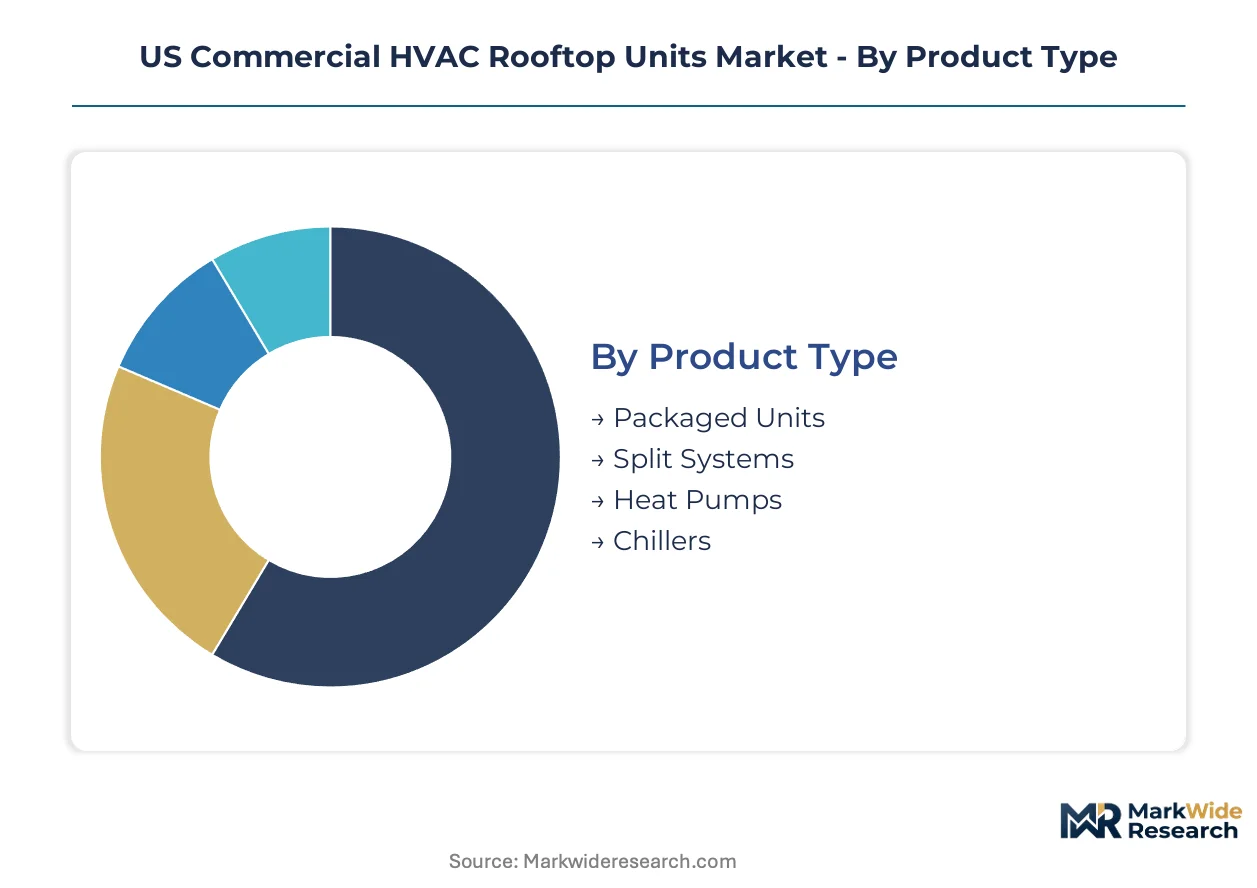
US commercial HVAC rooftop unit procurement patterns diverge sharply between volume-driven replacement cycles and premium specification projects. Understanding these segment boundaries reveals where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Packaged units command the volume tier while heat pumps capture the premium acceleration lane.
- Packaged Units:Self-contained systems integrating heating, cooling, and ventilation in single rooftop enclosures. Demand concentrates in Texas and Florida big-box retail where installation simplicity and maintenance accessibility override efficiency premiums. Gas-electric configurations dominate Sun Belt permits.
- Heat Pumps:Electric-only systems providing both heating and cooling through refrigeration cycle reversal. Cold-climate variants are expanding into northern states as electrification mandates compress replacement timelines; EER thresholds now match traditional gas heating in operational cost.
- Split Systems:Separated condenser and air handler configurations for buildings with interior mechanical room availability.
- Chillers:Centralized water-based cooling systems typically exceeding 150 tons capacity for large campus installations.
Today's leader: Packaged Units. Tomorrow's challenger: Heat Pumps.
End User:
Institutional buyers anchor replacement demand while retail chains drive new specification volumes.
- Educational Institutions:K-12 districts and universities generate predictable 15-20 year replacement cycles tied to bond financing schedules. Stable procurement volumes mask price sensitivity; Florida and Texas school boards prioritize local service response over factory-authorized networks.
- Retail Spaces:Big-box chains and strip mall operators concentrate demand for 20-50 ton gas-electric systems. Arizona and Nevada construction permits are accelerating warehouse and distribution center deployments with economizer integration requirements.
- Office Buildings:Multi-tenant commercial structures where smart building integration commands specification premiums.
- Hospitality:Hotels and resorts requiring zoned climate control with occupancy-based load management.
Educational Institutions lock in baseline volume. Retail Spaces dictate technology roadmaps through scale purchasing.
Installation Type:
New construction absorbs manufacturer capacity while retrofit creates aftermarket service attach rates.
- New Construction:Greenfield commercial projects in Sun Belt states specifying equipment during architectural design phase. Texas building permits for warehousing and logistics facilities are generating concentrated 20-50 ton demand with fast-track delivery requirements.
- Replacement:End-of-cycle equipment swaps in existing buildings where footprint constraints limit technology options. California's Title 24 stretch codes are accelerating turnover in institutional portfolios ahead of federal compliance deadlines.
- Retrofit:Partial system upgrades including variable frequency drive additions to existing packaged units.
- Modular:Staged capacity additions for expanding facilities or phased construction projects.
New Construction sets baseline specifications. Replacement generates recurring revenue through service contract attachment.
Energy Efficiency Rating:
Regulatory thresholds separate compliant baseline from certified premium tiers.
- Energy Star:EPA-certified equipment meeting efficiency thresholds 15% above federal minimums. Corporate sustainability officers are mandating certified units in lease negotiations, creating specification lock-in for qualified products in institutional procurement.
- EER:Energy Efficiency Ratio measuring cooling output per watt at peak conditions. DOE's 10 CFR Part 431 mandates are compressing replacement cycles as regional standards ratchet above federal baselines.
- SEER:Seasonal Energy Efficiency Ratio averaging performance across cooling season temperature variations.
- HSPF:Heating Seasonal Performance Factor for heat pump heating mode efficiency in cold-climate applications.
Energy Star dominates specification-grade procurement. EER compliance gates market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial HVAC rooftop units first achieved mass deployment in the post-war American Sun Belt, where flat-roof construction and cooling-dominated climates created ideal conditions for packaged systems. This historical foundation persists in contemporary demand patterns.
Texas
Warehouse and logistics construction in Dallas-Fort Worth and Houston generates concentrated demand for 20-50 ton gas-electric systems. The Texas Commission on Environmental Quality enforces regional air quality standards that accelerate equipment turnover in non-attainment zones. San Antonio and Austin school districts prioritize local service networks over factory-authorized dealers for replacement cycles.
Florida
Big-box retail expansion along I-4 and I-95 corridors sustains volume procurement of packaged units with corrosion-resistant coil coatings. The Florida Building Commission adopts ASHRAE 90.1 amendments with shortened compliance windows. Miami-Dade and Broward counties concentrate hospitality sector demand for zoned rooftop configurations with economizer integration.
California
Title 24 stretch codes in Los Angeles and San Diego markets mandate efficiency thresholds exceeding federal minimums by 15-20%. The California Air Resources Board enforces leak detection requirements stricter than EPA baselines. Silicon Valley data center construction drives specification of high-tonnage units with advanced controls integration.
Arizona
Phoenix and Tucson hyperscale facility development creates demand for rooftop units exceeding 75 tons with integrated economizers. The Arizona Corporation Commission oversees utility rebate programs that steer procurement toward heat pump configurations. Scottsdale and Tempe office renovations specify VRF-rooftop hybrid systems for multi-tenant climate control.
New York
Downstate commercial retrofits accelerate replacement cycles ahead of Local Law 97 carbon intensity deadlines. The New York State Energy Research and Development Authority administers incentive programs for cold-climate heat pump adoption. Long Island and Hudson Valley K-12 districts generate stable demand through bond-financed equipment refresh programs.
US Commercial HVAC Rooftop Units Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive distribution networks. Three manufacturer archetypes occupy distinct positions: full-line HVAC specialists with specification-grade engineering capabilities, diversified industrial groups leveraging cross-divisional technology transfer, and focused rooftop unit fabricators competing on regional service density. Consolidation pressure intensifies as refrigerant transition costs and controls integration requirements raise capital barriers. Strategic moves center on backward integration into compressor manufacturing and captive control system development.
Among the full-line specialists, Carrier and Trane Technologies exemplify scale-driven positioning through manufacturing footprint and channel control. Daikin Industries occupies a position representing variable refrigerant flow integration expertise applied to packaged platforms. These three anchors demonstrate how technology lineage shapes competitive archetype selection in a market where hardware differentiation compresses and software integration becomes the primary vector for premium positioning.
| Leading Market Players |
|---|
| Lennox International |
| Rheem Manufacturing |
| Carrier |
| Bosch Thermotechnology |
| LG Electronics |
| Trane Technologies |
| Daikin Industries |
| AAON |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Controls engineering talent concentration in the Midwest manufacturing corridor widens pricing-tier spreads, as BAS integration expertise commands premium labor rates that manufacturers pass through to specification-grade buyers while commodity packaged units compete on stripped-down configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with Energy Star certification and smart building integration capability separating tiers. Price differentiation rests on factory-authorized service bundling and regional delivery cost rather than hardware efficiency alone. Cost compression in the economy tier is intensifying because third-party energy service companies are unbundling maintenance from equipment purchase. Educational institutions exhibit highest price sensitivity, prioritizing local service response over factory premiums, while corporate sustainability officers in multi-tenant office buildings accept specification-grade pricing.
Supply Chain Analysis
Sheet metal fabrication and refrigeration assembly labor availability in Midwest manufacturing corridors anchors domestic production capacity. Large-scroll compressor supply draws from concentrated Midwest supplier bases, while copper and aluminum coil materials feed from commodity markets with 15-20% bill-of-materials exposure. Single-source vulnerability in compressor manufacturing creates supply chain risk during peak replacement seasons. Distribution runs through factory-authorized dealer networks competing with independent multi-brand contractors, particularly in K-12 institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Commercial HVAC Rooftop Units Market functions as a regulatory compounder, with DOE's 10 CFR Part 431 efficiency mandates and EPA refrigerant phasedowns forcing equipment turnover regardless of macroeconomic conditions.
For Market Incumbents: Deploy captive control system development to differentiate as hardware efficiency gaps compress between premium and standard tiers. Backward integration into compressor manufacturing defends margin position against supply concentration risks. Channel control investments in factory-authorized networks counter third-party energy service company fragmentation, particularly in Sun Belt states where independent contractors are capturing maintenance contracts. For New Entrants and Emerging Players: Capture cold-climate heat pump white space in northern states where electrification mandates are displacing gas heating dominance. Arizona data center cooling and VRF-rooftop hybridization for multi-tenant office renovations represent penetrable premium segments. A controls-first go-to-market angle bypasses manufacturing scale barriers incumbent on compressor supply access. For Investors and Strategic Acquirers: HVAC conglomerates with cross-divisional technology transfer capabilities are the most active acquirers in this space, seeking software integration assets and regional service density. Long-term viability over the coming decade hinges on refrigerant transition cost absorption and smart-ready deployment velocity. Monitor EPA Section 608 technician certification bottlenecks during peak replacement seasons as an inflection indicator for service attach rate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Reduces single-source dependency risks from Midwest supplier concentration. |
| Captive Control System Development | Enables software differentiation as hardware efficiency tiers converge under ASHRAE 90.1. |
| Energy Star Certification Investment | Locks in specification-grade procurement from corporate sustainability officers. |
| VRF-Rooftop Hybridization | Opens premium positioning in multi-tenant office renovations across Arizona and California. |
| Multi-Brand Service Certification | Captures maintenance contracts from K-12 districts prioritizing local response times. |
Research Methodology
Coverage spans Texas, Florida, California, Arizona, and New York, with primary inputs from each state driving regional demand pattern calibration. Primary interviews with facility maintenance directors, HVAC contractor operations managers, OEM procurement leads, and distributor inventory planners combined with secondary validation from DOE regulatory filings, EPA refrigerant phasedown schedules, ASHRAE standard revision documentation, and state-level building code adoption records. Bottom-up equipment shipment analysis and top-down construction permit triangulation anchored market sizing.
Rate-of-change decomposition across the analysis window separated replacement cycle velocity from new construction absorption capacity. Segmentation dimensions modeled include product type, end-user vertical, installation category, and energy efficiency tier, with regional regulatory stringency as an overlay variable. CAGRs were derived from equipment stock turnover assumptions tied to compliance deadline clustering and bond financing cycle alignment in institutional portfolios. Forecast inputs incorporated copper and aluminum commodity trajectory sensitivity and compressor supplier capacity utilization.
Refrigerant transition timeline acceleration, commodity price volatility spikes, and technician certification bottleneck severity are the dominant revision risks to modeled outcomes. Practitioners should monitor EPA enforcement intensity, Midwest manufacturing labor availability, and state-level stretch code adoption velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
Roof Vents Market
HVAC Systems
HVAC Control System Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Cold Insulation Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Global Building Thermal Insulation Material Market