
 Europe Boiler System Market | 2026-2036
Europe Boiler System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Boiler System Market Analysis
Multi-source component procurement is realigning supply strategies across the Europe Boiler System landscape as manufacturers diversify beyond single-country forging and casting supply. Vaillant Group leverages its German engineering heritage to dominate residential condensing installations across Central Europe. Viessmann anchors its position through captive heat pump-to-boiler hybrid development, while Bosch Industriekessel competes on industrial steam system integration.
A boiler system comprises a pressure vessel, burner assembly, heat exchanger, and control interface designed to generate steam or hot water for space heating, process heat, or power generation, typically operating at pressures from atmospheric to 200 bar depending on application. Gas boilers occupy the largest installed base across European residential and commercial stock, though biomass boilers represent the fastest-expanding product category as district heating operators phase out coal under national decarbonization mandates. Condensing technology captures dominant share in new residential builds, while non-condensing units persist in retrofit-constrained heritage structures where flue modifications prove cost-prohibitive.
The EU Green Deal, F-Gas Regulation, and Ecodesign Directive collectively mandate minimum efficiency thresholds and phase down high-GWP refrigerants in heat pump-boiler hybrids, reshaping product development roadmaps and certification requirements for market access. EMA and national building codes in Germany, France, and Italy enforce divergent installation standards that fragment compliance costs across borders. Stakeholders must monitor evolving carbon border adjustment mechanisms and national boiler ban timelines to calibrate manufacturing footprints and service network investments.
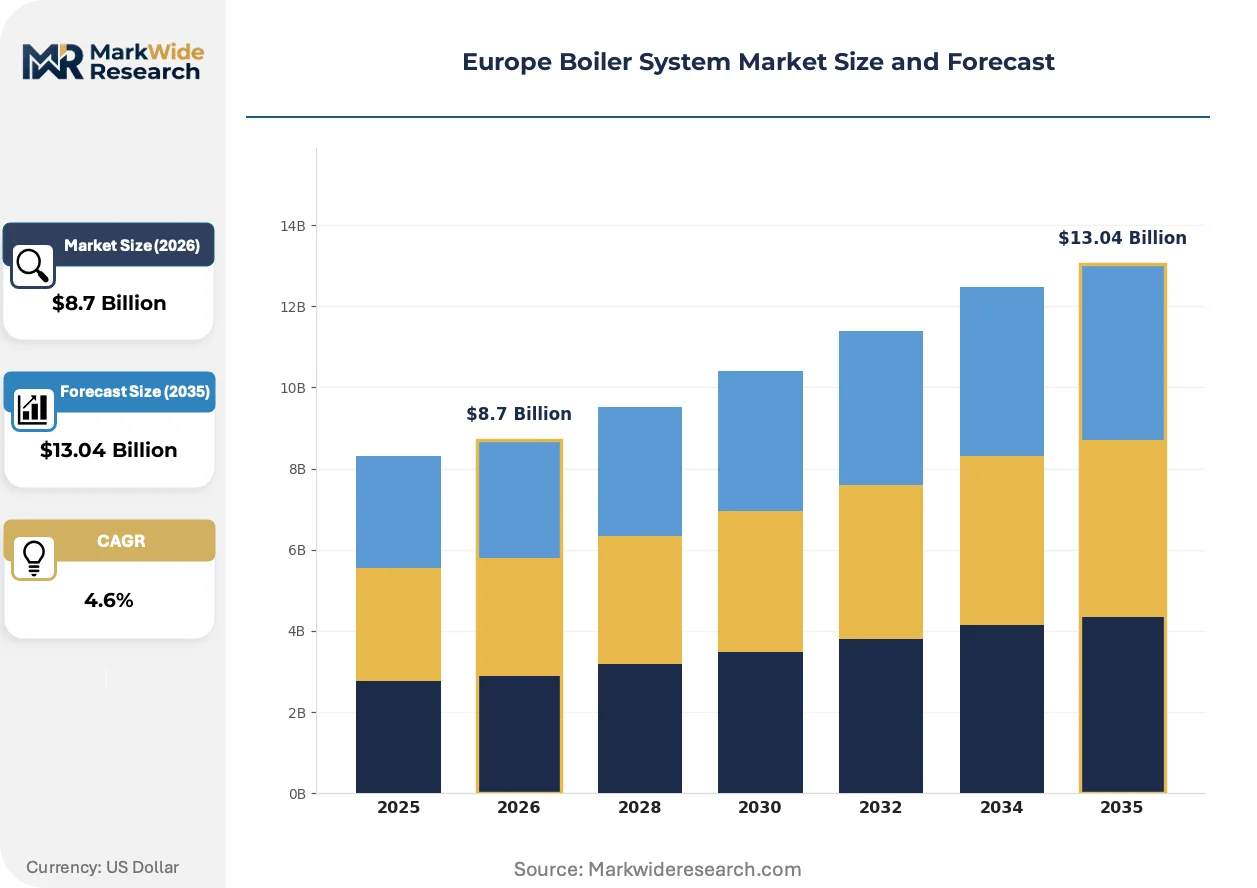
Market Dynamics
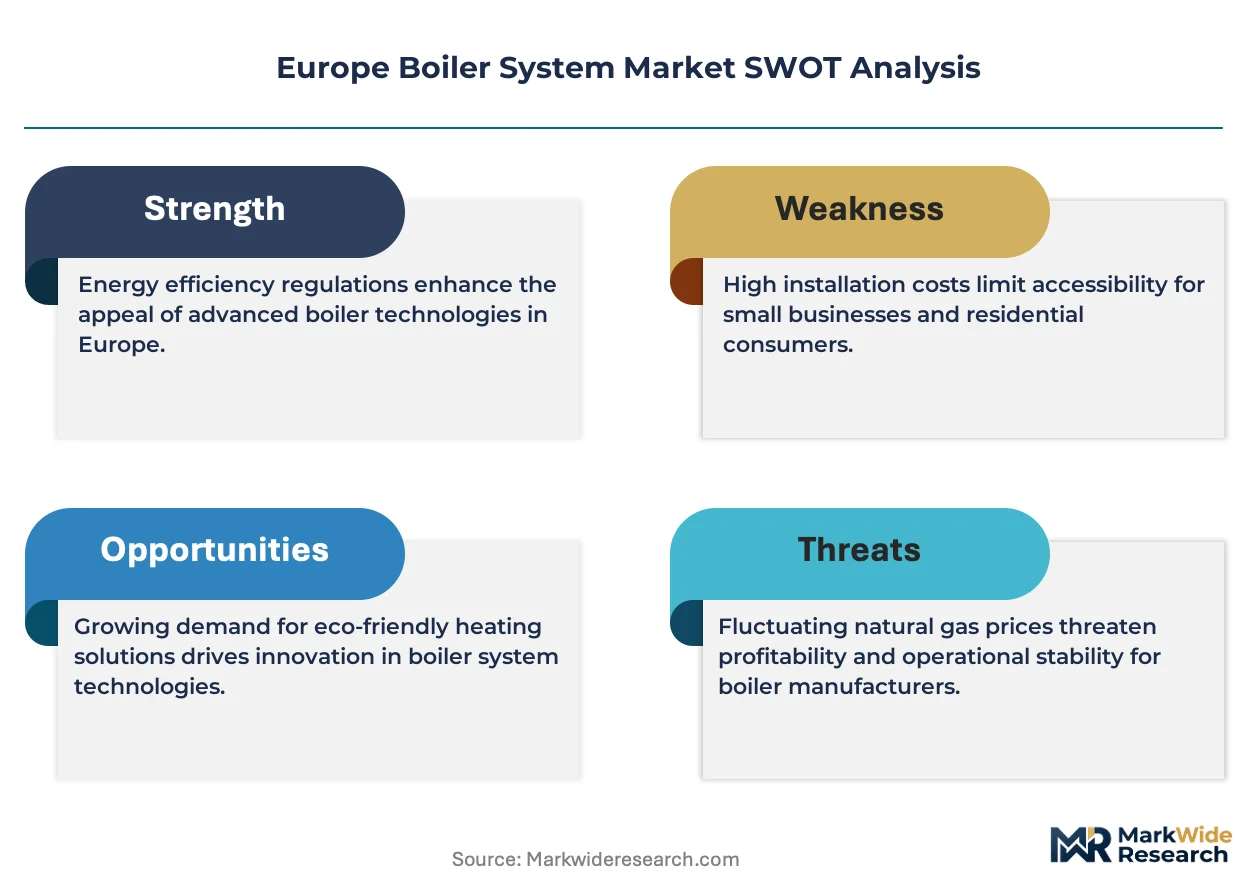
Condensing technology mandates under the EU Ecodesign Directive are forcing wholesale replacement cycles across Europe's installed boiler base, compressing payback periods and rewiring manufacturer R&D priorities toward efficiency thresholds rather than incremental improvements.
Growth Catalysts
- EU Green Deal decarbonization timelines:National coal phase-out commitments in Poland and Germany are accelerating district heating conversions to biomass and hydrogen-ready boilers.
- Manufacturing reshoring:Industrial boiler demand concentrates in German chemical corridors and Polish automotive clusters as supply chain localization intensifies.
- F-Gas Regulation phase-down:Heat pump-boiler hybrid systems face refrigerant constraints that favor natural gas and low-carbon hydrogen burner development.
Market Restraints
- Copper and steel input volatility:Heat exchanger fabrication costs fluctuate with commodity markets, squeezing margin structures for mid-tier manufacturers.
- Heritage building retrofit constraints:Non-condensing units persist where flue modifications violate conservation codes in Italian and French historic districts.
- Heat pump substitution threat:Air-source heat pumps capture new-build residential share in Nordic markets with milder winters and stronger subsidy frameworks.
Strategic Opportunities
- Hydrogen-ready boiler pre-positioning:Dutch and German gas grid blending trials create early-mover advantage for burner manufacturers certifying 20-100% H2 compatibility.
- Industrial process heat electrification gaps:High-temperature steam applications above 200°C remain underserved by heat pumps, preserving boiler relevance in pharmaceutical and food processing.
- Service contract digitization:Remote monitoring platforms enable predictive maintenance revenue streams independent of hardware replacement cycles.
Industry Challenges
- Certification timeline fragmentation:Divergent national implementation of Ecodesign standards across France, Italy, and Germany multiplies testing costs for pan-European product lines.
- Combustion engineering skill scarcity:Aging installer networks struggle to recruit technicians proficient in condensing flue gas analysis and low-NOx burner calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Boiler System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Boilers, Gas Boilers, Oil Boilers, Biomass Boilers Technology: Condensing, Non-Condensing, Combination, Instantaneous End User: Residential, Commercial, Industrial, Institutional Size: Small Capacity, Medium Capacity, Large Capacity, Custom Size |
| Companies Covered | Vaillant Group, Danstoker Boilers, Viessmann, Hoval, AC Boilers, Bosch Industriekessel, BDR Thermea, FERROLI, Babcock & Wilcox, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Boiler System Market Emerging Trajectories
Boiler system architecture is fragmenting into modular, software-defined platforms where hardware commoditization and digital service layers compete for margin capture across residential and industrial segments.
Condensing boiler technology is converging with heat pump systems in hybrid configurations that optimize seasonal coefficient of performance. German and Austrian utilities are deploying these systems in multi-family housing retrofits where full electrification exceeds grid capacity. The convergence is compressing standalone boiler replacement demand while expanding total addressable market for integrated thermal system providers.
The EU F-Gas Regulation is tightening refrigerant quotas for heat pump-boiler hybrids, redirecting manufacturer development toward natural refrigerants and combustion-only backup systems. Industrial boiler OEMs in Poland and Czechia are accelerating hydrogen burner certification to maintain market access. The regulation most severely impacts residential segments where R410A-dependent hybrids face 2027 phase-down cliffs.
After-sales service unbundling is disrupting traditional distribution channels as energy-as-a-service providers capture long-term maintenance contracts. Dutch housing associations and Swedish municipal landlords now procure heat provision rather than equipment ownership. This shift concentrates buyer power among large portfolio operators and marginalizes independent installer networks in the Benelux and Nordic markets.
Europe Boiler System Market Segmentation
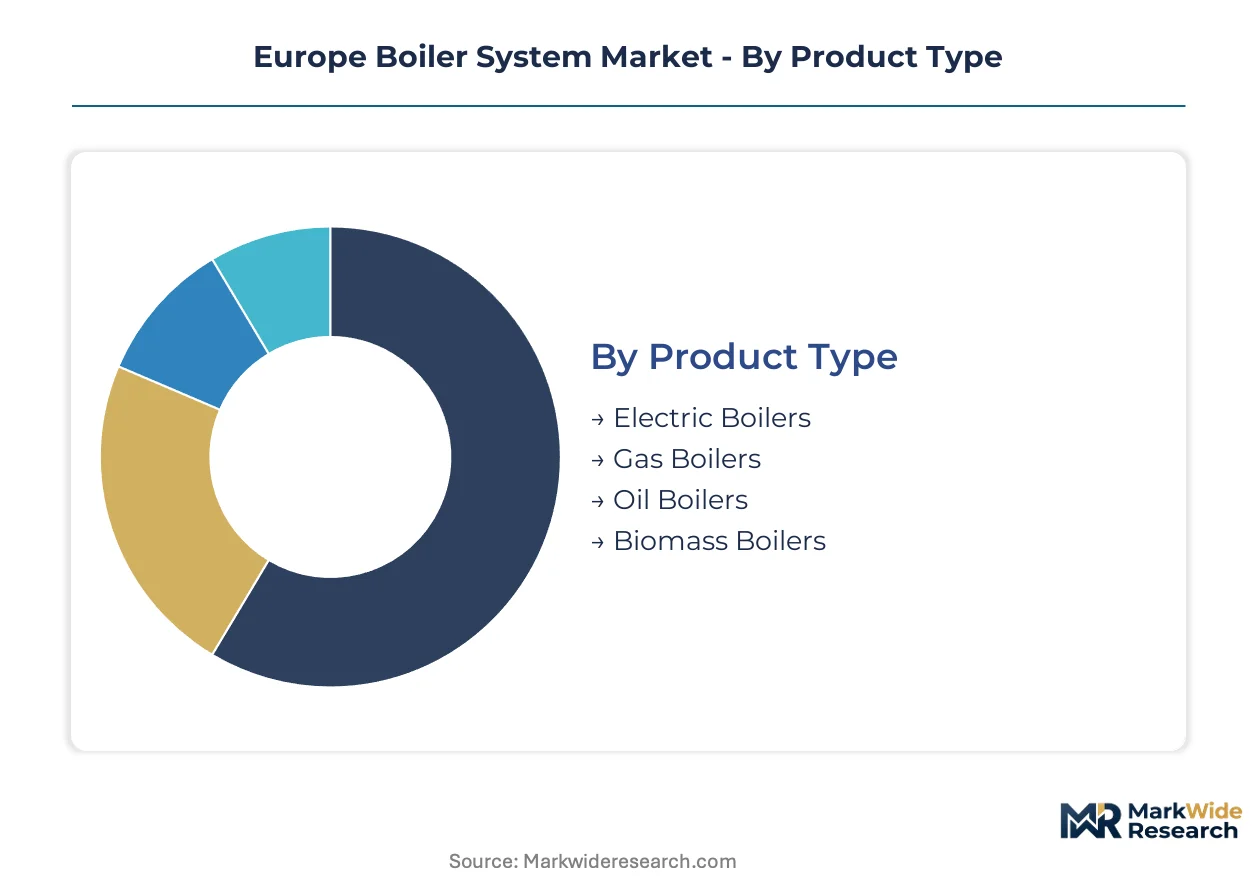
Boiler system segmentation in Europe reflects divergent decarbonization timelines across member states, with technology choices and capacity sizing directly tied to building stock age, grid infrastructure maturity, and national subsidy architectures. Manufacturers must configure product portfolios around these fault lines to avoid stranded inventory in markets with accelerating phase-out mandates.
Product Type:
Standardization dominates mass-market electric and gas categories, while biomass and oil segments retain customization for feedstock variability and heritage building constraints.
- Gas Boilers:These systems burn natural gas or hydrogen blends through sealed combustion chambers with modulating burners, achieving efficiency ratings above 90% in condensing configurations. Demand concentrates in German and Polish residential retrofits where grid density supports infrastructure, though Dutch hydrogen blending trials are accelerating H2-ready burner development. The installed base remains Europe's largest despite net-zero targets.
- Biomass Boilers:Combustion systems designed for wood pellets, chips, or agricultural residues, requiring automated fuel handling and emissions control systems. Nordic district heating operators in Sweden and Finland are deploying these at scale as coal phase-outs harden, with Danish utilities pioneering straw-fired industrial units. Feedstock supply security shapes procurement decisions.
- Electric Boilers:Resistance or electrode heating elements converting grid electricity to thermal energy without combustion emissions. French and Norwegian markets favor these where nuclear or hydroelectric surpluses depress power costs.
- Oil Boilers:Pressure-atomizing or vaporizing burners for distillate fuel oil, persisting in rural UK and Irish properties beyond gas grid reach. Regulatory pressure is compressing replacement demand to isolated off-grid applications.
Most installed capacity flows through Gas Boilers. Expansion is steepest in Biomass Boilers.
Technology:
Cost tier stratification separates premium condensing systems from economy non-condensing units, with combination and instantaneous technologies occupying mid-market positioning for space-constrained installations.
- Condensing:Heat exchangers engineered to recover latent heat from flue gas moisture, mandating corrosion-resistant stainless steel or aluminum-silicon alloys. German and Austrian building codes now require these for all new residential connections, with enforcement tightening across Benelux municipalities. The Ecodesign Directive's efficiency floors are eliminating non-compliant alternatives.
- Non-Condensing:Conventional atmospheric or fan-assisted burners exhausting higher-temperature flue gases, requiring only standard carbon steel construction. Italian and French historic districts with conservation codes block condensing retrofits where flue modifications alter building envelopes, preserving niche demand.
- Combination:Integrated domestic hot water heat exchangers eliminating separate cylinder requirements, dominating UK and Irish replacement markets where space constraints bite hardest.
- Instantaneous:On-demand water heating without storage volume, preferred in Mediterranean climates with lower space heating loads and higher summer hot water demand.
Condensing technology captures the majority of new-build specification. Instantaneous systems are climbing the fastest in southern European retrofit.
End User:
Application-driven segmentation separates residential volume plays from industrial margin opportunities, with commercial and institutional segments demanding customized service integration.
- Residential:Single-family and multi-family dwellings requiring 10-50 kW thermal output, typically wall-hung or floor-standing units with weather compensation controls. German housing associations and Swedish municipal landlords are aggregating procurement through heat-as-a-service contracts, shifting buyer power toward portfolio operators.
- Industrial:Process heat applications from 500 kW to 50 MW for steam generation, thermal oil systems, or direct firing. Polish automotive clusters and German chemical corridors are reshoring production, concentrating demand for high-pressure steam systems above 200°C where heat pumps fail.
- Commercial:Hotels, hospitals, and office buildings requiring 50-500 kW with redundancy provisions and part-load efficiency optimization. Service contract digitization is penetrating this segment fastest.
- Institutional:Schools, universities, and government facilities with extended payback tolerance and public procurement transparency requirements. EU Green Deal compliance deadlines are accelerating replacement cycles here.
Industrial end users command the highest per-unit margins. Residential volume sustains manufacturing scale.
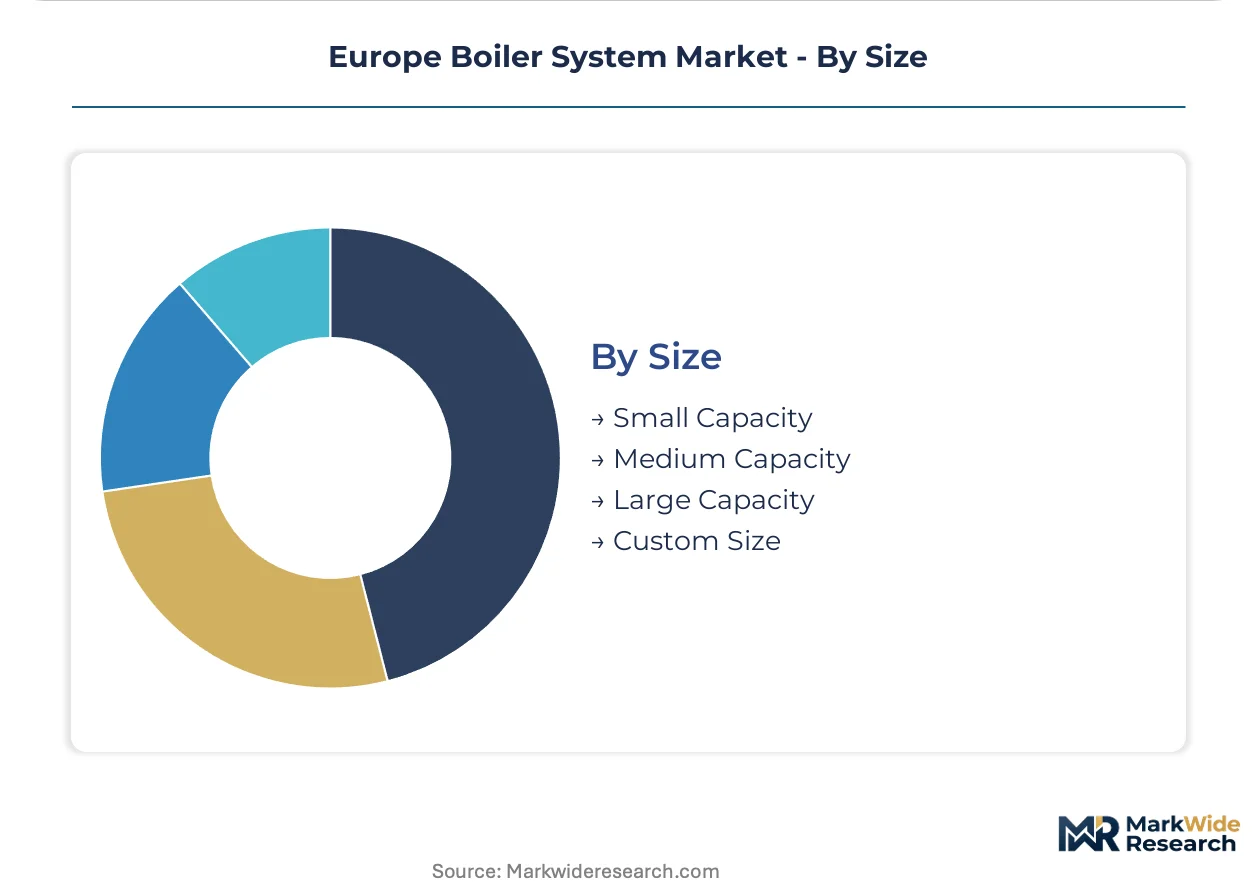
Size:
Volume concentration in small and medium capacity brackets contrasts with supply scarcity for large and custom engineered systems.
- Small Capacity:Units below 50 kW output serving single dwellings or small commercial premises, manufactured at scale with minimal configuration. Czech and Slovak OEMs dominate this bracket through cost-optimized production.
- Medium Capacity:50-500 kW systems for multi-family housing, small hotels, and light industrial process heat, requiring modular staging and cascade control. Danish and German engineering houses specialize here with building management system integration.
- Large Capacity:500 kW to 10 MW installations for district heating substations and industrial process lines, with extended lead times and site-specific engineering. Polish and Finnish manufacturers anchor this segment for biomass and solid fuel applications.
- Custom Size:Engineered-to-order systems beyond standard product ranges, typical for pharmaceutical sterilization, food processing, and power generation applications. Combustion engineering skill scarcity is elongating delivery timelines.
Medium Capacity systems move the highest unit volumes. Custom Size commands the steepest expansion trajectory in process heat electrification gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates Europe's largest boiler manufacturing footprint, with German engineering houses supplying condensing systems across Central and Eastern Europe. National decarbonization timelines are fragmenting demand patterns as some markets accelerate hydrogen-ready deployments while others extend fossil fuel boiler lifecycles.
Germany
Residential retrofit cycles and district heating network expansions in North Rhine-Westphalia drive condensing boiler replacement demand. The Federal Emissions Control Ordinance mandates minimum efficiency thresholds that eliminate non-condensing alternatives from new installations. Bosch Industriekessel anchors industrial steam system supply from its Stuttgart engineering base.
Poland
Coal phase-out commitments under the EU Green Deal are accelerating biomass boiler deployments across municipal heating networks. The National Fund for Environmental Protection channels subsidies toward hydrogen-ready burner retrofits in Silesian industrial clusters. Automotive reshoring in the Łódź corridor concentrates medium-capacity process heat demand.
France
Nuclear electricity surpluses in the Rhône-Alpes region favor electric boiler installations for residential and light commercial applications. The RE2020 environmental regulation tightens carbon budgets for new construction, compressing payback periods for high-efficiency gas systems. Historic district conservation codes in Paris and Lyon block condensing retrofits where flue modifications alter building envelopes.
Sweden
District heating operators in Stockholm and Gothenburg are deploying biomass boilers at scale as coal phase-outs harden under national climate legislation. The F-Gas Regulation refrigerant quotas redirect heat pump-boiler hybrid development toward natural refrigerants. Municipal landlords aggregate procurement through heat-as-a-service contracts that shift buyer power toward portfolio operators.
Netherlands
Hydrogen blending trials in the Groningen gas grid create early-mover certification requirements for 20-100% H2-ready burners. The Climate Agreement mandates 1.5 million homes off natural gas by 2030, though industrial process heat applications preserve boiler relevance in Rotterdam chemical corridors. Dutch housing associations now procure thermal energy provision rather than equipment ownership.
Europe Boiler System Market Vendor Landscape
Global majors compete with regional champions across technology specialization and service integration dimensions. The vendor base stratifies into three tiers: premium engineering houses with captive R&D, mid-market fabricators competing on cost-optimized production, and industrial specialists targeting process heat above 200°C. Consolidation pressure concentrates among mid-tier players as efficiency mandates commoditize standard gas boiler architectures. Two dominant competitive moves are reshaping positioning: hydrogen-ready burner certification races and predictive maintenance platform unbundling.
Among German-engineered residential specialists, Vaillant Group and Viessmann exemplify the premium-tier archetype through heritage brand positioning and hybrid system development. Bosch Industriekessel occupies the industrial integration segment. Danish and Austrian engineering houses anchor medium-capacity district heating supply. Polish and Czech OEMs concentrate cost-optimized small-capacity fabrication for price-sensitive Central European retrofits.
| Leading Market Players |
|---|
| Vaillant Group |
| Danstoker Boilers |
| Viessmann |
| Hoval |
| AC Boilers |
| Bosch Industriekessel |
| BDR Thermea |
| FERROLI |
| Babcock & Wilcox |
| Others |
Supply Flow & Price Mechanics
The EU Ecodesign Directive's efficiency mandates gate qualified supply to certified heat exchanger fabricators and premium-tier pricing access to German and Austrian engineering houses with captive stainless steel forging capabilities. Mid-tier Polish and Czech OEMs face margin compression as copper and aluminum-silicon alloy volatility squeezes cost-optimized production, while Dutch hydrogen-ready burner certification creates tiered pricing separation between H2-compatible and legacy natural gas architectures.
Pricing Analysis
Input-cost pass-through from copper and steel commodity markets compresses margins for mid-tier manufacturers unable to forward-hedge material positions. Three-tier pricing structure across premium condensing, standard non-condensing, and economy electric resistance systems differentiates by certification grade and after-sales service bundling. Pricing pressure stems from heat pump substitution in Nordic residential new-builds with stronger subsidy frameworks. Residential retrofit buyers exhibit highest price sensitivity, while industrial process heat purchasers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German forging houses supplying corrosion-resistant heat exchanger alloys to premium boiler OEMs. Manufacturing concentrates in Germany, Poland, and the Czech Republic, with raw material dependencies spanning Ukrainian steel semi-finished products, Chilean copper cathodes, and Chinese rare earth elements for burner control electronics. Supply chain risk centers on carbon border adjustment mechanism exposure for imported steel inputs. Distribution runs through captive installer networks in Central Europe and energy-as-a-service aggregators in Benelux and Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on condensing technology premiums and service contract digitization that decouples revenue from hardware replacement cycles. Cost-down drivers from modular platform standardization and predictive maintenance software deployment reinforce this trajectory.
For Market Incumbents: Cement hydrogen-ready burner certification leadership through early participation in Dutch and German gas grid blending trials. Deepen backward integration into stainless steel heat exchanger forging to defend against commodity volatility and Polish automotive reshoring demand concentration. Prioritize predictive maintenance platform development to capture recurring revenue independent of replacement cycles threatened by heat pump substitution. For New Entrants and Emerging Players: Enter via industrial process heat electrification gaps above 200°C where heat pumps fail, targeting pharmaceutical sterilization and food processing applications in German chemical corridors. Focus white-space capture on custom-engineered systems where combustion engineering skill scarcity elongates incumbent delivery timelines. Pursue heat-as-a-service contract structures with Swedish municipal landlords and Dutch housing associations to bypass established installer channel control. For Investors and Strategic Acquirers: Roll-up economics work for regional service platform consolidation because fragmented independent installer networks in Benelux and Mediterranean markets lack digitized maintenance capabilities. Long-term viability favors vertical integration into heat pump-boiler hybrid development and hydrogen burner technology. Monitor F-Gas Regulation refrigerant quota implementation as inflection signal for natural refrigerant system valuations versus R410A-dependent hybrid obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Burner Certification | Dutch and German grid blending trials create first-mover qualification barriers for competitors. |
| Predictive Maintenance Platform Deployment | Remote monitoring captures recurring revenue from Swedish municipal landlord portfolios. |
| Backward Integration into Heat Exchanger Forging | German stainless steel captive supply defends margin against copper volatility. |
| Biomass Boiler Capacity Expansion | Polish coal phase-out subsidies accelerate municipal district heating conversions. |
| Heat-as-a-Service Contract Structuring | Dutch housing association procurement shifts buyer power toward portfolio operators. |
Methodological Framework
Multiple input streams — plant engineer interviews, OEM procurement team discussions, district heating operator consultations, and aftermarket service head surveys — were reconciled against Ecodesign Directive implementation filings, EU F-Gas Regulation quota tracking, and national building code enforcement databases. Secondary validation drew from customs trade data for steel and copper inputs, SEC disclosures from listed industrial equipment manufacturers, and Benelux energy-as-a-service contract registries. Bottom-up unit shipment modeling and top-down heating system expenditure estimates were triangulated to anchor volume and value projections.
Data-stream reconciliation across product type, technology tier, end-use application, capacity sizing, and national regulatory cluster dimensions structured the analytical framework. CAGRs were derived from replacement cycle compression under efficiency mandates and hydrogen infrastructure deployment assumptions. Forecast inputs incorporated Ecodesign Directive enforcement timelines, F-Gas Regulation phase-down cliffs for refrigerant-dependent hybrids, and national coal phase-out commitments reshaping biomass boiler demand.
Inputs from OEM engineering directors and municipal heating procurement officers were available through the study window; gaps in real-time hydrogen blending trial performance data and carbon border adjustment mechanism final rules introduce uncertainty bands around hydrogen-ready system adoption curves. Forecasts reflect documented assumptions about regulatory enforcement consistency and commodity price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Roof Vents Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
HVAC Control System Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
Cold Insulation Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Water Saving Shower Heads Market