
 North America and GCC HVAC Insulation Market | 2026-2036
North America and GCC HVAC Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
North America and GCC HVAC Insulation Market Analytics
Texas is tilting toward expanded fiberglass manufacturing to serve Gulf Coast petrochemical and data center cooling projects. Owens Corning leverages its mineral wool and fiberglass portfolio to anchor utility-scale HVAC specifications across the southern United States. Johns Manville competes through specialized duct liner systems that dominate commercial retrofit channels in Chicago and Toronto.
HVAC insulation comprises thermal and acoustic barrier materials engineered to reduce heat transfer and control condensation in heating, ventilation, and air conditioning systems, typically specified by R-value, thermal conductivity, and fire-smoke-toxicity ratings to meet building energy codes and occupant safety requirements. Fiberglass retains the largest installed base across North American commercial buildings due to cost-performance balance and decades of contractor familiarity. Foam segments gain fastest in GCC residential towers where space-constrained duct designs and extreme ambient temperatures push specification toward higher-performing closed-cell polyurethane and phenolic boards.
ASHRAE 90.1 and the Saudi Building Code shape product compliance pathways by mandating minimum insulation thicknesses for chilled water piping and air distribution systems. The EPA's Significant New Alternatives Policy and UAE's Estidama Pearl Rating System further filter material selection toward low-global-warming-potential blowing agents and recycled content. Stakeholders must monitor code harmonization between ASHRAE updates and Gulf standardization initiatives to anticipate specification divergence or convergence across their North American and GCC portfolios.
Market Dynamics
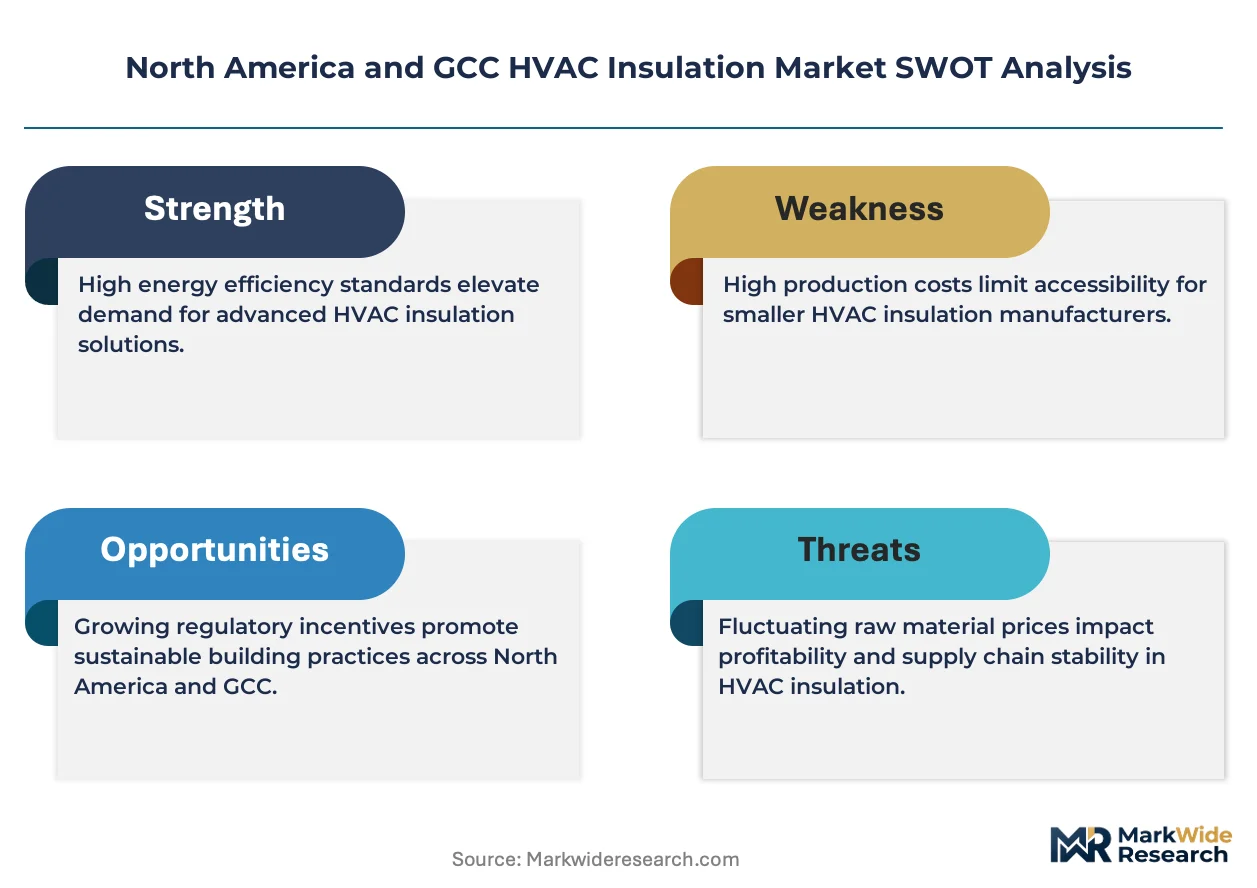
Energy code stringency across the United States and Gulf Cooperation Council member states is compressing specification cycles and forcing material upgrades in commercial building retrofits and new megaproject construction.
Growth Catalysts
- ASHRAE 90.1 thermal performance mandates:Minimum insulation thickness requirements for chilled water piping and air distribution systems are accelerating replacement demand in aging US commercial building stock.
- Saudi Building Code enforcement:Tightened thermal performance standards in Riyadh and Jeddah commercial towers are driving specification of higher-R-value materials in new construction.
- Data center cooling loads:Hyperscale facility construction in Texas and the UAE is creating concentrated demand for high-performance duct insulation with enhanced fire-smoke-toxicity ratings.
Market Restraints
- Blowing agent cost volatility:Low-global-warming-potential hydrofluoroolefin prices fluctuate with EPA Significant New Alternatives Policy quota adjustments, compressing margins on closed-cell polyurethane board production.
- Fiberglass supply concentration:US Gulf Coast manufacturing clusters face hurricane-related production disruption risks that propagate through contractor specification channels.
- Material thickness constraints:Space-constrained plenum designs in GCC residential towers limit retrofit options where existing infrastructure cannot accommodate code-mandated insulation depths.
Strategic Opportunities
- UAE Estidama Pearl Rating System:Recycled-content mandates in Abu Dhabi and Dubai are creating specification premiums for mineral wool products with post-consumer glass feedstock.
- Acoustic-thermal convergence:Open-plan office retrofits in Toronto and Chicago are driving bundled specification of duct liner systems that address both thermal and noise control requirements.
- Prefabricated duct modules:Factory-insulated spiral duct systems are penetrating Saudi hospital and airport projects where field installation labor shortages constrain traditional build-in-place methods.
Industry Challenges
- Certification timeline compression:Fire-smoke-toxicity testing backlog at UL and Intertek facilities is delaying product qualification for GCC export orders.
- Installer skill fragmentation:Phenolic and polyisocyanurate board installation requires specialized handling protocols that exceed the training depth available in regional contractor workforces across Texas and the Emirates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and GCC HVAC Insulation Market |
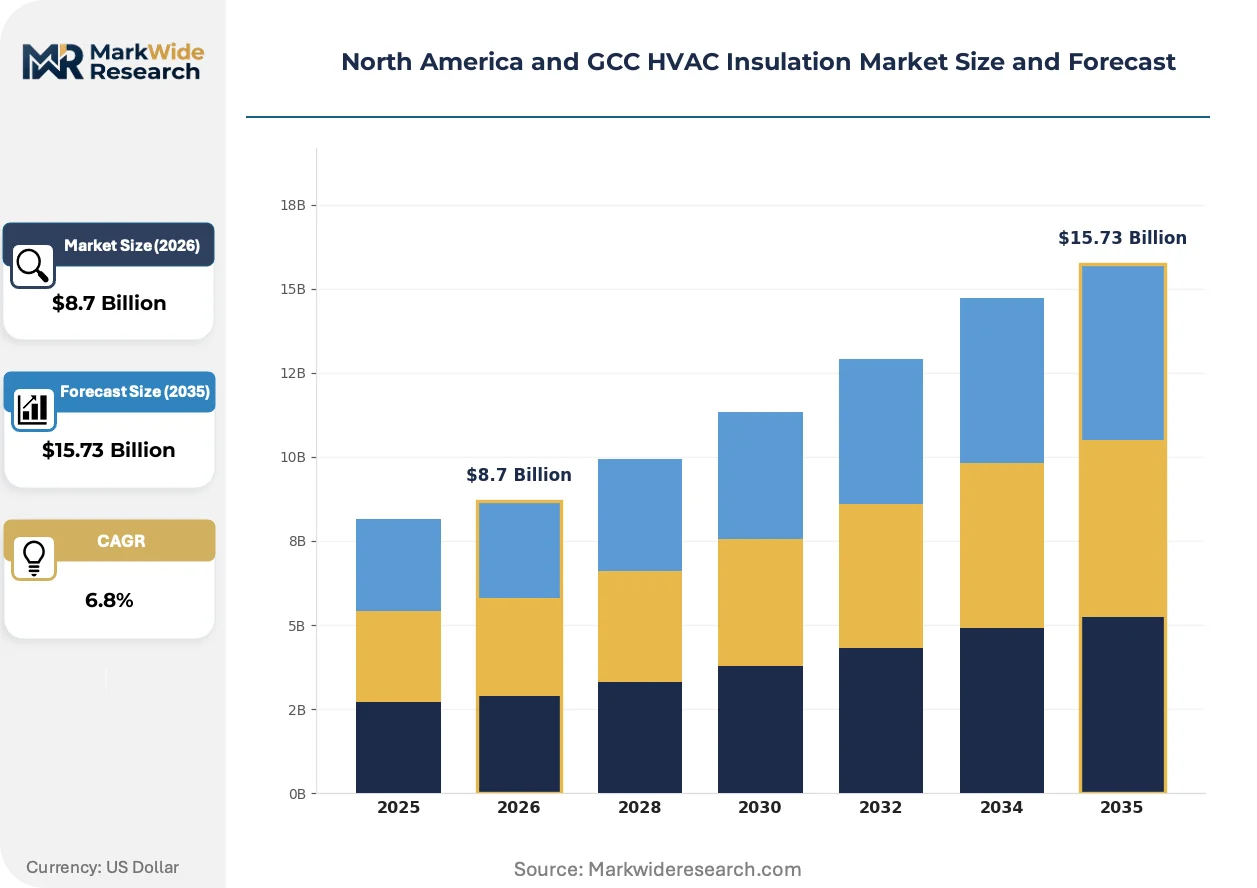
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Foam, Rubber, Mineral Wool Application: Residential, Commercial, Industrial, Institutional Installation: New Construction, Retrofit, DIY, Professional End User: Builders, Contractors, Engineers, Facility Managers |
| Companies Covered | Owens Corning, Johns Manville, Armacell International, Rockwool International, Knauf Insulation, Kingspan Group, Saint-Gobain, Arabian Fiberglass Insulation, L-ISOLANTE K-FLEX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and GCC HVAC Insulation Market Evolving Landscape
Digital specification tools and advanced material formulations are compressing the gap between code minimums and high-performance design intent across North American and Gulf commercial construction.
Aerogel-infused blanket insulation is virtualizing traditional fiberglass dominance in premium commercial applications where space constraints and thermal performance requirements collide. High-net-worth residential towers in Dubai and data center projects in Dallas-Fort Worth are specifying these materials despite cost premiums of three to five times conventional alternatives. The technology is virtualizing the trade-off between insulation thickness and R-value that has governed HVAC specification for decades.
The EPA's Significant New Alternatives Policy continues to restrict high-global-warming-potential hydrofluorocarbon blowing agents in closed-cell foam production. US manufacturers have reformulated polyurethane and polyisocyanurate product lines to comply with phasedown schedules, while GCC importers face compliance verification burdens at ports of entry. Saudi Arabia's SFDA and UAE's MOHAP are aligning national chemical registries with these restrictions, creating harmonized but stringent material qualification pathways.
Building information modeling integration is altering how mechanical contractors procure insulation materials and coordinate installation sequencing. Large general contractors in Houston and Riyadh now require digital material submittals that integrate thermal performance data directly into clash detection workflows. This specification behavior concentrates purchasing authority with engineering-procurement-construction firms and displaces traditional distributor relationships in projects above fifty million dollars.
North America and GCC HVAC Insulation Market Segmentation
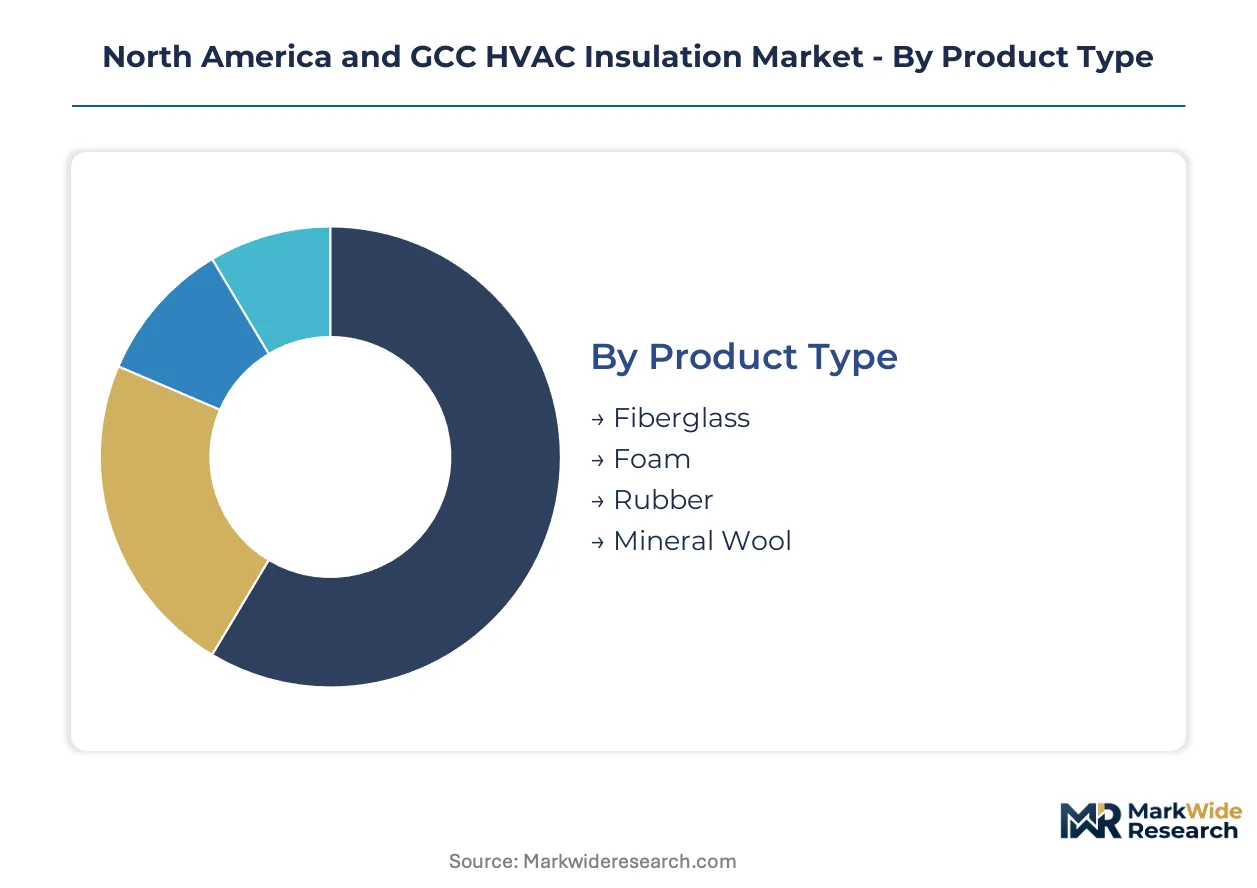
HVAC insulation specification varies sharply across building types and installation contexts. Product selection hinges on thermal performance targets, fire safety ratings, and labor availability at the project site.
Product Type:
The use-case spectrum spans cost-driven commercial retrofits to space-constrained premium installations where thermal efficiency per inch governs selection.
- Fiberglass:Composed of fine glass fibers bound with phenolic resin, this material delivers R-values between 3.0 and 4.0 per inch. Demand concentrates in Texas commercial retrofits where contractor familiarity and material cost drive specification. ASHRAE 90.1 compliance is achievable with standard thicknesses in plenum spaces with adequate clearance.
- Foam:Closed-cell polyurethane and phenolic boards achieve R-values of 6.0 to 8.0 per inch with low-global-warming-potential hydrofluoroolefin blowing agents. UAE residential towers specify these materials where duct chase dimensions cannot accommodate thicker fiberglass layers. Extreme ambient temperatures in Dubai and Riyadh amplify the value of thermal performance per unit thickness.
- Rubber:Elastomeric foam sheets provide flexible insulation for irregular duct geometries and vibration-dampening applications. Saudi hospital projects specify rubber for mechanical room piping where condensation control is critical.
- Mineral Wool:Stone or slag wool fibers deliver fire resistance ratings up to 1,200°C without toxic off-gassing. Abu Dhabi Estidama Pearl-rated projects favor mineral wool with post-consumer recycled content for green building certification points.
The dominant share belongs to fiberglass, while foam is closing the gap fastest.
Application:
Building type determines fire-smoke-toxicity requirements, acoustic performance needs, and thermal load characteristics.
- Commercial:Office towers and retail centers drive the largest absolute volume. Chicago and Toronto retrofits bundle thermal and acoustic specifications for open-plan environments. ASHRAE 90.1 mandates accelerate replacement cycles in buildings constructed before 2010.
- Residential:Single-family and multifamily construction in GCC states favors foam products where mechanical shafts are dimensionally constrained. Saudi Arabia's residential building code is tightening thermal envelope requirements for new tower construction.
- Industrial:Petrochemical facilities and manufacturing plants specify high-temperature mineral wool for process HVAC systems. Texas Gulf Coast expansions create concentrated demand for corrosion-resistant insulation systems.
- Institutional:Hospitals, schools, and government buildings require enhanced fire ratings and low-smoke emission materials. Saudi airport and healthcare megaprojects are specifying factory-insulated duct modules to compress installation schedules.
Commercial applications anchor current volume, with institutional projects expanding most quickly due to GCC megaproject pipelines.
Installation:
Project delivery method shapes material form factor, labor skill requirements, and procurement channel selection.
- New Construction:Greenfield projects allow integrated design of mechanical systems and insulation specifications. Houston and Riyadh engineering-procurement-construction firms now require digital material submittals compatible with building information modeling workflows.
- Retrofit:Existing building upgrades face space constraints and access limitations. US commercial stock built before ASHRAE 90.1 adoption is driving replacement demand as energy codes tighten enforcement.
- DIY:Homeowner-installed insulation is limited to residential applications with simple duct geometries. Big-box retail channels in the United States stock fiberglass batts for this segment.
- Professional:Certified mechanical contractors handle code-compliant installation with documented fire-smoke-toxicity ratings. GCC markets face installer skill gaps for phenolic and polyisocyanurate board protocols.
New construction commands the largest project scale, while retrofit activity is gaining share fastest as energy code enforcement intensifies.
End User:
Purchasing authority varies across the construction value chain, concentrating with entities that control specification documents.
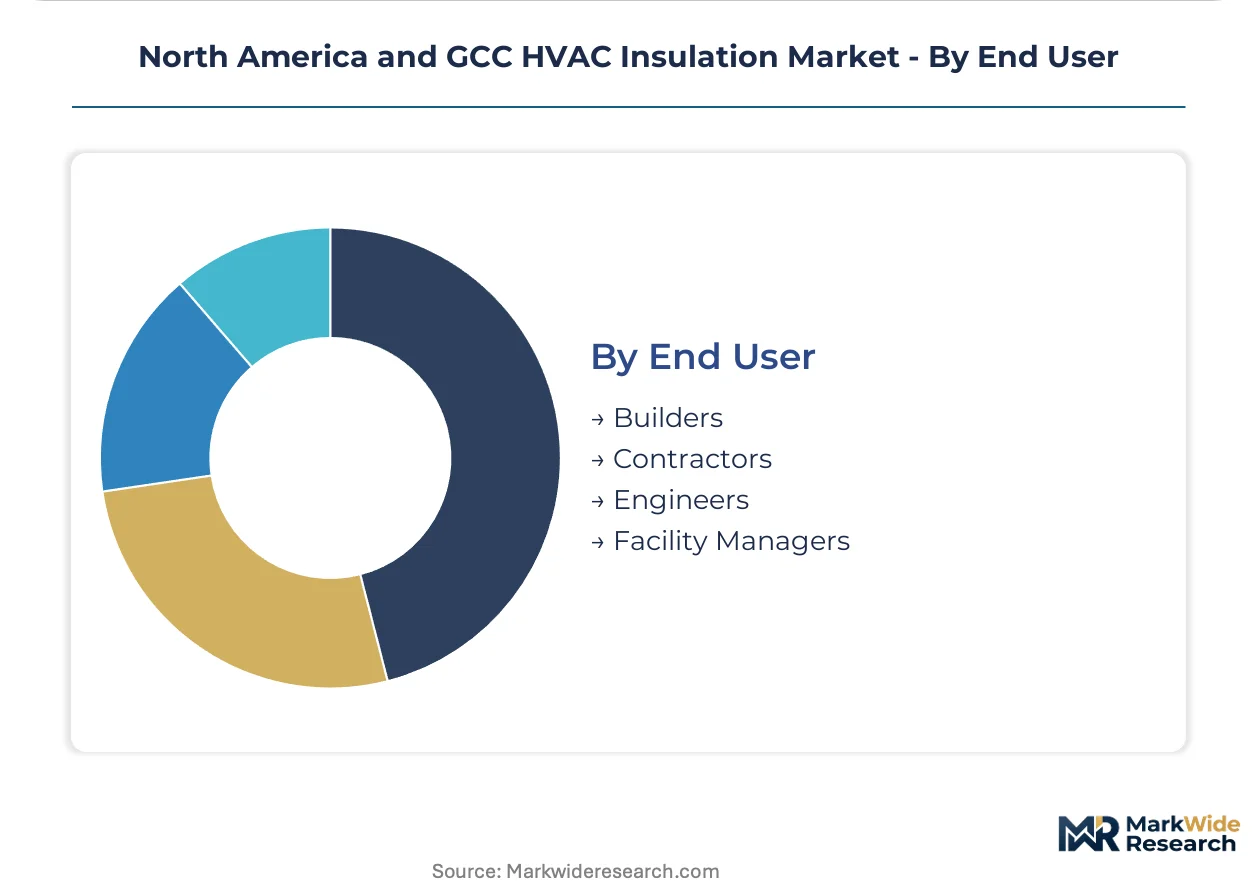
- Builders:Production homebuilders and multifamily developers select insulation for cost-optimized thermal compliance. Volume purchasing agreements with manufacturers reduce per-unit material costs.
- Contractors:Mechanical subcontractors execute installation and influence material selection through value engineering proposals. Texas and UAE contractor workforces show fragmentation in advanced foam handling skills.
- Engineers:Design firms specify thermal performance, fire ratings, and acoustic properties in construction documents. Large projects above fifty million dollars concentrate purchasing authority with engineering-procurement-construction firms.
- Facility Managers:Building operators drive replacement demand through energy cost reduction initiatives. US commercial retrofits often originate from facility management budget pressure rather than code mandates alone.
Engineers currently dominate specification authority, with facility managers emerging as the fastest-growing demand source through retrofit-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America and GCC HVAC Insulation Market splits sharply between US commercial retrofits driven by ASHRAE 90.1 enforcement and Gulf megaprojects requiring high-performance materials for extreme cooling loads. This consumption-mix differential shapes divergent specification priorities across the two geographies.
United States
Texas anchors domestic demand through hyperscale data center construction and petrochemical facility expansion along the Gulf Coast. The EPA's Significant New Alternatives Policy restricts high-global-warming-potential blowing agents, forcing polyurethane reformulation across domestic manufacturing. Chicago and Toronto commercial retrofits concentrate specification authority for bundled thermal-acoustic duct liner systems.
Saudi Arabia
Riyadh and Jeddah commercial towers drive specification of higher-R-value materials as the Saudi Building Code tightens thermal performance mandates. The SFDA aligns national chemical registries with EPA restrictions, creating harmonized material qualification pathways. NEOM Northwest megaproject construction is compressing installation schedules through factory-insulated duct module adoption.
United Arab Emirates
Dubai and Abu Dhabi residential towers specify closed-cell foam products where duct chase dimensions cannot accommodate thicker fiberglass layers. The UAE's MOHAP and Estidama Pearl Rating System mandate recycled content and low-global-warming-potential materials for green building certification. Abu Dhabi projects favor mineral wool with post-consumer glass feedstock for certification points.
Canada
Toronto's open-plan office retrofits bundle thermal and acoustic specifications as building owners seek energy cost reduction alongside occupant comfort. Provincial energy codes harmonize with ASHRAE 90.1 standards, accelerating replacement demand in commercial stock constructed before 2010. Mechanical contractors in the Greater Toronto Area face compressed specification cycles as enforcement intensifies.
North America and GCC HVAC Insulation Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The North America and GCC HVAC Insulation Market structures around multinational building materials conglomerates with mineral wool and fiberglass portfolios alongside specialized foam insulation fabricators. Three archetypes dominate: diversified global building materials suppliers, regional foam specialists, and vertically integrated glass fiber producers. Competitive moves center on capacity expansion in Texas and the UAE coupled with digital specification tool integration for engineering-procurement-construction firm procurement channels.
Within the diversified building materials tier, Owens Corning and Johns Manville exemplify scale-driven positioning across North American commercial retrofit channels. Armacell International occupies a specialist position in flexible foam insulation for irregular duct geometries and mechanical room applications. These three companies represent distinct capability configurations: fiberglass dominance, bundled thermal-acoustic systems, and elastomeric foam specialization respectively.
| Leading Market Players |
|---|
| Owens Corning |
| Johns Manville |
| Armacell International |
| Rockwool International |
| Knauf Insulation |
| Kingspan Group |
| Saint-Gobain |
| Arabian Fiberglass Insulation |
| L-ISOLANTE K-FLEX |
| Others |
Value Network & Pricing Analysis
Texas Gulf Coast manufacturing clusters concentrate fiberglass production capacity for North American commercial retrofit channels, with hurricane exposure and petrochemical feedstock volatility translating directly into pricing power asymmetries between domestic and imported material tiers. Owens Corning and Johns Manville leverage this geographic concentration to enforce contract premiums on ASHRAE 90.1-compliant specifications, while GCC importers absorb compliance verification costs at UAE and Saudi ports.
Pricing Analysis
Long-term offtake agreements dominate procurement for megaproject construction in Saudi Arabia and the UAE, insulating EPC firms from spot volatility in hydrofluoroolefin blowing agent markets. Three-tier pricing structure across premium aerogel-infused systems, standard mineral wool, and economy fiberglass batts differentiates by fire-smoke-toxicity certification grade and thermal performance per inch. Cost compression in closed-cell polyurethane board production is intensifying because EPA Significant New Alternatives Policy quota adjustments create input cost uncertainty. Production homebuilders in Texas exhibit highest price sensitivity, while data center developers in Dallas-Fort Worth and Dubai accept premiums for space-constrained high-R-value materials.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for mineral wool feedstock and specialty blowing agent chemicals. Manufacturing concentrates in the United States, Saudi Arabia, and the United Arab Emirates, with raw material dependencies on glass cullet, phenolic resin, and low-global-warming-potential hydrofluoroolefin formulations. Single-source vulnerability in UL and Intertek fire-smoke-toxicity testing capacity creates qualification bottlenecks for GCC export orders. Distribution runs through engineering-procurement-construction firm procurement channels for projects above fifty million dollars, displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerogel-infused blanket systems threaten traditional fiberglass dominance in premium commercial applications where space constraints and thermal performance requirements converge, forcing incumbents to defend specification authority through certification depth and digital tool integration.
For Market Incumbents: Build switching-cost moats through building information modeling integration that embeds thermal performance data directly into clash detection workflows used by Houston and Riyadh EPC firms. Expand fire-smoke-toxicity testing capacity at UL and Intertek to compress qualification timelines for GCC export orders. Defend against phenolic board specialists by anchoring utility-scale specifications through contractor training programs that address installer skill fragmentation across Texas and the Emirates. For New Entrants and Emerging Players: Mid-market commercial retrofits in Toronto and Chicago represent the most penetrable entry point for bundled thermal-acoustic duct liner systems that address open-plan office noise control requirements. Factory-insulated spiral duct modules for Saudi hospital and airport projects offer a second white-space target where field installation labor shortages constrain traditional build-in-place methods. Go-to-market execution should prioritize direct engagement with facility managers driving energy cost reduction initiatives rather than engineering specification channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mineral wool producers with post-consumer recycled content capabilities and Estidama Pearl Rating System certification depth. Long-term viability hinges on alignment with ASHRAE 90.1 and Saudi Building Code harmonization trajectories rather than commodity fiberglass volume. Acquisition targets should demonstrate digital specification tool integration and EPC firm procurement channel relationships. The signal to watch is code enforcement intensity in pre-2010 US commercial stock replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Texas fiberglass manufacturing additions serve Gulf Coast data center and petrochemical cooling demand clusters. |
| Backward Integration | In-house production of low-global-warming-potential blowing agents insulates margins from EPA quota volatility. |
| Digital Specification Integration | BIM-compatible material submittals concentrate purchasing authority with EPC firms in Houston and Riyadh. |
| Certification Investment | UL and Intertek fire-smoke-toxicity testing capacity expansion compresses GCC export order qualification timelines. |
| Joint Venture | Factory-insulated duct module partnerships with Saudi EPC firms address hospital and airport project labor constraints. |
Research Methodology
A standing panel of mechanical contractors, EPC procurement directors, facility managers, and building code officials provided ongoing calibration for demand assumptions and specification behavior patterns. Primary interviews with insulation product managers at diversified building materials conglomerates and specialized foam fabricators were cross-referenced against secondary validation from ASHRAE standard documentation, EPA Significant New Alternatives Policy filings, Saudi Building Code enforcement bulletins, and UAE Estidama Pearl Rating System technical guides. Bottom-up project pipeline analysis across Texas, Saudi Arabia, and the UAE was triangulated with top-down construction spending forecasts.
Scenario-bracketing around ASHRAE 90.1 adoption timelines and Saudi Building Code enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, installation context, and end-user purchasing authority, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from installed base replacement cycles and new construction penetration rates. Forecast inputs incorporated hyperscale data center cooling load specifications and GCC megaproject pipeline visibility.
Practitioners should monitor blowing agent cost volatility, hurricane-related production disruption in US Gulf Coast clusters, and code harmonization between ASHRAE updates and Gulf standardization initiatives for early signals of forecast revision. Forecasts reflect assumptions about enforcement continuity and material qualification pathway stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
Roof Insulation Market