
 Circular Saw Blades Market | 2026-2036
Circular Saw Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Circular Saw Blades Market Analysis
Skilled carbide-grinding technician shortages across Central European manufacturing hubs is unwinding capacity expansion plans at several specialty producers. Robert Bosch GmbH leverages its in-house sintering capabilities to sustain captive tungsten carbide supply for premium blade lines. Stanley Black and Decker competes through direct distribution control across North American home-improvement retail channels. Makita Corporation anchors its position in cordless-compatible thin kerf blade formats aligned with battery-powered tool ecosystems.
Circular saw blades are precision-engineered cutting discs, typically fabricated from hardened steel substrates with tungsten carbide or diamond grit edges brazed to tooth gullets, designed to sever wood, metal, or composite materials through rotary motion at peripheral speeds exceeding 80 meters per second. Their industrial purpose centers on dimensional accuracy and feed-rate efficiency in repetitive production environments. Tungsten carbide blades occupy the dominant value share due to superior wear resistance in hardwood and engineered-wood applications. Diamond coated segments command premium positioning in abrasive composite and cement-bonded panel cutting where conventional tooth geometries degrade rapidly. Bi-Metal formulations sustain growth in metal fabrication workshops requiring intermittent steel-cutting capability without dedicated cold saw investment.
OSHA workplace safety mandates in the United States govern blade guard specifications and noise exposure thresholds, while REACH chemical compliance in Europe restricts cobalt content in carbide binding matrices. Germany's KBA and Japan's METI both enforce rotational integrity testing protocols that filter uncertified imports from aftermarket channels. Stakeholders must monitor evolving alloy substitution trends as cobalt supply constraints and regulatory thresholds reshape raw material sourcing strategies.
Market Dynamics
Carbide-tipped blade technology is supplanting high-speed steel across precision woodworking and metal fabrication, compressing margins for conventional substrate producers while concentrating value capture among sintering-capable manufacturers.
Growth Catalysts
- REACH chemical compliance thresholds:European cobalt content restrictions are accelerating alloy substitution R&D, creating first-mover advantage for binding-matrix innovators who preempt regulatory tightening.
- Battery-powered tool ecosystems:Cordless circular saw proliferation is pulling demand for thin kerf blade formats optimized for lower-torque, higher-RPM motor characteristics.
- German manufacturing clusters:Concentrated specialized production around LEUCO AG and STARK SpA anchors European supply security for furniture and construction OEMs.
Market Restraints
- Tungsten carbide input volatility:Cobalt supply constraints from Central African mining concentration expose blade producers to binding alloy price spikes and availability interruptions.
- Rotational integrity certification barriers:Germany's KBA and Japan's METI testing protocols filter uncertified imports, structurally limiting aftermarket channel penetration for non-compliant manufacturers.
- Diamond segment cost premiums:Abrasive composite cutting applications face capital intensity barriers where diamond-coated blades command multiples over carbide alternatives.
Strategic Opportunities
- OSHA workplace safety mandate alignment:Blade guard specification and noise exposure threshold compliance creates specification windows for engineered vibration-dampening substrate designs.
- Bi-metal formulation expansion:Intermittent steel-cutting capability without dedicated cold saw investment opens metal fabrication workshop segments previously served by separate equipment categories.
- Direct distribution control:Home-improvement retail channel consolidation enables margin capture and private-label positioning for producers with captive North American logistics infrastructure.
Industry Challenges
- Carbide-grinding technician scarcity:Skilled workforce shortages across Central European manufacturing hubs are unwinding capacity expansion timelines at specialty producers.
- Legacy equipment integration friction:Precision blade formats optimized for cordless ecosystems face compatibility constraints with installed bases of corded high-torque saws.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circular Saw Blades Market |
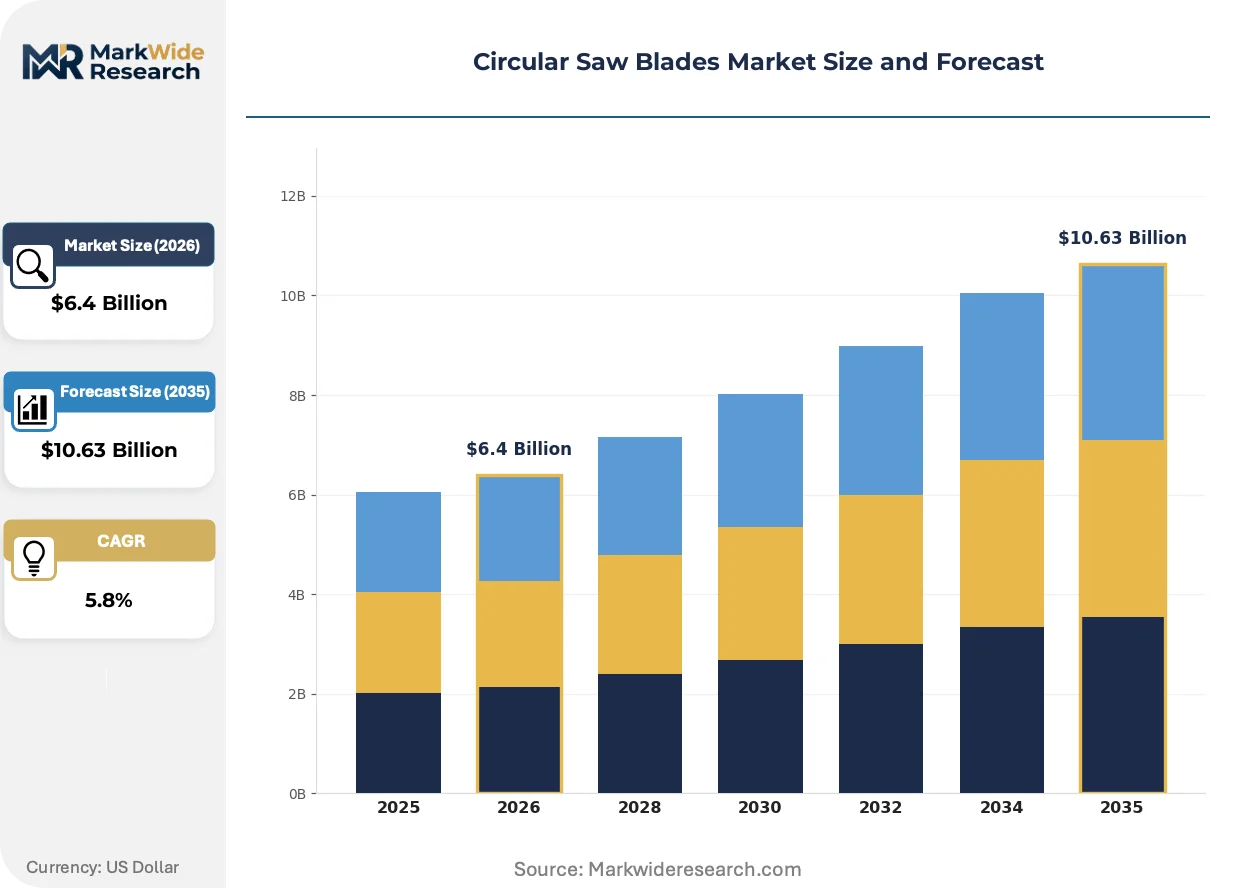
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tungsten Carbide, High-Speed Steel, Bi-Metal, Diamond Coated Application: Woodworking, Metal Cutting, Construction, Plastics Form: Standard Blades, Specialty Blades, Thin Kerf Blades, Replacement Blades End User: Manufacturers, Contractors, DIY Enthusiasts, Distributors |
| Companies Covered | Robert Bosch GmbH, Stanley Black and Decker, Makita Corporation, Freud, Lenox Corporation, DEWALT, General Saw Corporation, LEUCO AG, STARK SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circular Saw Blades Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are simultaneously pulling blade formulation toward tungsten carbide dominance while pushing binding matrix innovation to reduce strategic mineral dependence.
Polycrystalline diamond compact edge technology is supplanting conventional carbide in cement-bonded panel and abrasive composite applications where tooth geometry degradation previously forced frequent blade replacement. Engineered wood product manufacturers in Germany and Austria are adopting these formats aggressively. The structural consequence is compressing aftermarket revenue cycles while concentrating premium positioning among producers with in-house diamond synthesis or sintering partnerships.
REACH Annex XVII cobalt restrictions are forcing binding matrix reformulation across European supply chains, with ECHA compliance deadlines accelerating tungsten carbide substitution trials. Producers face reformulation cost absorption or premium pricing tests. Woodworking verticals in Scandinavia and Benelux are responding fastest, with specification sheets already excluding legacy cobalt-rich grades from new equipment tenders.
Buyers are consolidating procurement around certified rotational integrity standards, with KBA and METI test documentation becoming mandatory for insurance liability coverage in commercial carpentry operations. Traditional aftermarket distributors lose share to direct manufacturer relationships where batch traceability and test certificate provision are bundled. This pattern concentrates most visibly in German-speaking Central Europe and Japanese metropolitan construction markets.
Circular Saw Blades Market Segmentation
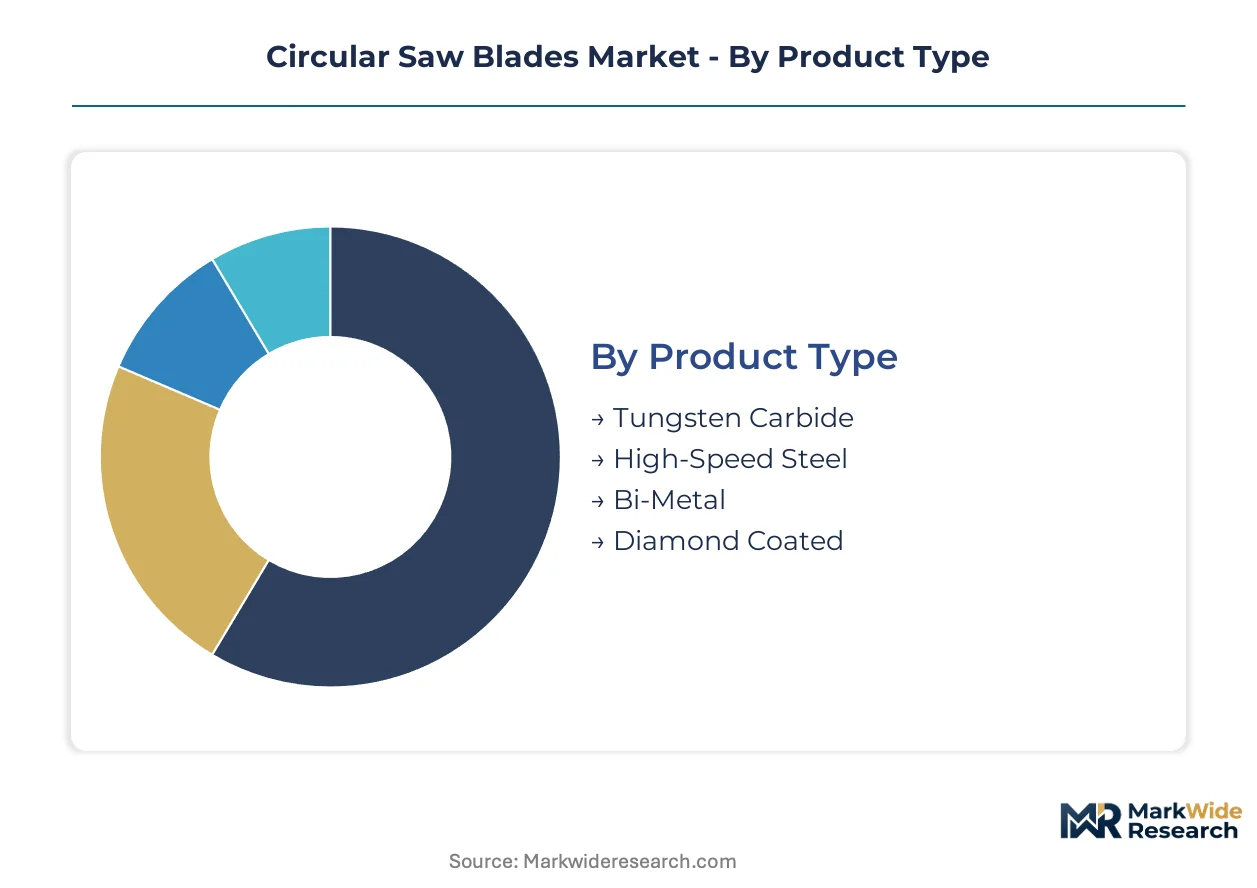
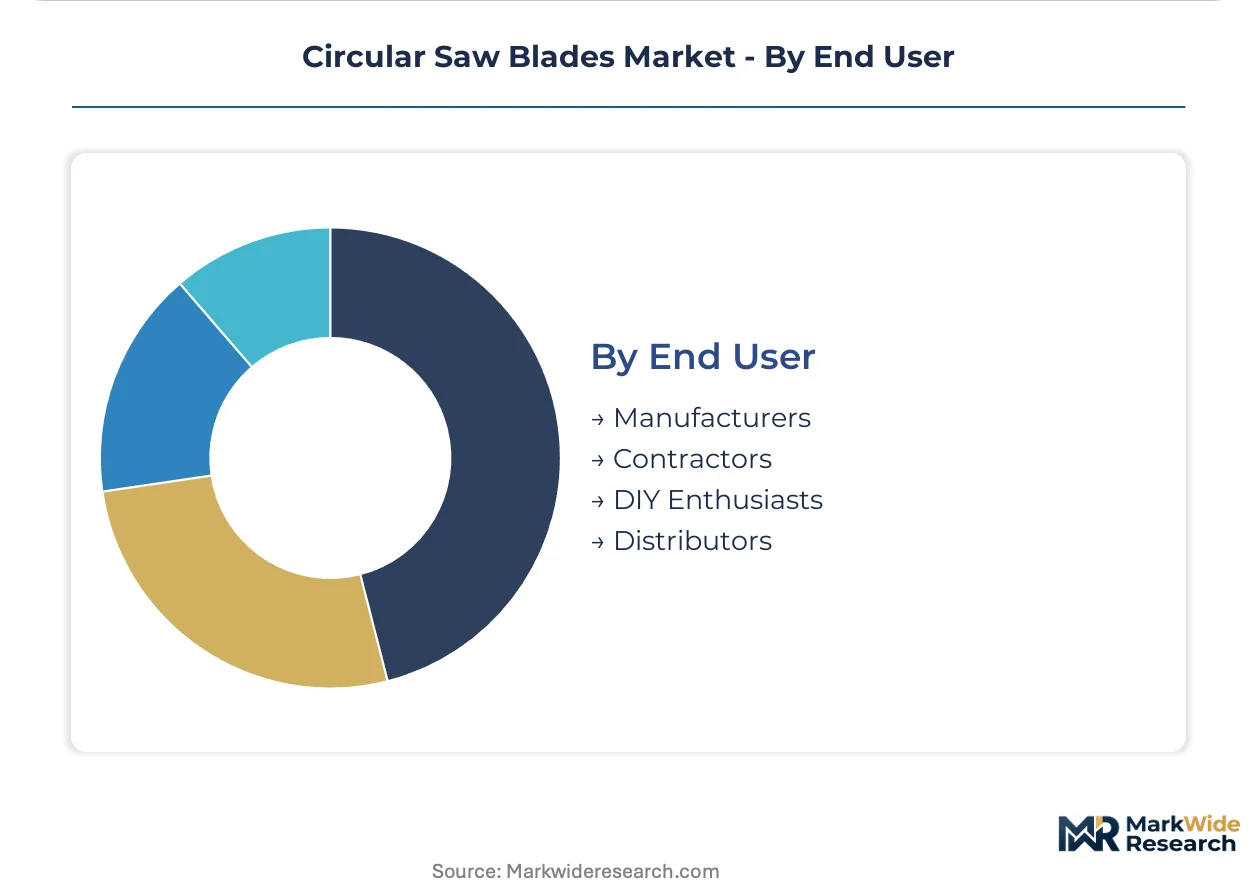
Circular saw blade segmentation reveals divergent sourcing patterns across substrate technologies and end-use applications. Product format specifications vary sharply between domestic workshop procurement and export-oriented industrial supply chains.
Product Type:
German and Austrian manufacturers dominate export supply for premium carbide grades, while high-speed steel production concentrates in lower-cost Asian supply bases serving price-sensitive replacement markets.
- Tungsten Carbide:Hardened steel substrates with brazed tungsten carbide tooth edges deliver superior wear resistance in hardwood and engineered-wood cutting. Demand concentrates among German furniture manufacturers and Austrian engineered wood producers seeking dimensional accuracy at feed rates exceeding 80 meters per second. REACH Annex XVII cobalt restrictions are accelerating binding matrix reformulation trials across European supply chains.
- Diamond Coated:Polycrystalline diamond compact edges command premium positioning in cement-bonded panel and abrasive composite applications where conventional carbide geometries degrade rapidly. German construction material manufacturers are adopting these formats aggressively to compress blade replacement cycles.
- High-Speed Steel:Conventional hardened steel formulations serve intermittent cutting tasks in budget-constrained workshop environments.
- Bi-Metal:Composite steel substrates with variable tooth hardness enable intermittent steel-cutting capability without dedicated cold saw investment.
Tungsten carbide holds the largest share; momentum sits with diamond coated formats.
Application:
Cost tier stratification separates capital-intensive industrial cutting from maintenance-driven replacement procurement across vertical end-uses.
- Woodworking:Precision dimensional cutting in repetitive production environments drives specification for vibration-dampening substrate designs. German and Austrian furniture manufacturers anchor European demand concentration, with procurement consolidating around KBA-certified rotational integrity documentation for insurance liability coverage.
- Metal Cutting:Bi-metal formulations sustain workshop demand for intermittent steel processing without dedicated equipment investment. Japanese metal fabrication SMEs favor thin kerf compatibility with cordless tool ecosystems.
- Construction:Abrasive composite and cement-bonded panel cutting requirements pull specification toward diamond-coated segments in German-speaking Central European markets.
- Plastics:Specialized tooth geometries address thermal deformation risks in synthetic material processing.
Woodworking commands the dominant value position; metal cutting applications are climbing the fastest as bi-metal substitution accelerates.
Form:
Volume concentration in replacement blades reflects installed base maintenance economics, while thin kerf innovation tracks cordless tool proliferation.
- Thin Kerf Blades:Reduced plate thickness optimizes cutting efficiency for lower-torque, higher-RPM motor characteristics in battery-powered circular saws. Makita Corporation's cordless ecosystem alignment exemplifies format-specific demand concentration.
- Standard Blades:Conventional plate geometries serve corded high-torque saw installed bases where legacy equipment integration constraints limit thin kerf adoption.
- Specialty Blades:Application-specific tooth configurations address niche material processing requirements.
- Replacement Blades:Aftermarket procurement cycles concentrate volume in distributor channels, though direct manufacturer relationships are gaining share where batch traceability and test certificate provision are bundled.
Replacement blades generate the highest unit volume; thin kerf formats are gaining share fastest from cordless tool ecosystem expansion.
End User:
Customer type determines channel structure, with manufacturers consolidating direct procurement while contractors and DIY segments flow through retail intermediaries.
- Contractors:Commercial carpentry operations mandate certified rotational integrity standards with KBA and METI test documentation for insurance liability coverage. German woodworking contractors represent a key demand expansion segment.
- Manufacturers:Industrial OEMs specify precision blade formats with engineered vibration-dampening substrates aligned with OSHA workplace safety mandates on noise exposure thresholds.
- DIY Enthusiasts:Home-improvement retail channel procurement favors price-accessible standard formats over premium carbide grades.
- Distributors:Traditional aftermarket intermediaries face share erosion to direct manufacturer relationships where specification bundling includes compliance documentation.
Manufacturers represent the highest value concentration; contractor procurement is expanding most quickly as certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical compliance thresholds in Germany anchor European regulatory gravity for circular saw blade manufacturing. German KBA rotational integrity testing protocols filter uncertified imports from aftermarket channels across Central European construction markets. Industrial clusters in Stuttgart and Hanover concentrate specialized carbide-tipped blade production serving furniture and engineered wood verticals.
Germany
LEUCO AG and STARK SpA anchor specialized manufacturing clusters serving European construction OEMs. ECHA compliance deadlines for cobalt content restrictions are accelerating binding matrix reformulation trials across Baden-Württemberg and Lower Saxony production facilities. Stuttgart-area fabricators dominate premium carbide grade export supply for dimensional accuracy in hardwood cutting applications.
United States
OSHA workplace safety mandates govern blade guard specifications and noise exposure thresholds in commercial carpentry operations. Home-improvement retail channel consolidation enables margin capture for producers with captive North American logistics infrastructure. Midwestern industrial distributors face share erosion to direct manufacturer relationships where batch traceability and test certificate provision are bundled.
Japan
METI rotational integrity testing protocols filter uncertified imports from aftermarket channels in Tokyo and Osaka metropolitan construction markets. Thin kerf blade formats optimized for cordless tool ecosystems concentrate demand among Japanese metal fabrication SMEs. Nagoya-area manufacturers align specification sheets with battery-powered circular saw proliferation trends.
Austria
Engineered wood product manufacturers in Upper Austria are adopting polycrystalline diamond compact edge technology aggressively. REACH Annex XVII cobalt restrictions are forcing specification exclusions of legacy cobalt-rich grades from new equipment tenders in Vorarlberg furniture clusters. Linz-area procurement offices consolidate around KBA-certified documentation for insurance liability coverage.
China
High-speed steel production concentrates in lower-cost supply bases serving price-sensitive replacement markets. MIIT standards enforcement creates structural barriers for uncertified blade imports into Shanghai and Guangzhou construction material distribution channels. Pearl River Delta fabricators supply budget-constrained workshop environments across Southeast Asian export markets.
Circular Saw Blades Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the circular saw blades market. Sintering-capable manufacturers capture premium positioning through in-house tungsten carbide supply control, while high-volume fabricators compete on standardized steel substrate economics. The market structures around three archetypes: integrated materials specialists, retail-channel dominators, and cordless ecosystem anchors. Dominant competitive moves include direct distribution infrastructure buildout and binding matrix reformulation R&D to preempt regulatory tightening.
Among German-anchored specialists, LEUCO AG and STARK SpA occupy positions within the premium-tier carbide segment serving European OEM procurement consolidation. Robert Bosch GmbH represents the integrated materials archetype through captive sintering capabilities. Stanley Black and Decker and Makita Corporation exemplify divergent channel strategies, with the former sitting within retail-channel control and the latter anchoring cordless-compatible format specialization.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Stanley Black and Decker |
| Makita Corporation |
| Freud |
| Lenox Corporation |
| DEWALT |
| General Saw Corporation |
| LEUCO AG |
| STARK SpA |
| Others |
Supply Flow & Price Mechanics
Tungsten carbide displacement of high-speed steel substrates simultaneously concentrates supply geography around German sintering clusters and compresses pricing power for conventional steel producers serving Asian replacement markets. Buyers face widening spreads between REACH-compliant premium grades and uncertified imports filtered by KBA and METI protocols.
Pricing Analysis
German and Austrian export grades command multiples over Pearl River Delta high-speed steel alternatives, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on KBA rotational integrity certification and cobalt-free binding matrix compliance, with ECHA deadlines intensifying cost absorption pressure on mid-tier European fabricators. DIY enthusiasts through home-improvement retail channels exhibit highest price sensitivity, while German furniture manufacturers prioritize dimensional accuracy over unit economics.
Supply Chain Analysis
Strategic stockpiling of tungsten carbide feedstock dominates German sintering-capable producers, while just-in-tim inventory prevails among Asian high-speed steel fabricators exposed to spot cobalt volatility. Supply concentrates in Germany, China, and Japan, with raw material dependencies spanning Central African cobalt, Chinese tungsten concentrate, and European binding alloy formulations. Single-source vulnerability in cobalt supply creates structural risk, with distribution running through direct manufacturer relationships for certified grades and traditional aftermarket intermediaries for replacement blades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The circular saw blades market tracks construction and furniture manufacturing cycles, with German housing starts and Japanese battery-powered tool adoption serving as lead indicators for demand inflection.
For Market Incumbents: Consolidate captive sintering capabilities to secure tungsten carbide supply against Central African cobalt constraints. Expand KBA and METI certification coverage to filter aftermarket competition, while accelerating binding matrix reformulation R&D ahead of REACH Annex XVII tightening. Channel control through direct distribution infrastructure captures margin from eroding traditional distributor relationships. For New Entrants and Emerging Players: Aftermarket documentation bundling gaps—where incumbents under-serve contractors requiring batch traceability for insurance liability—offer white-space entry. Target Austrian engineered wood producers and Japanese metal fabrication SMEs with thin kerf formats optimized for cordless ecosystems. Pursue private-label partnerships with North American home-improvement retailers lacking captive blade supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German carbide specialists holding KBA certification but lacking sintering integration. Five-to-ten year viability hinges on cobalt substitution chemistry leadership and cordless format alignment. Monitor German housing permit data and Makita cordless saw shipment volumes as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Sintering | Captive supply secures margin against cobalt price volatility for German producers. |
| Binding Matrix Reformulation R&D | REACH Annex XVII compliance creates first-mover advantage in European OEM procurement. |
| Thin Kerf Format Development | Cordless ecosystem alignment captures Japanese metal fabrication SME demand. |
| Direct Distribution Infrastructure Buildout | Batch traceability bundling displaces traditional aftermarket intermediaries. |
| KBA and METI Certification Expansion | Rotational integrity documentation becomes mandatory for commercial carpentry insurance. |
Methodological Framework
A standing panel of carbide-grinding technicians, OEM procurement managers at German furniture manufacturers, aftermarket distribution heads, and ECHA regulatory affairs specialists provided ongoing calibration across primary interviews and secondary validation. Bottom-up demand modeling drew from customs trade data, KBA certification registries, SEC filings of listed tool manufacturers, and construction material production statistics. Top-down market sizing triangulated against machinery investment flows and cobalt consumption reports.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated substrate technology, end-use application, form factor, and customer type dimensions. CAGRs derived from fitted growth curves applied to equipment replacement cycles and cordless tool penetration trajectories, with German housing starts and Japanese power tool shipments serving as exogenous demand inputs.
Underlying assumptions cover REACH enforcement timelines and cobalt supply continuity, with deviation risk concentrated in Central African mining disruptions and battery-powered tool adoption rates. Revision becomes warranted when cordless circular saw shipment growth crosses thresholds that restructure replacement blade demand composition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Masonry Cleaners Market
Tools
Horizontal Milling Machine Market
Tools
Global Staple Gun Market
Tools
Cordless Bandsaw Sander Market
Tools
Europe Paint Spray Guns Market
Tools
Rotary Hammer Drill Market
Tools
End Mill Holder Market
Tools
Chainsaw Market
Tools
Handheld Engraving Machine Market
Tools
Paint Spray Guns Market
Tools
Drill Presses Market
Tools
Brazing Torch Market
Tools
Power Nibbler Market
Tools
Global Table Saws Market
Tools
Extensometer Market
Tools
Woodworking Tools Market