
 Water Saving Shower Heads Market | 2026-2036
Water Saving Shower Heads Market Size, Share, and Industry Trends Forecast 2026-2036
Water Saving Shower Heads Market Analytics
EPA WaterSense certification is hardening the cost-of-entry calculus for new entrants seeking placement in federally funded housing projects. GROHE AG leverages its captive foundry network in Portugal to sustain margin control across thermostatic product lines. Kohler Co. anchors North American distribution through exclusive plumbing wholesaler relationships that competitors struggle to replicate.
Water saving shower heads are bathroom fixtures engineered to deliver rated spray performance below 2.0 gallons per minute through flow restrictors, pressure-compensating valves, or aerator inserts. Low-flow technology dominates residential retrofits where utility rebate eligibility hinges on certified performance thresholds, while smart-connected variants with usage analytics represent the fastest-expanding margin pool in hospitality specification. Pressure-compensating designs maintain consistent output across variable inlet pressures, making them the default specification in high-rise commercial towers where aerating models suffer performance degradation.
EPA WaterSense, the EU Ecodesign Directive, and California's Title 20 appliance standards collectively tighten allowable flow rates and testing protocols, forcing manufacturers to redesign spray engines or forfeit market access. Stakeholders must monitor regulatory divergence between federal efficiency mandates and state-level rebate qualification criteria, as misalignment between EPA certification and local utility program requirements can disqualify otherwise compliant products from procurement shortlists.
Market Dynamics
Building code convergence around flow-rate ceilings is compressing product development cycles, forcing manufacturers to redesign spray engines for dual certification across EPA WaterSense and EU Ecodesign testing protocols simultaneously.
Growth Catalysts
- EU Ecodesign Directive:Mandated maximum flow rates for sanitary tapware accelerate hospitality retrofit cycles across Germany, France, and Italy ahead of enforcement deadlines.
- Smart water metering infrastructure:Utility deployment of real-time consumption tracking creates rebate eligibility pathways for connected shower heads with usage analytics.
- High-rise commercial construction:Pressure-compensating valve technology addresses variable inlet pressure conditions in vertical towers, expanding specification in urban core developments.
Market Restraints
- Brass alloy cost volatility:Foundry input prices for copper-zinc alloys fluctuate with commodity markets, squeezing margin on thermostatic product lines.
- Testing laboratory capacity:EPA WaterSense certification backlog extends product launch timelines by six to nine months for new entrants lacking established lab relationships.
- Aerating model performance degradation:Hard water mineral accumulation reduces spray quality in regions with high calcium carbonate content, limiting retrofit appeal.
Strategic Opportunities
- India BIS standards alignment:Draft water efficiency labeling creates first-mover positioning for manufacturers pre-certifying products ahead of mandatory implementation.
- Subscription-based filter replacement:Recurring revenue models for anti-scale cartridge programs penetrate the premium residential segment.
- California Title 20 expansion:Proposed amendments to appliance standards may extend flow-rate requirements to commercial fixtures, opening public building procurement.
Industry Challenges
- Spray pattern engineering talent:Computational fluid dynamics specialists command premium compensation, constraining R&D expansion at mid-tier manufacturers.
- Legacy plumbing infrastructure compatibility:Variable thread standards and retrofit adapter requirements complicate installation training for contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Saving Shower Heads Market |
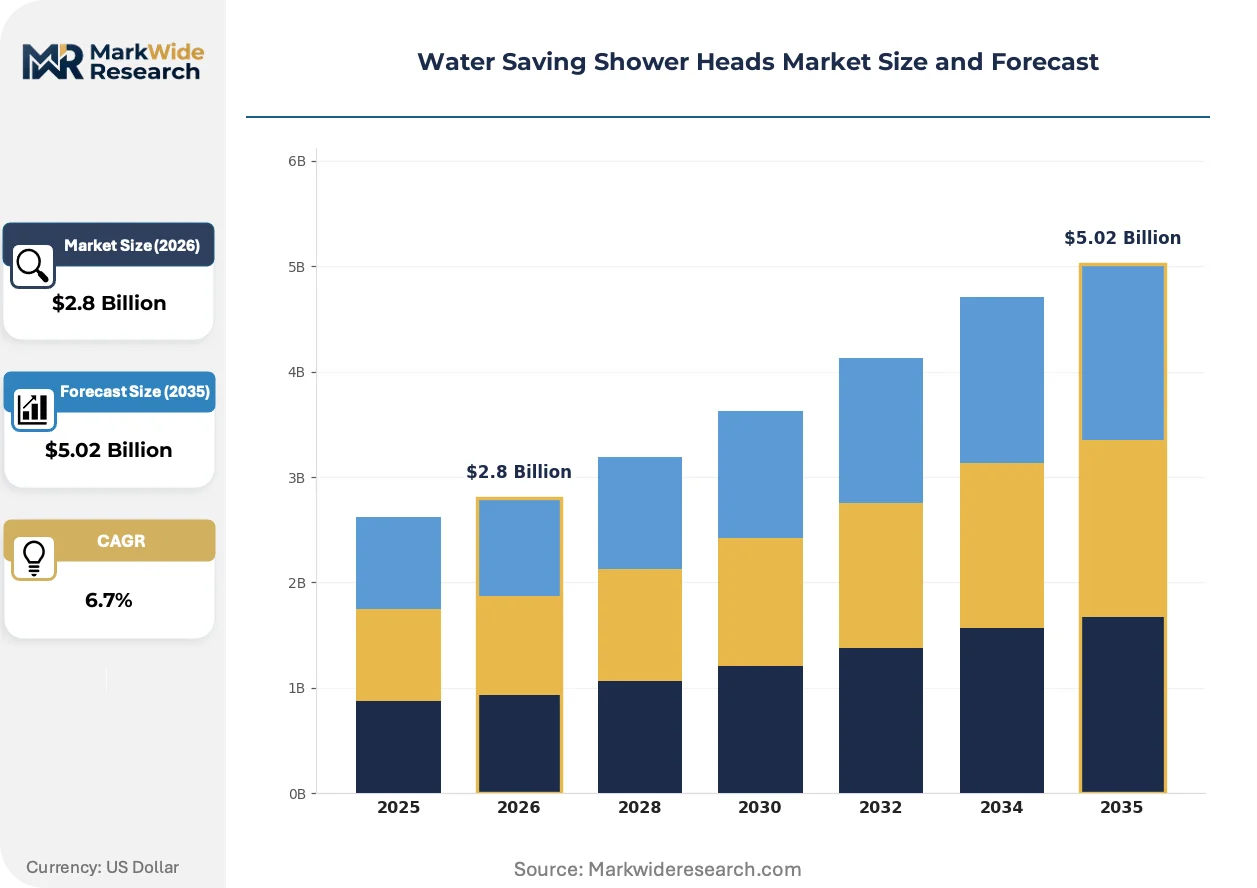
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Handheld, Rainfall, Smart Technology: Low Flow, Pressure Compensating, Aerating, Thermostatic End User: Residential, Commercial, Hospitality, Industrial Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | GROHE AG, LIXIL Corporation, Kohler Co., Jacuzzi Inc., Aqualisa, Masco Corporation, Moen Incorporated, Dornbracht, Hansgrohe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Saving Shower Heads Market Evolving Landscape
Digital water management systems are penetrating fixture specification, embedding consumption analytics directly into bathroom hardware and reshaping how utilities structure rebate eligibility around verified performance data.
Air-induction technology is integrating pressurized ambient air into water streams to maintain perceived spray intensity at reduced flow rates. Hospitality chains in California and Germany specify these systems to satisfy guest experience benchmarks while meeting regulatory thresholds. The technology is integrating usage data capture capabilities that feed building management dashboards, compressing the distinction between fixture hardware and smart building infrastructure.
EPA WaterSense certification protocols are tightening spray coverage uniformity requirements, eliminating marginal products from federally funded housing procurement shortlists. Manufacturers must redesign nozzle geometries and retest existing SKUs to maintain program eligibility. Multi-family housing developers in Texas and Florida now treat WaterSense listing as a non-negotiable bid qualification, shifting competitive position toward certified incumbents.
Utility rebate program administration is consolidating around third-party verification platforms that require connected fixture installation for eligibility. Contractors in the Pacific Northwest and New England must now coordinate digital commissioning alongside physical installation. The shift compresses traditional wholesale distribution margins as platform fees capture value previously retained by plumbing supply houses.
Water Saving Shower Heads Market Segmentation
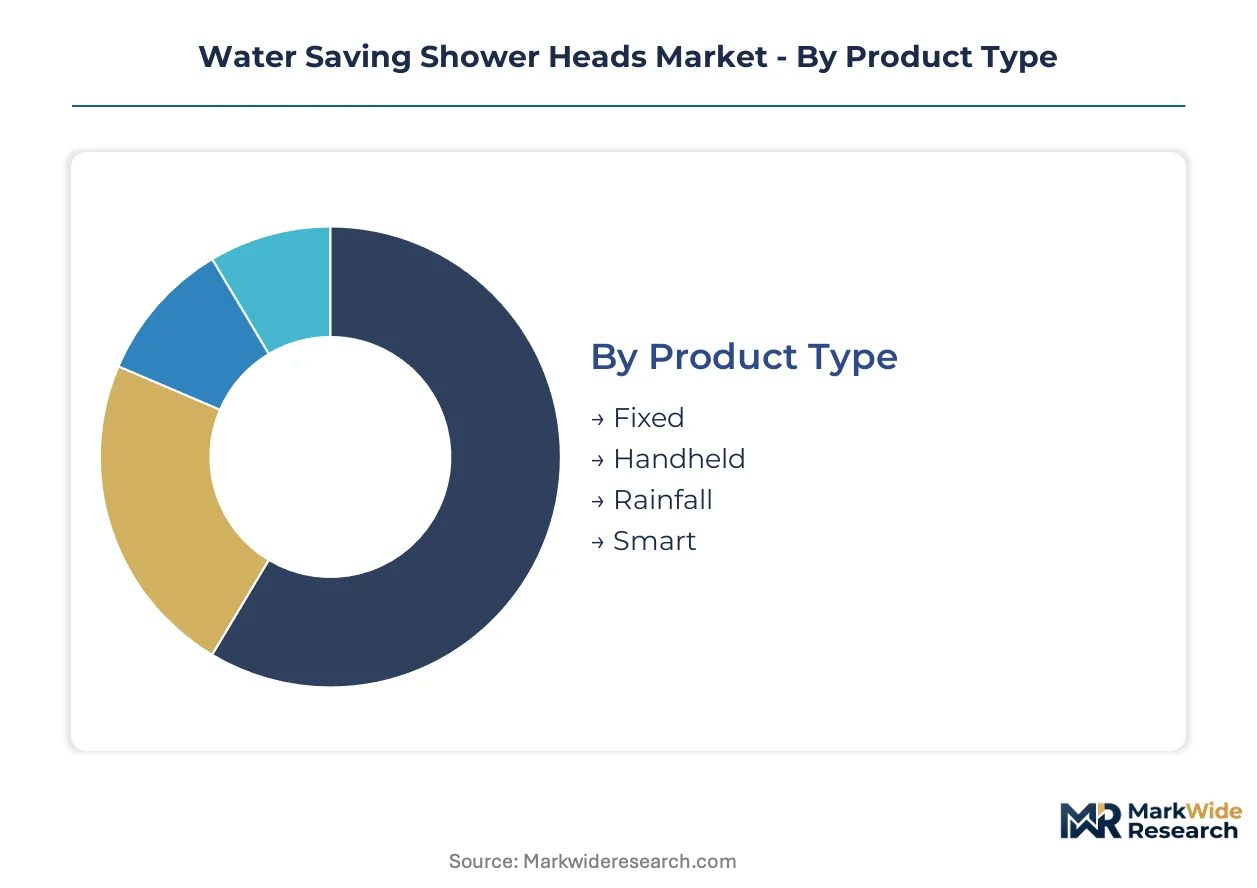
Segmentation in water saving shower heads reveals how regulatory pressure and installation context reshape procurement patterns. Buyers select products based on certification requirements, pressure conditions, and rebate eligibility rather than price alone.
Product Type:
Cost tier separates specification-grade hospitality retrofits from mass-market residential replacements.
- Fixed:Wall-mounted units with integrated flow restrictors dominate new construction specifications where California Title 20 compliance is mandatory. Multi-family housing developers in Texas and Florida treat EPA WaterSense listing as a non-negotiable bid qualification, shifting procurement toward certified fixed-mount suppliers.
- Handheld:Detachable wand configurations with flexible hose attachments concentrate in residential retrofit channels where aging-in-place accessibility drives replacement cycles. German plumbing wholesalers report handheld units capturing premium shelf space ahead of EU Ecodesign enforcement deadlines.
- Rainfall:Large-diameter overhead spray heads with air-induction technology maintain perceived intensity at reduced flow rates.
- Smart:Connected fixtures with embedded usage analytics and building management system integration.
Volume sits with Fixed; growth tilts toward Smart.
Technology:
Application context determines whether pressure stability or aeration quality takes priority in specification.
- Low Flow:Flow restrictors limiting output below 2.0 gallons per minute represent the baseline technology for residential rebate programs. Utility administrators in the Pacific Northwest require digital commissioning verification for eligibility, compressing traditional wholesale margins.
- Pressure Compensating:Valve mechanisms maintaining consistent spray performance across variable inlet pressures serve as default specification in high-rise commercial towers. Urban core developments in vertical construction markets favor these units where aerating models suffer degradation.
- Aerating:Air-mixing inserts that reduce water volume while maintaining spray coverage.
- Thermostatic:Temperature-stabilizing valves preventing scalding through automatic mixing.
Low Flow commands current procurement volume; Pressure Compensating is climbing the fastest in commercial specification.
End User:
Customer type dictates whether regulatory compliance or guest experience benchmarks drive purchasing decisions.
- Residential:Single-family and multi-family household replacements where utility rebate eligibility hinges on certified performance thresholds. EPA WaterSense certification backlog extends product launch timelines for new entrants lacking established laboratory relationships.
- Commercial:Office building and institutional facility procurement governed by public sector bid requirements.
- Hospitality:Hotel and resort chains across Europe retrofitting guest bathrooms ahead of Ecodesign mandates.
- Industrial:Manufacturing and processing facility wash stations with durability requirements.
Residential absorbs the greatest unit volume; Hospitality shows the steepest expansion trajectory.
Distribution Channel:
Supply concentration varies by whether installation requires contractor coordination or consumer self-selection.
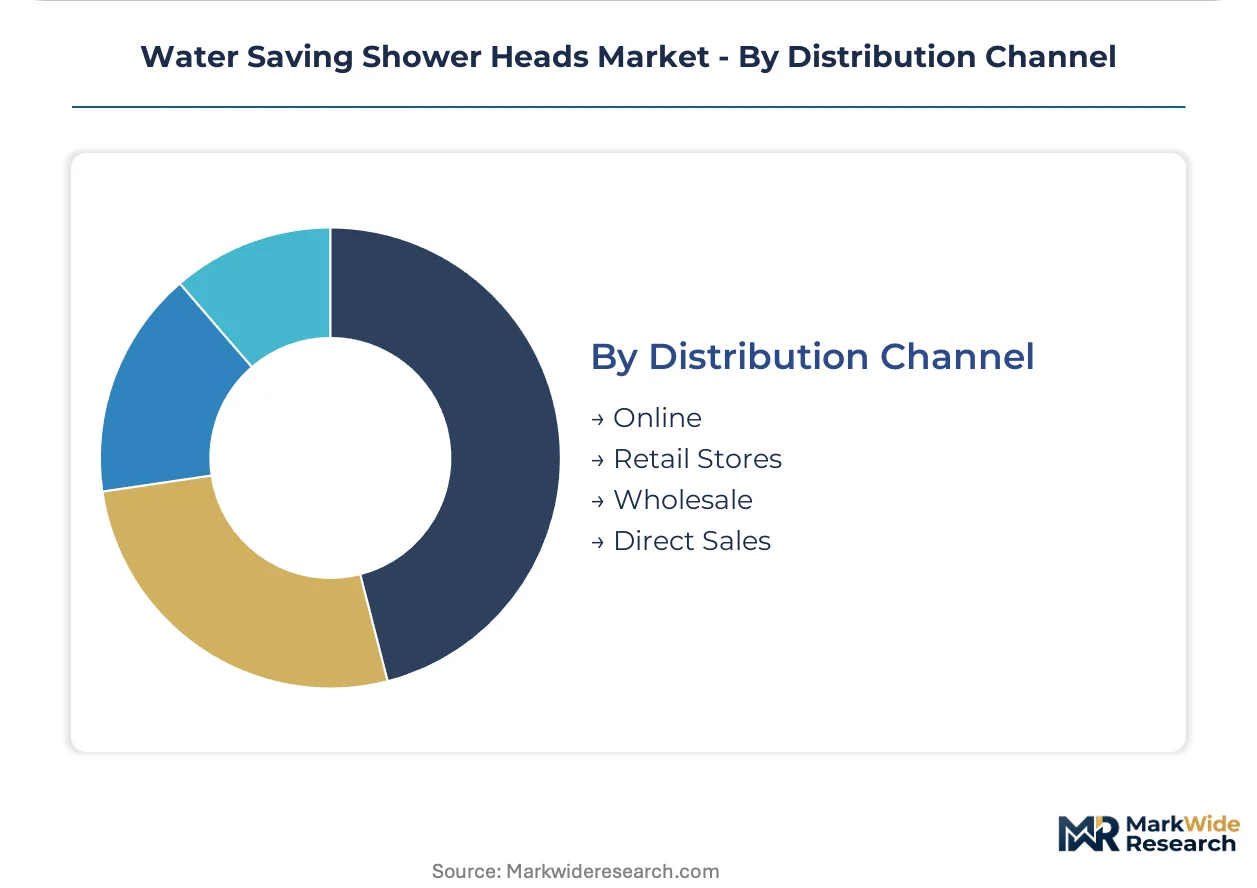
- Online:Direct-to-consumer platforms capturing replacement demand from homeowners seeking rebate-eligible models. Third-party verification platforms now require connected fixture installation for program eligibility, shifting value capture from plumbing supply houses to digital intermediaries.
- Retail Stores:Big-box and specialty hardware channels serving emergency replacement and renovation projects.
- Wholesale:Plumbing supply houses and distributor networks serving contractor-specified commercial projects.
- Direct Sales:Manufacturer relationships with hospitality chains and multi-property developers.
Wholesale retains commercial project volume; Online is gaining share fastest in residential replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement volume concentrates in Germany and California where building codes and rebate programs intersect. Hospitality chains across Europe retrofit ahead of regulatory deadlines while utility administrators in North America tighten verification protocols.
United States
California Title 20 appliance standards and EPA WaterSense certification drive multi-family housing procurement in Texas and Florida. Utility rebate programs in the Pacific Northwest now require digital commissioning verification for connected fixture eligibility. Los Angeles and San Francisco anchor commercial specification volume for pressure-compensating designs in high-rise developments.
Germany
EU Ecodesign Directive enforcement deadlines accelerate hospitality retrofit cycles across hotel chains. Plumbing wholesalers report handheld units capturing premium shelf space ahead of mandatory flow-rate implementation. The Rhine-Ruhr industrial corridor sustains captive foundry networks supplying thermostatic valve components to fixture manufacturers.
India
Draft BIS water efficiency labeling standards create first-mover positioning for manufacturers pre-certifying products. Residential replacement demand concentrates in Maharashtra and Gujarat where utility rebate programs pilot smart metering infrastructure. Mumbai and Delhi-NCR drive specification for low-flow fixtures in commercial tower construction.
United Kingdom
Building regulations tightening flow-rate ceilings compress product development cycles for dual certification. Hospitality retrofit demand concentrates in London and Southeast England ahead of EU alignment deadlines. The Midlands manufacturing base supplies aerator insert components to European fixture assemblers.
Japan
METI efficiency standards and aging housing stock drive residential replacement cycles in Kanto and Kansai regions. Smart water metering deployment in Tokyo creates rebate pathways for connected fixtures with usage analytics. Osaka anchors commercial specification for thermostatic designs in hospitality and institutional projects.
Water Saving Shower Heads Market Competitive Landscape
German producers anchor the premium tier through captive manufacturing networks; North American specialists hold distribution advantages in contractor channels. The vendor base stratifies across three tiers: integrated fixture conglomerates with foundry ownership, mid-scale specialists in pressure-compensating technology, and regional fabricators serving retrofit replacement. Dominant competitive moves include backward integration into brass alloy supply and exclusive wholesaler relationship lockups.
Among Germany-based fabricators, GROHE AG and Hansgrohe exemplify the integrated premium archetype through captive production control. Kohler Co. occupies a position representing North American distribution concentration through plumbing supply house relationships. LIXIL Corporation sits within the Asia-Pacific scale-driven tier serving multi-regional specification markets.
| Leading Market Players |
|---|
| GROHE AG |
| LIXIL Corporation |
| Kohler Co. |
| Jacuzzi Inc. |
| Aqualisa |
| Masco Corporation |
| Moen Incorporated |
| Dornbracht |
| Hansgrohe |
| Others |
Value Network & Pricing Analysis
Multi-family housing developers in Texas and Florida anchor procurement volume for EPA WaterSense-certified fixtures, compressing supplier margins through volume-contract pricing that favors incumbents with established laboratory relationships and dual-certification capabilities.
Pricing Analysis
Short lead-time premiums apply to pressure-compensating valve assemblies where EPA WaterSense certification backlog extends standard delivery windows. Three-tier pricing structure separates thermostatic hospitality specifications from standard residential fixed-mount units and economy aerator retrofit kits. Cost compression in brass alloy inputs is intensifying because foundry capacity concentrates in Portugal and Germany. Price sensitivity peaks among online direct-to-consumer buyers comparing rebate-eligible models, while hospitality chains prioritize guest experience benchmarks over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Portuguese captive foundry networks supplying thermostatic valve castings to German fixture manufacturers. Component sourcing draws from Germany for precision-machined valve bodies, China for aerator inserts and hose assemblies, and India for emerging BIS-standard production. Tariff exposure runs through brass alloy import dependencies tied to copper-zinc commodity markets. Distribution runs through plumbing supply houses serving contractor-specified commercial projects, with digital platform fees capturing value from traditional wholesale channels in connected-fixture rebate programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected fixtures with embedded usage analytics are displacing legacy low-flow hardware as utilities mandate digital commissioning verification for rebate eligibility, compressing the competitive window for non-smart product lines.
For Market Incumbents: Extend certification investment into dual EPA WaterSense and EU Ecodesign protocols ahead of regulatory divergence, while backward integration into brass alloy supply buffers margin compression from commodity volatility. Lock exclusive wholesaler relationships in North American plumbing supply channels against emerging digital platform intermediaries.
For New Entrants and Emerging Players: Enter via pre-certification positioning under India's draft BIS water efficiency labeling standards, where first-mover advantage awaits mandatory implementation. Target residential replacement demand in Maharashtra and Gujarat utility rebate pilots, leveraging direct-to-consumer platforms with subscription-based anti-scale cartridge programs.
For Investors and Strategic Acquirers: The window for entry favors mid-scale pressure-compensating technology specialists with captive CFD engineering talent and established high-rise commercial specification relationships. Monitor smart water metering infrastructure deployment rates in Pacific Northwest and New England utilities as the inflection signal for connected-fixture rebate program expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous EPA WaterSense and EU Ecodesign testing preserves market access across regulatory jurisdictions. |
| Backward Integration into Foundry Capacity | Captive brass alloy supply in Portugal or Germany insulates margin from copper-zinc commodity volatility. |
| Smart Fixture Platform Development | Embedded usage analytics qualify products for utility rebate programs requiring digital commissioning verification. |
| Subscription Filter Replacement Model | Recurring revenue from anti-scale cartridge programs penetrates premium residential retrofit segments. |
| India BIS Pre-Certification | Early alignment with draft water efficiency labeling creates positioning ahead of mandatory standards implementation. |
Research Methodology
Document review covered regulatory filings from EPA WaterSense and EU Ecodesign directive databases, complemented by interviews with plumbing supply house procurement managers, utility rebate program administrators, hospitality facility directors, and thermostatic valve foundry operations heads. Secondary sources included building code compliance records, customs trade data for brass alloy imports, and SEC filings from listed fixture manufacturers. Bottom-up unit demand estimates triangulated against top-down construction spending projections.
Cross-referencing historical certification timeline data with expert panel input on laboratory capacity constraints shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology mechanism, end-user vertical, and distribution channel, with regional regulatory cluster as an industry-specific overlay. CAGRs were derived from elasticity-adjusted replacement cycle analysis, incorporating smart metering infrastructure deployment curves and hospitality retrofit acceleration patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory divergence between federal efficiency mandates and state-level rebate qualification criteria. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Europe District Cooling Pipeline Network Market