
 Industrial Electric Boiler Market | 2026-2036
Industrial Electric Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Electric Boiler Market Analysis
Direct-to-facility engineering partnerships is tilting procurement authority toward technical specialists rather than traditional distributors. Bosch Thermotechnology leverages its integrated heat-pump and boiler portfolio to control specification conversations with plant engineers. Cleaver-Brooks sustains its installed-base advantage through aftermarket service contracts that anchor long-term customer relationships. Mitsubishi Heavy Industries competes on large-scale thermal power integration, extending its energy-systems expertise into industrial steam applications.
An industrial electric boiler converts electrical energy into heat through resistive or electrode elements, generating steam or hot water at pressures typically ranging from low-pressure process heating to high-pressure power-generation thresholds. These systems serve manufacturing facilities requiring precise temperature control, zero on-site combustion emissions, and rapid load-response capability. Horizontal configurations dominate heavy-process installations where footprint flexibility and maintenance access determine project economics, while steam-output units capture premium-margin opportunities in pharmaceutical sterilization and clean-steam applications. The above-1000 kW power rating segment leads volume in energy-intensive sectors, though 301-600 kW units are displacing gas alternatives in mid-size food processing plants where carbon targets tighten fastest.
The EU F-Gas Regulation and REACH chemical compliance frameworks restrict refrigerant and insulation material choices in boiler system design, pushing manufacturers toward certified low-GWP component supply chains. EPA emissions standards for industrial sources in the United States and China's MEE carbon-intensity benchmarks create divergent certification burdens that shape regional product portfolios. Stakeholders must monitor how national grid-decarbonization timelines alter the lifecycle carbon accounting that justifies electric boiler capital expenditure against fossil alternatives.
Market Dynamics
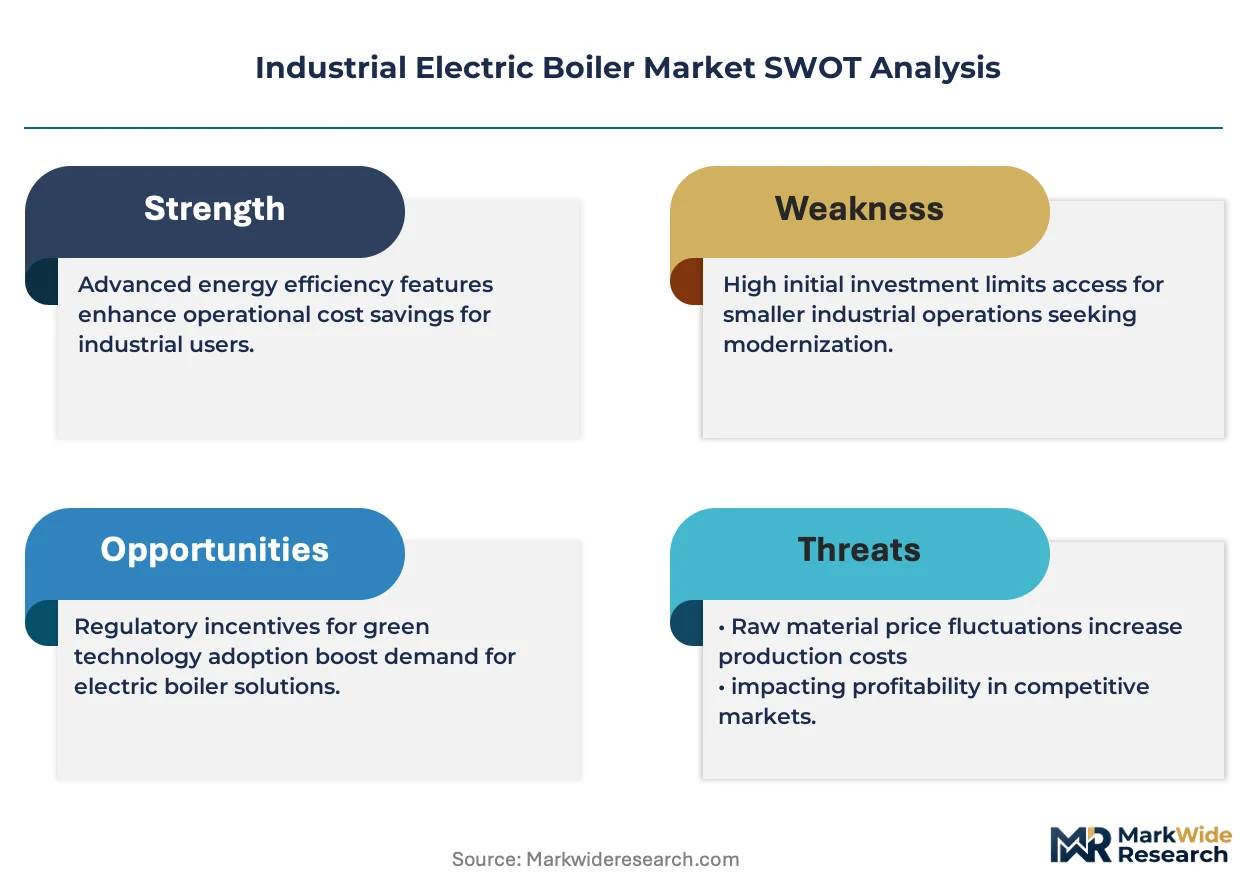
The EU F-Gas Regulation and parallel decarbonization mandates are forcing facility retrofits across energy-intensive manufacturing, redirecting capital from gas-fired infrastructure toward electric steam systems that eliminate on-site combustion emissions.
Growth Catalysts
- EU F-Gas Regulation:Industrial facilities in Germany and the Netherlands face mandatory refrigerant-phaseout timelines that accelerate boiler electrification projects in chemical processing clusters.
- Food and beverage sterilization:Clean-steam requirements in dairy and pharmaceutical manufacturing pull demand toward electrode boiler configurations with rapid load-response capability.
- Grid-decarbonization accounting:Lifecycle carbon methodologies in Sweden and Denmark now favor electric thermal systems over biomass alternatives in district heating applications.
Market Restraints
- Copper and nickel price volatility:Resistive heating element manufacturing faces input cost swings that compress margin stability for boiler OEMs.
- Transformer infrastructure gaps:Rural industrial parks in Poland and Romania lack grid capacity upgrades needed for megawatt-scale electric steam deployment.
- Electrode scaling limitations:High-conductivity feedwater requirements restrict electrode boiler adoption in regions with variable water chemistry.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU CBAM creates competitive advantage for electric boiler operators exporting processed goods to European markets.
- Heat-pump boiler convergence:Integration of high-temperature heat pumps with electric steam generators opens efficiency gains in paper and pulp drying applications.
- Aftermarket service digitization:Predictive maintenance platforms for resistive element degradation create recurring revenue streams independent of new equipment sales.
Industry Challenges
- High-voltage electrical contracting scarcity:Qualified installation capacity for above-1000 kW systems lags project pipeline growth in German manufacturing corridors.
- Legacy control system integration:SCADA retrofit complexity extends commissioning timelines when electric boilers replace existing gas-fired assets in continuous-process plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Electric Boiler Market |
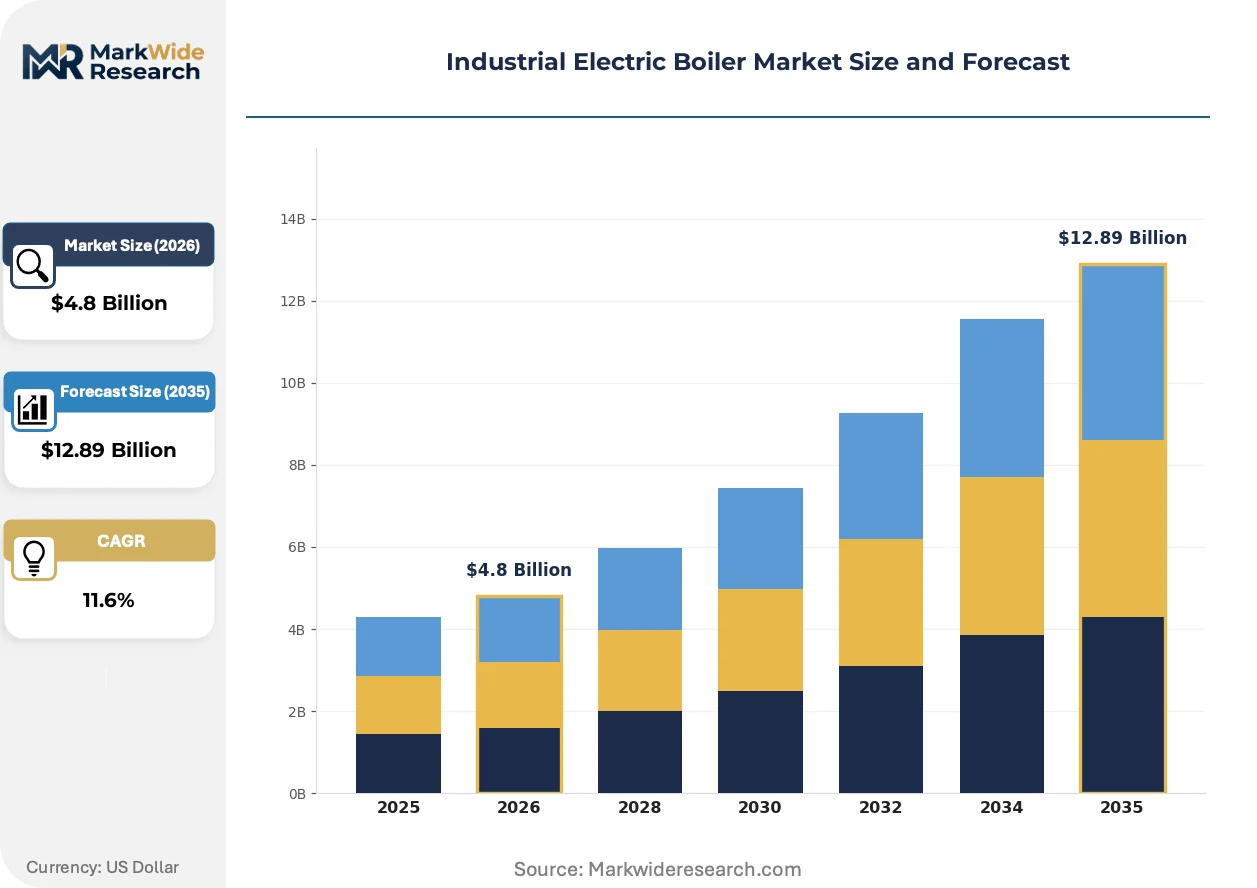
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Instantaneous, Steam End User: Manufacturing, Food & Beverage, Pharmaceuticals, Textiles Power Rating: Up to 300 kW, 301-600 kW, 601-1000 kW, Above 1000 kW Installation: On-site, Off-site, Modular, Portable |
| Companies Covered | Chromalox, Mitsubishi Heavy Industries, Bosch Thermotechnology, Thermax, Babcock & Wilcox Enterprises, Viessmann Climate Solutions, PARAT Halvorsen AS, Bosch Industriekessel, Cleaver-Brooks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Electric Boiler Market Emerging Trajectories
Electrode boiler technology is collapsing the cost-performance gap with resistive systems, while regulatory pressure on refrigerants and combustion emissions accelerates specification conversations toward all-electric thermal architectures.
Electrode steam generators leverage water conductivity to pass current directly through the boiler feed, achieving thermal efficiencies above 99% without heating element degradation. Pharmaceutical sterilization facilities in Switzerland and Belgium are specifying electrode configurations for clean-steam applications where mineral carryover must approach zero. This technology is collapsing the historical premium pricing of high-purity steam systems, compressing margins for traditional resistive boiler suppliers serving life-science end-uses.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants used in heat-pump hybrids and thermal storage systems paired with electric boilers. Boiler OEMs must now certify low-GWP insulation materials and refrigerant circuits under ECHA REACH frameworks, extending product development cycles by 8-14 months for pan-European compliance. German engineering-intensive clusters face the tightest compliance windows, driving consolidation toward suppliers with pre-certified component supply chains.
Plant engineers now specify integrated thermal-energy-as-service contracts rather than capital equipment purchases, transferring operational risk to OEM service arms. Food processors in Denmark and the Netherlands favor performance-guaranteed steam supply agreements with uptime penalties written into 10-year terms. This contracting evolution concentrates procurement authority with technical specialists at Bosch Thermotechnology and Cleaver-Brooks, marginalizing traditional distributor channels in specification conversations.
Industrial Electric Boiler Market Segmentation
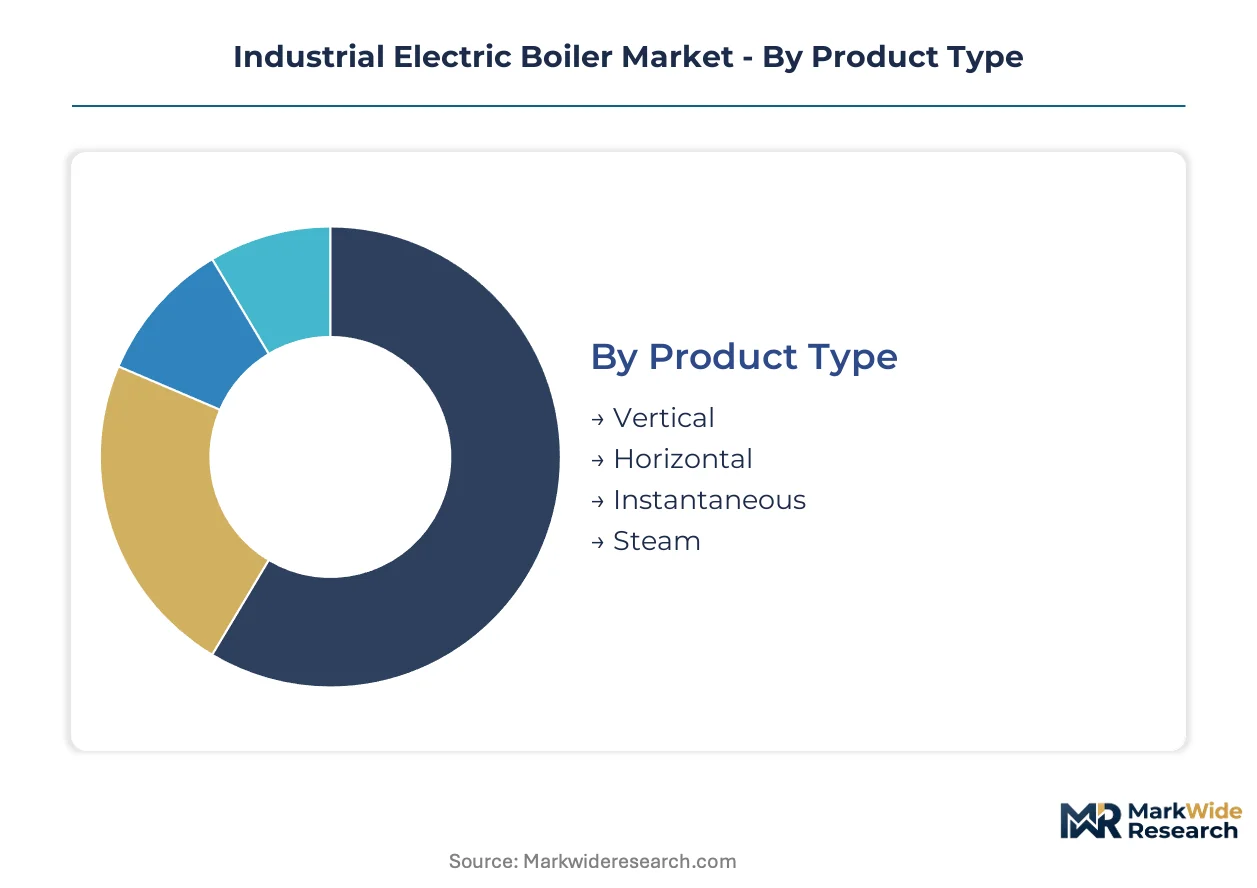
Segmentation in the industrial electric boiler market reveals how thermal energy specifications diverge across facility constraints and process requirements. Procurement patterns cluster around installation flexibility, steam purity demands, and grid-connection capacity rather than uniform capacity scaling.
Product Type:
Configuration geometry determines footprint economics and maintenance access for facility engineers specifying new thermal assets.
- Horizontal:These units mount at grade level with side-access panels that simplify element replacement in continuous-process plants. German chemical processors specify horizontal configurations for 24-hour operations where downtime minimization outweighs capital cost premiums.
- Steam:Steam-output generators achieve saturation pressures required for pharmaceutical sterilization and clean-process applications. Swiss and Belgian life-science facilities specify electrode-based steam systems for zero-mineral-carryover requirements under EMA manufacturing guidelines.
- Vertical:Compact footprint suits retrofit installations in urban manufacturing facilities with constrained mechanical room space.
- Instantaneous:On-demand heating eliminates storage losses for facilities with intermittent hot-water requirements.
Horizontal configurations command the established base. The steepest expansion runs through Steam systems.
End User:
Process thermal intensity and emissions compliance timelines create divergent specification priorities across industrial sectors.
- Food & Beverage:Dairy pasteurization and beverage sterilization require clean-steam systems with rapid load-response for batch-cycle variability. Dutch and Danish processors face the EU's tightest carbon-accounting mandates, accelerating displacement of gas-fired units in cheese production and brewing operations.
- Manufacturing:General manufacturing spans heat-treatment, parts washing, and process heating with moderate pressure requirements. German automotive component suppliers specify 301-600 kW resistive units for paint-curing lines where precise temperature control reduces defect rates.
- Pharmaceuticals:cGMP compliance drives specification toward electrode steam with validated purity documentation.
- Textiles:Dyeing and finishing operations require consistent hot-water delivery for color-fastness consistency.
Manufacturing retains the largest installed base. Food & Beverage shows the steepest expansion trajectory as carbon border adjustments reshape export competitiveness.
Power Rating:
Electrical connection capacity and load-profile continuity determine optimal kW specification for facility operators.
- Above 1000 kW:Megawatt-scale electrode systems serve district heating networks and large chemical processing clusters. Swedish municipal utilities specify these units for grid-balancing services where rapid thermal response absorbs renewable electricity surges.
- 301-600 kW:Mid-capacity resistive boilers displace gas alternatives in food processing plants with tightening carbon targets. Polish meat processors adopt this segment for smokehouse and cooking operations where EU F-Gas compliance deadlines approach.
- Up to 300 kW:Small-format units serve auxiliary heating and pilot-scale manufacturing operations.
- 601-1000 kW:Intermediate capacity fills the gap between mid-size processing and megawatt-scale thermal demand.
Above 1000 kW systems anchor the revenue base. The 301-600 kW range is expanding most quickly as mid-size facilities electrify.
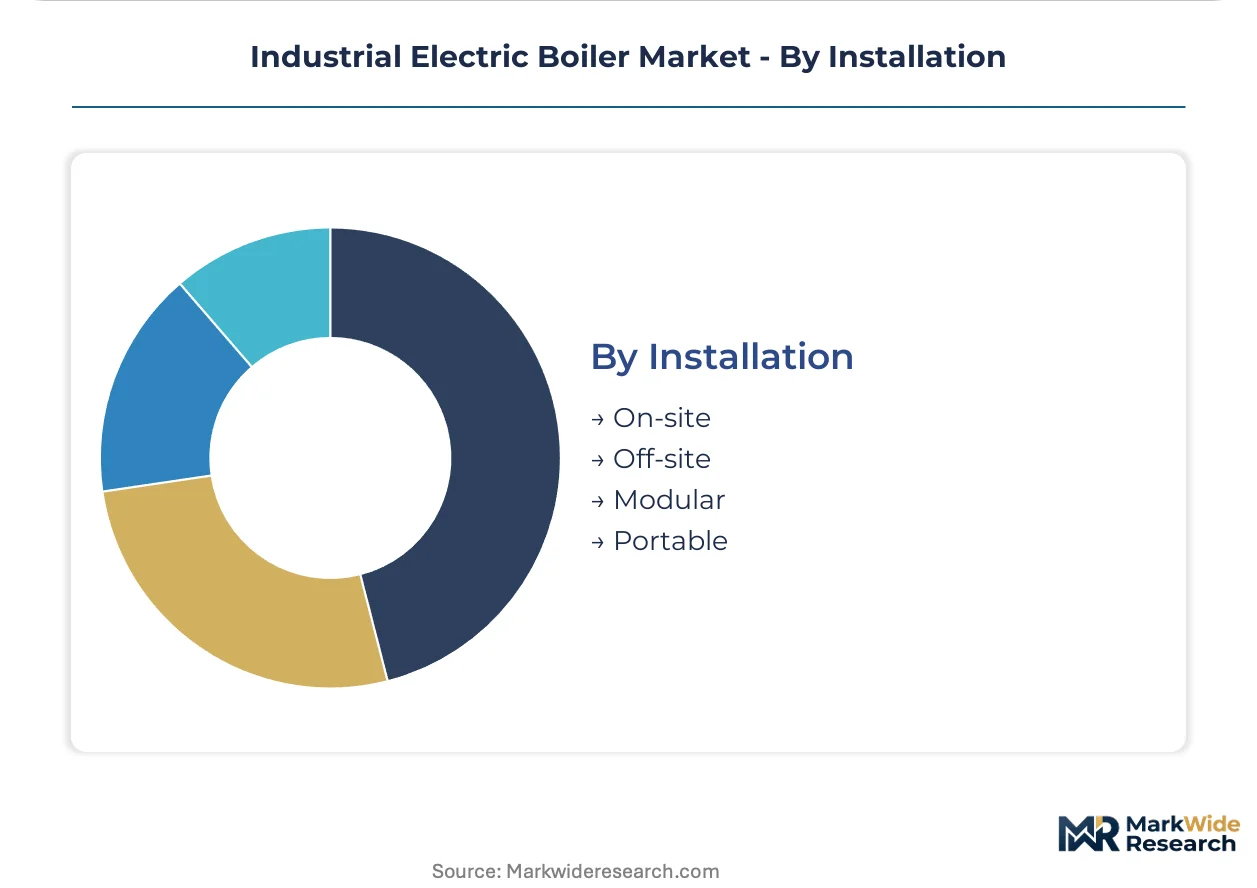
Installation:
Deployment modality shapes project timelines, capital structure, and operational risk allocation between owners and OEMs.
- On-site:Traditional stick-built installation with permanent electrical infrastructure and custom piping integration. German engineering-intensive clusters favor on-site construction for above-1000 kW systems where SCADA integration complexity demands specialized commissioning.
- Modular:Pre-fabricated skid-mounted systems reduce field construction duration and standardize quality control. Dutch food processors specify modular packages for phased capacity expansion with performance-guaranteed steam supply contracts.
- Off-site:Centralized thermal generation with distribution to multiple facilities.
- Portable:Trailer-mounted units provide temporary capacity for maintenance outages or seasonal demand spikes.
On-site installation commands the established base. Modular deployment shows the steepest expansion as energy-as-service contracts gain share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea grid interconnect underwrites Northern Europe's electrification trajectory, while the Trans-European Networks for Energy (TEN-E) corridors channel investment toward industrial decarbonization clusters. These transmission assets concentrate electric boiler deployment in manufacturing corridors with surplus renewable capacity.
Germany
Automotive paint-curing lines and chemical processing clusters in North Rhine-Westphalia drive 301-600 kW resistive unit specifications. The EU F-Gas Regulation mandates refrigerant phaseout timelines that accelerate boiler electrification in Ludwigshafen's chemical corridor. Engineering-intensive manufacturers in Baden-Württemberg specify horizontal configurations for 24-hour continuous operations.
Netherlands
Dairy pasteurization and cheese production facilities prioritize clean-steam electrode systems for batch-cycle variability. The country's carbon-accounting mandates under the EU Green Deal framework outpace neighboring jurisdictions. Food processors in Friesland adopt modular skid-mounted packages with performance-guaranteed steam supply contracts.
Sweden
Municipal utilities specify above-1000 kW electrode systems for district heating networks that absorb renewable electricity surges. Lifecycle carbon methodologies under the national environmental code favor electric thermal systems over biomass alternatives. Grid-balancing services in Stockholm's metropolitan district anchor megawatt-scale deployment.
Poland
Meat processing smokehouses and cooking operations adopt 301-600 kW units as EU F-Gas compliance deadlines approach. Rural industrial parks face transformer infrastructure gaps that constrain megawatt-scale deployment. Silesian manufacturing corridors concentrate mid-capacity resistive boiler adoption for heat-treatment applications.
United States
EPA emissions standards for industrial sources redirect capital toward electric steam systems in chemical processing clusters along the Gulf Coast. Pharmaceutical sterilization facilities in New Jersey and North Carolina specify electrode configurations for cGMP compliance. The Inflation Reduction Act's clean energy tax credits accelerate facility retrofits in Texas petrochemical corridors.
Industrial Electric Boiler Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in heating element and control module supply. The vendor base stratifies between diversified industrial conglomerates with energy-systems portfolios and dedicated boiler OEMs with installed-base service networks. Two strategic archetypes dominate: integrated thermal-platform suppliers leveraging heat-pump convergence, and aftermarket-focused specialists anchoring long-term service relationships. Competitive moves concentrate on energy-as-service contract structures and predictive maintenance platform deployment.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries occupies a position exemplifying large-scale thermal power integration into industrial steam applications. Bosch Thermotechnology and Bosch Industriekeller represent the integrated-platform archetype, leveraging combined heat-pump and boiler portfolios. Cleaver-Brooks anchors the installed-base specialist tier, sustaining customer relationships through aftermarket service contracts. PARAT Halvorsen AS exemplifies the Nordic engineering-intensive fabricator archetype serving maritime and industrial clusters.
| Leading Market Players |
|---|
| Chromalox |
| Mitsubishi Heavy Industries |
| Bosch Thermotechnology |
| Thermax |
| Babcock & Wilcox Enterprises |
| Viessmann Climate Solutions |
| PARAT Halvorsen AS |
| Bosch Industriekessel |
| Cleaver-Brooks |
| Others |
Supply Flow & Price Mechanics
Copper and nickel price volatility determines both margin compression in resistive heating element manufacturing and the geographic relocation of component sourcing toward Nordic supply chains with captive metal processing. This input-cost instability widens pricing spreads between premium electrode systems and standard resistive configurations while forcing OEMs to restructure supplier portfolios around long-term offtake agreements rather than spot-market procurement.
Pricing Analysis
Volume-discount tiering structures separate megawatt-scale district heating contracts from mid-capacity food processing installations, with pricing stratifying across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Premium electrode configurations with EMA-validated clean-steam documentation command substantial markups over standard resistive units in pharmaceutical applications. Cost compression in the mid-capacity 301-600 kW segment is intensifying because Polish and Romanian meat processors face simultaneous carbon-compliance deadlines and transformer infrastructure constraints. Food and beverage buyers exhibit the highest price sensitivity due to thin operating margins in commodity dairy and brewing operations, while pharmaceutical sterilization facilities prioritize purity documentation over unit economics.
Supply Chain Analysis
Upstream feedstock concentration for resistive heating elements centers on German and Finnish copper alloy processors, with electrode boiler manufacturing drawing from Swedish and Norwegian stainless steel fabricators specialized in high-purity pressure vessels. Nickel-chromium resistance wire, ceramic insulation cores, and precision-machined electrode assemblies constitute the critical component triad. Single-source vulnerability runs through Ukrainian titanium sponge supply for corrosion-resistant electrode coatings, disrupted by regional conflict logistics. Distribution runs through engineering-direct channels rather than traditional HVAC distributors, with Bosch Thermotechnology and Cleaver-Brooks maintaining specification control through integrated service arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial electric boiler market tracks a cyclical recovery pattern anchored to EU F-Gas Regulation compliance deadlines that trigger replacement waves across chemical processing and food manufacturing clusters every regulatory cycle.
For Market Incumbents: Harden installed-base retention through predictive maintenance platform deployment that locks in aftermarket revenue streams independent of new equipment cycles. Deepen backward integration into certified low-GWP insulation material supply chains to compress ECHA REACH compliance timelines by 8-14 months. Prioritize electrode technology R&D to collapse the cost-performance gap with resistive systems before margin compression accelerates in life-science end-uses. For New Entrants and Emerging Players: Pursue modular skid-mounted system opportunities in Dutch and Danish food processing corridors where energy-as-service contracting concentrates procurement authority away from traditional distributor channels. Target Polish meat processing smokehouse applications in the 301-600 kW range as EU F-Gas deadlines approach and transformer gaps constrain incumbent megawatt-scale deployment. Lead with performance-guaranteed steam supply agreements featuring uptime penalties to bypass capital-purchase approval cycles. For Investors and Strategic Acquirers: EU CBAM implementation reshapes the acquisition landscape by creating competitive advantage premiums for electric boiler operators serving export-oriented European manufacturers. Five-to-ten year viability favors platform integrators with combined heat-pump and boiler portfolios over pure-play resistive specialists facing electrode technology disruption. Target Nordic engineering-intensive fabricators with maritime and industrial cluster relationships. Monitor Swedish grid-balancing service contract awards as the inflection signal for megawatt-scale electrode system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-GWP Components | ECHA REACH pre-certification compresses product development cycles for pan-European compliance. |
| Electrode Technology Licensing | Swiss and Belgian pharmaceutical sterilization facilities drive clean-steam specification migration. |
| Energy-as-Service Contract Expansion | Dutch food processors favor 10-year performance-guaranteed steam supply with uptime penalties. |
| Modular Skid-Mounted System Scale-Up | Phased capacity expansion aligns with Polish transformer infrastructure constraints in rural industrial parks. |
| Predictive Maintenance Platform Deployment | German chemical processors prioritize 24-hour continuous operation uptime over capital cost premiums. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across German chemical processing and Dutch food manufacturing clusters. Secondary validation drew from ECHA REACH regulatory filings, EU F-Gas Regulation implementation timelines, customs and trade data on copper and nickel alloy imports, and SEC 10-K disclosures from diversified industrial conglomerates with energy-systems portfolios. Bottom-up capacity installation tracking and top-down macroeconomic overlay were triangulated to reconcile divergent data sources.
Calibration against historical electrification adoption curves in district heating and chemical processing anchored the projection framework across the analysis window. Segmentation dimensions modeled include product configuration geometry, steam purity requirements, power rating tiers, and installation modality. CAGRs were derived from regression analysis of facility retrofit pipelines against regulatory compliance deadlines, incorporating grid-decarbonization timeline assumptions and lifecycle carbon accounting methodology shifts favoring electric thermal systems.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, copper and nickel spot markets, or transformer infrastructure investment rates would shift the trajectory. Forecasts reflect documented assumptions regarding EU F-Gas phaseout adherence and national grid-decarbonization schedules. Cross-checking against IEA industrial electrification pathway benchmarks and national utility capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Underfloor Heating Market