
 Commercial Kitchen Ventilation System Market | 2026-2036
Commercial Kitchen Ventilation System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Kitchen Ventilation System Market Analysis
Stainless steel is expanding its share in commercial kitchen ventilation fabrication as coated carbon steel faces cost volatility and corrosion liability in high-grease environments. Halton Group Oy Ltd leverages proprietary Capture Jet technology to sustain premium positioning in European foodservice infrastructure. Greenheck Fan Corp anchors North American supply through extensive domestic manufacturing networks. Daikin Industries Ltd competes on integrated HVAC-ventilation platforms that combine climate control with exhaust management.
Commercial kitchen ventilation systems are engineered assemblies comprising grease filters, exhaust fans, ductwork, and fire suppression interfaces designed to capture, contain, and expel airborne contaminants, heat, and moisture generated during food preparation. These systems typically operate at air velocities between 1,500 and 2,500 feet per minute at the hood face to maintain capture efficiency over cooking surfaces while minimizing energy losses from conditioned air evacuation. Canopy hoods dominate installed base volumes due to universal compatibility with line-cooking configurations across restaurant and catering formats. Retrofit installations represent the fastest-growing installation type segment as aging foodservice infrastructure faces escalating fire code enforcement and energy compliance deadlines.
The US Environmental Protection Agency and Department of Energy jointly shape product efficiency mandates through commercial kitchen appliance standards, while the National Fire Protection Association's NFPA 96 governs grease duct construction and cleaning protocols that directly dictate system specification. The European Union's Ecodesign Directive and F-Gas Regulation progressively constrain refrigerant and energy profiles in integrated ventilation-climate systems. Stakeholders must monitor evolving municipal electrification ordinances in major metropolitan zones that increasingly prohibit gas-fired makeup air units, forcing equipment portfolio recalibration toward all-electric architectures.
Market Dynamics
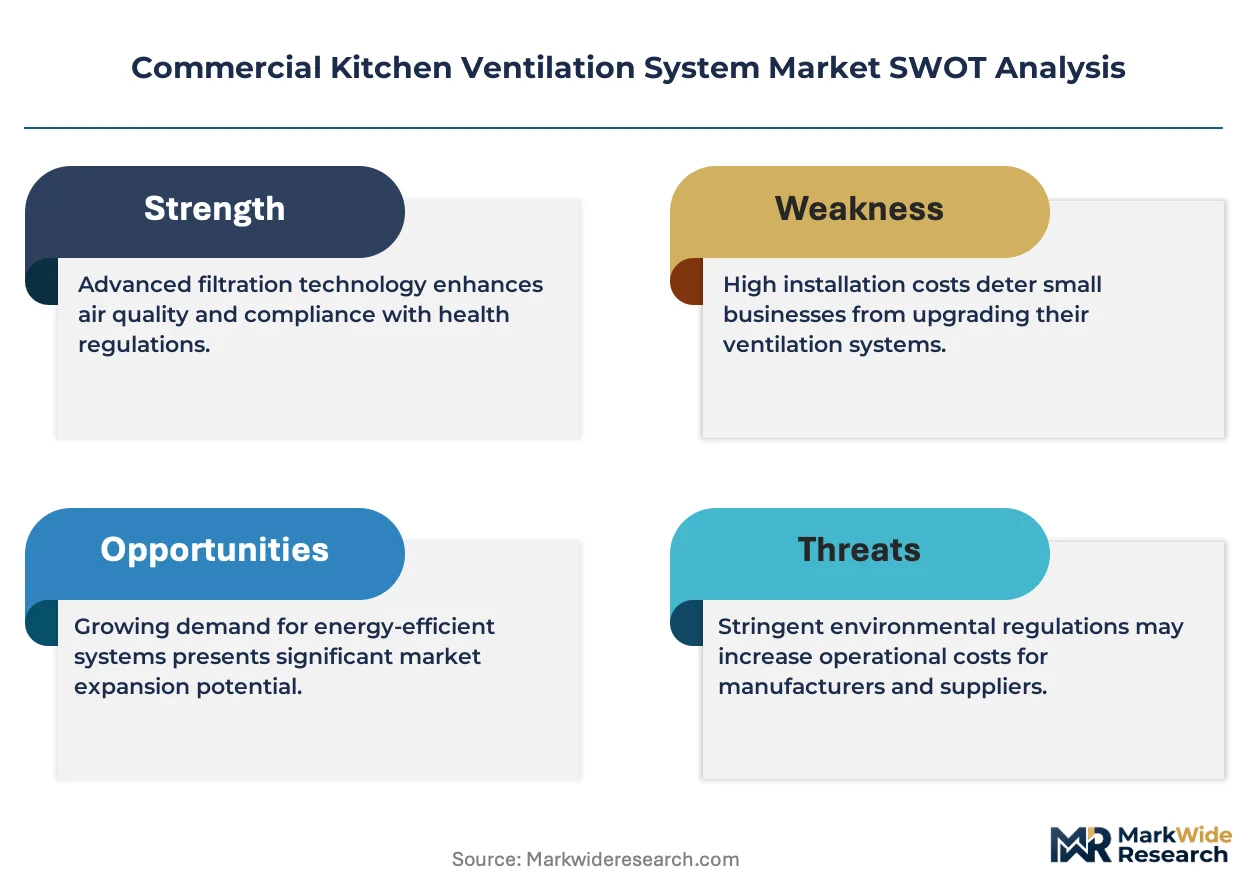
Variable-speed exhaust technologies are rewriting equipment procurement criteria as the US Department of Energy's appliance efficiency standards force manufacturers to abandon constant-volume fan architectures. This single technical mandate cascades through specification sheets, installer training, and retrofit economics across foodservice infrastructure.
Growth Catalysts
- NFPA 96 enforcement tightening:Municipal fire code inspections in US metropolitan zones are accelerating replacement cycles for aging grease duct systems that fail modern construction standards.
- Cloud kitchen proliferation:India's metropolitan hospitality clusters are generating concentrated demand for compact, high-throughput hood systems optimized for delivery-only operations.
- Stainless steel fabrication dominance:Coated carbon steel's corrosion liability in high-grease environments is pushing specification toward corrosion-resistant alloys with lower lifecycle maintenance.
Market Restraints
- Electrical infrastructure retrofit costs:All-electric makeup air unit mandates in electrifying municipalities require panel upgrades and service capacity expansion that strain operator capex.
- Specialized installation labor scarcity:Certified kitchen exhaust technicians capable of integrating fire suppression interfaces are concentrated in legacy foodservice hubs, limiting deployment velocity in emerging markets.
- Supply concentration in Southeast Asian steel:Raw material sourcing for hood fabrication faces geographic concentration risk from regional mill capacity constraints.
Strategic Opportunities
- Integrated HVAC-ventilation platforms:Climate control and exhaust management convergence creates specification openings for manufacturers with dual competency in thermal and air quality systems.
- EU F-Gas Regulation alignment:Refrigerant-constrained ventilation-climate systems position early adopters for preferential treatment in European public procurement frameworks.
- Quick-service restaurant chain standardization:Southeast Asian expansion programs seek unified equipment platforms across multi-country footprints, favoring suppliers with regional service networks.
Industry Challenges
- Legacy gas-fired infrastructure stranding:Operators with recently installed makeup air units face accelerated obsolescence as municipal electrification ordinances prohibit their continued deployment.
- Capture efficiency certification complexity:Laboratory test protocols for hood face velocity performance lack harmonization across jurisdictions, forcing redundant validation for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Kitchen Ventilation System Market |
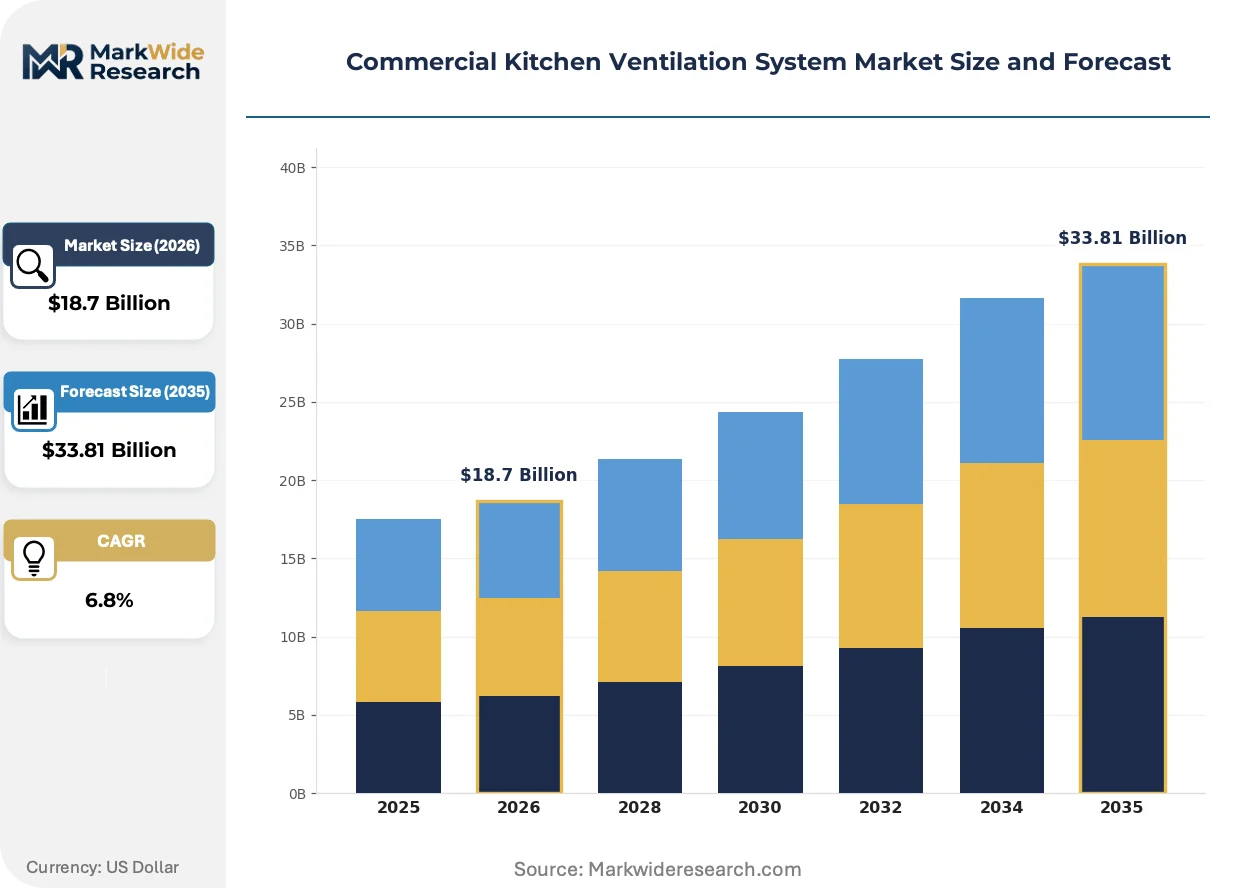
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Canopy Hoods, Wall-Mounted Hoods, Downdraft Hoods, Ceiling-Mounted Hoods Distribution Channel: Direct Sales, Distributors, Online Retail, Retail Outlets End User: Restaurants, Cafes, Fast Food Chains, Catering Services Installation Type: New Installations, Retrofits, Custom Installations, Standard Installations |
| Companies Covered | Halton Group Oy Ltd, Systemair AB, Captive Aire Systems Inc., The Middleby Corp., Dover Corp., Greenheck Fan Corp., Illinois Tool Works Inc., Melink Corp., Daikin Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Kitchen Ventilation System Market Emerging Trajectories
Commercial kitchen ventilation is undergoing platform-level transformation as energy compliance, fire safety digitization, and operator labor models converge on equipment architecture decisions. Three forces are actively restructuring competitive position.
Capture Jet technology is rewriting hood design economics by reducing required exhaust airflow volumes through targeted velocity augmentation at the capture zone. Quick-service chains in European markets are specifying these systems to minimize conditioned air losses and utility operating costs. The technology is compressing the performance gap between standard canopy hoods and premium island configurations, enabling specification downgrade without efficiency sacrifice.
The US Environmental Protection Agency's commercial kitchen appliance standards are mandating fan efficacy thresholds that eliminate single-speed motor architectures from new installations. Manufacturers are responding with electronically commutated motor platforms and demand-controlled ventilation logic. Full-service restaurants with variable cooking loads are the primary adoption segment, as their intermittent peak usage patterns maximize variable-speed energy savings.
Cloud kitchen operators are consolidating procurement authority at the portfolio level rather than individual site level, shifting vendor relationships toward enterprise service agreements with standardized maintenance protocols. Equipment suppliers are unbundling installation from ongoing filter exchange and duct cleaning services to align with this centralized buying pattern. This behavioral shift is most pronounced in Indian and Southeast Asian metropolitan zones where delivery-aggregator-backed kitchen networks are scaling fastest.
Commercial Kitchen Ventilation System Market Segmentation
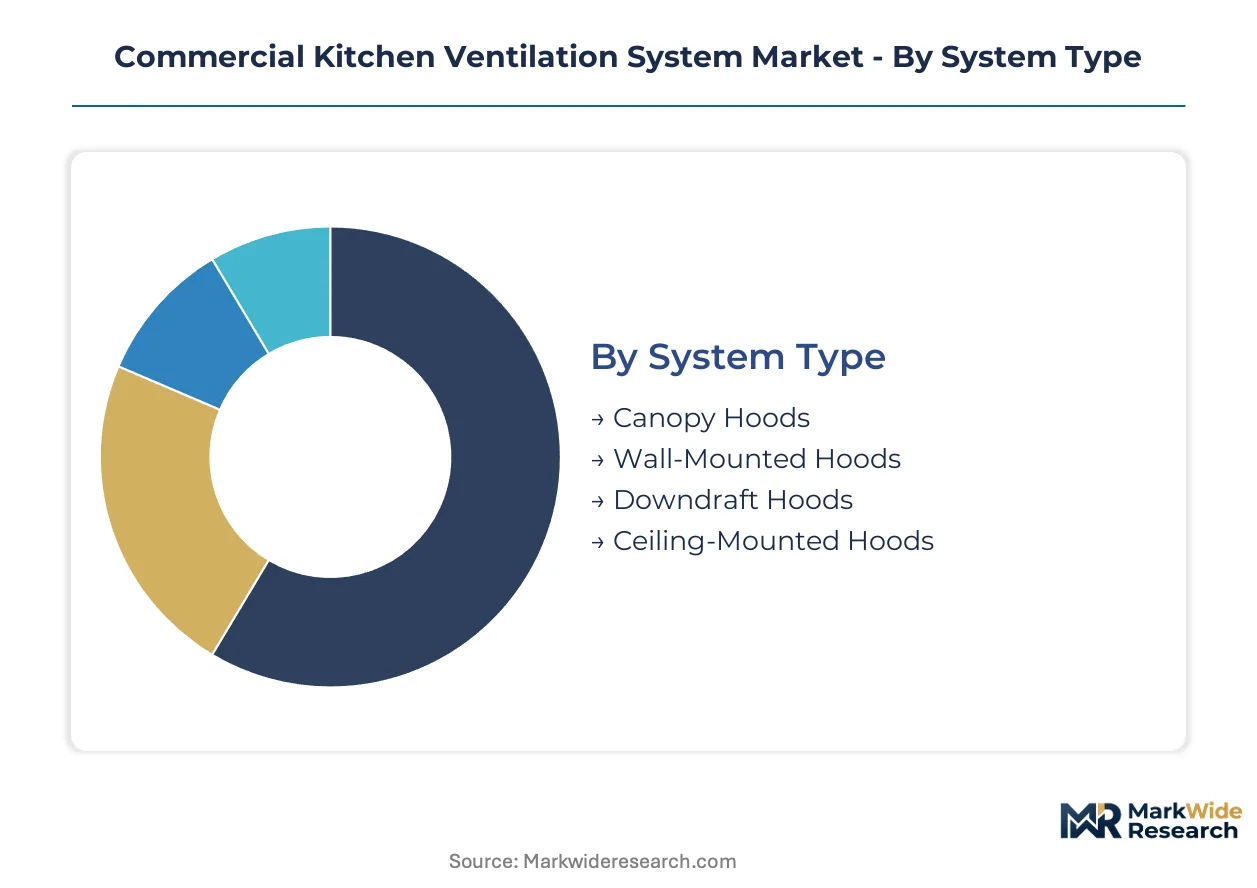
Commercial kitchen ventilation procurement varies sharply by operational scale and regulatory environment. Equipment specification differs fundamentally between high-volume chain rollouts and independent operator retrofits. Understanding these divides reveals where margin concentrates and where volume flows.
System Type:
Customization spans from standardized canopy formats to site-engineered island configurations, with specification depth correlating directly to kitchen layout complexity and local fire code stringency.
- Canopy Hoods:These wall-mounted or island configurations with vertical front faces dominate installed volumes across line-cooking operations. Demand concentrates in India's cloud kitchen clusters and Southeast Asian quick-service expansions, where standardized footprints enable rapid deployment and uniform maintenance protocols.
- Wall-Mounted Hoods:Engineered for single-battery installations against kitchen perimeters, these systems offer lower material costs than island equivalents. US metropolitan retrofits favor these units where existing grease duct infrastructure limits layout flexibility, though Capture Jet technology is narrowing performance gaps with premium alternatives.
- Downdraft Hoods:Recessed ventilation drawing contaminants downward at cooking surface level suits front-of-house exhibition kitchens.
- Ceiling-Mounted Hoods:Suspended configurations enable open-plan kitchen designs without vertical obstructions.
Most installed capacity flows through Canopy Hoods. Expansion is steepest in Ceiling-Mounted Hoods.
Distribution Channel:
Channel selection tracks project scale and technical integration requirements, with complex fire suppression interfaces favoring direct manufacturer relationships over transactional procurement.
- Direct Sales:Manufacturer-direct relationships dominate large-chain rollouts requiring unified service agreements across multi-site portfolios. Southeast Asian quick-service expansion programs specify this channel to secure regional spare parts availability and standardized technician training.
- Distributors:Local inventory holding and installation coordination make this channel essential for independent restaurants and retrofit timelines. India's metropolitan hospitality clusters rely on distributor networks for rapid hood system procurement where cloud kitchen operators prioritize speed-to-operation over capital optimization.
- Online Retail:Standardized low-capacity units for replacement and small-format operations.
- Retail Outlets:Immediate availability for emergency replacements and small commercial kitchens.
Volume concentrates through Distributors. Direct Sales is climbing the fastest as enterprise procurement centralizes.
End User:
User category determines duty cycle intensity, grease loading profiles, and regulatory exposure, with full-service formats facing distinct compliance burdens from delivery-only operations.
- Restaurants:Full-service establishments with variable cooking loads drive demand for variable-speed exhaust technologies. The US Department of Energy's appliance efficiency standards are forcing these operators toward electronically commutated motor platforms that match fan output to real-time cooking activity.
- Fast Food Chains:Standardized menus and predictable throughput enable optimized hood sizing and unified equipment platforms. Southeast Asian expansion programs specify these systems for cross-border deployment with centralized maintenance protocols.
- Cafes:Limited cooking equipment and lower grease generation permit compact hood configurations.
- Catering Services:Mobile and temporary installation requirements favor modular, rapidly deployable ventilation.
Fast Food Chains account for the largest installed base. Cloud kitchen proliferation is pushing Restaurants toward the steepest specification upgrade cycle.
Installation Type:
Installation complexity ranges from drop-in replacements to engineered integration with existing building systems, with regulatory deadlines accelerating retrofit activity.
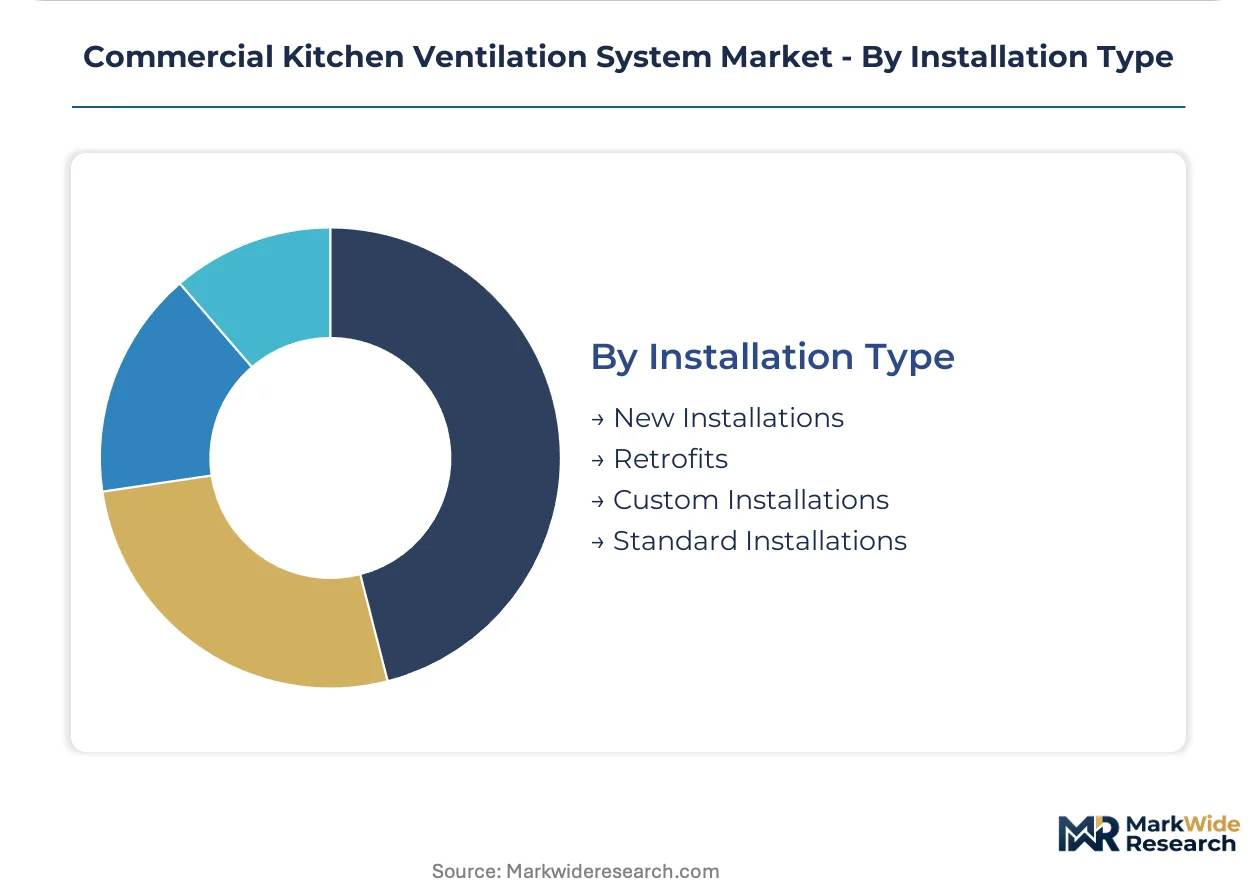
- Retrofits:Aging grease duct infrastructure facing escalating NFPA 96 enforcement drives replacement demand. US metropolitan fire code inspections are accelerating cycles for systems failing modern construction standards, particularly where municipalities prohibit continued operation of non-compliant gas-fired makeup air units.
- New Installations:Greenfield construction enables optimized system sizing and integrated HVAC-ventilation platforms. Indian cloud kitchen rollouts specify these installations for delivery-aggregator-backed kitchen networks scaling in metropolitan zones.
- Custom Installations:Site-specific engineering for non-standard kitchen layouts and heritage building constraints.
- Standard Installations:Pre-engineered packages for typical footprints with minimal field modification.
Retrofits dominate current procurement volume. New Installations show the strongest forward momentum as cloud kitchen construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's metropolitan hospitality clusters anchor procurement velocity for commercial kitchen ventilation systems. Cloud kitchen proliferation across Mumbai, Bangalore, and Delhi-NCR concentrates demand for compact hood configurations. Regulatory divergence across major economies is fragmenting equipment specification standards.
United States
Full-service restaurant retrofits drive specification upgrades for variable-speed exhaust technologies. The Environmental Protection Agency's commercial kitchen appliance standards mandate fan efficacy thresholds that eliminate single-speed motor architectures. NFPA 96 enforcement in Chicago, New York, and Los Angeles accelerates replacement cycles for aging grease duct infrastructure.
India
Cloud kitchen operators in Mumbai, Bangalore, and Delhi-NCR generate concentrated demand for high-throughput hood systems. The Bureau of Indian Standards governs equipment safety certification for commercial foodservice infrastructure. Delivery-aggregator-backed kitchen networks are scaling fastest in these metropolitan zones, favoring standardized maintenance protocols.
Germany
Integrated HVAC-ventilation platforms gain traction in full-service and institutional kitchen formats. The EU F-Gas Regulation constrains refrigerant profiles in climate-integrated exhaust systems. Industrial fabricators in North Rhine-Westphalia and Bavaria supply premium canopy configurations for European foodservice rollouts.
China
Quick-service restaurant chain expansion programs standardize equipment procurement across multi-province footprints. The Ministry of Ecology and Environment shapes air quality compliance frameworks for commercial exhaust discharge. Manufacturing clusters in Guangdong and Zhejiang provinces supply hood fabrication for domestic and Southeast Asian markets.
Southeast Asia
Quick-service restaurant chains across Thailand, Vietnam, and Indonesia expand commercial kitchen footprints with unified equipment platforms. National building codes in Singapore and Malaysia mandate fire suppression integration in grease exhaust systems. Bangkok and Jakarta metropolitan zones concentrate procurement for high-volume canopy hood deployments.
Commercial Kitchen Ventilation System Market Vendor Landscape
Global majors compete with regional champions across technology integration and service network depth. The market structures around three tiers: integrated HVAC-ventilation conglomerates, specialized exhaust fabricators with captive distribution, and regional component assemblers serving price-sensitive procurement. Dominant competitive moves include geographic expansion through distributor acquisition and technology licensing for variable-speed control platforms.
Among European specialists, Halton Group Oy Ltd and Systemair AB exemplify the technology-differentiated tier, while Captive Aire Systems Inc. anchors North American regional service density. These three occupy positions that illustrate how fabrication competency, distribution control, and regulatory compliance capabilities define competitive segmentation across procurement channels.
| Leading Market Players |
|---|
| Halton Group Oy Ltd |
| Systemair AB |
| Captive Aire Systems Inc. |
| The Middleby Corp. |
| Dover Corp. |
| Greenheck Fan Corp. |
| Illinois Tool Works Inc. |
| Melink Corp. |
| Daikin Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Stainless steel coil costs cascade through commercial kitchen ventilation fabrication, with 304-grade alloy pricing separating premium European canopy systems from Southeast Asian quick-service rollouts. Labor-intensive Capture Jet assembly and certified fire suppression integration anchor the upper tier, while standardized wall-mounted hoods compete on mill-direct material sourcing and distributor markups.
Pricing Analysis
Input-cost pass-through from nickel volatility and energy-intensive stainless processing shapes tiered pricing across the market. Premium-mid-economy pricing differentiation rests on UL 710 certification tier and after-sales service bundling, with certified kitchen exhaust technician scarcity inflating installation quotes in emerging markets. Pricing pressure stems from cloud kitchen operators consolidating procurement at portfolio level and unbundling installation from ongoing maintenance. Fast-food chains exhibit lowest price sensitivity due to standardized multi-site agreements, while independent restaurants face acute budget constraints on retrofit timelines.
Supply Chain Analysis
Domestic-content mandates in India's Bureau of Indian Standards certification and US Buy American provisions for federal foodservice contracts are reshaping sourcing patterns toward localized fabrication. Hood manufacturing draws from stainless steel mills in China, India, and Indonesia, with electronic motor drives and fire suppression interfaces sourced from Germany and Japan. Single-source vulnerability concentrates in Southeast Asian steel coil supply, where regional mill capacity constraints create delivery uncertainty. Distribution runs through captive distributor networks for independent operators and direct manufacturer relationships for chain rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial kitchen ventilation offers margin expansion through variable-speed technology premiumization and service revenue unbundling, with cloud kitchen centralization shifting buyer power toward enterprise-scale suppliers.
For Market Incumbents: To counter municipal electrification ordinances stranding gas-fired makeup air inventory, accelerate EC motor platform certification and secure spare parts warehousing in Southeast Asian expansion markets. Backward integration into stainless fabrication in India and Vietnam insulates against regional mill volatility while satisfying local-content requirements for public procurement. For New Entrants and Emerging Players: Begin with ceiling-mounted hood configurations for European exhibition kitchen retrofits, where open-plan design trends outpace incumbent product development cycles. Target India's tier-2 cloud kitchen clusters outside Mumbai and Bangalore, where delivery-aggregator networks scale fastest and distributor relationships remain unsettled. Lead with standardized maintenance protocol subscriptions to align with portfolio-level procurement centralization. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor networks with captive technician certification programs because cloud kitchen operators prioritize speed-to-operation over capital optimization and will pay service premiums for guaranteed response times. Target mid-cap fabricators with Bureau of Indian Standards and UL dual certification capability. Watch NFPA 96 enforcement intensity in US metropolitan zones as the signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Technology Licensing | Electronically commutated motor platforms satisfy EPA fan efficacy mandates while opening premium pricing tiers. |
| Regional Distributor Acquisition | Captive technician networks in Southeast Asia secure quick-service chain rollout contracts with guaranteed service response. |
| Integrated HVAC-Ventilation Platform Development | Daikin and Greenheck demonstrate specification pull from full-service operators seeking unified climate-exhaust management. |
| Cloud Kitchen Enterprise Service Agreements | Portfolio-level procurement authority in India favors suppliers unbundling installation from filter exchange and duct cleaning. |
| EU F-Gas Regulation Alignment | Refrigerant-constrained ventilation-climate systems position early adopters for preferential treatment in European public procurement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with commercial kitchen equipment procurement directors, certified exhaust installation contractors, cloud kitchen portfolio managers, and fire suppression system integrators with secondary validation from EPA appliance efficiency filings, NFPA 96 code revision records, and Bureau of Indian Standards certification databases. Bottom-up unit economics from hood system deployments triangulated against top-down construction spending and foodservice permitting data.
Comparable historical periods anchored the projection horizon, with segmentation modeled across system type, installation category, end-user format, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated baseline volumes, incorporating cloud kitchen construction pipelines, municipal electrification ordinance adoption curves, and variable-speed technology substitution rates as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced revisions to US Department of Energy efficiency standards, abrupt nickel price shocks from supply disruptions, and pandemic-scale disruptions to foodservice demand. Forecasts reflect documented assumptions about regulatory enforcement continuity and material cost stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Hydronic Control Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Roof Insulation Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Roof Vents Market
HVAC Systems
Aeration System Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Ductless HVAC System Market