
 HVAC Insulation Market | 2026-2036
HVAC Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Insulation Market Intelligence
Energy performance contracting is hardening the link between material specification and long-term operational savings. This shift benefits specialized manufacturers like Rockwool International A/S, which leverages its expertise in non-combustible mineral wool. Saint-Gobain S.A. competes across a broad product spectrum, from fiberglass to high-performance foams. Meanwhile, Armacell International S.A. differentiates with its flexible elastomeric foam insulation for ductwork and piping.
HVAC insulation encompasses materials engineered to minimize thermal energy transfer within heating, ventilation, and air conditioning systems. These materials are rated by their thermal resistance, or R-value, with higher values indicating better insulating performance. Their primary purpose is to enhance system energy efficiency and prevent condensation. Mineral wool and fiberglass products continue to dominate the new construction segment, while foam board and spray foam find traction in retrofitting applications due to their application flexibility.
Global energy management standards like ISO 50001, coupled with national regulations such as the US EPA's building codes and the EU's Energy Performance of Buildings Directive, set minimum thermal performance requirements. These frameworks directly influence material selection and thickness specifications in both new and existing buildings. Manufacturers must now navigate the trade-offs between achieving higher thermal resistance, meeting stringent fire safety classifications, and providing materials with verifiable sustainability credentials.
Market Dynamics
The convergence of stringent building energy codes and non-combustibility standards is the primary force shaping the market. Regulations like the EU's Energy Performance of Buildings Directive (EPBD) compel higher R-values, while fire safety classifications favor mineral-based insulations over certain foams.
Growth Catalysts
- Energy Efficiency Mandates:The EU's F-Gas Regulation and US EPA building codes are tightening thermal performance requirements for HVAC systems. This directly drives demand for higher R-value insulation materials in both new construction and retrofits.
- Data Center Expansion:Proliferation of data centers, which require precise climate control and high energy consumption, creates substantial demand for high-performance insulation. This is particularly visible in clusters around Frankfurt, Germany and Ashburn, Virginia in the US.
- Mineral Wool Adoption:The inherent non-combustible properties of mineral wool are increasing its specification in commercial and industrial buildings. Its acoustic dampening qualities provide an additional benefit for occupied spaces, further supporting its use in ductwork.
Market Restraints
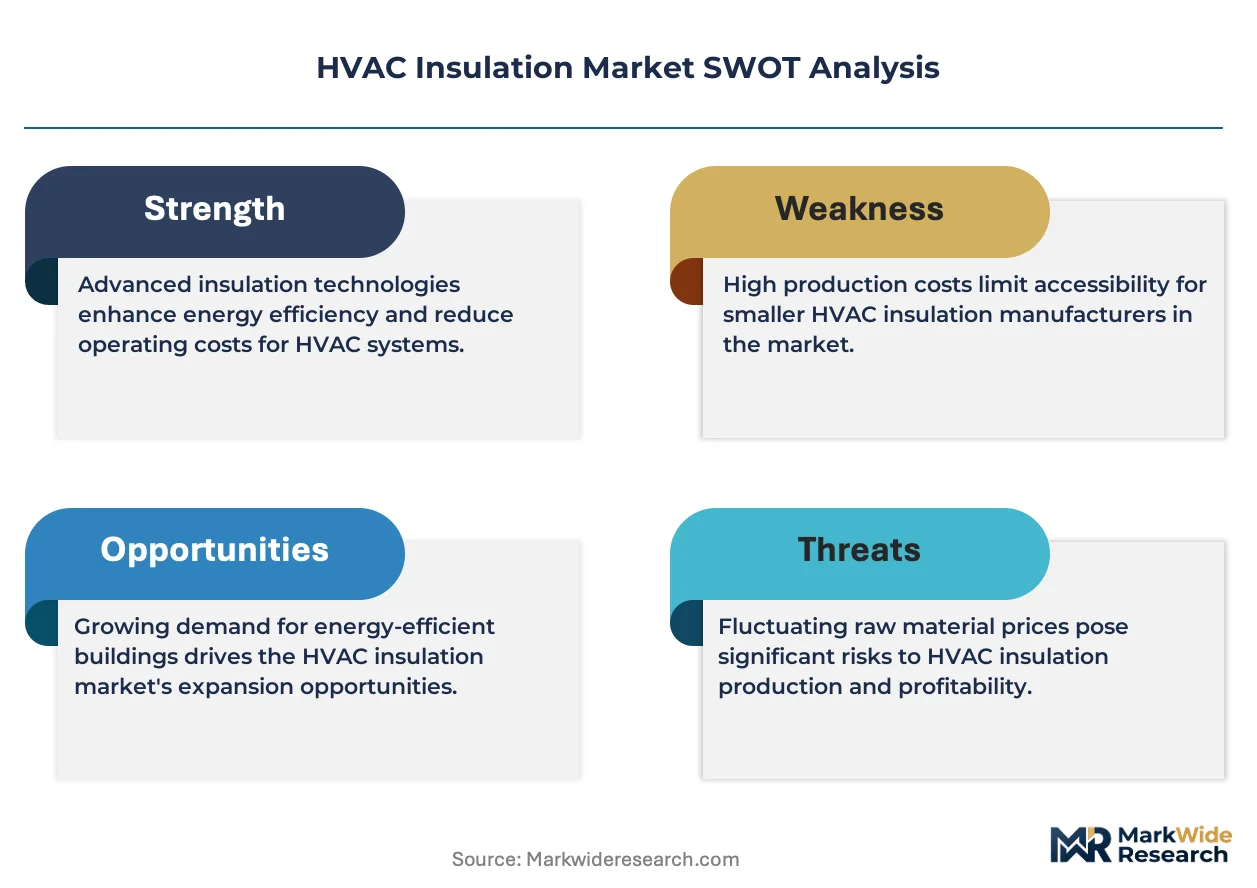
- Raw Material Volatility:The cost of key inputs for foam insulation, such as MDI and polyols, is subject to petrochemical market fluctuations. This price instability complicates project bidding and can erode manufacturer margins, especially for smaller producers.
- Alternative Cooling Technologies:The emergence of ductless mini-split systems and radiant heating/cooling reduces the total volume of ductwork requiring insulation. This substitution threat is most prominent in the residential and light commercial segments.
- Installation Skill Gaps:Proper installation of spray foam and complex flexible elastomeric foam systems requires specialized training. A shortage of certified installers can lead to performance issues and limit the adoption of these effective materials.
Strategic Opportunities
- Retrofitting in Eastern Europe:Countries like Poland and the Czech Republic present significant opportunities for retrofitting older building stock. EU funding tied to the Green Deal provides a financial mechanism for large-scale energy efficiency upgrades in these markets.
- Cryogenic and LNG Insulation:The expansion of liquefied natural gas (LNG) infrastructure requires specialized insulation capable of handling extreme cold. This creates a high-value niche for materials like cellular glass and polyisocyanurate foams designed for cryogenic applications.
- Aerogel Integration:Incorporating aerogel into insulation blankets and wraps offers superior thermal performance in a much thinner profile. This is ideal for space-constrained applications, such as retrofitting historic buildings or insulating complex mechanical systems.
Industry Challenges
- Complex Fire Safety Certification:Navigating the patchwork of fire safety standards, such as ASTM E84 in the US and EN 13501-1 in Europe, is a significant operational hurdle. Testing and certification processes are lengthy and costly for manufacturers introducing new materials.
- Recycling Infrastructure Deficiencies:A lack of established, scalable recycling streams for post-consumer fiberglass and foam insulation products presents a challenge. This limits manufacturers' ability to meet corporate sustainability goals and circular economy demands from specifiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Insulation Market |
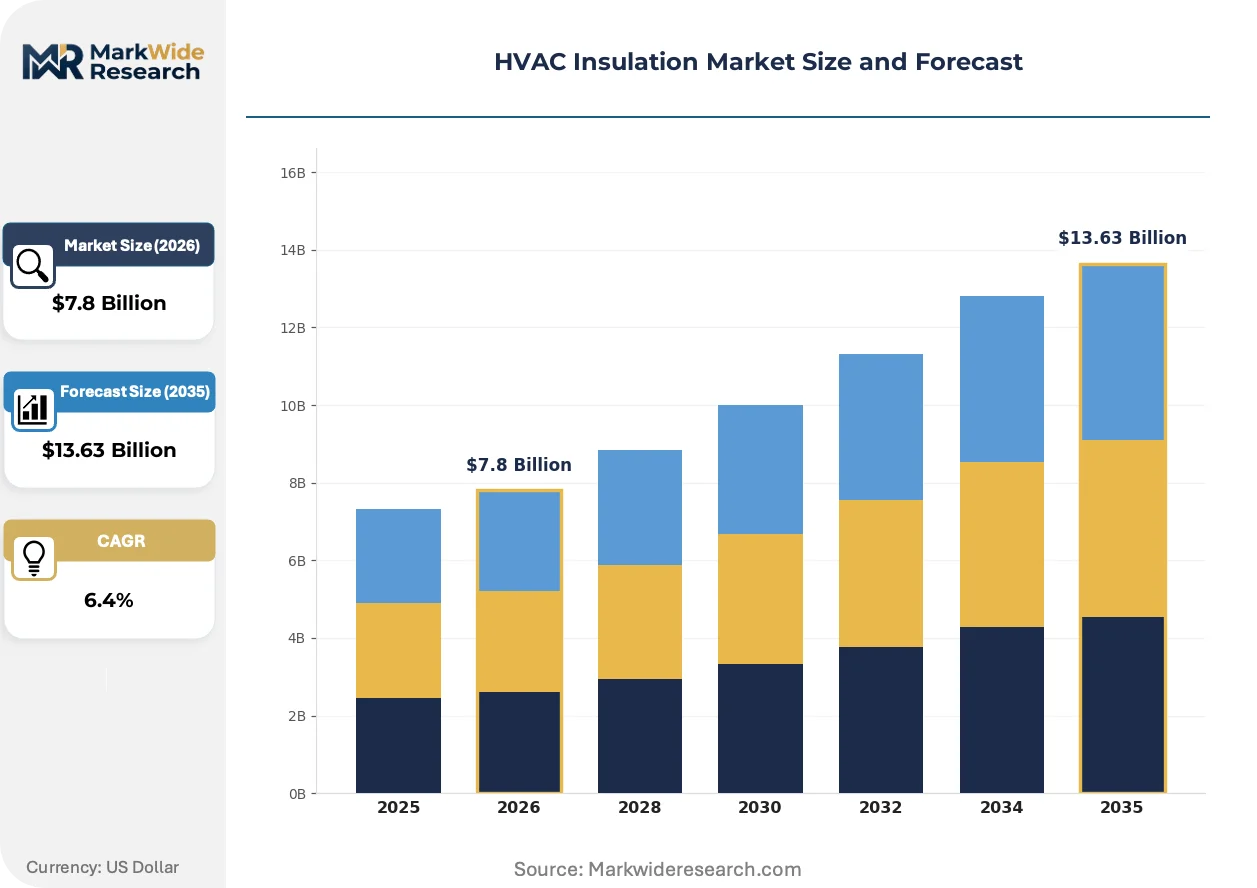
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Foam Board, Mineral Wool, Spray Foam Installation Method: New Construction, Retrofitting, DIY, Professional Installation End User: Residential, Commercial, Industrial, Institutional Thickness: 1 inch, 2 inches, 3 inches, 4 inches |
| Companies Covered | Rockwool International A/S, Johns Manville Corporation, Owens Corning Corporation, PPG Industries Inc., Armacell International S.A., Saint-Gobain S.A., Kingspan Group Plc., Xiamen Goot Advanced Material Co., Ltd., Knauf Insulation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Insulation Market Strategic Shifts & Innovations
Material science advancements are pushing HVAC insulation beyond simple thermal resistance toward multi-functional performance. The market is witnessing a clear pivot to materials that integrate fire safety, acoustic dampening, and verifiable sustainability credentials into a single product specification.
Flexible elastomeric foam offers closed-cell structures that provide excellent thermal efficiency and inherent vapor resistance, preventing condensation on cold pipes and ducts. Data centers and healthcare facilities are rapidly adopting this material for its clean, fiber-free composition and ease of installation. This technology is expanding into applications previously dominated by fiberglass, particularly in critical environments where moisture control and particulate shedding are primary concerns.
The global adoption of the ISO 50001 energy management standard is formalizing the link between insulation specification and long-term operational cost reduction. This framework requires organizations to systematically track energy performance, making the ROI of high-performance insulation more transparent and justifiable for facility managers. Industrial manufacturing and large commercial property management sectors are most affected, now prioritizing life-cycle cost analysis over initial material purchase price.
A move toward off-site prefabrication and modular construction methods is altering how insulation is specified and installed. This trend favors factory-applied insulation or pre-insulated ductwork systems over traditional on-site, manual application, reducing labor time and improving quality consistency. The shift is most visible in large-scale commercial projects in North America and Western Europe, where labor costs and project timelines are under intense scrutiny.
HVAC Insulation Market Segmentation
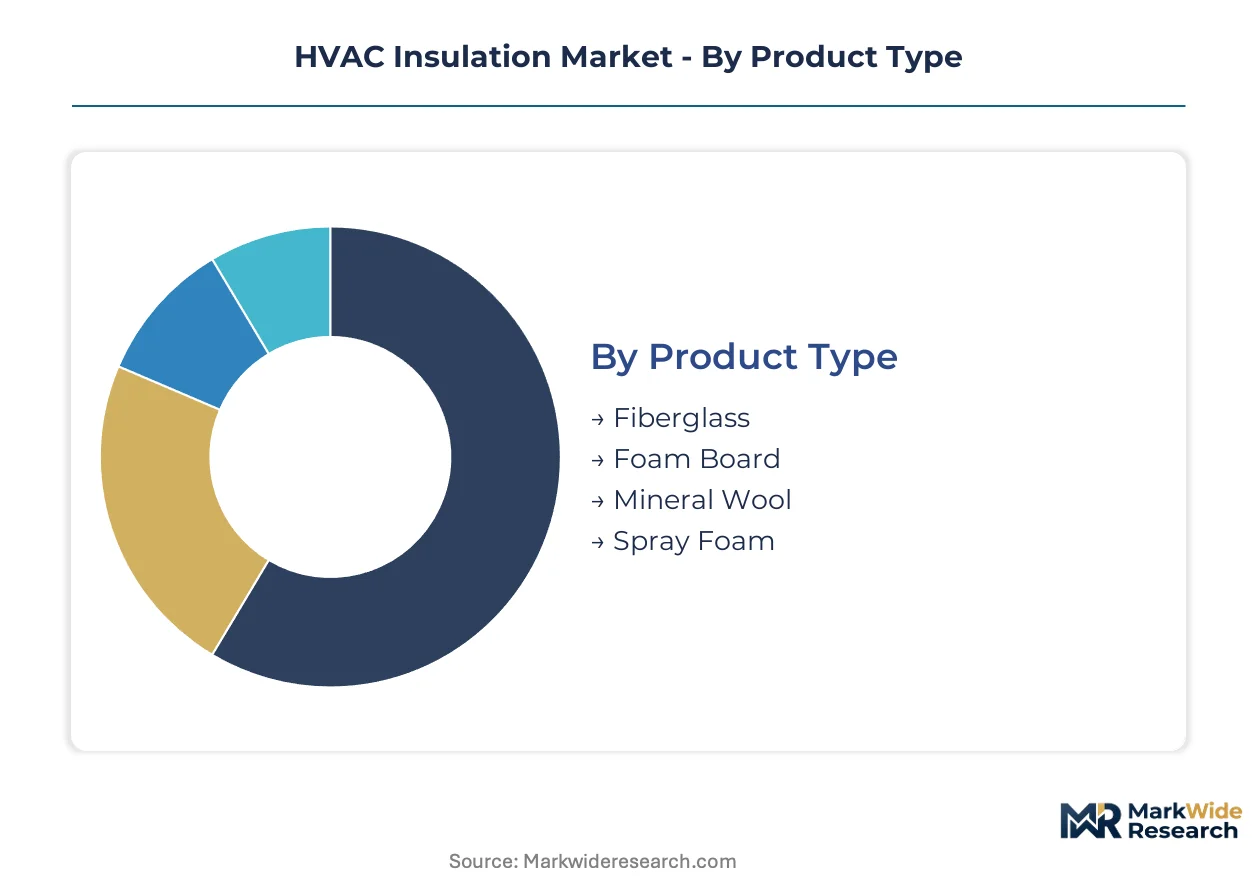
The HVAC insulation market segmentation provides a granular view of material preferences and application trends across diverse end-use sectors. Dissecting these categories reveals underlying demand drivers and technological shifts influencing product development and market dynamics. This analysis helps identify key growth pockets and strategic opportunities within the industry.
Product Type:
Material selection often hinges on specific project requirements and performance mandates, influencing both energy efficiency and safety classifications.
- Mineral Wool:This fibrous material, derived from molten rock or slag, offers inherent non-combustibility and excellent acoustic dampening properties. Demand concentrates in commercial and industrial buildings, driven by stringent fire safety classifications like EN 13501-1 and the need for sound attenuation in occupied spaces.
- Fiberglass:Composed of fine glass fibers, fiberglass insulation provides cost-effective thermal resistance and dominates the new construction segment. Its widespread use in residential and light commercial projects is supported by established manufacturing processes and ease of availability.
- Foam Board:Rigid insulation panels made from materials like polyisocyanurate or extruded polystyrene, offering high R-values in a compact form. It finds traction in retrofitting applications due to its ease of installation and structural rigidity.
- Spray Foam:An in-situ applied insulation, typically polyurethane, that expands to fill cavities and create an airtight seal. This material is increasingly specified for challenging retrofit projects and complex architectural designs requiring superior air barrier performance.
Mineral Wool leads on scale; Spray Foam leads on momentum.
Installation Method:
The chosen installation method significantly influences material selection, labor costs, and project timelines across various building types.
- New Construction:This segment involves integrating insulation during the initial building phase, often favoring traditional materials like fiberglass and mineral wool. Demand here is consistently driven by building codes and energy performance directives for new structures.
- Retrofitting:This process upgrades insulation in existing buildings to improve energy efficiency, frequently utilizing foam board and spray foam for their adaptability. Opportunities are expanding in regions like Eastern Europe, supported by EU Green Deal funding.
- DIY:Do-It-Yourself installations typically involve simpler, easier-to-handle insulation products for residential projects. This method is prevalent in smaller-scale home improvement tasks where professional labor costs are a consideration.
- Professional Installation:Specialized contractors apply complex insulation systems, including flexible elastomeric foams and advanced spray foams. A shortage of certified installers can limit the adoption of these high-performance materials in certain markets.
New Construction maintains the largest volume; Retrofitting exhibits the steepest expansion trajectory.
End User:
Distinct end-user segments exhibit varied insulation demands, shaped by operational requirements, climate control needs, and specific regulatory environments.
- Commercial:This sector includes offices, retail, and data centers, requiring high-performance insulation for precise climate control and energy efficiency. Data center expansion, particularly in regions like Frankfurt and Ashburn, drives significant demand for specialized solutions.
- Industrial:Manufacturing facilities and processing plants utilize robust insulation to manage extreme temperatures and reduce energy consumption in production processes. Global energy management standards like ISO 50001 formalize the need for high-performance materials here.
- Residential:Homeowners prioritize comfort and reduced energy bills, driving demand for cost-effective thermal insulation in walls, attics, and HVAC ducts. US EPA building codes influence material selection and R-value requirements in this segment.
- Institutional:Schools, hospitals, and government buildings require insulation that meets stringent fire safety, acoustic, and indoor air quality standards. These facilities often specify materials that contribute to a healthy and quiet indoor environment.
Commercial applications contribute the highest value; Industrial applications demonstrate rapid adoption of advanced solutions.
Thickness:
Insulation thickness directly impacts thermal resistance and overall system energy efficiency, with specifications driven by climate zones and performance targets.
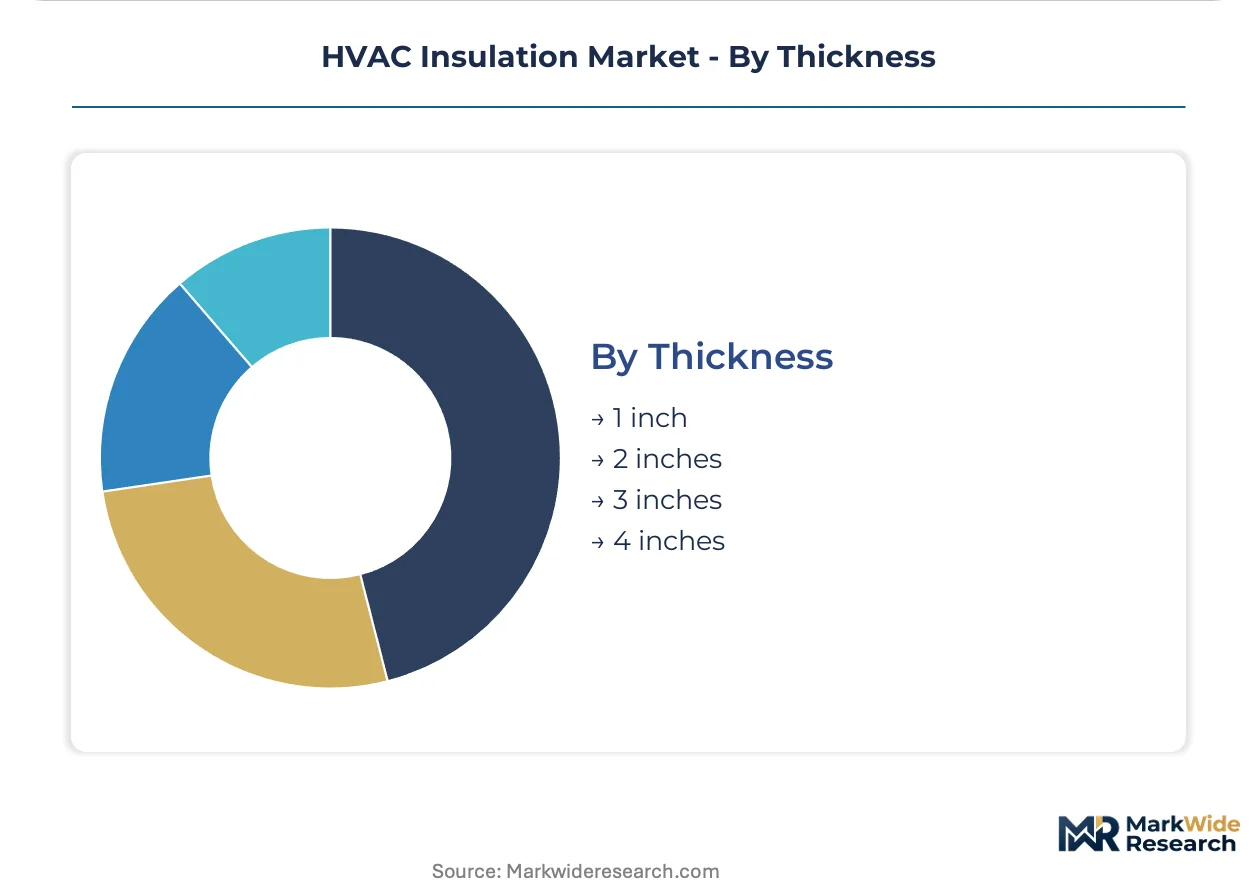
- 2 inches:A common thickness providing a foundational level of thermal performance suitable for many standard HVAC ductwork and piping applications. This thickness balances material cost with basic energy efficiency requirements.
- 4 inches:This thicker insulation offers enhanced thermal resistance, crucial for systems operating in extreme temperature environments or demanding high energy savings. It is increasingly specified for data centers and industrial processes requiring precise temperature control.
- 1 inch:Primarily used for less critical applications or where space constraints are significant, offering minimal thermal resistance. This thickness may be selected for condensation control rather than substantial energy savings.
- 3 inches:Provides an intermediate level of thermal performance, often chosen when balancing improved R-value with project budget and space availability. It offers a step up from thinner options without the bulk of maximum thickness.
2 inches represents a foundational segment; 4 inches addresses specialized performance needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States emphasizes energy efficiency through stringent building codes, Germany prioritizes non-combustibility in commercial construction. This divergence in regulatory focus shapes material demand and product innovation across global markets. Data center expansion and retrofitting initiatives are driving demand for high-performance HVAC insulation in both developed and emerging economies.
United States
Data center proliferation in the United States creates substantial demand for precise climate control solutions. The US EPA building codes mandate specific R-values, driving the specification of advanced insulation materials. Ashburn, Virginia, a major data center hub, demonstrates concentrated demand for high-performance elastomeric foams and thicker mineral wool solutions.
Germany
Industrial manufacturing clusters in Germany require robust insulation for process efficiency and fire safety. The EU's F-Gas Regulation pushes for higher system efficiency, directly impacting insulation choices in new builds and retrofits. The Frankfurt region, with its growing data center infrastructure, shows significant uptake of specialized HVAC insulation products.
Poland
Retrofitting older building stock in Poland offers significant opportunities for energy efficiency upgrades. EU funding tied to the Green Deal provides financial mechanisms for large-scale insulation projects. Urban centers like Warsaw and Krakow are seeing increased demand for foam board and spray foam in commercial and residential renovations.
China
Rapid urbanization and industrial expansion in China fuel demand for HVAC insulation in new construction projects. The country's national energy conservation policies encourage the use of higher R-value materials. Manufacturing hubs in the Yangtze River Delta region are adopting advanced insulation for industrial facilities and large commercial complexes.
India
Infrastructure development and a growing commercial sector in India are driving the need for efficient HVAC systems. The Bureau of Energy Efficiency (BEE) standards influence material selection for energy-efficient buildings. Major metropolitan areas like Mumbai and Delhi are experiencing increased specification of fiberglass and mineral wool for large-scale commercial and institutional projects.
HVAC Insulation Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. Large diversified material conglomerates often compete with niche players offering specialized solutions. The market exhibits archetypes ranging from broad-portfolio providers to highly specialized foam manufacturers. Companies are increasingly pursuing portfolio diversification and strategic partnerships to expand their market reach.
Specialists in high-performance materials often anchor the premium segment, providing solutions for critical applications. Rockwool International A/S exemplifies expertise in non-combustible mineral wool, catering to stringent fire safety requirements. Saint-Gobain S.A. represents a diversified approach, competing across a broad product spectrum, from fiberglass to high-performance foams. Armacell International S.A. occupies a position as a specialist in flexible elastomeric foam insulation for ductwork and piping, differentiating through application-specific innovation.
| Leading Market Players |
|---|
| Rockwool International A/S |
| Johns Manville Corporation |
| Owens Corning Corporation |
| PPG Industries Inc. |
| Armacell International S.A. |
| Saint-Gobain S.A. |
| Kingspan Group Plc. |
| Xiamen Goot Advanced Material Co., Ltd. |
| Knauf Insulation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private-equity-backed specialists in HVAC insulation often exhibit distinct supply behaviors, influencing pricing discipline across specific material segments. Their investment strategies directly shape production capacity and regional price stability.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard fiberglass and mineral wool products. Pricing for high-performance HVAC insulation often follows a value-based model, particularly for specialized solutions in data centers and industrial applications. Certification levels, such as specific fire safety classifications and R-value tiers, drive significant price differentiation. Raw material volatility for foam insulation inputs like MDI and polyols exerts upward pricing pressure on those segments. Residential and DIY buyers exhibit the highest price sensitivity, while commercial and industrial end-users prioritize long-term operational savings and performance.
Supply Chain Analysis
Domestic-content mandates in the European Union are reshaping sourcing strategies for HVAC insulation manufacturers. Global supply for mineral wool and fiberglass concentrates heavily in industrial clusters within Germany and China. Key raw material dependencies include molten rock and slag for mineral wool, glass fibers for fiberglass, and petrochemical derivatives like MDI and polyols for foam products. Commodity price volatility for these chemical inputs represents a structural supply chain risk. Distribution typically runs through specialized industrial distributors for commercial projects and large retailers for residential and DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC insulation market presents a geographic-arbitrage opportunity, particularly between Western European markets with stringent energy codes and Eastern European regions requiring extensive retrofitting. This differential stems from varying regulatory pressures and associated material costs.
For Market Incumbents:Deepen investment in material science R&D to develop multi-functional insulation integrating fire safety, acoustic dampening, and sustainability credentials. Expand certified installer networks, particularly for complex flexible elastomeric foam and spray foam systems, to counter installation skill gaps and ensure performance. Strengthen relationships with large commercial specifiers and data center operators to mitigate the threat from alternative cooling technologies. Pursue strategic partnerships for circular economy initiatives, addressing recycling infrastructure deficiencies.
For New Entrants and Emerging Players:Enter via niche segments requiring specialized performance, such as cryogenic insulation for LNG infrastructure or aerogel integration for space-constrained retrofits. Target the retrofitting market in Eastern Europe, leveraging EU Green Deal funding and emphasizing application flexibility with foam board and spray foam. Differentiate through verifiable sustainability credentials and simplified installation processes to gain traction with facility managers. Focus on solutions that address both energy efficiency and complex fire safety standards.
For Investors and Strategic Acquirers:Private equity funds are the most active acquirers in this space, seeking to consolidate specialized manufacturers and integrate advanced material technologies. The market demonstrates strong long-term viability, driven by global energy management standards and escalating climate control demands across commercial and industrial sectors. Target acquisition candidates include mid-sized manufacturers specializing in flexible elastomeric foams or advanced mineral wool with robust certification portfolios. Watch for increased M&A activity among diversified material conglomerates seeking to expand their high-performance insulation offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand flexible elastomeric foam production | Addresses growing demand from data centers and healthcare facilities for advanced thermal and vapor control. |
| Invest in mineral wool recycling technologies | Enhances circular economy credentials and meets sustainability demands from European specifiers and regulators. |
| Form strategic partnerships for aerogel integration | Accelerates development of ultra-thin, high-performance insulation for space-constrained retrofitting applications. |
| Acquire specialized spray foam installation firms | Secures access to certified labor and improves quality consistency for complex retrofit projects. |
| Develop multi-functional insulation products | Integrates fire safety, acoustic dampening, and thermal resistance into single solutions for commercial buildings. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. The analysis combines in-depth primary interviews with HVAC engineers, facility managers, procurement leads, and material scientists, validated against extensive secondary research. Secondary sources included EU's EPBD reports, US EPA building codes, ISO 50001 documentation, and industry association reports. A robust bottom-up and top-down triangulation approach ensured data accuracy.
Granularity for the forecast framework modeled demand across product type, installation method, end user, and material thickness. An analytical framework integrated historical performance with future projections across the analysis window to derive Compound Annual Growth Rates. Key segmentation dimensions also included the regional regulatory environment impacting material selection. Energy efficiency mandates and data center expansion rates served as critical industry-specific forecast inputs.
The model holds under current regulatory frameworks and expected raw material stability; deviation in geopolitical instability or rapid technological disruption in cooling would shift projections. Forecasts reflect assumptions regarding global economic growth and sustained demand for energy-efficient buildings. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
HVAC Control System Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Cold Insulation Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Roof Vents Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
HVAC and Fire Protection Insulation Market