
 HVAC Blower and Fan Systems Market | 2026-2036
HVAC Blower and Fan Systems Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Blower and Fan Systems Market Outlook
Aftermarket service revenue is reshaping margin distribution across the HVAC blower and fan systems value chain. Greenheck Fan Corporation leverages its extensive distribution network to dominate replacement parts and field service. Systemair AB anchors its competitive position through geographic diversification across European and North American markets. ebm-papst Group specializes in EC motor technology leadership, capturing premium positioning in energy-efficient applications.
HVAC blower and fan systems comprise electromechanical air-moving equipment designed to generate controlled airflow at specified static pressures, typically operating at efficiencies between 40% and 75% depending on impeller geometry and motor configuration. These systems serve the fundamental purpose of thermal regulation, contaminant removal, and combustion air supply across built environments and industrial processes. Centrifugal fans command the largest installed base due to their pressure-generating capability in ducted applications, while axial fans capture growth in compact cooling and ventilation scenarios where low static resistance prevails. EC motor technology represents the fastest-expanding segment as building codes tighten energy intensity requirements and operators seek variable-speed control for demand-responsive operation.
The U.S. Department of Energy enforces minimum fan efficiency rating standards that compel manufacturers to redesign impellers and motor pairings for compliance. EPA regulations on industrial emissions and ventilation control shape product specifications for heavy-duty exhaust and process air applications. China's GB standards and MIIT efficiency directives impose parallel requirements on equipment sold into the country's massive construction pipeline. Stakeholders must monitor regulatory divergence between efficiency test methods as this determines which product platforms achieve multi-jurisdiction certification without costly redesign cycles.
Market Dynamics
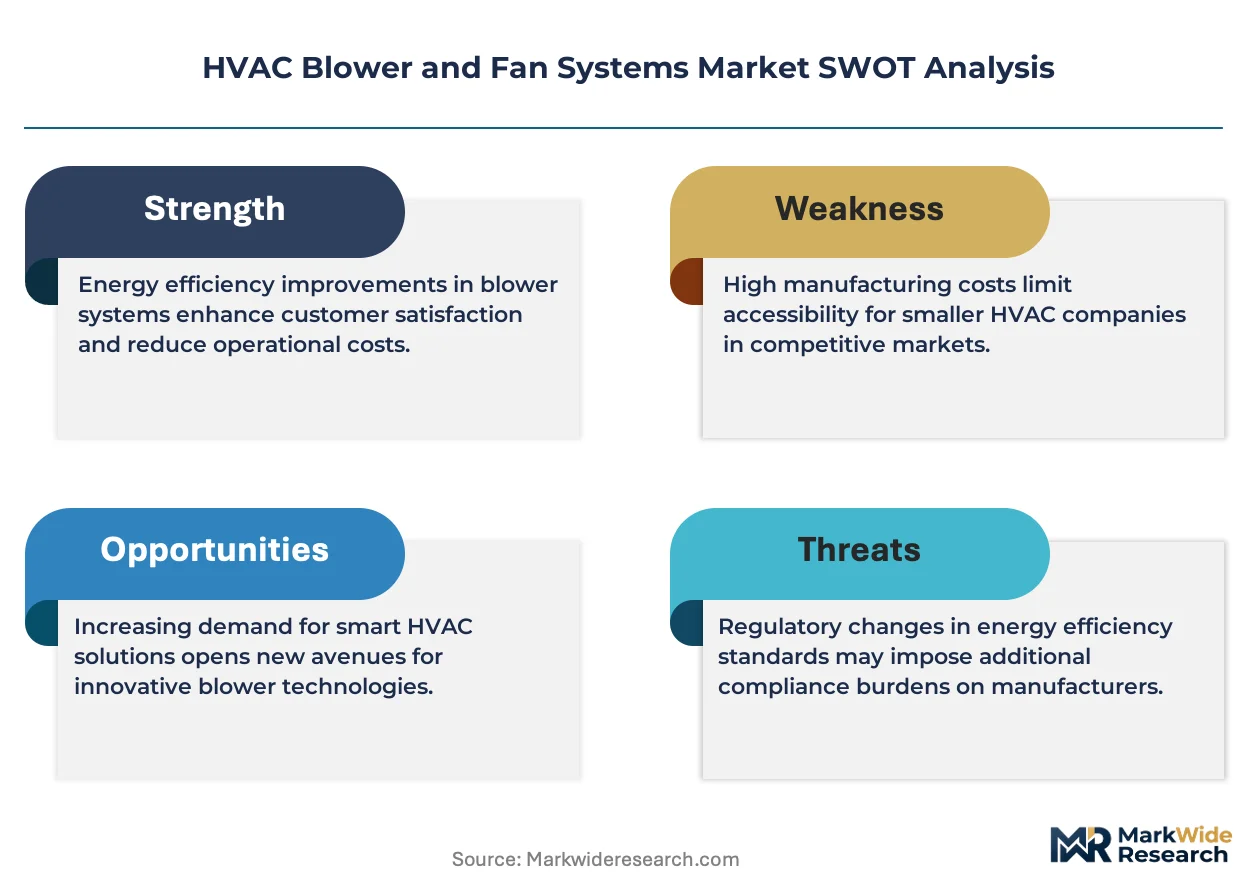
EC motor retrofits are compressing replacement cycles as building operators face compliance deadlines under tightening efficiency mandates. The shift from AC induction to electronically commutated drives is redistributing value capture toward motor specialists and away from legacy impeller fabricators.
Growth Catalysts
- Data center thermal loads:Hyperscale facilities in Northern Virginia and Frankfurt are specifying high-static centrifugal arrays for precision cooling. Rack density thresholds above 30kW per cabinet demand redundant fan configurations.
- MIIT efficiency directives:China's Ministry of Industry and Information Technology is phasing out IE2 motor classes in commercial HVAC applications. Domestic manufacturers must recertify product lines to GB 18613-2020 Grade 3 minimums.
- Heat pump deployment:Cold-climate air-source heat pumps require larger evaporator blowers to maintain capacity at sub-zero ambient temperatures. Nordic and North American residential retrofits are driving impeller redesigns for low-temperature operation.
Market Restraints
- Rare earth magnet supply:EC motors depend on neodymium-iron-boron magnets concentrated in Chinese processing facilities. Price volatility in dysprosium and terbium feeds directly into motor cost structures.
- Duct retrofit compatibility:Existing commercial buildings employ legacy spiral ductwork sized for lower-pressure AC blowers. Upgrading to high-efficiency EC-driven units often requires complete distribution system replacement.
- Skilled technician scarcity:Variable-speed drive commissioning and BACnet integration demand controls expertise that mechanical contractors rarely possess. Training lags behind equipment complexity in most metropolitan labor markets.
Strategic Opportunities
- Indoor air quality mandates:ASHRAE Standard 62.1 ventilation rate increases are forcing upgrades in aging school and office infrastructure. Higher outdoor air fractions require upsized supply fans with demand-controlled ventilation capability.
- Predictive maintenance platforms:Vibration monitoring and motor current signature analysis enable service contract bundling. Equipment OEMs can capture recurring revenue streams previously lost to independent service providers.
- Industrial exhaust recovery:Heat recovery ventilation in food processing and pharmaceutical cleanrooms pairs EC blowers with enthalpy wheels. This application remains underpenetrated relative to commercial building deployments.
Industry Challenges
- Multi-jurisdiction certification:Efficiency test methods diverge between AMCA 210 in North America and ISO 5801 in Europe. Product platforms require separate validation campaigns, extending development timelines.
- Legacy control integration:Building automation systems deployed before 2015 often lack native EC motor communication protocols. Retrofit projects face commissioning complexity when bridging Modbus and BACnet networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Blower and Fan Systems Market |
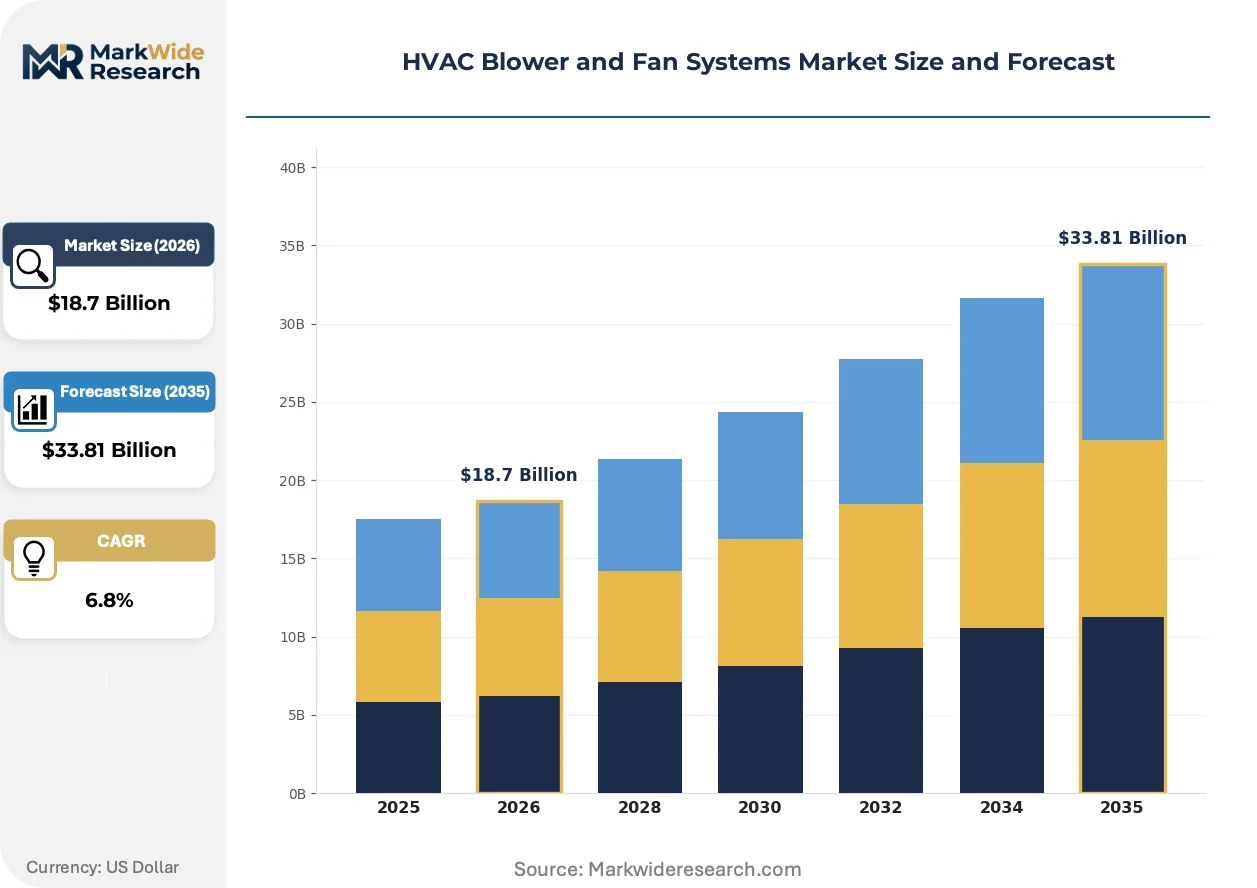
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Fans, Axial Fans, Blowers, Exhaust Fans Application: Residential, Commercial, Industrial, Automotive Technology: Variable Speed, Direct Drive, Belt Drive, EC Motors End User: Manufacturers, Contractors, HVAC Distributors, Building Owners |
| Companies Covered | Greenheck Fan Corporation, Systemair AB, Twin City Fan Companies, Ltd., FläktGroup Holding GmbH, ebm-papst Group, Loren Cook Company, Johnson Controls International, Ziehl-Abegg SE, Air System Components, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Blower and Fan Systems Market Strategic Shifts
Digital twin technology is penetrating HVAC system design, enabling airflow simulation before physical installation. This capability is compressing engineering change orders and reducing field commissioning failures.
Aerodynamic blade design software is digitizing impeller development cycles. Computational fluid dynamics platforms from Siemens and Ansys allow virtual pressure-flow curve validation. Fan manufacturers in Germany and Japan are adopting these tools to cut prototype iterations by half. The result is faster time-to-market for application-specific geometries.
The U.S. Department of Energy's fan efficiency rating standards are tightening compliance windows for covered equipment. Manufacturers must submit third-party test data to the DOE certification database before interstate commerce. This regulatory pressure is accelerating consolidation among smaller impeller fabricators lacking in-house testing laboratories.
Facility managers are unbundling equipment procurement from installation and maintenance contracts. Large mechanical contractors now compete directly with OEM service arms for multi-year performance agreements. This disintermediation is most visible in healthcare and higher education verticals where capital and operating budgets sit under separate administrative control.
HVAC Blower and Fan Systems Market Segmentation
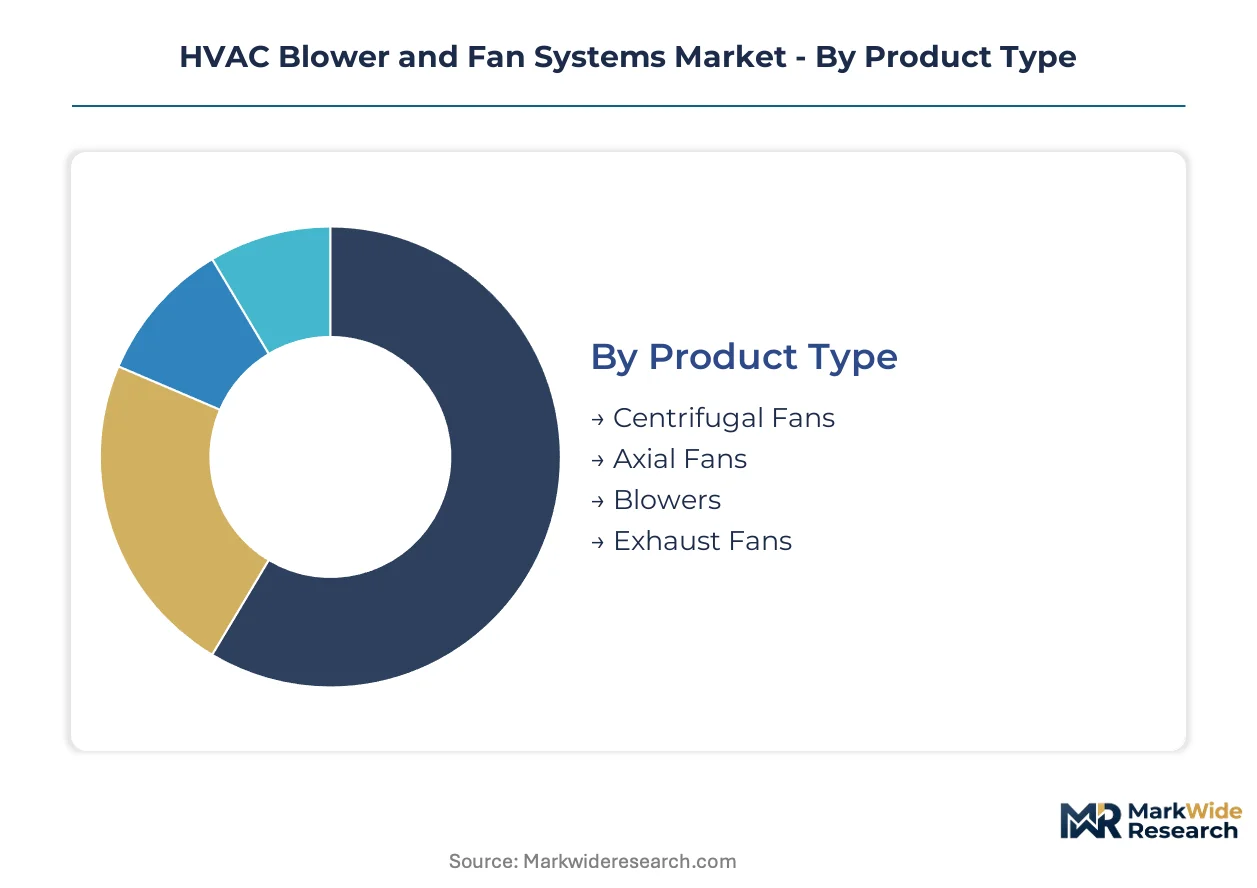
Segmentation reveals how technology maturity, regulatory pressure, and end-use economics fragment the HVAC blower and fan systems market. Product architecture, motor technology, and customer procurement patterns each create distinct competitive arenas with divergent margin profiles and growth trajectories.
Product Type:
Mature centrifugal designs dominate pressure-intensive applications, while axial configurations capture emerging demand in compact thermal management.
- Centrifugal Fans:Forward-curved and backward-inclined impeller geometries generate static pressures exceeding 10 inches water gauge for ducted distribution systems. Data center precision cooling arrays in Northern Virginia and Frankfurt specify redundant centrifugal configurations to handle rack densities above 30kW per cabinet. Regulatory pressure from DOE fan efficiency rating standards is forcing impeller redesigns to maintain compliance without sacrificing pressure capability.
- Axial Fans:Propeller-style airfoils operate at lower pressure differentials with compact footprints ideal for electronics cooling and rooftop ventilation. Heat pump evaporator modules in Nordic residential retrofits specify axial blowers for sub-zero ambient operation. MIIT efficiency directives in China are accelerating the displacement of AC induction drives with electronically commutated alternatives in this segment.
- Blowers:Positive-displacement and regenerative designs deliver pulsation-free airflow for pneumatic conveying and combustion air supply.
- Exhaust Fans:Wall- and roof-mounted configurations serve contaminant removal in commercial kitchens, laboratories, and industrial process enclosures.
Centrifugal fans retain volume leadership; axial fans hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive industrial specifications from price-sensitive residential procurement patterns.
- Commercial:Office towers, retail complexes, and healthcare facilities specify packaged rooftop units with integrated fan arrays. ASHRAE Standard 62.1 ventilation rate increases are forcing upgrades in aging school infrastructure across the United States. Higher outdoor air fractions require upsized supply fans with demand-controlled ventilation capability and BACnet integration.
- Industrial:Process ventilation, material handling, and combustion air systems demand heavy-duty construction with corrosion-resistant coatings. Food processing and pharmaceutical cleanrooms pair EC blowers with enthalpy wheels for exhaust heat recovery. EPA emissions regulations shape product specifications for fume exhaust and dust collection applications.
- Residential:Split-system air handlers and heat pump indoor units compete primarily on installed cost and acoustic performance.
- Automotive:Cabin climate control and battery thermal management systems specify compact, lightweight blowers with rapid transient response.
Commercial applications command the largest revenue pool; industrial segments generate the highest margin premiums.
Technology:
Customer type differentiation separates specification-driven OEM procurement from retrofit-focused contractor replacement markets.
- EC Motors:Electronically commutated permanent-magnet drives achieve part-load efficiencies exceeding 80% with integrated variable-speed control. Building operators facing compliance deadlines under tightening efficiency mandates are compressing replacement cycles through EC retrofits. Rare earth magnet supply concentration in Chinese processing facilities introduces cost volatility through dysprosium and terbium price swings.
- Variable Speed:Inverter-driven AC induction motors enable demand-responsive airflow modulation without full EC motor cost premiums. Legacy building automation systems deployed before 2015 often lack native communication protocols, creating commissioning complexity when bridging Modbus and BACnet networks.
- Direct Drive:Motor-impeller coupling eliminates belt maintenance and alignment issues in continuous-duty applications.
- Belt Drive:Pulley ratios enable field-adjustable speed modification for balancing and commissioning flexibility.
EC motors are gaining share fastest; belt drive configurations face accelerating displacement.
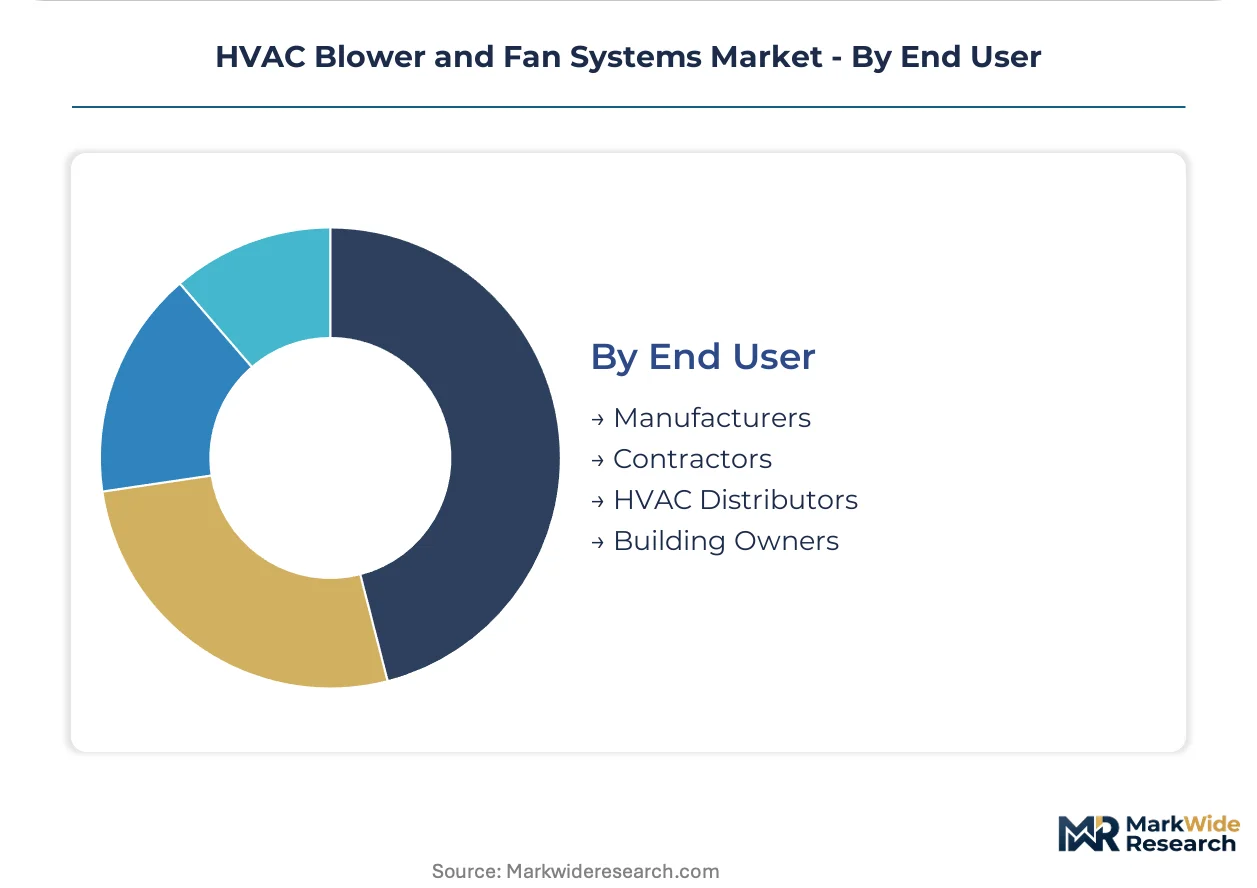
End User:
Supply concentration among motor specialists and impeller fabricators shapes how value distributes across distribution channels.
- Building Owners:Facility managers unbundle equipment procurement from installation and maintenance contracts, seeking multi-year performance agreements. Healthcare and higher education verticals drive this disintermediation where capital and operating budgets sit under separate administrative control.
- HVAC Distributors:Stocking distributors capture replacement parts revenue and field service margins in aftermarket channels.
- Contractors:Mechanical installation firms specify equipment based on familiarity, local support, and commissioning assistance availability.
- Manufacturers:OEMs of air handling units, rooftop packages, and heat pumps integrate fan subsystems into finished equipment.
Building owners are consolidating specification authority; distributors retain aftermarket profit pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer price sensitivity varies sharply by geography. Commercial contractors in India and Southeast Asia prioritize first-cost minimization. German and Japanese industrial purchasers accept 40-60% premiums for energy-efficient configurations.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives demand for high-static centrifugal arrays. The Department of Energy enforces fan efficiency rating standards that compel impeller redesigns. ASHRAE Standard 62.1 ventilation mandates are forcing school infrastructure upgrades across the Midwest and Southeast.
China
Commercial building stock expansion and industrial ventilation infrastructure investment concentrate demand in the Yangtze River Delta and Pearl River Delta. MIIT efficiency directives phase out IE2 motor classes under GB 18613-2020 Grade 3 minimums. Domestic manufacturers in Zhejiang and Jiangsu provinces dominate cost-competitive axial fan production.
Germany
Industrial process ventilation and pharmaceutical cleanroom specifications sustain premium EC motor adoption. The EU F-Gas Regulation and Ecodesign Directive shape equipment compliance requirements. Manufacturing clusters in Baden-Württemberg and Bavaria host precision impeller fabricators serving pan-European distribution.
Japan
Heat pump deployment for cold-climate residential retrofits accelerates evaporator blower demand. METI efficiency standards and JIS certification requirements filter market entry. Industrial concentration in the Chubu region around Nagoya supports automotive and electronics cooling subsystem integration.
India
Commercial real estate development in Mumbai and Delhi-NCR expands ducted HVAC installations. BIS energy efficiency labeling and CEA motor performance standards tighten procurement specifications. Price-sensitive contractor markets in Gujarat and Tamil Nadu favor belt-drive AC configurations over EC alternatives.
HVAC Blower and Fan Systems Market Competitive Environment
Capability concentration sits with motor technology specialists; scale advantage sits with diversified ventilation equipment fabricators. The market structures around three tiers: integrated air handling unit OEMs, standalone impeller manufacturers, and EC motor technology providers. Strategic moves center on aftermarket service contract capture and geographic diversification to offset regional construction cyclicality.
Within the diversified equipment tier, Greenheck Fan Corporation and Systemair AB occupy positions spanning commercial and industrial ventilation. ebm-papst Group anchors the EC motor specialization vector. These three exemplify how value capture distributes between fabrication scale and technology premium.
| Leading Market Players |
|---|
| Greenheck Fan Corporation |
| Systemair AB |
| Twin City Fan Companies, Ltd. |
| FläktGroup Holding GmbH |
| ebm-papst Group |
| Loren Cook Company |
| Johnson Controls International |
| Ziehl-Abegg SE |
| Air System Components, Inc. |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Jiangsu provinces anchor global axial fan manufacturing capacity, and their production scale directly determines pricing power for cost-competitive commercial ventilation equipment. EC motor suppliers in Baden-Württemberg command 40-60% premiums through magnet technology control, while belt-drive AC configurations face margin compression from Chinese domestic competition.
Pricing Analysis
Aftermarket service contracts and replacement parts revenue drive lifetime value capture for established ventilation equipment OEMs. Three-tier pricing structure across premium EC-motor systems, standard variable-speed AC units, and economy belt-drive configurations segments buyers by efficiency compliance urgency and operating budget constraints. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers are flooding Southeast Asian and Middle Eastern distribution channels with unbranded alternatives. Healthcare and higher education facility managers show lowest price sensitivity due to separate capital and operating budget controls, while Indian commercial contractors in Gujarat and Tamil Nadu prioritize first-cost minimization above operating efficiency.
Supply Chain Analysis
Export control regimes on rare earth processing technology limit Western motor manufacturers' access to neodymium-iron-boron magnet supply concentrated in Chinese facilities. Manufacturing capacity clusters in China, Germany, and Japan feed downstream assembly operations across three continents. Supply chains draw from dysprosium and terbium feedstocks, silicon steel laminations, and precision-machined aluminum impeller castings. Single-source vulnerability in Chinese rare earth magnet processing introduces cost volatility that propagates through EC motor bill-of-materials. Distribution runs through stocking distributors capturing aftermarket parts revenue, mechanical contractors specifying on familiarity, and OEM integration channels for air handling unit manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as facility managers unbundle equipment procurement from installation contracts and consolidate multi-year performance agreements under single administrative control. This shift fragments specification authority away from mechanical contractors toward building owners with direct OEM relationships.
For Market Incumbents: Harden aftermarket service contract capture through predictive maintenance platform deployment using vibration monitoring and motor current signature analysis. Deepen channel control by certifying distributor technicians on EC motor commissioning and BACnet integration to offset skilled labor scarcity. Vertical integration into rare earth magnet sourcing or permanent-magnet motor manufacturing insulates margin pressure from Chinese supply concentration.
For New Entrants and Emerging Players: Build out industrial exhaust heat recovery applications pairing EC blowers with enthalpy wheels in food processing and pharmaceutical cleanrooms, a segment underpenetrated relative to commercial building deployments. Target Nordic residential heat pump retrofits requiring redesigned evaporator blowers for sub-zero ambient operation. Go-to-market through OEM subsystem partnerships rather than direct brand competition against established ventilation equipment fabricators.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because efficiency mandate tightening across DOE, MIIT, and EU Ecodesign frameworks compresses replacement cycles and forces technology upgrades regardless of construction cyclicality. Acquisition targets should display EC motor technology leadership or captive aftermarket service revenue streams. The signal to watch is divergence in multi-jurisdiction certification timelines as AMCA 210 and ISO 5801 test method misalignment determines which product platforms achieve cross-border compliance without costly redesign.
| Strategic Initiative | Industry Significance |
|---|---|
| EC Motor Technology Licensing | Permanent-magnet motor specialists capture premium positioning as DOE fan efficiency rating standards tighten compliance windows. |
| Predictive Maintenance Platform Launch | Vibration monitoring and current signature analysis enable OEMs to displace independent service providers in aftermarket revenue capture. |
| Backward Integration into Rare Earth Magnet Supply | Upstream control over neodymium-iron-boron sourcing insulates EC motor cost structures from Chinese processing concentration. |
| Geographic Diversification into India | Commercial real estate expansion in Mumbai and Delhi-NCR opens ducted HVAC installations despite price-sensitive contractor markets. |
| Industrial Exhaust Heat Recovery Joint Venture | Partnerships with enthalpy wheel manufacturers unlock underpenetrated food processing and pharmaceutical cleanroom applications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment certification databases to establish market size and growth trajectory. Primary interviews engaged HVAC equipment OEM procurement directors, mechanical contractor operations managers, facility maintenance directors, and aftermarket service heads across commercial, industrial, and residential end-use segments. Secondary validation drew from DOE certification database entries, AMCA laboratory test reports, MIIT efficiency directive publications, and SEC 10-K disclosures from listed ventilation equipment manufacturers. Bottom-up unit shipment estimates triangulate against top-down construction spending allocation models.
Forecast inputs include technology substitution curves from AC induction to EC motor drives, regulatory compliance deadline calendars across major jurisdictions, and data center construction pipeline tracking in Northern Virginia and Frankfurt. Segmentation modeling covers product architecture, motor technology tier, application vertical, and end-user procurement pattern dimensions. CAGRs derive from fitted adoption curves applied to replacement cycle compression and new build penetration rates, with heat pump deployment intensity and ventilation rate mandate expansion as HVAC-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by rare earth magnet suppliers or EC motor technology licensors would shift outcomes beyond modeled ranges. Material shifts in multi-jurisdiction certification timeline divergence or export control expansion on permanent-magnet technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Ductless HVAC System Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Aeration System Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Commercial Kitchen Ventilation System Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
Air Pressure Booster System Market