
 Residential Security Market | 2026-2036
Residential Security Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Security Market Intelligence
The concentration of semiconductor manufacturing for security sensors is restructuring the component supply chain for alarm system producers. Honeywell International Inc. leverages its extensive industrial technology portfolio to offer integrated building security solutions. ADT Inc. sustains its market position through a strong brand presence and professional monitoring services. ASSA ABLOY AB specializes in access solutions, focusing on smart locks and electronic door hardware.
Residential security encompasses a system of inter-communicating electronic devices and mechanical hardware designed to protect a home from intrusion, fire, and other threats. These systems often utilize wireless protocols like Z-Wave or Zigbee to connect sensors, cameras, and control panels. Video doorbells and smart locks represent the fastest-growing product categories, driven by convenience and demand for package theft prevention. While homeowners remain the primary end-user segment, solutions tailored for property managers managing multiple units are gaining traction.
Data privacy regulations, such as the GDPR in Europe, impose strict requirements on how personal data from surveillance cameras is stored and processed. In the United States, the FCC regulates the wireless communication components within security systems to prevent signal interference. Stakeholder focus now turns to establishing clear standards for AI ethics and interoperability between different manufacturers' devices.
Market Dynamics
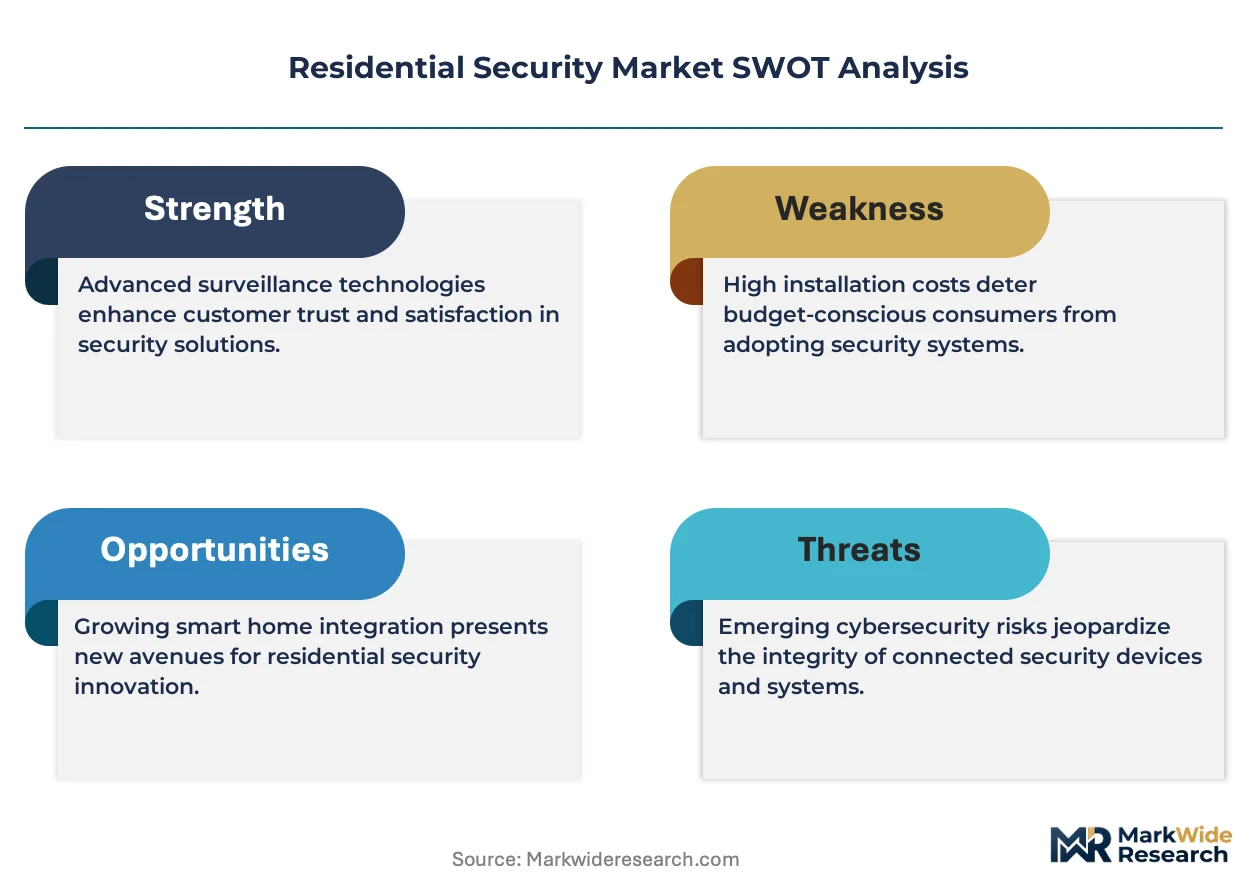
The convergence of artificial intelligence with sensor and camera hardware is the central force shaping the residential security market. This integration moves systems beyond simple intrusion detection, creating new value propositions around proactive threat identification and lifestyle automation for homeowners.
Growth Catalysts
- AI-Powered Analytics:The integration of AI into surveillance cameras to perform real-time object and facial recognition directly addresses homeowner demand for package theft prevention and reducing false alarms from pets or vehicles.
- Property Management Solutions:Demand from property managers for centralized security solutions across multi-family housing portfolios provides a scalable growth channel, moving beyond the traditional single-family homeowner segment.
- Smart Home Ecosystems:High consumer spending on smart home devices in markets like the United States creates a pull-through effect for security products, which are often integrated as a core component of a connected home.
Market Restraints
- Data Privacy Regulation:Strict regulations like the GDPR in Europe impose significant compliance costs and technical constraints on how personal data from video surveillance is collected, stored, and processed by service providers.
- Component Supply Concentration:The high concentration of semiconductor manufacturing for critical security sensors in East Asia creates supply chain vulnerabilities and pricing volatility for alarm system producers globally.
- Interoperability Limitations:The use of competing proprietary wireless protocols, such as Z-Wave and Zigbee, fragments the market and can lock consumers into a single manufacturer's ecosystem, hindering broader system adoption.
Strategic Opportunities
- Environmental Hazard Sensing:Expanding system capabilities beyond security to include monitoring for environmental threats like water leaks, freezing pipes, or poor air quality opens new revenue streams and enhances the product's value proposition.
- Technology Convergence:The combination of AI analytics with 5G connectivity enables high-fidelity, low-latency video streaming and remote monitoring, creating opportunities for premium tiered services in urban areas.
- Underpenetrated Developing Markets:Rising disposable incomes and property ownership in countries such as India and Brazil present significant opportunities for market entry with affordable, scalable security solutions tailored to local needs.
Industry Challenges
- Legacy System Integration:Integrating modern, IP-based security systems with the millions of older, hardwired alarm panels already installed in homes presents a significant technical and logistical challenge for installers and homeowners.
- AI Ethics Standardization:A lack of clear, globally accepted standards for AI ethics and bias in surveillance applications creates development uncertainty and reputational risk for manufacturers deploying these technologies.
- Skilled Technician Shortage:A deficit of technicians proficient in both traditional low-voltage wiring and modern IT network configuration complicates the installation and maintenance of sophisticated, integrated security systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Security Market |
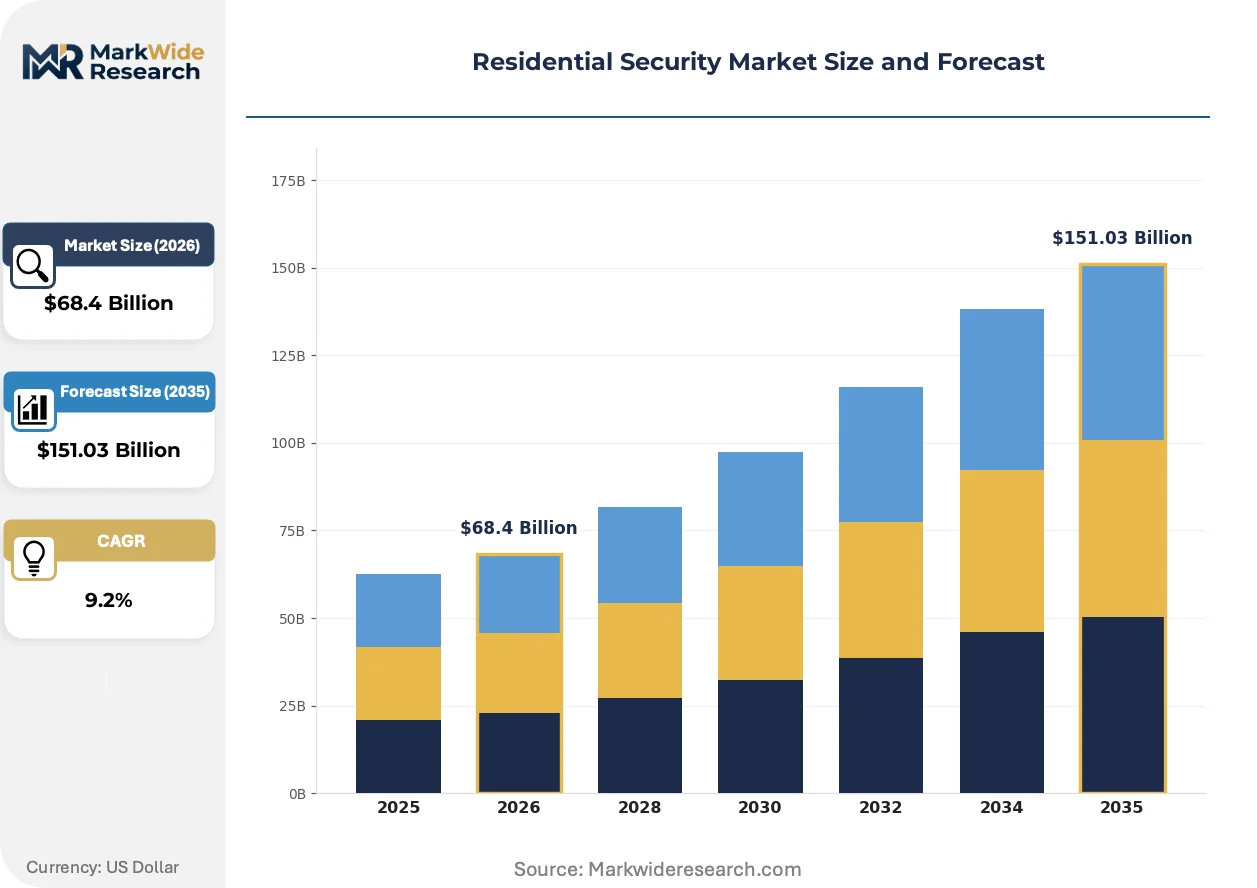
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $151.03 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alarm Systems, Surveillance Cameras, Smart Locks, Motion Sensors, Video Doorbells Technology: Wireless, Wired, Biometrics, Facial Recognition, Infrared Sensors Application: Home Intrusion Prevention, Fire Detection, Elderly Monitoring, Package Theft Prevention, Child Safety End User: Homeowners, Property Managers, Tenants, Security Firms, Vacation Home Operators |
| Companies Covered | ADT Inc., Honeywell International Inc., Johnson Controls, ASSA ABLOY AB, Robert Bosch GmbH, Hangzhou Hikvision Digital Technology Co., Ltd., Alarm.com Holdings Inc., SimpliSafe Inc., Vivint Smart Home Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Security Market Strategic Shifts & Innovations
Software-defined capabilities are transforming residential security from a static hardware sale into a dynamic, service-oriented model. Value is migrating from the physical device to the intelligence of the analytics, the responsiveness of the monitoring, and the seamlessness of the user experience.
Edge computing in security cameras and video doorbells allows for on-device processing of analytics, such as person detection or package identification. Homeowners and property managers are adopting these devices to receive faster, more relevant alerts and to minimize the amount of sensitive video data sent to the cloud. This trend is decentralizing security data processing away from cloud-based servers, granting users greater control over personal privacy and reducing system latency.
The European Union's AI Act is establishing a risk-based framework for artificial intelligence systems. This regulation classifies certain public and private surveillance applications as high-risk, mandating strict compliance regarding data quality, transparency, and human oversight. Security equipment manufacturers targeting the EU market are now embedding these requirements into their product development cycles, particularly for cameras with biometric or behavioral analysis features.
A consumer shift toward unbundling hardware from services is altering traditional business models. Buyers increasingly acquire security devices from retail channels and then select separate, often contract-free, professional monitoring plans or opt for self-monitoring through mobile applications. This disintermediates the legacy model of a single provider bundling hardware, installation, and a multi-year service contract, a pattern most visible in the North American DIY security segment.
Residential Security Market Segmentation
The residential security market's diverse offerings and consumer needs necessitate a granular segmentation analysis. Understanding these distinct categories provides clarity on demand drivers, technological shifts, and competitive landscapes. This detailed breakdown highlights areas of concentrated growth and specific end-user requirements.
Product Type:
The concentration of manufacturing for specific components heavily influences the supply and innovation within residential security product types.
- Smart Locks:These electronic locking devices offer keyless entry, remote access control, and integration with smart home systems. Demand concentrates in urban areas, driven by convenience, property management needs, and enhanced access control.
- Video Doorbells:Equipped with cameras, microphones, and speakers, these devices allow homeowners to see and communicate with visitors remotely. Their demand is high in the United States, primarily for package theft prevention and enhanced home monitoring.
- Alarm Systems:These integrated systems detect intrusions using various sensors and alert homeowners or professional monitoring services.
- Surveillance Cameras:Networked cameras provide real-time video monitoring and recording capabilities for interior and exterior home security.
- Motion Sensors:Devices that detect movement within a specified area, often triggering alarms or activating other security components.
Today's leader: Video Doorbells. Tomorrow's challenger: Smart Locks.
Technology:
The application requirements for residential security solutions dictate the prevalent technology choices for effective threat detection and user interaction.
- Wireless:These systems utilize radio frequencies like Z-Wave or Zigbee for communication between devices, offering flexible installation without extensive cabling. Consumer preference for DIY installation and ease of integration drives adoption across many markets.
- Facial Recognition:This AI-powered technology identifies individuals based on their unique facial features, enhancing access control and personalized security alerts. Integration with surveillance cameras for proactive threat identification is a key driver.
- Wired:Traditional security systems rely on physical cables for power and data transmission, offering high reliability and resistance to interference.
- Biometrics:Authentication methods using unique biological characteristics, such as fingerprints or voice, for secure access control.
- Infrared Sensors:These devices detect heat signatures or changes in infrared radiation, commonly used for motion detection in alarm systems.
Wireless solutions are expanding most quickly, while facial recognition technology is gaining share fastest.
Application:
Different customer types prioritize distinct security applications, shaping product development and service offerings across the market.
- Package Theft Prevention:This application leverages video doorbells and surveillance cameras to deter and record instances of package theft from doorsteps. Strong consumer demand in the United States directly influences product innovation in this area.
- Home Intrusion Prevention:Core to residential security, this application uses alarms, sensors, and cameras to detect unauthorized entry into a home. Homeowners consistently prioritize robust intrusion detection capabilities.
- Fire Detection:Systems designed to identify the presence of smoke or excessive heat, triggering alarms to warn occupants of a potential fire.
- Elderly Monitoring:Solutions enabling remote oversight of elderly individuals, often incorporating fall detection and emergency alert features for family members.
- Child Safety:Applications focused on protecting children within the home environment, including pool alarms, window sensors, and restricted access controls.
Package Theft Prevention shows the steepest expansion trajectory, with Home Intrusion Prevention maintaining consistent demand.
End User:
The maturity of various end-user segments dictates their specific security needs and willingness to adopt advanced residential security solutions.
- Homeowners:This segment comprises individuals who own and reside in single-family homes, representing the largest traditional customer base for residential security systems. Their demand is driven by personal safety, asset protection, and smart home integration.
- Property Managers:These professionals oversee multi-family housing units and seek integrated security solutions for multiple properties. Centralized management and scalable systems for numerous tenants drive their increasing adoption.
- Tenants:Individuals renting residential properties, often seeking flexible, portable, and cost-effective security options for their leased living spaces.
- Security Firms:Companies that provide professional monitoring, installation, and maintenance services for residential security systems.
- Vacation Home Operators:Owners or managers of seasonal or rental properties requiring remote monitoring and access control capabilities.
Property Managers represents the fastest-growing segment, while homeowners remain the largest end-user base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks significantly influence residential security market dynamics, often prompting production shifts based on compliance costs. Varying data privacy standards and AI governance approaches create distinct operational environments for manufacturers. This divergence can lead to strategic relocation of development or manufacturing capabilities to optimize market access and cost structures.
United States
Consumer spending on smart home devices and the strong demand for package theft prevention drive significant security product innovation. The FCC regulates wireless communication components within these systems, ensuring signal integrity across devices. Silicon Valley in California concentrates on developing advanced smart home integration platforms for security solutions.
Germany
Demand for integrated building security solutions and smart locks in urban areas propels market expansion in Germany. The GDPR imposes stringent data privacy requirements on surveillance camera data storage and processing. Munich's technology ecosystem fosters advanced sensor development and AI analytics for residential security systems.
China
Manufacturing concentration for security sensors and the large-scale production of smart home devices define China's market contribution. GB standards influence product design and interoperability for domestic security systems within the country. Shenzhen's extensive manufacturing hub produces a high volume of surveillance cameras and smart hardware components.
India
Rising disposable incomes and increasing property ownership create demand for affordable, scalable security solutions across India. BIS certification ensures product quality and safety for security devices entering the Indian market. Bangalore's burgeoning tech industry drives software development for scalable, app-based security monitoring platforms.
Residential Security Market Key Industry Players
East Asian producers anchor one tier of the residential security market, specializing in component manufacturing and high-volume hardware production. North American and European specialists hold significant positions in integrated solutions, software development, and service provision. The market structure features established industrial conglomerates offering broad portfolios and dedicated security firms focusing on monitoring services. Companies engage in portfolio diversification, strategic partnerships, and technology licensing to expand their market reach and protect intellectual property.
Industrial technology conglomerates, such as Honeywell International Inc., exemplify the broad portfolio approach, integrating security solutions with wider building management systems through extensive R&D capabilities. Dedicated security service providers like ADT Inc. anchor the professional monitoring segment, leveraging strong brand recognition and established customer bases for recurring revenue streams. Hangzhou Hikvision Digital Technology Co., Ltd. represents the hardware manufacturing tier, particularly in surveillance cameras and video analytics components, reflecting the production scale and technological advancements from East Asia.
| Leading Market Players |
|---|
| ADT Inc. |
| Honeywell International Inc. |
| Johnson Controls |
| ASSA ABLOY AB |
| Robert Bosch GmbH |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Alarm.com Holdings Inc. |
| SimpliSafe Inc. |
| Vivint Smart Home Inc. |
| Others |
Cost & Logistics Intelligence
The European Union's AI Act, establishing a risk-based framework for AI, gates qualified supply for surveillance systems and influences premium pricing for compliant, ethically developed solutions. This mandate ensures product integrity and consumer trust.
Pricing Analysis
Retailer markup significantly influences the final cost of residential security hardware, especially for DIY segments. Pricing follows a hybrid model, combining per-unit transactional hardware sales with recurring subscription fees for professional monitoring. Brand premium and comprehensive after-sales service drive price differentiation in the premium tier. Pricing softness stems from the proliferation of low-cost, self-monitored DIY options, making tenants the most price-sensitive segment.
Supply Chain Analysis
Single-source vulnerability sits with East Asian producers for critical semiconductor components, impacting the residential security supply chain. Manufacturing concentration in China defines the production of smart home devices and surveillance cameras. The industry relies on wireless modules and camera sensors as key inputs, creating a structural risk of pricing volatility. Distribution predominantly runs through retail channels for DIY products and professional installers for integrated systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential security market presents a late-cycle quality story, driven by a demand-shift toward premium specifications like AI-powered analytics and proactive threat identification. Consumers seek enhanced functionality and seamless integration, not just basic protection.
For Market Incumbents:To counter AI ethics uncertainty and hardware commoditization, incumbents must accelerate R&D in AI-powered analytics and secure strategic partnerships for software development. Integrating environmental hazard sensing beyond traditional security offers portfolio diversification. Investing in clear AI ethics standards and interoperability ensures long-term consumer trust and regulatory compliance.
For New Entrants and Emerging Players:AI-powered edge computing offers a technology-first wedge into the residential security market, enabling faster, more private alerts. New entrants should target underpenetrated developing markets like India and Brazil with affordable, scalable solutions. Property management solutions for multi-family housing represent a key white-space opportunity. An app-based monitoring and self-installation go-to-market angle can capture cost-sensitive consumers.
For Investors and Strategic Acquirers:Roll-up economics work for integrated solution providers because market fragmentation creates opportunities for consolidation. The residential security market demonstrates strong long-term viability as an essential service with sustained growth driven by smart home integration. Acquisition targets should focus on software-defined security firms with strong AI analytics capabilities. The standardization of AI ethics across geographies is a critical signal to watch for accelerated market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-Powered Analytics | Introducing advanced AI features enhances proactive threat identification for homeowners. |
| Strategic Partnership: Interoperability Standards | Collaborating on open standards fosters broader system adoption across devices. |
| Acquisition of Specialist Firm: Software-Defined Security | Acquiring firms with strong software capabilities shifts value from hardware to services. |
| Geographic Expansion: Underpenetrated Developing Markets | Entering new regions like India captures demand from rising property ownership. |
| Investment in Edge AI Development | Enhancing on-device processing capabilities reduces cloud dependency and improves privacy for users. |
Research Approach
Bottom-up homeowner and property manager modeling reconciled against top-down smart home device manufacturing tracking forms the analytical core of this study. Primary interviews with security system integrators, smart home device manufacturers, and end-users provided qualitative insights. These insights were validated against secondary data from FCC filings, smart home device sales data, and industry association reports. This approach ensured comprehensive market understanding and robust data triangulation.
Historical trendline analysis informed the projection of future market growth across the analysis window. The analytical framework modeled key segments including product type, technology, application, and end-user, alongside regional adoption patterns. Compound annual growth rates were derived from a multi-factor regression analysis, integrating inputs such as smart home device penetration rates and regulatory compliance costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to changes in data privacy laws and semiconductor supply stability. Forecasts inherently reflect documented assumptions regarding technological advancements and consumer spending. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Global Security Policy Management Market
Security and Surveillance
Russian Intelligent Eavesdropping Detection System Market
Security and Surveillance
Integrated Security Services Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Latin America Security Services Market
Security and Surveillance
Shock Sensor Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Integrated Security Solutions Market
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Maritime Security Market