
 Integrated Security Solutions Market | 2026-2036
Integrated Security Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Security Solutions Market Outlook
Enterprise-grade certification requirements is bifurcating the competitive landscape into qualified integrators and commodity installers. Cisco leverages its networking hardware footprint to anchor unified security fabric deployments across Fortune 500 campuses. Palo Alto Networks sustains R&D intensity in AI-driven threat detection, competing directly with CrowdStrike's cloud-native endpoint architecture. Fortinet controls manufacturing scale for its proprietary security processing units, differentiating cost structures against software-only rivals.
Integrated security solutions combine physical access control, video surveillance, intrusion detection, and cybersecurity protocols into unified command platforms operating on common data layers with sub-100-millisecond alert correlation thresholds. These systems serve critical infrastructure, commercial facilities, and government installations requiring coordinated threat response across electronic and physical domains. Video surveillance solutions occupy mature margin pools in commercial real estate, while AI-driven technology segments capture fastest expansion as behavioral analytics displace rule-based alerting. Cloud-based deployment models are displacing on-premises infrastructure in mid-market accounts, though hybrid installation types retain dominance in regulated industrial end-user verticals.
FCC equipment authorization standards shape wireless sensor deployment in US commercial installations, while the EU AI Act imposes conformity requirements on automated threat classification systems across European government end-user contracts. Germany's BSI technical guidelines and France's ANSSI certification frameworks create compliance moats for qualified integrators bidding on critical national infrastructure. Stakeholders must monitor convergence between physical security standards and cybersecurity mandates as procurement specifications increasingly reject siloed vendor proposals.
Market Dynamics
Convergence between physical access control and cybersecurity protocols is collapsing procurement silos as unified command platforms displace standalone security stacks across critical infrastructure installations.
Growth Catalysts
- EU NIS2 Directive:The directive mandates stronger baseline protections for critical entities across energy, transport, and digital infrastructure sectors, compelling facility operators to consolidate vendor relationships.
- Smart city infrastructure:Singapore's national digital infrastructure program is accelerating unified platform adoption through standardized data interoperability requirements for municipal security systems.
- AI-driven behavioral analytics:Machine learning classification of anomalous physical movement patterns is displacing rule-based video analytics in high-security government installations.
Market Restraints
- Semiconductor supply concentration:Proprietary security processing units depend on advanced fabrication nodes concentrated in Taiwan, creating single-source vulnerability for hardware-anchored vendors.
- EU AI Act compliance friction:Automated threat classification systems face conformity assessment bottlenecks that extend sales cycles by 8-14 months for European government contracts.
- Legacy system substitution:Analog CCTV infrastructure with 10-15 year depreciation schedules slows replacement demand in commercial real estate portfolios.
Strategic Opportunities
- Industrial corridor consolidation:Germany's manufacturing belt presents concentrated demand as automotive and chemical facilities merge physical and cyber defense procurement functions.
- Cloud-native mid-market penetration:SaaS-delivered security orchestration platforms are capturing mid-market accounts previously served by fragmented local integrators.
- Hybrid deployment architectures:Edge computing convergence with cloud analytics is enabling new service models for regulated verticals requiring data sovereignty.
Industry Challenges
- Cross-domain certification complexity:Integrators must simultaneously maintain BSI technical guidelines for physical systems and ANSSI cybersecurity credentials, extending qualification timelines.
- Sub-100-millisecond latency engineering:Alert correlation across electronic and physical domains demands specialized network architecture expertise scarce in conventional security channels.
- Interoperability standard fragmentation:Competing proprietary protocols from incumbent vendors complicate multi-manufacturer deployments in enterprise campus environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Security Solutions Market |
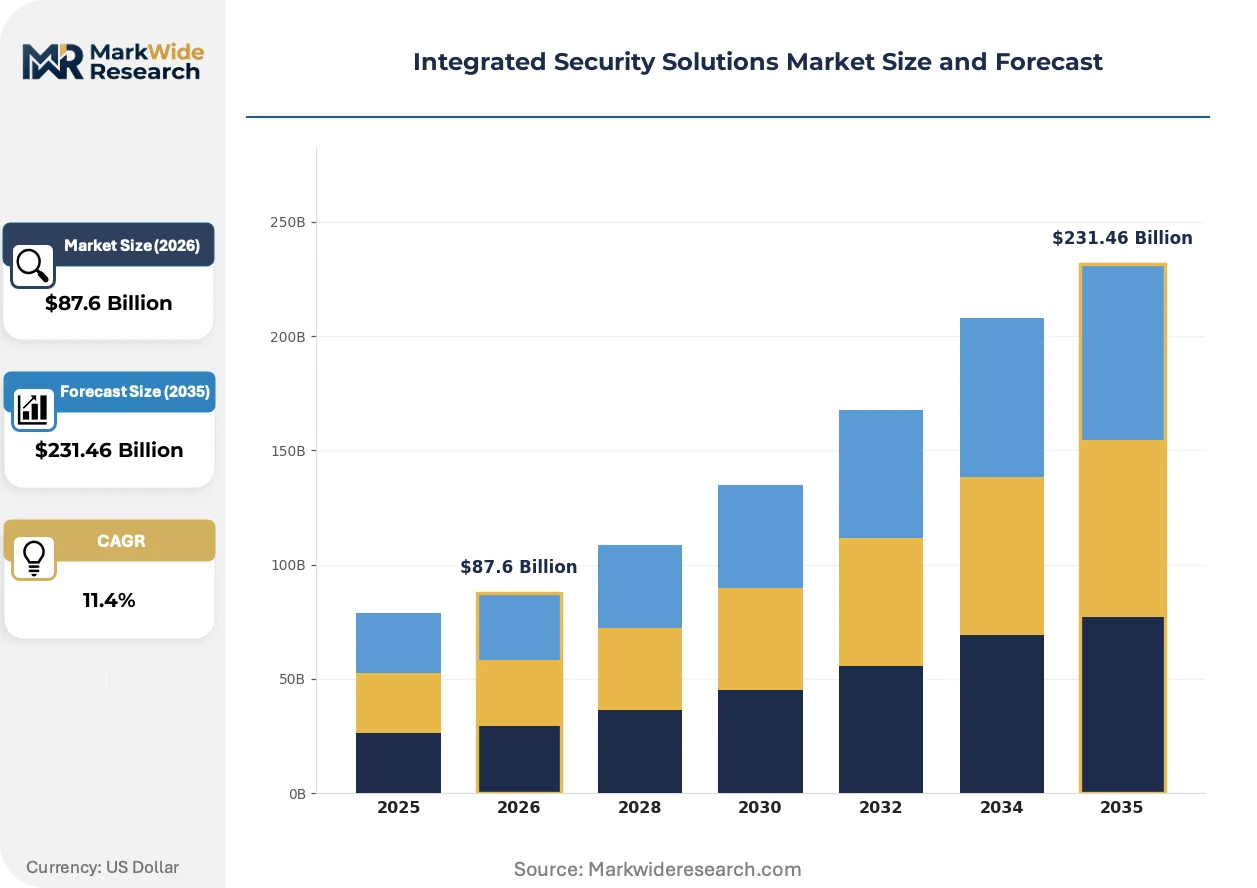
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Video Surveillance, Access Control, Intrusion Detection, Perimeter Security End User: Commercial, Residential, Government, Industrial Technology: Cloud-based, On-premises, IoT-enabled, AI-driven Installation Type: Wired, Wireless, Hybrid, Standalone |
| Companies Covered | Cisco, Microsoft Security, Palo Alto Networks, Zscaler, IBM Security, Fortinet, CrowdStrike, Google Cloud Security, Check Point Software Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Security Solutions Market Strategic Shifts
Three forces are compressing the technology refresh cycle: artificial intelligence is displacing heuristic detection methods, regulatory jurisdictions are expanding compliance scope, and buyer procurement functions are consolidating vendor panels.
Edge-deployed neural inference engines for real-time video analytics are displacing centralized server-based processing architectures in large-scale surveillance networks. Critical infrastructure operators in energy and transportation verticals are adopting these systems to reduce bandwidth costs and enable autonomous response triggers. The shift is compressing margins for traditional video management software vendors while elevating hardware-software integrated solution providers.
The EU AI Act imposes conformity requirements on automated threat classification systems deployed across European government end-user contracts. High-risk AI applications in biometric identification and critical infrastructure monitoring face mandatory third-party assessment and CE marking obligations. Defense integrators and smart city contractors are restructuring development pipelines to embed explainability documentation and human-in-the-loop overrides from design phase.
Consolidated procurement functions in Fortune 500 campus security are unbundling historically separate physical and cyber security budgets into unified capital allocation frameworks. Chief Security Officers are displacing siloed facility management and IT security reporting lines with integrated risk governance structures. This organizational restructuring is most visible in US financial services and healthcare verticals where regulatory scrutiny spans HIPAA, SEC cybersecurity rules, and state biometric privacy laws.
Integrated Security Solutions Market Segmentation
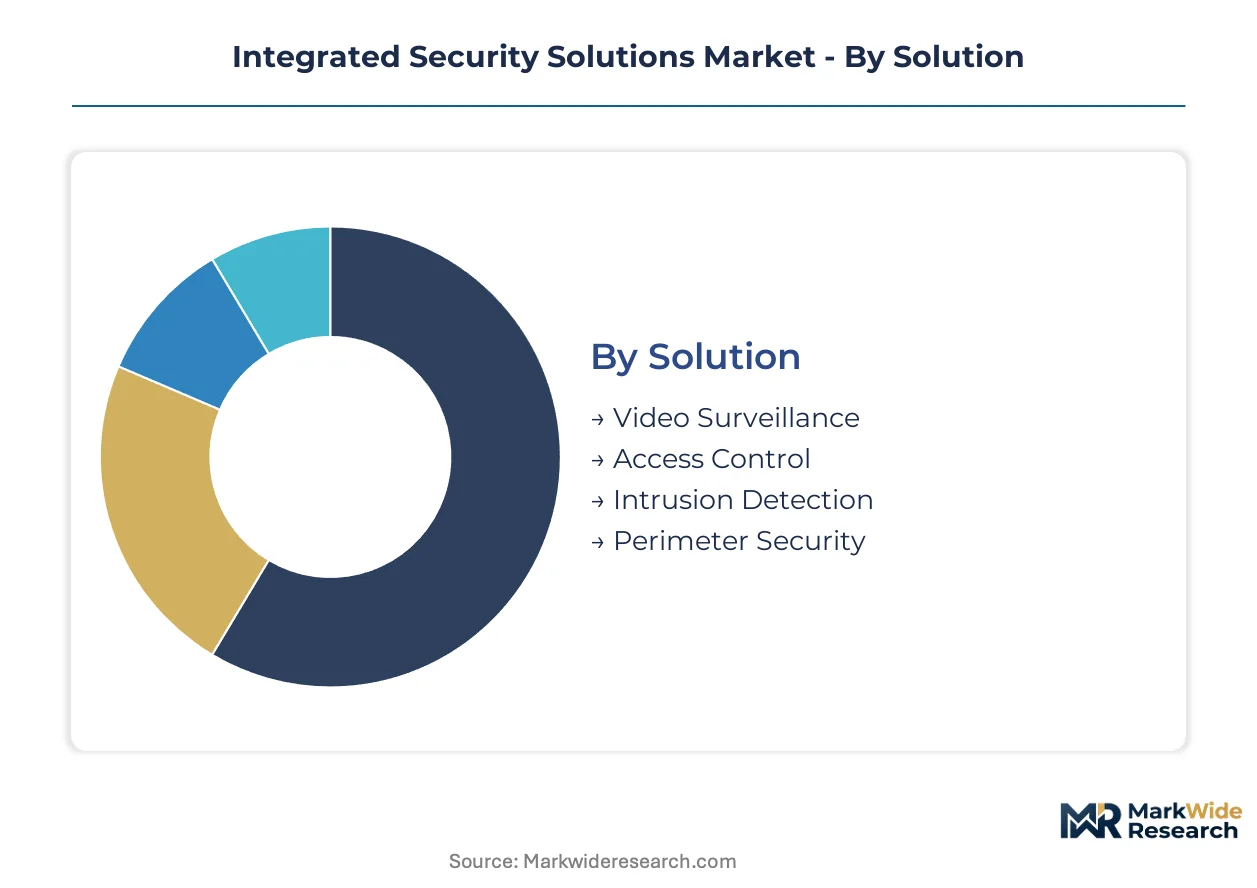
Segmentation in integrated security solutions reveals how procurement channels fragment across solution complexity, regulatory exposure, and infrastructure legacy. Buyers route high-assurance deployments through certified integrators while commoditized segments flow via distributor networks with diverging margin structures.
Solution:
Channel mix varies sharply by solution type, with video surveillance flowing through commercial real estate contractors and access control dominating direct enterprise sales.
- Video Surveillance:IP camera networks with edge analytics capabilities serve commercial property managers and retail operators. Demand concentrates in Singapore's smart city infrastructure where municipal procurement mandates unified data interoperability standards. FCC equipment authorization shapes wireless sensor deployment timelines in US installations.
- Access Control:Biometric and credential-based entry systems integrate physical barriers with identity management protocols. Germany's industrial corridor drives consolidation as automotive and chemical facilities merge physical and cyber defense procurement under single vendor relationships.
- Intrusion Detection:Sensor networks and alarm systems protect perimeter boundaries and interior zones.
- Perimeter Security:Fence-mounted detection, radar, and thermal monitoring for critical infrastructure boundaries.
By volume, Video Surveillance leads. By growth pace, Access Control is expanding most quickly.
End User:
Cost tier segmentation separates high-assurance government contracts with extended qualification cycles from price-sensitive residential installations.
- Commercial:Office complexes, retail chains, and hospitality properties deploy integrated platforms combining video, access, and cyber monitoring. The EU NIS2 Directive is forcing facility operators in energy and transport sectors to consolidate vendor relationships and reject siloed proposals.
- Industrial:Manufacturing plants, refineries, and logistics hubs require sub-100-millisecond alert correlation across electronic and physical domains. France's ANSSI certification frameworks create compliance moats for qualified integrators bidding on critical national infrastructure.
- Government:Federal, state, and municipal installations with mandated security clearances and certification requirements.
- Residential:Single-family homes and multi-unit dwellings with DIY and professionally monitored options.
Commercial captures the largest revenue pool. Industrial posts the steepest expansion trajectory as operational technology security converges with physical protection.
Technology:
Maturity curves separate established on-premises architectures from cloud-native platforms capturing mid-market accounts previously served by fragmented local integrators.
- AI-driven:Machine learning classification of anomalous physical movement patterns displaces rule-based video analytics. EU AI Act conformity requirements extend sales cycles by 8-14 months for European government contracts due to mandatory third-party assessment and CE marking obligations.
- Cloud-based:SaaS-delivered security orchestration platforms reduce capital expenditure and enable rapid deployment. Mid-market accounts in regulated verticals increasingly favor these models despite data sovereignty concerns that hybrid architectures address.
- On-premises:Local server and storage infrastructure retaining dominance in regulated industrial end-user verticals.
- IoT-enabled:Sensor networks with embedded connectivity for distributed monitoring and automated response triggers.
On-premises retains the installed base majority. AI-driven solutions are gaining share fastest as behavioral analytics displace legacy detection methods.
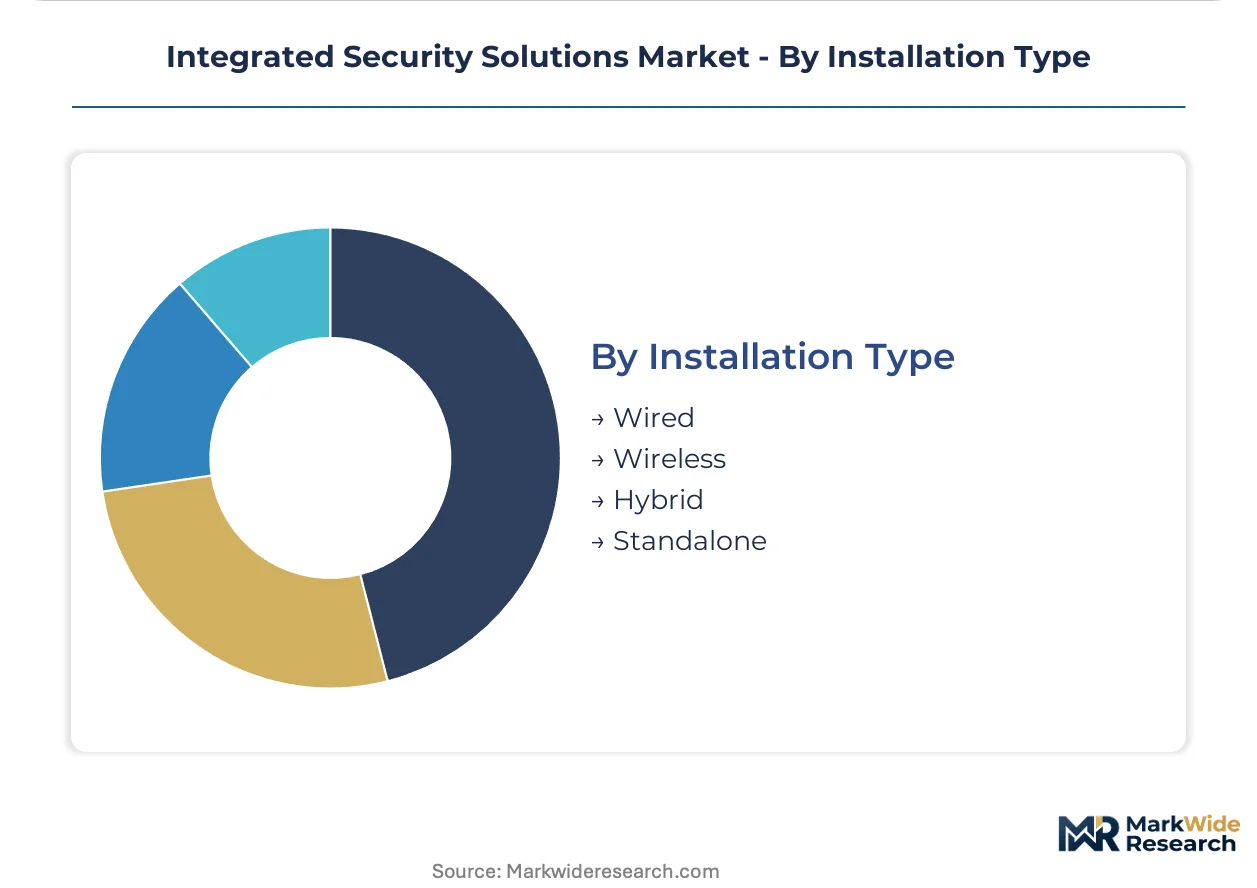
Installation Type:
Supply concentration in wireless chip fabrication creates cost tier differentiation between proprietary hardware-anchored vendors and software-only rivals.
- Hybrid:Edge computing convergence with cloud analytics enables new service models for regulated verticals requiring data sovereignty. Germany's BSI technical guidelines and France's ANSSI frameworks favor these architectures for critical infrastructure where latency and compliance constraints coexist.
- Wired:Ethernet and fiber-based infrastructure delivers deterministic performance for high-assurance government and financial services installations. Legacy analog CCTV with 10-15 year depreciation schedules slows replacement demand in commercial real estate portfolios.
- Wireless:Radio-frequency and cellular-connected devices reducing installation labor in retrofit applications.
- Standalone:Single-function systems without integration requirements for small-scale or temporary deployments.
Wired maintains the largest installed footprint. Hybrid architectures are climbing the fastest as edge-cloud convergence reshapes procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Singapore demonstrate the lowest price elasticity as smart city mandates override procurement discretion, while commercial real estate operators in the United States retain maximum flexibility to delay upgrades across depreciating analog infrastructure cycles.
United States
Financial services and healthcare verticals drive unified security procurement as HIPAA and SEC cybersecurity rules compel consolidated risk governance. FCC equipment authorization standards shape wireless sensor deployment timelines across commercial installations. New York Metro and Greater Boston anchor Fortune 500 campus deployments where Chief Security Officers merge physical and cyber budgets.
Germany
Automotive and chemical facilities in the industrial corridor concentrate demand for hybrid edge-cloud architectures. BSI technical guidelines create compliance moats for qualified integrators bidding on critical national infrastructure. Bavaria and North Rhine-Westphalia host manufacturing clusters merging operational technology security with physical protection procurement.
Singapore
National digital infrastructure programs accelerate unified platform adoption through standardized data interoperability requirements for municipal security systems. Smart city procurement mandates override traditional vendor selection processes. The city-state's critical infrastructure operators exhibit minimal price sensitivity to compliance-driven specifications.
France
ANSSI certification frameworks extend qualification timelines for integrators serving government and critical infrastructure contracts. Automated threat classification systems face mandatory conformity assessments under EU AI Act implementation. Île-de-France hosts defense integrators restructuring development pipelines for explainable AI documentation.
United Kingdom
Financial services regulators drive consolidated security governance structures across London and Southeast commercial campuses. Mid-market accounts increasingly favor cloud-native deployment models despite data sovereignty concerns. The region exhibits accelerating procurement consolidation as CSRD disclosure requirements expand compliance scope.
Integrated Security Solutions Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with networking hardware specialists anchoring unified fabric deployments while cloud-native specialists capture behavioral analytics segments. The competitive structure bifurcates between qualified integrators meeting enterprise-grade certification requirements and commodity installers serving price-sensitive commercial real estate. Three archetypes dominate: hardware-anchored platform vendors, AI-driven threat detection specialists, and cloud-native endpoint security providers. M&A activity concentrates on cybersecurity-physical security convergence capabilities, while strategic partnerships address sub-100-millisecond latency engineering requirements.
Among networking-centric platform providers, Cisco leverages infrastructure footprint to anchor unified security fabric deployments. Palo Alto Networks and Fortinet occupy distinct positions on the hardware-software spectrum, with the former exemplifying AI-driven threat detection intensity and the latter representing proprietary security processing unit scale advantages. These three entities collectively illustrate how vendor differentiation maps to underlying technology architecture choices rather than geographic or vertical segmentation.
| Leading Market Players |
|---|
| Cisco |
| Microsoft Security |
| Palo Alto Networks |
| Zscaler |
| IBM Security |
| Fortinet |
| CrowdStrike |
| Google Cloud Security |
| Check Point Software Technologies |
| Others |
Value Chain & Pricing Dynamics
Edge-deployed neural inference engines replacing centralized server-based video analytics are redrawing supply geography toward Taiwan and South Korea while compressing margins for traditional video management software vendors and elevating hardware-integrated solution pricing power.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value for integrated security deployments, with recurring revenue streams often exceeding initial hardware margins by substantial multiples. Three-tier pricing structure across premium certified integrators, standard enterprise deployments, and economy commodity installers reflects BSI and ANSSI certification moats. Cost compression in the mid-market SaaS tier is intensifying because cloud-native platforms displace fragmented local integrators. Commercial real estate operators exhibit maximum price sensitivity due to 10-15 year analog CCTV depreciation schedules, while Singapore smart city procurement demonstrates minimal elasticity under compliance-driven mandates.
Supply Chain Analysis
Extended lead times for advanced fabrication nodes have become the defining operational constraint for hardware-anchored vendors competing on sub-100-millisecond latency specifications. Proprietary security processing units draw from Taiwan, South Korea, and USA fabrication capacity, with silicon wafers, specialized ASIC designs, and edge inference accelerators constituting critical input categories. Single-source vulnerability in Taiwan semiconductor concentration presents structural supply chain risk. Distribution runs through certified integrator networks for high-assurance government and industrial contracts, while commercial real estate flows via distributor channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among Fortune 500 Chief Security Officers is shifting buyer power toward unified platform vendors and away from fragmented point-solution providers, compressing vendor panels and extending qualification timelines.
For Market Incumbents: Consolidate through backward integration into proprietary security processing unit fabrication to defend against software-only rivals exploiting cloud-native cost structures. Anchor unified security fabric deployments across campus environments by leveraging existing networking infrastructure relationships. Fortify certification investments under EU NIS2 Directive and BSI technical guidelines to deepen compliance moats against emerging entrants.
For New Entrants and Emerging Players: Differentiate on AI-driven behavioral analytics specialization targeting European government contracts where EU AI Act conformity requirements extend incumbent sales cycles and create service-layer opportunities. Penetrate the cloud-native mid-market segment previously served by fragmented local integrators through SaaS-delivered security orchestration platforms. Pursue partnership-based go-to-market models with established networking hardware vendors to bypass direct certification barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed physical security integrators lacking cybersecurity convergence capabilities and facing compressed multiples from procurement consolidation. Five-to-ten year viability favors targets with hybrid edge-cloud architecture expertise and dual BSI-ANSSI certification credentials. Monitor EU AI Act implementation velocity as the critical inflection signal for automated threat classification system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies physical access control with Palo Alto Networks AI-driven threat detection protocols. |
| Certification Investment | Accelerates BSI and ANSSI qualification timelines for German industrial corridor contracts. |
| Strategic Partnership | Addresses sub-100-millisecond latency engineering through edge-cloud convergence architectures. |
| Acquisition of Specialist Firm | Fills AI-driven behavioral analytics gaps for EU AI Act compliance documentation requirements. |
| Geographic Expansion | Captures Singapore smart city procurement through standardized data interoperability mandates. |
Study Parameters
A spread of perspectives from Chief Security Officers, certified integrator technical directors, government procurement officers, and cloud platform engineers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU NIS2 Directive implementation guidance, BSI technical guideline documentation, and ANSSI certification framework records. Bottom-up segment sizing triangulated with top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled encompass solution type, end-user vertical, deployment technology, and installation architecture across the projection horizon. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory inflection points. Forecast inputs incorporated EU AI Act conformity assessment timelines, smart city infrastructure procurement schedules, and semiconductor fabrication capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of NIS2 Directive mandates or accelerated Taiwan semiconductor supply diversification would require recalibration. Forecasts reflect documented assumptions regarding procurement consolidation velocity and cloud-native platform substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Asia-Pacific Urban Security Screening Market
Security and Surveillance
Global Acoustic Hailing Devices Market
Security and Surveillance
Smart Security in Healthcare Market
Security and Surveillance
Cargo Container X-Ray Inspection Systems Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Airport Baggage Screening Systems Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Latin America Electronics Security Market
Security and Surveillance
Airport Security Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
Europe Security Testing Market
Security and Surveillance
Surveillance Radars Market