
 Integrated Security Services Market | 2026-2036
Integrated Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Security Services Market Foresight
The United Arab Emirates is tilting toward integrated security capacity through smart city investments and critical infrastructure hardening. Cisco dominates Middle East enterprise deployments with its converged networking-security architecture. IBM Security anchors large government and financial contracts through its managed security services division. Accenture Security differentiates via consulting-led transformation engagements that bundle physical and cyber operations.
Integrated security services combine physical protection systems, cybersecurity operations, and risk management into unified service architectures that coordinate threat detection, access governance, and incident response across facilities and networks. These services typically deploy sensor fusion platforms that correlate video analytics, access log data, and network telemetry through centralized security operations centers to enable real-time situational awareness. CCTV Surveillance and Access Control represent mature revenue pools with established margin structures, while Cloud-Based Solutions within the Technology dimension is expanding fastest as enterprises migrate security operations off-premises. The Delivery Model split shows Managed Services capturing disproportionate growth as buyers seek to outsource operational complexity and transfer capital expenditure to operational budgets.
FCC regulations govern wireless spectrum use for security communications in the US, while EU GDPR and NIS2 frameworks mandate data protection and incident reporting standards that reshape service provider liability and contract terms across European deployments. The EU AI Act further constrains biometric and automated surveillance components by requiring conformity assessments before market placement. Stakeholders must monitor how converging physical-cyber regulatory regimes will force restructuring of service portfolios and certification investments.
Market Dynamics
Critical infrastructure operators are consolidating vendor relationships under unified physical-cyber contracts, compressing procurement cycles and forcing service providers to restructure delivery models around integrated outcome guarantees rather than discrete system sales.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident reporting and supply chain security requirements are compelling European energy and transport operators to upgrade to managed detection and response services that unify facility monitoring with network defense.
- Sensor fusion platforms:Correlation engines that integrate video analytics, access logs, and network telemetry into single-pane situational awareness are accelerating replacement cycles for siloed security infrastructure.
- Germany:Industrial facility operators are bundling physical protection and cybersecurity procurement under single-source contracts, creating anchor demand for integrated service architectures.
Market Restraints
- Specialized talent scarcity:Professionals capable of operating converged physical-cyber security operations centers command premium compensation, elevating service delivery costs.
- EU AI Act conformity assessments:Biometric and automated surveillance components face extended pre-market certification timelines, delaying deployment of facial recognition and behavioral analytics packages.
- Legacy system integration:Existing access control and CCTV investments in mature facilities resist seamless connectivity with cloud-native security platforms, fragmenting operational workflows.
Strategic Opportunities
- United Arab Emirates smart city investments:Critical infrastructure hardening programs are creating demand for converged networking-security architectures across government and commercial developments.
- Managed services delivery:Buyer preference for operational expenditure models over capital-intensive system ownership is opening recurring revenue streams for outsourced security operations.
- Cloud migration tailwinds:Enterprises migrating security operations off-premises are seeking providers capable of unifying on-premise physical sensors with cloud-native cyber monitoring.
Industry Challenges
- Multi-domain certification complexity:Service providers must maintain parallel credentials across physical security licensing, cybersecurity frameworks, and sector-specific compliance regimes.
- Interoperability engineering:Correlating data streams from proprietary access control, video management, and network detection systems demands custom integration work that erodes margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Security Services Market |
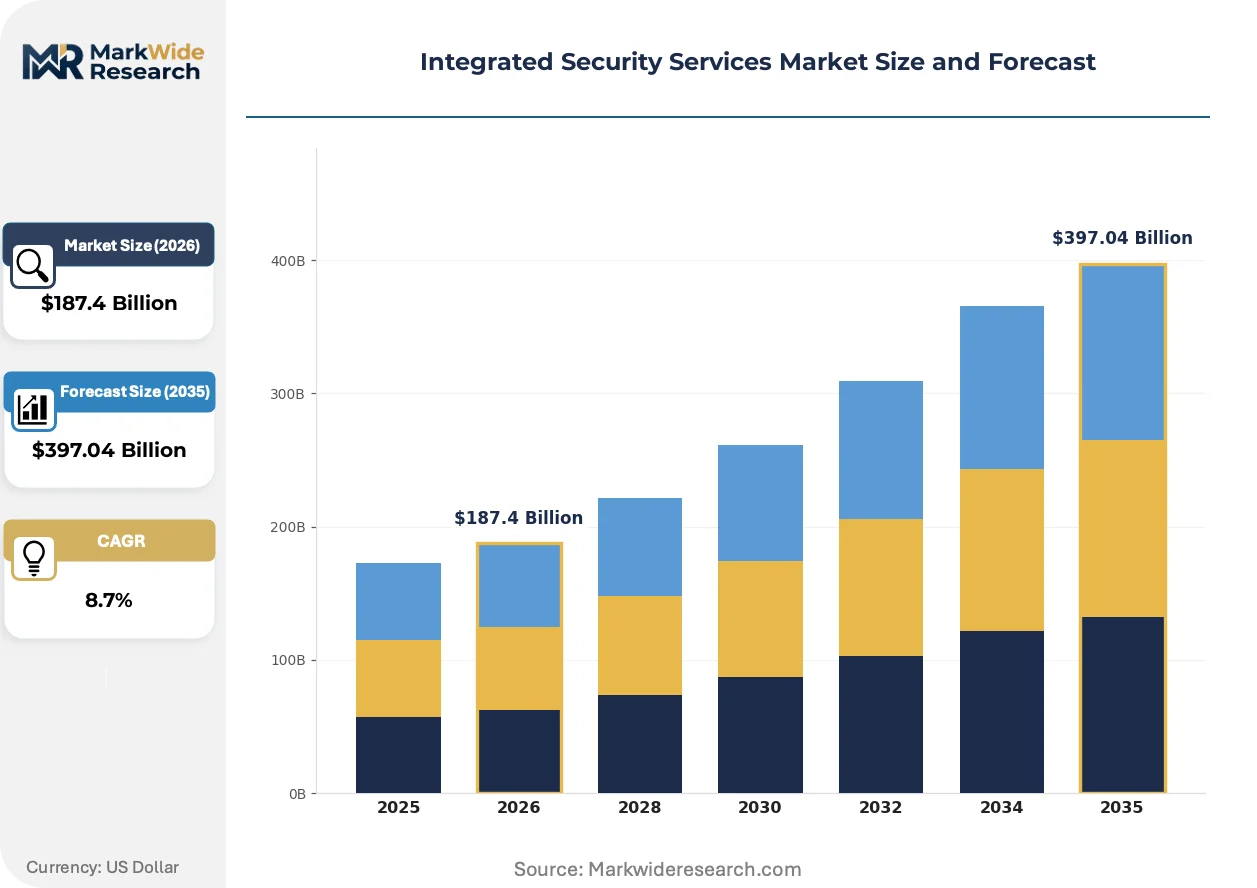
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: CCTV Surveillance, Access Control, Intrusion Detection, Alarm Monitoring End User: Residential, Commercial, Government, Industrial Technology: IoT Security, Cloud-Based Solutions, Biometric Systems, Wireless Technologies Delivery Model: Managed Services, Event Monitoring, On-Premises, Hybrid Solutions |
| Companies Covered | Verizon, Check Point, Cisco, NTT DATA, Trustwave, IBM Security, AT&T Cybersecurity, EY, Accenture Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Security Services Market Shifts & Advancements
Convergence between physical security infrastructure and cybersecurity operations is dissolving traditional procurement boundaries, forcing architectural redesigns that treat facilities and networks as unified attack surfaces.
AI-driven video analytics is collapsing the distinction between passive surveillance and active threat detection. These systems autonomously flag anomalous behaviors across facility perimeters and correlate visual cues with network intrusion indicators. Critical infrastructure operators in energy and transportation are deploying these capabilities at scale. The technology is collapsing response timelines from minutes to seconds by fusing sensor inputs through centralized security operations centers.
The EU AI Act imposes conformity assessment requirements on biometric identification and automated surveillance systems before market placement. Security service providers must document risk management systems and accuracy testing protocols for AI components. European deployments of facial recognition and crowd analytics face extended certification timelines, compressing vendor profit margins and favoring larger providers with dedicated regulatory affairs capacity.
Buyers are consolidating vendor relationships under enterprise-wide security service contracts that bundle physical protection, cyber monitoring, and risk consulting. Discrete system sales and break-fix maintenance agreements are losing share to subscription-based managed services with guaranteed uptime and response commitments. German industrial operators pioneered this shift, and the model is propagating through European energy and transport sectors.
Integrated Security Services Market Segmentation
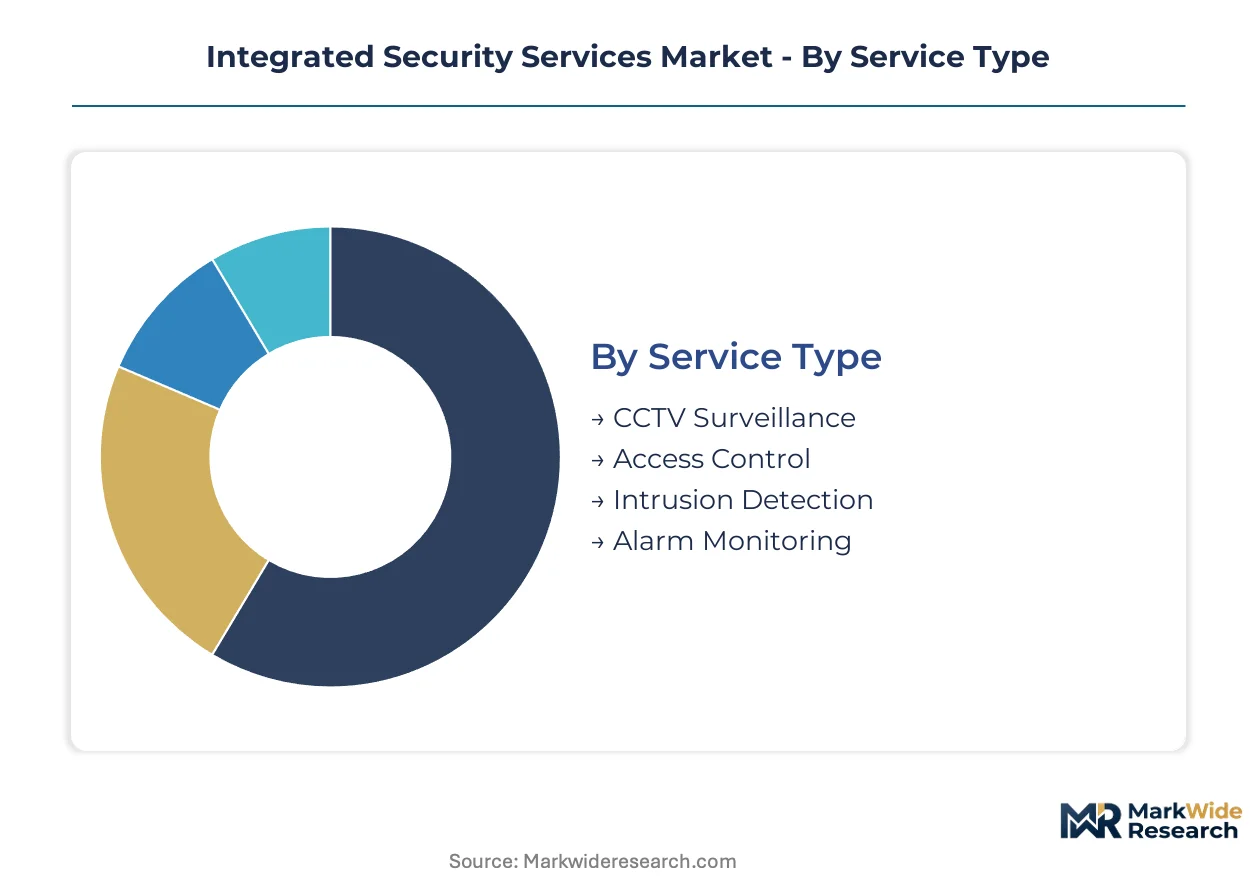
Segmentation in integrated security services reveals how procurement complexity varies dramatically across service architectures. Buyers with converged physical-cyber requirements demand fundamentally different support structures than those purchasing discrete capabilities.
Service Type:
After-sales service intensity peaks where sensor networks require continuous calibration and software updates to maintain detection accuracy.
- CCTV Surveillance:Camera networks with AI analytics demand ongoing firmware management and lens maintenance to sustain image quality. German industrial operators bundle these services under multi-year uptime guarantees with penalty clauses for downtime.
- Access Control:Credential systems and biometric readers require periodic recalibration and integration with HR databases. Demand concentrates in UAE government facilities modernizing legacy card readers with mobile-enabled authentication.
- Intrusion Detection:Perimeter sensors and motion detectors need seasonal sensitivity adjustments.
- Alarm Monitoring:Central station verification services operate on subscription revenue models.
By volume, CCTV Surveillance leads. By growth pace, Access Control is ahead.
End User:
Cost tier differentiation separates capital-intensive industrial deployments from operational-expenditure models favored by commercial buyers.
- Industrial:Manufacturing and energy facilities demand 99.9% availability commitments with on-site response teams. German chemical plants and UAE oil terminals anchor this segment through unified physical-cyber contracts.
- Government:Critical infrastructure and defense installations require cleared personnel and air-gapped systems. EU NIS2 compliance is forcing upgrades across transport and energy ministries.
- Commercial:Office complexes and retail chains prioritize scalable cloud monitoring.
- Residential:Smart home integration drives DIY installation with professional monitoring subscriptions.
Industrial captures the highest contract values. Government shows the steepest expansion trajectory.
Technology:
Application context determines whether edge computing or centralized processing architectures prevail.
- Cloud-Based Solutions:Off-premises security operations centers aggregate telemetry from distributed facilities. European enterprises migrating from on-premise video management systems are accelerating procurement.
- IoT Security:Sensor networks connecting access readers, cameras, and environmental monitors require device-level certificate management. UAE smart city deployments are scaling these architectures across municipal infrastructure.
- Biometric Systems:Facial recognition and fingerprint authentication face EU AI Act certification delays.
- Wireless Technologies:5G and LoRaWAN backhaul reduce cabling costs for perimeter deployments.
Cloud-Based Solutions dominate new deployments. IoT Security is expanding most quickly.
Delivery Model:
Customer type separates buyers seeking full operational transfer from those retaining in-house control.
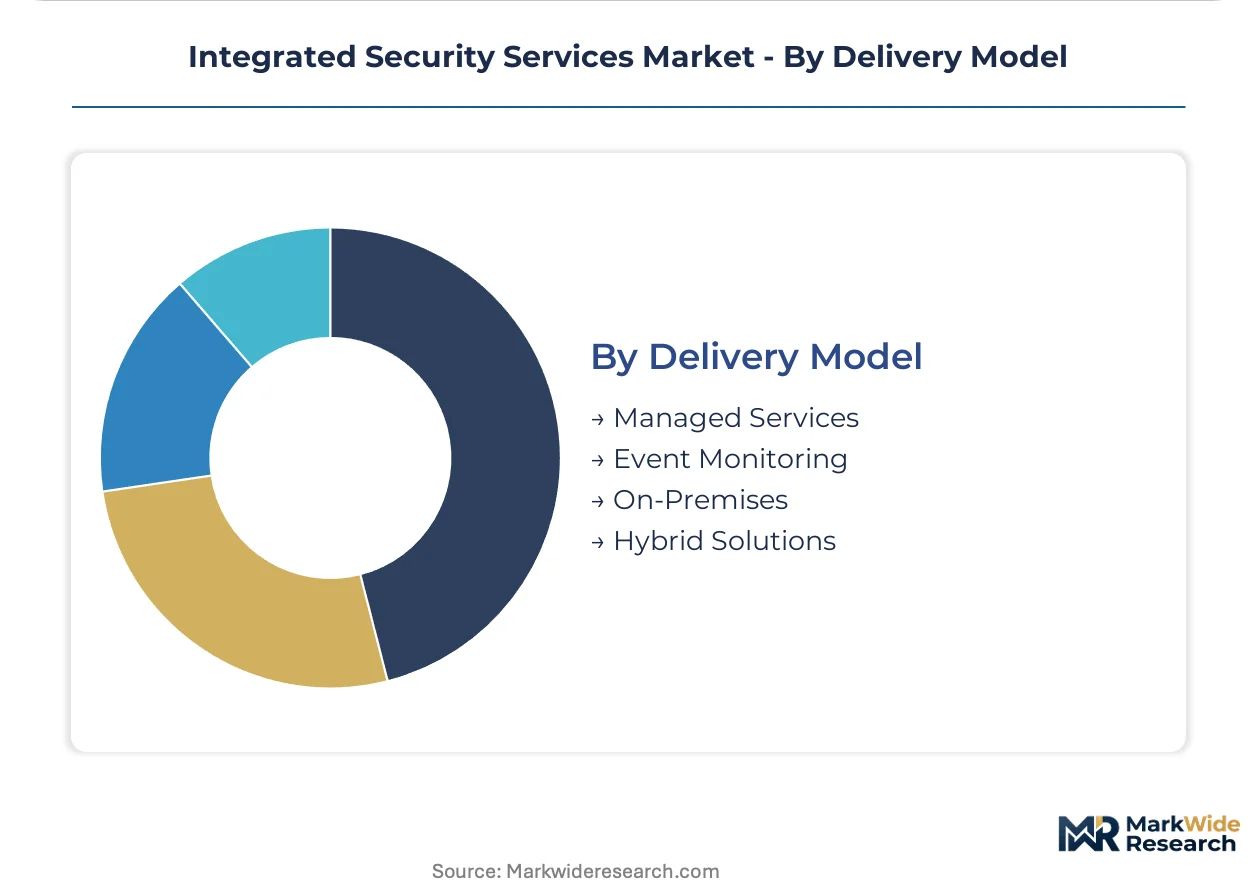
- Managed Services:Comprehensive outsourcing of security operations including staffing, maintenance, and incident response. German industrial operators pioneered this model; it now propagates through European energy and transport sectors.
- Hybrid Solutions:Split architectures keep sensitive video processing on-premise while pushing analytics to cloud platforms. Demand concentrates where data residency requirements conflict with AI processing needs.
- Event Monitoring:Centralized verification of alarms with dispatch coordination.
- On-Premises:Self-operated security centers with vendor support contracts.
Managed Services leads by recurring revenue. Hybrid Solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider networks concentrate in Germany, the UAE, and the United States where critical infrastructure operators are consolidating procurement under unified physical-cyber contracts. Regulatory divergence across jurisdictions is fragmenting certification requirements and reshaping vendor liability structures.
United States
FCC spectrum regulations govern wireless security communications while energy operators modernize grid protection. The IRA's infrastructure funding accelerates substation hardening programs. Texas and California anchor demand through utility-scale deployments of converged monitoring systems.
Germany
Industrial facility operators bundle physical protection and cybersecurity under single-source contracts. EU NIS2 mandates incident reporting for energy and transport sectors. The Ruhr industrial corridor and Bavarian chemical clusters drive procurement of managed detection and response services.
United Arab Emirates
Smart city investments and critical infrastructure hardening programs expand integrated security capacity. MOHAP and federal regulators coordinate data protection standards across government and commercial developments. Dubai and Abu Dhabi municipal authorities deploy converged networking-security architectures at scale.
United Kingdom
GDPR and post-Brexit data residency requirements reshape cloud security procurement. Financial services regulators mandate operational resilience testing for critical systems. The City of London and Thames Valley tech corridors concentrate demand for hybrid on-premise and cloud-native monitoring.
Japan
METI guidelines promote IoT security standards for industrial facilities. Manufacturing conglomerates integrate facility monitoring with supply chain cyber defenses. The Kanto region around Tokyo and Osaka's Kansai industrial belt lead deployment of sensor fusion platforms.
Integrated Security Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, analytics engines, and credential hardware. The vendor landscape organizes around three tiers: global consultancies bundling physical and cyber operations, telecommunications carriers with managed security service divisions, and pure-play cybersecurity firms extending into facility monitoring. Consolidation pressures intensify as buyers demand unified outcome guarantees rather than discrete product sales. Strategic moves center on vertical capability acquisition and managed service contract expansion.
Within the telecommunications carrier tier, Verizon and AT&T Cybersecurity occupy positions anchored by network infrastructure and enterprise customer relationships. Cisco exemplifies the converged platform archetype, bridging networking equipment with security operations. IBM Security sits within the enterprise consulting segment, representing the integrated transformation model that German industrial operators pioneered.
| Leading Market Players |
|---|
| Verizon |
| Check Point |
| Cisco |
| NTT DATA |
| Trustwave |
| IBM Security |
| AT&T Cybersecurity |
| EY |
| Accenture Security |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp logistics corridor governs equipment import costs for European security integrators, compressing margins on cloud-native deployments while amplifying price premiums for certified on-premise installations. Supply concentration in German industrial automation and Taiwanese sensor manufacturing feeds tiered pricing structures that separate compliance-heavy government contracts from cost-optimized commercial deployments.
Pricing Analysis
EU NIS2 Directive dictates the pricing tier structure by mandating incident reporting capabilities that only premium managed service packages deliver. Three-tier pricing stratifies across certified government-grade, industrial-hardened, and standard commercial levels. Certification under EU AI Act conformity assessment protocols commands substantial premiums for biometric components. Cost compression in the commercial tier intensifies as cloud-native entrants displace legacy on-premise vendors. Government buyers exhibit minimal price sensitivity due to compliance mandates, while mid-market commercial facilities negotiate aggressively on per-camera and per-access-point metrics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk profiles for video analytics hardware and network security appliances. Component sourcing concentrates in Germany for industrial control systems, Taiwan for optical sensors and semiconductors, and China for mass-market camera assemblies. Supply chains draw from specialized silicon for AI inference engines, hardened cabling for perimeter installations, and cryptographic modules for access credential systems. Single-source vulnerability in facial recognition algorithm licensing creates procurement bottlenecks for European deployments. Distribution runs through authorized integrator networks that maintain parallel physical security licensing and cybersecurity framework certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated security services represent a high-growth disruption as AI-driven sensor fusion collapses response timelines from minutes to seconds and regulatory mandates force wholesale procurement consolidation. The EU AI Act and NIS2 Directive together eliminate discrete vendor strategies, rewarding unified platform architectures with compliance-embedded delivery.
For Market Incumbents: Build regulatory affairs capacity as a moat against certification delays that erode margins. Acquire specialized biometric testing laboratories to compress EU AI Act conformity timelines. Expand managed services contracts with guaranteed uptime commitments that transfer operational risk from industrial buyers. Deepen backward integration into sensor manufacturing to secure supply continuity against Taiwanese semiconductor bottlenecks. For New Entrants and Emerging Players: Establish a beachhead in UAE smart city infrastructure where converged networking-security architectures lack entrenched vendor relationships. Target mid-sized German chemical facilities seeking alternatives to incumbent system integrators. Develop cloud-native sensor fusion platforms that undercut on-premise legacy installations on total cost of ownership. Position through channel partnerships with telecommunications carriers rather than direct enterprise sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with dual physical-cyber certification coverage over component specialists facing commoditization. Long-term viability hinges on recurring revenue density from managed services contracts rather than discrete system sales. Acquisition targets should demonstrate existing EU AI Act conformity assessment progress and established relationships with German industrial operators. Watch sensor fusion patent filings as an inflection indicator for platform differentiation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Services Contract Expansion | Captures recurring revenue from German industrial operators consolidating vendor relationships under unified physical-cyber agreements. |
| EU AI Act Conformity Investment | Accelerates market placement timelines for biometric identification systems facing extended certification requirements. |
| Sensor Fusion Platform Development | Enables real-time correlation of video analytics, access logs, and network telemetry through centralized security operations centers. |
| UAE Smart City Partnership | Secures anchor demand from Dubai and Abu Dhabi municipal authorities deploying converged networking-security architectures. |
| Biometric Testing Laboratory Acquisition | Compresses pre-market certification delays that currently fragment vendor profit margins across European deployments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with security operations directors, managed services procurement leads, regulatory compliance officers, and facility management executives; and secondary validation against EU NIS2 implementation guidance, FCC spectrum allocation records, UAE smart city procurement databases, and customs trade data for security equipment imports. Bottom-up triangulation across facility-level deployment records and top-down reconciliation against service provider contract disclosures anchored volume estimates.
Forecast inputs encompassed service type segmentation by after-sales intensity, technology migration patterns from on-premise to cloud-native architectures, and delivery model shifts toward operational expenditure structures. Segmentation dimensions modeled include service architecture convergence level, end-user compliance tier, technology deployment model, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves calibrated against historical managed services penetration rates and sensor replacement cycles.
Stress conditions across EU AI Act enforcement intensity, Taiwanese semiconductor supply continuity, and German industrial capital expenditure cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and certification capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Latin America Security Services Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market
Security and Surveillance
India CCTV Market
Security and Surveillance
Global Traveler Security Services Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Europe Border Security Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
Smart Security Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Global Security As a Service Market