
 Wireless Security System Market | 2026-2036
Wireless Security System Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Security System Market Intelligence
The direct-to-consumer (DTC) sales channel, amplified by e-commerce platforms, is reshaping competitive positioning among system providers. SimpliSafe, Inc. leverages a strong DTC model to reach residential customers directly with its DIY installation kits. In contrast, Johnson Controls International plc sustains its market presence through established professional installer networks and B2B distribution partnerships for commercial premises. Ring LLC, an Amazon subsidiary, dominates the video doorbell sub-segment with its deeply integrated smart home ecosystem.
A wireless security system comprises a network of interconnected devices that communicate without physical wiring to a central control panel. These systems operate on various radio frequencies, utilizing communication protocols like Wi-Fi, Z-Wave, or Zigbee to transmit signals from sensors and cameras. Surveillance cameras, particularly those featuring high-definition video and cloud storage, command a significant share of the product mix. While residential customers constitute the largest end-user base, the small business segment is expanding rapidly due to lower installation costs.
In the United States, FCC regulations govern the radio frequency spectrum and transmission power of wireless security components. Concurrently, Europe's GDPR imposes strict data privacy and processing standards on video surveillance and associated cloud services. The development of new products is influenced by these divergent regulatory landscapes. Stakeholders must therefore balance the push for enhanced connectivity features with the increasing stringency of data protection mandates across key markets.
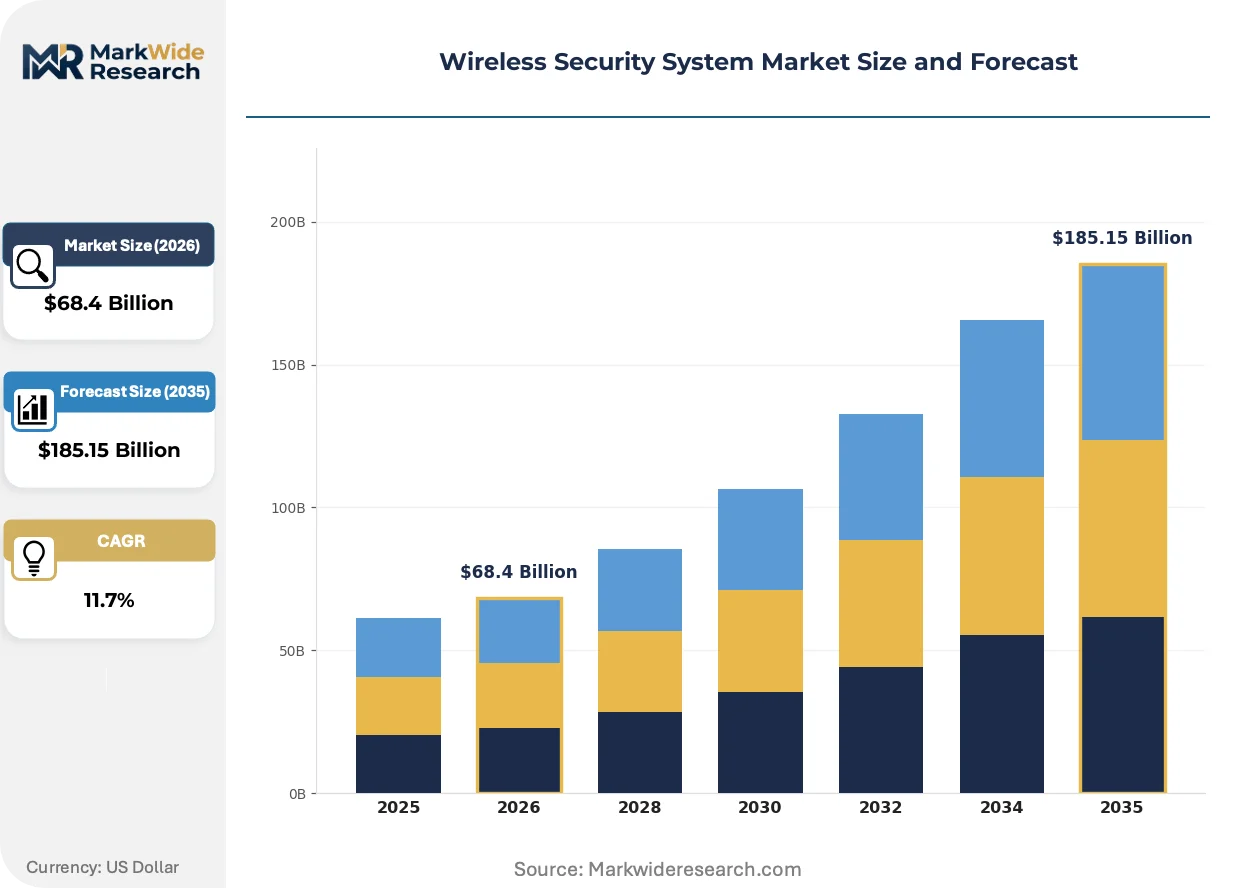
Market Dynamics
The divergence between feature-rich AI capabilities and stringent data privacy mandates like Europe's GDPR is the central force defining product development. This tension dictates engineering priorities, balancing analytics with consumer data protection and regulatory compliance.
Growth Catalysts
- AI-Powered Analytics:The integration of artificial intelligence and machine learning into cameras for real-time object recognition and behavioral analysis enhances threat detection accuracy.
- Small Business Adoption:Lower installation costs and scalable, cloud-managed solutions are driving rapid adoption among small and medium-sized enterprises seeking affordable security.
- Smart Home Ecosystems:The expansion of smart home platforms in the United States and Europe creates pull-through demand for integrated security devices like cameras and sensors.
Market Restraints
- Radio Frequency Congestion:High device density in residential and commercial areas creates interference on unlicensed Wi-Fi and Z-Wave spectrum, impacting system reliability and performance.
- Protocol Interoperability:A lack of a universal communication standard across proprietary, Z-Wave, and Zigbee protocols creates fragmentation, limiting device compatibility for end-users.
- Data Privacy Compliance Burden:Regulations like GDPR impose significant development and operational costs on manufacturers, particularly for cloud storage and video processing services.
Strategic Opportunities
- 5G-Enabled Connectivity:Leveraging 5G cellular networks for primary or backup communication can provide higher bandwidth and lower latency for 4K video streams and faster response.
- Insurance Sector Partnerships:Collaborations with insurance carriers to offer policy discounts for homes and businesses with verified, professionally monitored wireless security systems present a new sales channel.
- Underpenetrated Emerging Markets:Residential and small business segments in regions like Latin America and Southeast Asia offer significant greenfield growth potential for security providers.
Industry Challenges
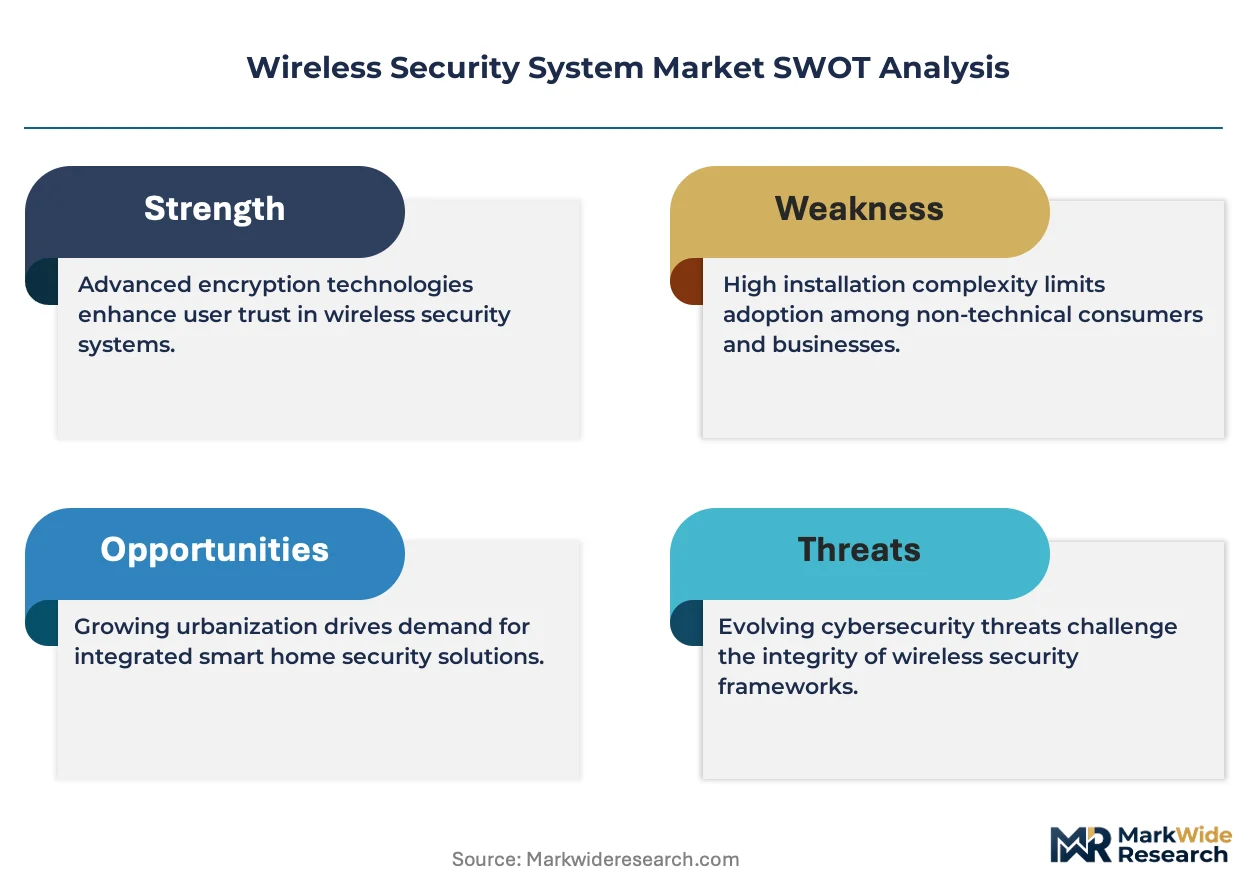
- Evolving Cybersecurity Threats:The proliferation of connected endpoints creates a vast attack surface, demanding continuous firmware updates and robust encryption protocols to defend against breaches.
- Installer Skill Gaps:A shortage of technicians trained in IP networking and complex system integration limits growth in the professionally installed commercial security segment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Security System Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motion Sensors, Door Window Sensors, Surveillance Cameras, Control Panels, Smoke Detectors Technology: Zigbee, Z-Wave, Wi-Fi, Bluetooth, Cellular Application: Home Monitoring, Commercial Premises, Government Buildings, Educational Institutions, Warehouses End User: Residential Customers, Small Businesses, Corporate Entities, Property Management Firms |
| Companies Covered | ADT Inc., Honeywell International Inc., Johnson Controls International plc, Vivint Smart Home, Inc., SimpliSafe, Inc., Ring LLC, Bosch Security Systems, Hikvision Digital Technology Co., Ltd., Axis Communications AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Security System Market Strategic Shifts & Innovations
Market evolution is defined by the transition from hardware-centric security to service-oriented models. This pivot emphasizes recurring revenue from cloud storage, monitoring, and AI analytics, altering vendor value propositions and customer relationships.
Edge computing integrates AI processing directly onto cameras or local gateways. Privacy-conscious residential users and small businesses are adopting this technology to minimize data transmission to the cloud. This trend is virtualizing the need for constant, high-bandwidth cloud connectivity for real-time event analysis, reducing latency and operational costs.
Europe's pending AI Act introduces a risk-based framework for artificial intelligence systems, directly impacting video surveillance. It compels manufacturers to increase transparency in algorithm training and data usage to avoid high-risk classifications. The commercial security segment, especially systems used for monitoring public-access areas, must adapt product designs to comply.
Subscription-based models are displacing one-time hardware sales as the primary purchasing method for security systems. This "Security-as-a-Service" approach disrupts the traditional installer channel by shifting revenue from upfront equipment markups to recurring monthly fees. The shift is most pronounced in the North American residential and DIY small business markets.
Wireless Security System Market Segmentation
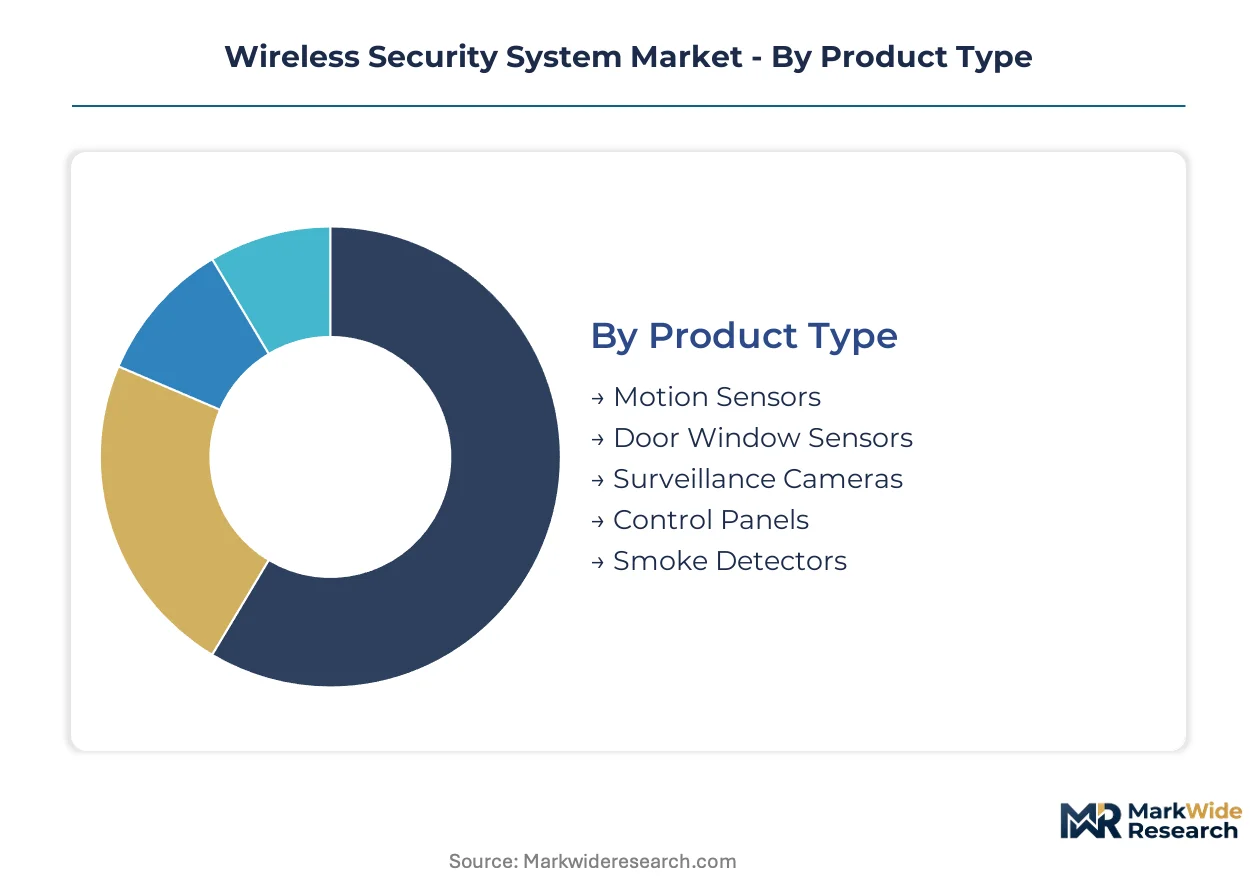
Understanding the varied requirements across different market segments is critical for strategic product development and market penetration in the wireless security system industry. This segmentation analysis provides a granular view of the components, technologies, applications, and end-users driving demand.
Product Type:
The after-sales service intensity varies significantly across product types, influencing ongoing revenue streams and customer loyalty for system providers.
- Surveillance Cameras:These devices capture high-definition video feeds, often integrating AI for real-time object recognition and behavioral analytics, demanding robust cloud storage and processing capabilities. Demand concentrates in both residential smart home ecosystems and commercial premises requiring advanced threat detection.
- Control Panels:Centralized hubs manage all interconnected devices, processing sensor data and enabling system arming/disarming, often with touchscreen interfaces and remote access via mobile applications. These panels are essential for system functionality, with demand driven by the need for integrated system management across all end-user segments.
- Motion Sensors:These components detect movement within a designated area, triggering alarms or recording events, primarily using passive infrared (PIR) technology.
- Door Window Sensors:Comprising two magnetic parts, these sensors detect when a door or window is opened, serving as a primary perimeter defense for homes and businesses.
- Smoke Detectors:Integrated into wireless systems, these devices sense smoke particles, providing early warning of fires and often linking to emergency services.
Surveillance Cameras hold the largest share; momentum sits with Control Panels.
Technology:
Different communication technologies carry distinct cost implications for both hardware and ongoing operational expenses, impacting overall system affordability and performance.
- Wi-Fi:Leveraging existing internet infrastructure, Wi-Fi connectivity offers high bandwidth for video streaming and broad compatibility with smart home devices, though it can suffer from network congestion. This technology is widely adopted in residential settings due to its ubiquity and ease of integration.
- Cellular:Providing an independent communication channel, cellular connectivity acts as a reliable primary or backup link, ensuring system functionality even during power outages or internet disruptions, making it crucial for professional monitoring. Demand is increasing for 5G-enabled solutions in both residential and commercial applications.
- Zigbee:A low-power, mesh networking protocol, Zigbee is ideal for battery-operated sensors due to its energy efficiency and ability to extend network range.
- Z-Wave:Another low-power wireless protocol, Z-Wave specializes in home automation, offering robust signal transmission and interoperability across a wide range of smart devices.
- Bluetooth:Primarily used for short-range device pairing and direct control, Bluetooth enables local connectivity for accessories like keypads or remote controls within a security system.
Wi-Fi technology dominates for ease of integration; Cellular solutions are gaining traction for reliability.
Application:
The diverse application landscape reflects varying security needs across distinct customer types, each requiring tailored solutions and feature sets.
- Home Monitoring:This segment encompasses systems designed for residential properties, focusing on intruder detection, video surveillance, and smart home integration to provide safety and convenience for homeowners. Demand is high in the United States, driven by smart home adoption.
- Commercial Premises:Solutions for businesses prioritize comprehensive surveillance, access control, and remote monitoring capabilities, often integrating with existing building management systems. Small businesses are rapidly adopting these systems due to lower installation costs.
- Government Buildings:These applications require highly secure, robust systems with advanced access control and comprehensive surveillance to protect critical infrastructure and sensitive information.
- Educational Institutions:Security systems in schools and universities focus on campus-wide surveillance, access management, and emergency response capabilities to ensure student and staff safety.
- Warehouses:Large storage facilities utilize wireless security for perimeter protection, inventory monitoring, and deterring theft, often requiring extensive sensor networks and high-definition cameras.
Home Monitoring comprises the largest segment; Commercial Premises are expanding due to specific business needs.
End User:
End-user segments represent different volume thresholds and purchasing behaviors for wireless security solutions, influencing distribution strategies and product customization.
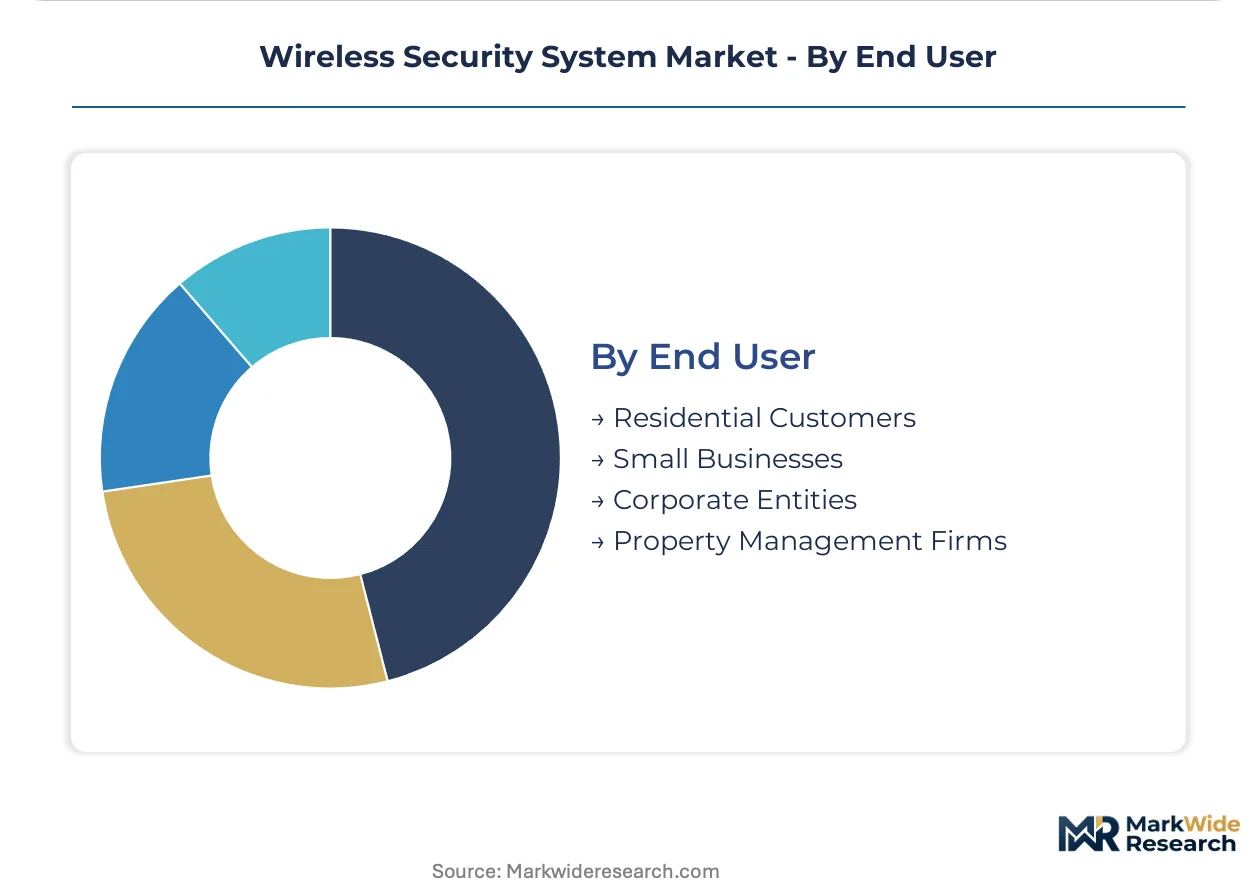
- Residential Customers:Individual homeowners constitute the largest end-user base, often seeking DIY installation kits and integrated smart home functionality, prioritizing affordability and ease of use. High consumer adoption of smart home ecosystems in the United States drives this segment.
- Small Businesses:This segment includes enterprises with limited budgets, seeking scalable, cloud-managed security solutions that offer lower installation costs and remote monitoring capabilities. Rapid adoption among small and medium-sized enterprises is a significant growth catalyst.
- Corporate Entities:Large corporations require enterprise-grade security systems, often involving complex integrations, professional monitoring, and compliance with stringent data protection standards like GDPR.
- Property Management Firms:These firms deploy wireless security across multiple residential or commercial properties, seeking centralized management, remote access, and cost-effective scalability for their portfolios.
Residential Customers form the largest user base; Small Businesses are experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC regulations in the United States anchor product development, particularly for radio frequency spectrum and transmission power of wireless security components. This market sees strong pull-through demand from high consumer adoption of smart home ecosystems. The focus remains on integrated, user-friendly security solutions for residential applications.
United States
High consumer adoption of smart home ecosystems drives demand for integrated security devices and DIY installation kits. FCC regulations govern the radio frequency spectrum and transmission power of wireless security components. Silicon Valley and other tech hubs foster innovation in integrated smart home security platforms and services.
Germany
Corporate entities and privacy-conscious residential users prioritize robust, compliant wireless security systems. Europe's GDPR imposes strict data privacy and processing standards on video surveillance and associated cloud services. The Munich region sees development of AI-powered edge computing solutions for enhanced data protection.
United Kingdom
Insurance sector partnerships and smart home integration create specific demand for verified, professionally monitored systems. UK GDPR influences data processing for cloud storage and video analytics services post-Brexit. London's tech hubs foster startups focused on subscription-based security models and service offerings.
China
Rapid urbanization and smart city initiatives stimulate demand for extensive surveillance and access control systems. GB standards influence product safety and performance requirements for all wireless security components. Shenzhen manufacturers focus on high-volume production of surveillance cameras and integrated security platforms.
India
Underpenetrated emerging markets, particularly the small business segment, offer significant greenfield growth potential. BIS standards ensure product quality and compatibility across diverse wireless security system offerings. Bangalore's tech ecosystem supports development of affordable, cloud-managed security solutions for scaling enterprises.
Wireless Security System Market Key Industry Players
Direct-to-consumer (DTC) specialists and established professional service providers split the market. This structural divergence creates distinct competitive positioning, with some vendors focusing on residential DIY and others on commercial B2B solutions. Strategic acquisitions and ecosystem integration represent dominant competitive moves among market participants.
Within the direct-to-consumer archetype, SimpliSafe, Inc. and Ring LLC exemplify companies leveraging e-commerce platforms to reach residential customers directly. SimpliSafe offers DIY installation kits, while Ring LLC, an Amazon subsidiary, dominates the video doorbell sub-segment. Johnson Controls International plc anchors the professional installation segment, sustaining its market presence through established networks and B2B distribution partnerships for commercial premises.
| Leading Market Players |
|---|
| ADT Inc. |
| Honeywell International Inc. |
| Johnson Controls International plc |
| Vivint Smart Home, Inc. |
| SimpliSafe, Inc. |
| Ring LLC |
| Bosch Security Systems |
| Hikvision Digital Technology Co., Ltd. |
| Axis Communications AB |
| Others |
Cost & Logistics Intelligence
Shenzhen's high-volume manufacturing capacity for surveillance cameras directly influences global pricing, particularly for entry-level and mid-range wireless security systems. This production concentration creates competitive pressure, impacting overall market affordability and vendor margins.
Pricing Analysis
Pricing disparities emerge across regions, with North American residential DIY kits reflecting aggressive competition. Subscription-based models, or "Security-as-a-Service," now dominate, shifting revenue from upfront hardware sales to recurring monthly fees. Price differentiation stems from after-sales service bundles, including cloud storage and professional monitoring, and advanced AI features. Cost compression in the residential segment is intensifying due to DTC competition, making these customers highly price-sensitive, unlike corporate entities.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, supporting the capital-intensive manufacturing of wireless security components. Manufacturing largely concentrates in China, particularly Shenzhen, for surveillance cameras and control panels, and other Southeast Asian hubs for sensors. The supply chain relies on specialized semiconductors for AI processing and radio frequency modules for connectivity. Single-source vulnerability for critical chipsets poses a structural risk. Distribution runs through direct-to-consumer e-commerce and established B2B networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a platform-economics inflection, driven by the deep integration of security devices into broader smart home ecosystems. This shift prioritizes seamless interoperability and recurring service revenue over standalone hardware sales.
For Market Incumbents: Pre-empt the erosion of market share by aggressively expanding into service-oriented models beyond hardware sales. Consolidate professional installer networks through strategic partnerships to counter margin pressure from DTC entrants. Invest heavily in R&D for AI-powered edge computing solutions, enhancing data protection and reducing reliance on costly cloud infrastructure.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated emerging markets like Latin America and Southeast Asia. Target the rapidly expanding small business segment with affordable, cloud-managed solutions and scalable offerings. Differentiate through robust 5G-enabled connectivity, offering superior bandwidth for 4K video streams. Leverage insurance sector partnerships to offer policy discounts, creating a new sales channel for verified systems.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring revenue platform play because subscription-based models are displacing one-time hardware sales. Acquisition targets include firms with proprietary AI analytics, edge computing capabilities, or strong regional presence in expanding small business segments. The market's structural shift towards service-oriented models provides stable cash flows; watch for successful implementation of Europe's AI Act.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand AI-powered Edge Computing | Reduces cloud dependency and enhances data privacy for German corporate entities. |
| Deepen Smart Home Ecosystem Integration | Captures pull-through demand from US residential customers adopting smart devices. |
| Forge Insurance Sector Partnerships | Unlocks new sales channels and incentivizes adoption for UK homes and businesses. |
| Develop 5G-Enabled Security Solutions | Provides higher bandwidth and lower latency for commercial premises requiring 4K video streams. |
| Target Small Business Segment in Emerging Markets | Addresses greenfield growth potential in India and Latin America with scalable, affordable systems. |
Research Approach
Initial hypotheses were tested against primary input from security system manufacturers, professional installers, and corporate security managers, then refined through iterative feedback. Secondary validation drew from FCC regulations, GDPR documentation, company financial disclosures, and industry association reports. A bottom-up estimation of device shipments and a top-down market sizing were triangulated for volume and value outputs.
Demand-supply balance was modeled across the analysis window, considering end-user adoption trends and manufacturing capacities. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory environment. Compound Annual Growth Rates were derived from historical trends and projected technological advancements. Smart home ecosystem penetration rates and 5G infrastructure rollout served as key forecast inputs.
Stress conditions across cybersecurity threat evolution and regulatory stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Building Access Control Security Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
North America Home Security System Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Port Security Systems Market
Access Control Systems
Restricted Access Barrier System (RABS) Market