
 Explosive Vapour Detector Market | 2026-2036
Explosive Vapour Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Explosive Vapour Detector Market Foresight
Multi-source procurement for ion mobility spectrometry modules is broadening as prime contractors diversify supplier risk across Asian and European component houses. Smiths Detection leverages captive manufacturing of chemical sensing arrays to sustain margin control across airport and defense contracts. FLIR Systems anchors its position through thermal imaging convergence with trace explosive detection at critical infrastructure sites. Rapiscan Systems competes on integrated checkpoint architectures that combine X-ray and vapour detection lanes.
An explosive vapour detector identifies trace concentrations of nitro-based compounds, peroxide derivatives, and other energetic materials through ion mobility spectrometry or mass spectrometry, achieving detection thresholds below one part per billion for security-critical environments. Portable detectors lead volume shipments due to military dismounted operations and law enforcement patrol requirements, while fixed installations at airport checkpoints command premium pricing through integration complexity and certification overhead. Photoionization sensors represent the fastest-expanding technology segment as manufacturers reduce false-alarm rates through selective ultraviolet ionization of target analyte classes.
The US Transportation Security Administration coordinates with the FAA to mandate certified explosive trace detection at Category X airport checkpoints, directly shaping product qualification timelines and procurement specifications. European airports operate under EASA security directives aligned with the EU Aviation Security Regulation, requiring member states to maintain harmonized detection capability across Schengen-zone transit hubs. Stakeholders must monitor evolving certification thresholds for emerging homemade explosive precursors and decide whether to internalize spectroscopic R&D or partner with specialized sensor firms.
Market Dynamics
Ion mobility spectrometry module procurement is fragmenting across Asian and European component suppliers as prime contractors hedge against single-source dependency in security-critical supply chains.
Growth Catalysts
- Aviation and Transportation Security Act mandates:TSA checkpoint certification requirements in the United States compel Category X airports to maintain certified explosive trace detection capability, creating sustained replacement cycles for aging portal installations.
- Photoionization sensor advancement:Selective ultraviolet ionization architectures are reducing false-positive rates for peroxide-based compounds, expanding law enforcement adoption beyond traditional nitro-compound screening.
- Schengen-zone harmonization:EASA security directives under EU Aviation Security Regulation require synchronized detection standards across Frankfurt, Munich, and Amsterdam transit hubs, consolidating procurement specifications.
Market Restraints
- Helium-3 supply constraints:Neutron detection subsystems face input cost volatility as nuclear non-proliferation protocols restrict isotope availability from Russian and US federal stockpiles.
- Spectrometer core concentration:High-resolution mass spectrometry modules rely on German and Japanese precision optics houses, creating geographic supply risk for tier-one integrators.
- Homemade explosive precursor diversity:TATP and HMTD variants evade conventional IMS libraries, forcing continuous spectroscopic database updates that strain R&D budgets.
Strategic Opportunities
- Critical infrastructure convergence:Mass transit authorities in Germany and France are adopting walk-through trace portals originally developed for aviation, opening non-aviation revenue streams.
- Dual-use thermal imaging integration:Combining FLIR thermal cores with vapour detection arrays creates perimeter security bundles for data centers and government facilities.
- Indian airport modernization:Bureau of Civil Aviation Security mandates under the Aircraft Security Act are driving first-time deployments at tier-two airports in Hyderabad and Bangalore.
Industry Challenges
- IMS calibration specialist scarcity:Field service engineers with ion mobility spectrometry drift-tube expertise command premium wages, constraining OEM service network expansion.
- EU-type examination timelines:CE marking under the Machinery Directive and ATEX certification for explosive atmospheres extends product launch cycles by 14-18 months.
- Legacy X-ray integration friction:Checkpoint retrofits require API harmonization between vapour detection portals and existing baggage screening lanes, complicating unified command interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosive Vapour Detector Market |
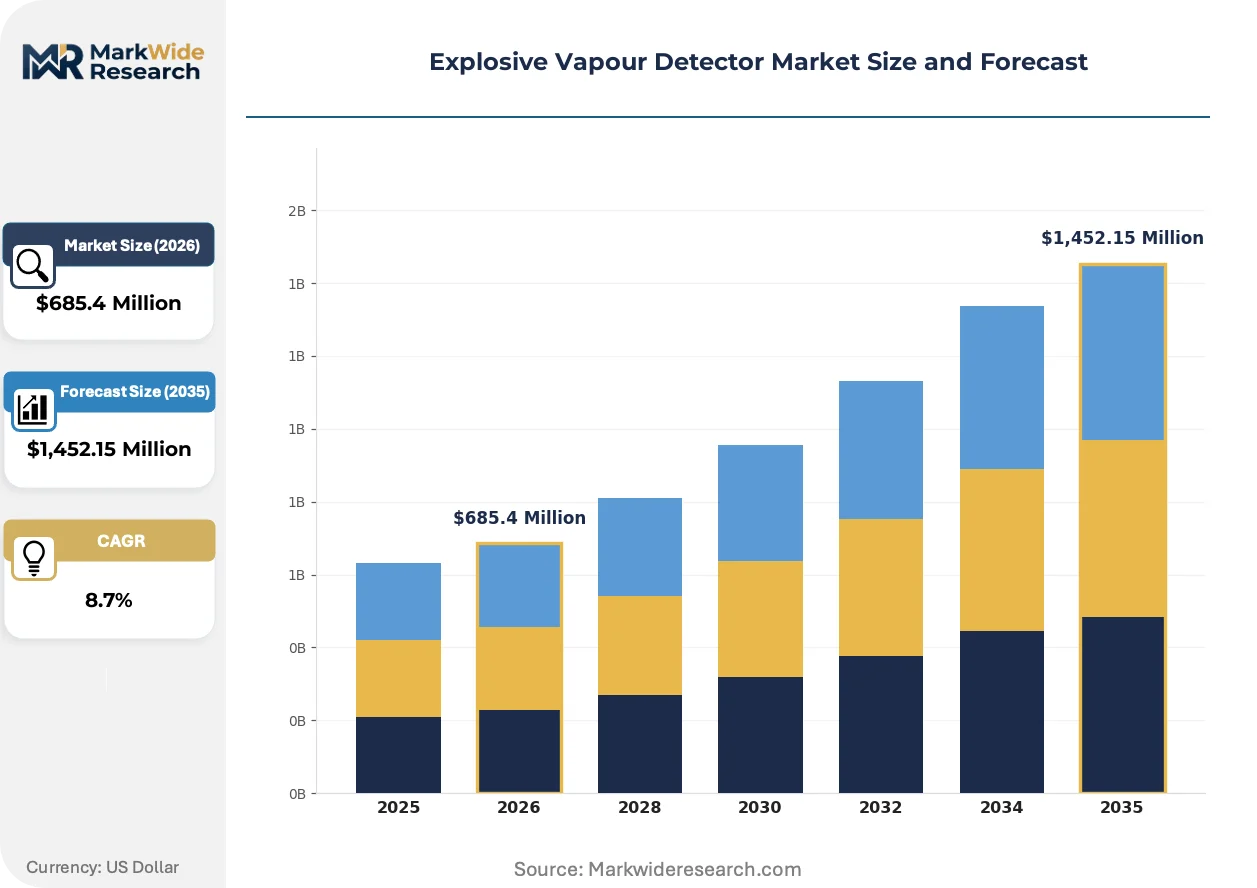
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Handheld Detectors, Wireless Detectors Technology: Infrared Sensors, Catalytic Sensors, Metal Oxide Sensors, Photoionization Sensors End User: Military, Airports, Industrial Facilities, Law Enforcement Agencies Application: Border Security, Fire Safety, Hazardous Material Detection, Surveillance |
| Companies Covered | Smiths Detection, FLIR Systems, Rapiscan Systems, Bruker Corporation, OSI Systems, Leidos Holdings, L3Harris Technologies, Chemring Group, NUCTECH Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosive Vapour Detector Market Shifts & Advancements
Detection hardware architectures are fragmenting into interchangeable sub-assemblies as security integrators demand field-upgradeable sensitivity tiers without full system replacement.
Photoionization detection arrays are modularizing into swappable sensor cartridges that airports can reconfigure between passenger checkpoint and cargo screening modes. German integrators at Frankfurt Airport are piloting hot-swappable ultraviolet lamp modules that reduce maintenance windows from four hours to forty-five minutes. This modularity is compressing product lifecycle revenue from monolithic system sales toward recurring sensor cartridge replacement streams.
REACH restrictions on perfluorinated compounds are forcing European manufacturers to reformulate drift-tube sealing materials and ionization source substrates. The substitution mandates affect IMS module durability testing protocols, extending EASA certification timelines for next-generation portals. French and Dutch airports are responding by front-loading procurement of pre-2026 certified inventory to hedge against approval delays.
Consolidated maintenance contracts are displacing discrete hardware purchases as TSA and European hub operators bundle detection, X-ray, and access control servicing under single-vendor accountability structures. Channel intermediaries specializing in security integration are capturing value previously retained by OEM direct sales teams. This concentration is most visible in United States Category X airports where five-year total-cost-of-ownership agreements now dominate RFP evaluation criteria.
Explosive Vapour Detector Market Segmentation
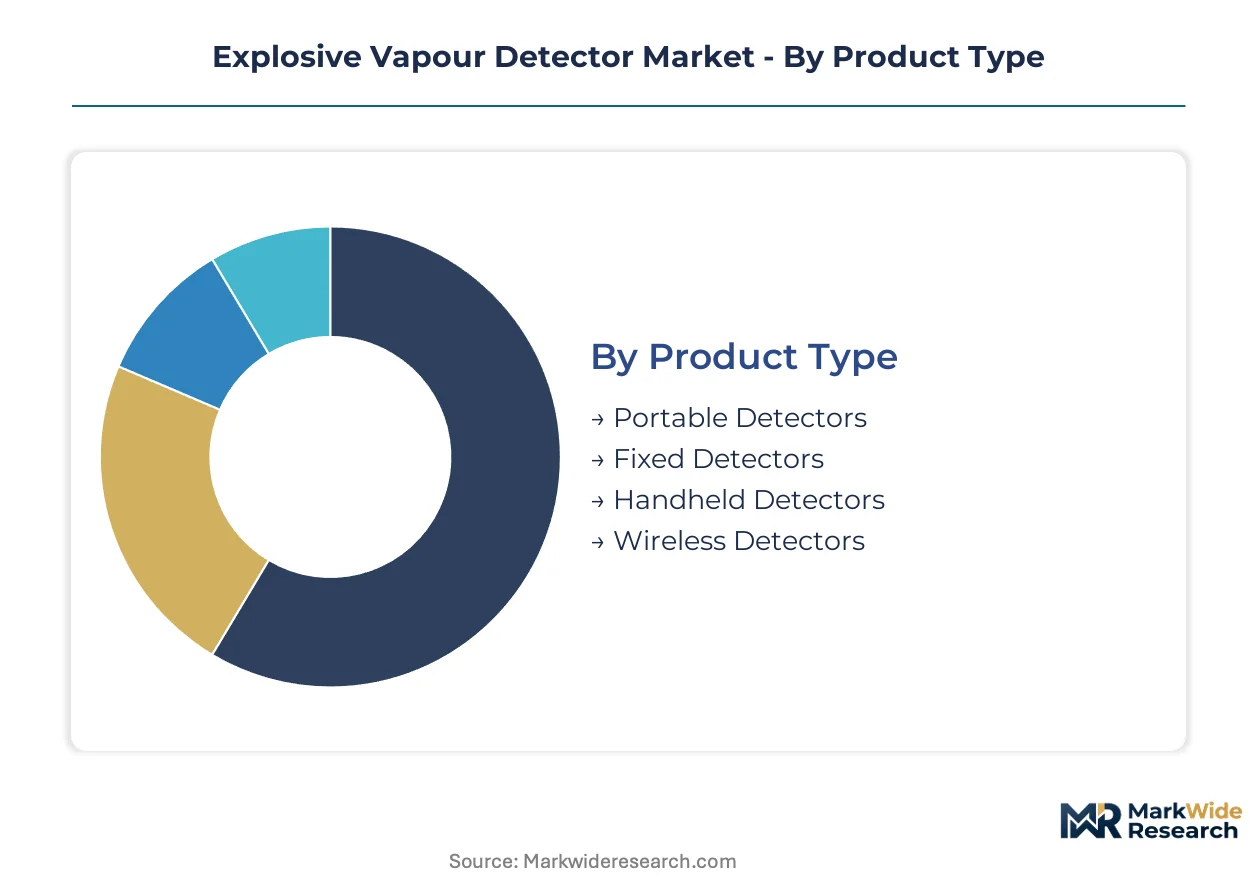
Explosive vapour detector procurement varies sharply across deployment contexts, with ion mobility spectrometry specifications, portability requirements, and certification thresholds creating distinct commercial clusters. Technology selection and product form factor together determine pricing architecture and replacement cycle intensity.
Product Type:
Portability specifications define procurement patterns across military, aviation, and law enforcement channels, with weight thresholds and battery autonomy driving contract award criteria.
- Portable Detectors:Battery-powered units under five kilograms enable dismounted military operations and mobile law enforcement patrols. Demand concentrates in US military procurement through TSA-mandated checkpoint retrofits at Category X airports, where rapid deployment capability commands premium pricing.
- Fixed Detectors:Permanent installations integrate with airport checkpoint architectures and critical infrastructure perimeter systems. Frankfurt and Munich airports in Germany are deploying next-generation walk-through portals under EASA security directives, consolidating procurement specifications across Schengen-zone transit hubs.
- Handheld Detectors:Single-operator units prioritize ergonomic design for extended field use. Border security agencies in France and the Netherlands specify these for vehicle inspection lanes.
- Wireless Detectors:Mesh-networked sensor arrays enable distributed coverage without hardwired infrastructure. Industrial facilities in Germany adopt these for refinery perimeter monitoring.
Fixed detectors lead on scale; wireless detectors are gaining share fastest through critical infrastructure convergence.
Technology:
Detection sensitivity thresholds and false-alarm rates determine technology adoption, with selective ionization methods displacing legacy architectures in security-critical environments.
- Photoionization Sensors:Selective ultraviolet ionization architectures achieve sub-part-per-billion detection thresholds for peroxide-based compounds. TSA checkpoint mandates and European airport procurement are accelerating replacement of legacy IMS modules, with reduced false-positive rates driving law enforcement adoption beyond traditional nitro-compound screening.
- Infrared Sensors:Non-dispersive infrared absorption identifies molecular signatures through characteristic wavelength absorption. Military logistics operations in the United States specify these for cargo screening due to ruggedized packaging and minimal calibration requirements.
- Catalytic Sensors:Combustion-based detection responds to broad hydrocarbon classes with lower selectivity. Industrial safety applications in French chemical plants deploy these for area monitoring where explosive atmosphere certification under ATEX directives governs equipment selection.
- Metal Oxide Sensors:Semiconductor resistance changes detect reducing gas concentrations at moderate sensitivity. Cost-sensitive border security deployments in India utilize these for first-line screening at tier-two airport checkpoints.
Photoionization sensors lead on momentum; infrared sensors retain scale in military channels.
End User:
Procurement authority structures and certification requirements fragment demand across defense, aviation, industrial, and public safety verticals.
- Military:Dismounted operations and forward operating base security drive demand for ruggedized, battery-operated units. US Department of Defense procurement emphasizes interoperability with existing chemical detection networks.
- Airports:TSA certification requirements and EASA security directives mandate certified explosive trace detection at Category X checkpoints. Frankfurt Airport's deployment of walk-through portals exemplifies European hub modernization.
- Industrial Facilities:Refinery and petrochemical site security requires ATEX-certified equipment for explosive atmosphere zones. German chemical manufacturers specify integrated perimeter systems.
- Law Enforcement Agencies:Bomb squads and tactical units prioritize portable units with rapid warm-up cycles. French National Police procurement emphasizes interoperability with existing command systems.
Airports lead on contract value; law enforcement agencies are expanding procurement most quickly through municipal security grants.
Application:
Threat profiles and operational tempos determine sensor configuration, with checkpoint throughput requirements diverging from perimeter monitoring specifications.
- Border Security:Vehicle and cargo inspection lanes require high-throughput screening with minimal false alarms. Dutch and Belgian customs authorities specify integrated vapour and X-ray architectures.
- Fire Safety:Arson investigation and post-blast analysis applications demand laboratory-grade sensitivity. German federal criminal police maintain centralized spectroscopic databases.
- Hazardous Material Detection:Industrial accident response and clandestine lab interdiction require broad-spectrum analyte libraries. US EPA coordination with law enforcement shapes equipment specifications.
- Surveillance:Covert deployment in transportation hubs and public venues drives miniaturization requirements. French mass transit authorities pilot distributed sensor networks.
Border security leads on procurement volume; surveillance applications are expanding most quickly through critical infrastructure protection mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Airport's deployment of walk-through explosive trace portals exemplifies how German aviation security investments are reshaping procurement patterns across European transit infrastructure. National regulatory frameworks and certification mandates drive divergent adoption timelines across major markets.
United States
TSA checkpoint certification requirements under the Aviation and Transportation Security Act compel Category X airports to maintain certified explosive trace detection capability. The FAA coordinates with the Department of Homeland Security to tighten screening standards. Atlanta and Dallas-Fort Worth hubs are driving replacement cycles for aging portal installations.
Germany
Frankfurt and Munich airports are deploying next-generation walk-through explosive trace detectors under EASA security directives. The KBA enforces harmonized detection standards across Schengen-zone transit infrastructure. Bavaria's industrial corridor is consolidating procurement specifications for integrated checkpoint architectures.
France
French mass transit authorities are adopting aviation-derived walk-through trace portals for critical infrastructure protection. ANSM security protocols align with EU Aviation Security Regulation mandates. The Île-de-France region is piloting distributed sensor networks across Parisian transportation hubs.
India
Bureau of Civil Aviation Security mandates under the Aircraft Security Act are driving first-time deployments at tier-two airports. CDSCO equipment certification timelines shape vendor qualification processes. Hyderabad and Bangalore aviation clusters are modernizing passenger screening infrastructure.
United Kingdom
UK border security agencies specify integrated vapour and X-ray architectures for high-throughput vehicle inspection lanes. The Civil Aviation Authority enforces checkpoint standards aligned with evolving threat assessments. London Heathrow's procurement decisions influence specification trends across Commonwealth aviation markets.
Explosive Vapour Detector Market Competitive Landscape
Global majors compete with regional champions across certification-heavy procurement channels, with tier-one integrators leveraging captive manufacturing to sustain margin control. The vendor base clusters around three strategic archetypes: diversified defense conglomerates with security divisions, specialized detection technology pure-plays, and Asian component suppliers penetrating module procurement. Dominant competitive moves include backward integration into chemical sensing arrays and strategic partnerships to secure spectroscopic database licensing.
Within the diversified defense tier, Smiths Detection and FLIR Systems exemplify integrated platform providers combining thermal imaging convergence with trace detection architectures. Rapiscan Systems occupies a position among checkpoint integration specialists bundling X-ray and vapour detection lanes. These three entities represent distinct competitive vectors—captive manufacturing, thermal-core convergence, and unified checkpoint architectures—shaping how procurement authorities evaluate total-cost-of-ownership agreements.
| Leading Market Players |
|---|
| Smiths Detection |
| FLIR Systems |
| Rapiscan Systems |
| Bruker Corporation |
| OSI Systems |
| Leidos Holdings |
| L3Harris Technologies |
| Chemring Group |
| NUCTECH Company |
| Others |
Supply & Pricing Matrix
Captive manufacturing of chemical sensing arrays anchors both supply security and pricing power for tier-one integrators serving TSA-certified airport deployments. Smiths Detection's in-house production of ion mobility spectrometry modules insulates margin structures from volatile component markets while enabling premium positioning in EASA-mandated European procurement channels.
Pricing Analysis
Helium-3 supply constraints and precision optics costs pass through unevenly across detector tiers, with neutron detection subsystems absorbing sharper input volatility than photoionization architectures. Three-tier pricing structure across certified airport portals, military-grade portable units, and industrial safety monitors reflects divergence in certification overhead and integration complexity. Cost compression in metal oxide sensor segments is intensifying because Indian tier-two airports prioritize first-cost minimization over detection sensitivity. Municipal law enforcement agencies exhibit highest price sensitivity, while Category X airport authorities prioritize total-cost-of-ownership metrics that embed service bundling premiums.
Supply Chain Analysis
EASA and TSA certification gating restricts qualified supplier pools to a narrow tier of German, Japanese, and US precision optics houses with demonstrated drift-tube manufacturing histories. Ion mobility spectrometry modules draw from specialized ultraviolet lamp foundries in the Netherlands and ceramic substrate fabricators in Japan. Single-source vulnerability concentrates in high-resolution mass spectrometry cores, where two Japanese houses control precision ion optic supply. Distribution runs through security integrators consolidating formerly discrete hardware, installation, and maintenance contracts under unified accountability structures at North American and European hub airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The explosive vapour detector market functions as a stable compounder, with regulatory mandate-driven replacement cycles at Category X airports providing predictable revenue visibility regardless of macroeconomic volatility.
For Market Incumbents: Lock in multi-year total-cost-of-ownership agreements with TSA and major European hub operators before modular sensor cartridge architectures commoditize hardware margins. Deepen backward integration into photoionization lamp manufacturing to offset REACH-driven material substitution costs. Prioritize spectroscopic database licensing partnerships to neutralize homemade explosive precursor detection gaps that strain R&D budgets.
For New Entrants and Emerging Players: Tier-two Indian airports present the most penetrable buyer archetype, with Bureau of Civil Aviation Security mandates creating first-deployment demand without entrenched incumbent relationships. Municipal mass transit authorities in France and Germany offer secondary white-space, adopting aviation-derived walk-through portals for critical infrastructure protection. Pursue channel partnerships with established security integrators rather than direct OEM competition to bypass certification timeline disadvantages.
For Investors and Strategic Acquirers: Roll-up economics work for specialized IMS calibration service providers because field engineer scarcity creates localized pricing power and recurring revenue streams attach durably to installed base expansion. Five-to-ten year viability hinges on spectroscopic platform breadth rather than single-technology exposure. Monitor EASA certification timeline extensions for next-generation portals as the inflection signal indicating consolidation pressure on undercapitalized pure-plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Photoionization Sensor Cartridge Modularization | Frankfurt Airport's hot-swappable lamp pilots compress maintenance windows and shift revenue toward recurring replacement streams. |
| Backward Integration into Chemical Sensing Arrays | Smiths Detection's captive manufacturing insulates margins from Asian component volatility in security-critical supply chains. |
| Thermal Imaging Convergence Bundles | FLIR Systems combines thermal cores with vapour detection for data center perimeter contracts outside traditional aviation channels. |
| Spectroscopic Database Licensing Partnerships | Collaborations with specialized sensor firms address TATP and HMTD detection gaps that strain internal R&D budgets. |
| Consolidated Maintenance Contract Capture | Channel intermediaries bundle detection, X-ray, and access control servicing under single-vendor accountability at US Category X airports. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airport security procurement directors, TSA certification engineers, ion mobility spectrometry R&D leads, and field service operations managers with secondary validation against EASA security directives, FAA checkpoint standards filings, EU Aviation Security Regulation amendments, and customs trade data on spectrometer component flows. Bottom-up shipment modeling and top-down procurement budget analysis triangulated to segment-level estimates.
Segment-weighting across the projection horizon applied differential growth coefficients to portable, fixed, handheld, and wireless detector form factors, with technology tiers photoionization, infrared, catalytic, and metal oxide sensors receiving distinct penetration curves based on TSA and EASA certification timelines. End-user verticals military, aviation, industrial, and law enforcement were modeled separately, with Indian airport modernization and European mass transit adoption as specific demand inputs. CAGRs derived from replacement cycle analysis at Category X airports and greenfield deployment schedules at tier-two hubs.
Underlying measurement precision varies by segment; certified airport portal shipments carry tighter precision than emerging surveillance application estimates due to consolidated procurement disclosure. Forecasts embed assumptions regarding EASA certification timeline stability and helium-3 supply continuity that material shifts in Russian isotope export protocols or REACH substitution mandates could revise. A model refresh is warranted upon material change in TSA checkpoint technology refresh schedules or EU homemade explosive precursor detection standard updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Airport Baggage Screening Systems Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Global Traveler Security Services Market
Security and Surveillance
Middle East and Africa Cargo and Vehicle Screening Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market
Security and Surveillance
Smart Security in Healthcare Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Europe Border Security Market