
 Keyless Entry System Market | 2026-2036
Keyless Entry System Market Size, Share, and Industry Trends Forecast 2026-2036
Keyless Entry System Market Intelligence
China's expanding manufacturing capacity for electronic components is narrowing the cost gap between traditional locks and keyless systems. Continental AG leverages its deep automotive integration to embed these systems in new vehicle platforms. Robert Bosch GmbH competes on the breadth of its security portfolio, which covers residential to commercial applications. NXP Semiconductors specializes in the secure connectivity chips that power these devices.
A keyless entry system is an electronic lock that grants access without a physical key, verifying credentials from an authorized device. These systems function via radio-frequency protocols like Bluetooth Low Energy (BLE) to authenticate users. While smart keys continue to dominate the vehicle access application, mobile app-based systems are expanding rapidly in commercial buildings. The underlying technology is shifting from older RFID to more dynamic NFC and Bluetooth solutions.
Compliance with radio spectrum regulations, such as those from the U.S. Federal Communications Commission (FCC), is mandatory. In Europe, products must adhere to CE marking requirements, which cover safety and electromagnetic compatibility, while China's GB standards govern electronic product quality. Future development will focus on enhancing cryptographic security protocols to counter emerging cyber threats without compromising user convenience.
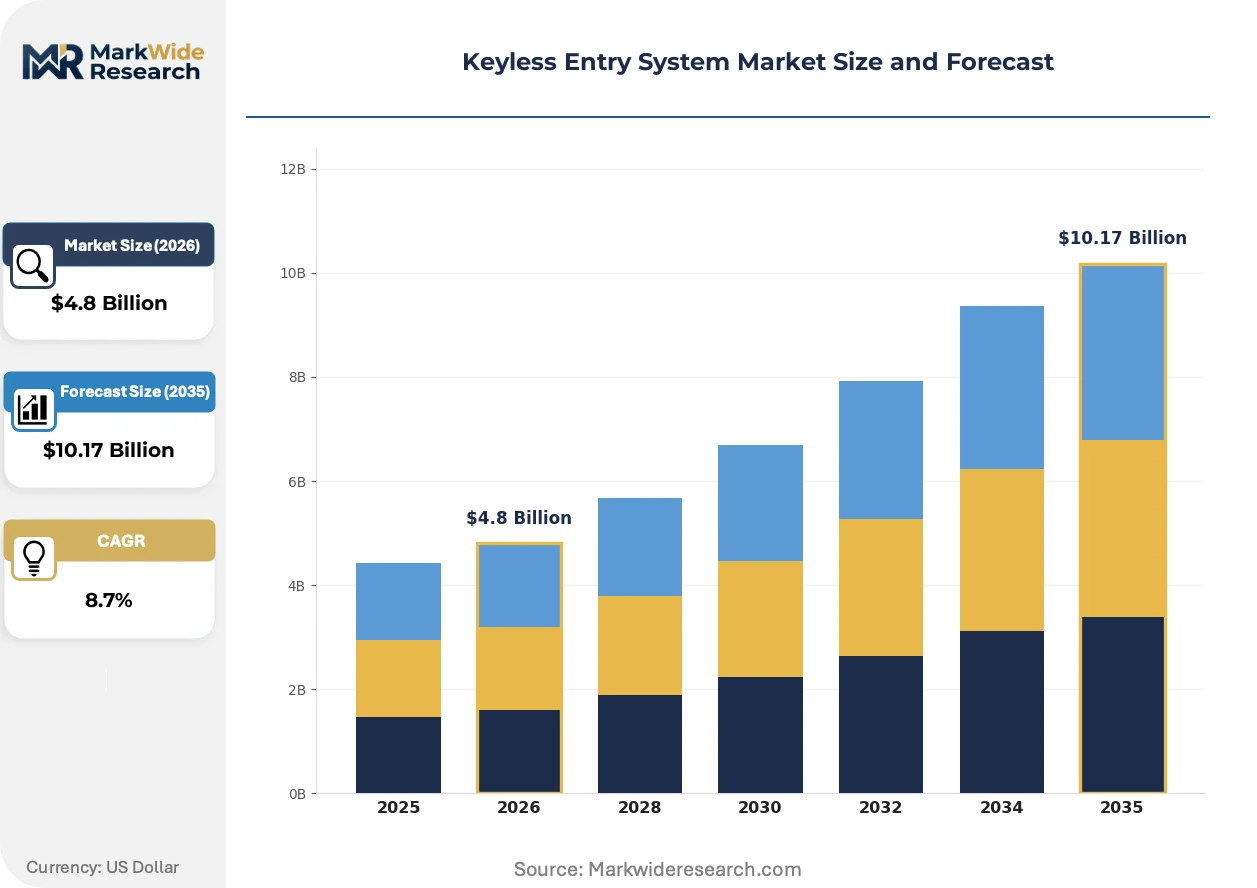
Market Dynamics
The market's central dynamic is the technological convergence of secure connectivity protocols like NFC and BLE with the expanding Internet of Things (IoT) ecosystem. This integration is fundamentally altering access control from a static, hardware-centric function to a dynamic, software-managed service, particularly within automotive and commercial building applications.
Growth Catalysts
- Smartphone Integration:The ubiquity of smartphones equipped with Bluetooth Low Energy (BLE) and Near Field Communication (NFC) provides a universal platform for mobile credentials, eliminating the need for dedicated physical fobs or cards.
- Smart Building Adoption:Demand from the commercial real estate sector for integrated building management systems is a significant catalyst, as keyless entry enhances security, simplifies tenant access, and improves operational efficiency.
- Automotive Industry Demand:Germany's advanced automotive sector is a key driver, with vehicle manufacturers increasingly incorporating passive keyless entry and digital key solutions as standard features to enhance user convenience and vehicle security.
Market Restraints
- High Retrofit Costs:The significant upfront capital investment required to replace existing mechanical locks and wire infrastructure in older buildings presents a major cost barrier compared to traditional lock-and-key systems.
- Cybersecurity Concerns:Persistent vulnerabilities to sophisticated cyberattacks, such as relay attacks or signal jamming, create user trust deficits and restrain adoption, particularly in high-security applications.
- Regulatory Fragmentation:Navigating disparate radio-frequency regulations, including FCC standards in the United States, CE marking in Europe, and GB standards in China, adds complexity and cost to product development and global distribution.
Strategic Opportunities
- Residential Market Penetration:The multi-family housing and single-family smart home segments represent a substantial, underpenetrated market for simplified, app-based keyless solutions managed by property owners or homeowners.
- System Integration with IoT:There is a significant opportunity to bundle keyless entry with other smart building systems, such as climate control, lighting, and surveillance, creating a unified and automated building environment.
- Emerging Market Infrastructure:Smart city projects across Asia-Pacific and the Middle East are creating new opportunities for large-scale deployments in public, commercial, and residential infrastructure developments.
Industry Challenges
- Legacy System Interoperability:A primary operational challenge is ensuring new keyless entry platforms can seamlessly integrate with the diverse and often outdated security and IT infrastructure present in existing buildings.
- Lack of Protocol Standardization:The absence of a universal communication standard among manufacturers leads to vendor lock-in and interoperability problems, complicating system expansion and management for end-users.
- Cryptographic Protocol Development:A continuous challenge involves advancing cryptographic security measures to defend against emerging cyber threats without compromising the speed and convenience expected by users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keyless Entry System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Key, Smart Key, Key Card, Biometric Scanner, Mobile App Technology: RFID, Bluetooth, NFC, Infrared, Ultrasonic Application: Residential Doors, Commercial Buildings, Hotel Rooms, Vehicle Access, Warehouse Entry End User: Homeowners, Facility Managers, Hospitality Operators, Vehicle Fleet Administrators, Warehouse Supervisors |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Valeo SA, Hella GmbH & Co. KGaA, Lear Corporation, NXP Semiconductors, Alps Alpine Co. Ltd., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keyless Entry System Market Strategic Shifts & Innovations
The evolution of keyless entry systems is defined by a move toward software-defined access and cloud-based management. This transition enables more flexible, scalable, and data-rich security solutions that can be managed remotely, reflecting a broader shift in how physical spaces are secured and operated.
Mobile credentialing uses a person's smartphone as a secure, digital key for building or vehicle access. Commercial real estate operators and corporate facility managers are adopting this technology to streamline access for employees and visitors. The market's core authentication technology is migrating from physical RFID cards and key fobs toward more dynamic, over-the-air managed credentials delivered via BLE or NFC protocols.
Data privacy regulations, such as Europe's GDPR, impose stringent rules on the handling of personal information generated by access control systems. This is forcing manufacturers to embed privacy-by-design principles into their software, including features for data anonymization and explicit user consent. The hospitality and residential rental sectors are most directly impacted, requiring auditable compliance to avoid substantial financial penalties.
A shift from one-time hardware purchases toward recurring revenue services like Access-as-a-Service (AaaS) is reshaping procurement patterns. This subscription model bundles hardware, cloud software, system updates, and ongoing support into a predictable operational expense. The trend is most visible in the flexible office and enterprise sectors, where it aligns with preferences for opex-based financial models over large capital outlays.
Keyless Entry System Market Segmentation
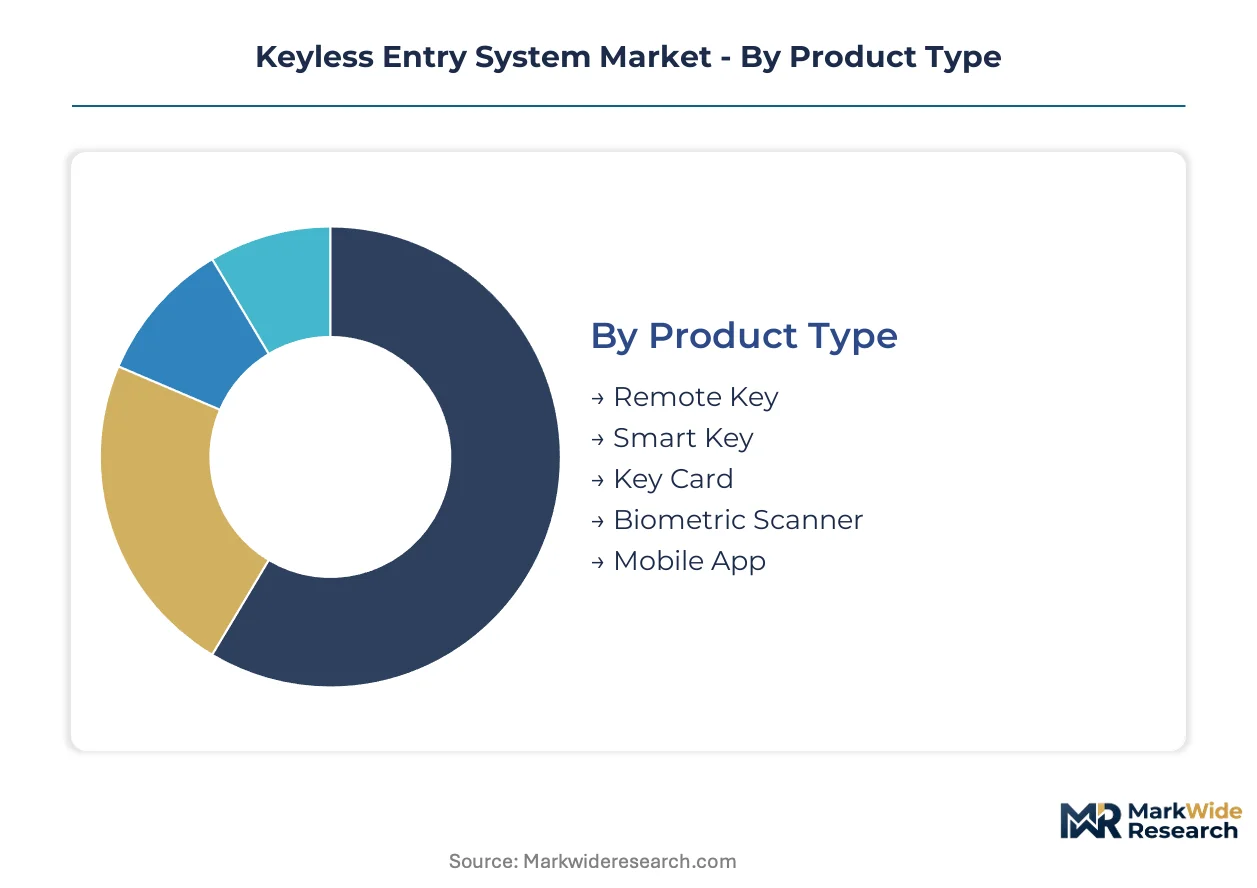
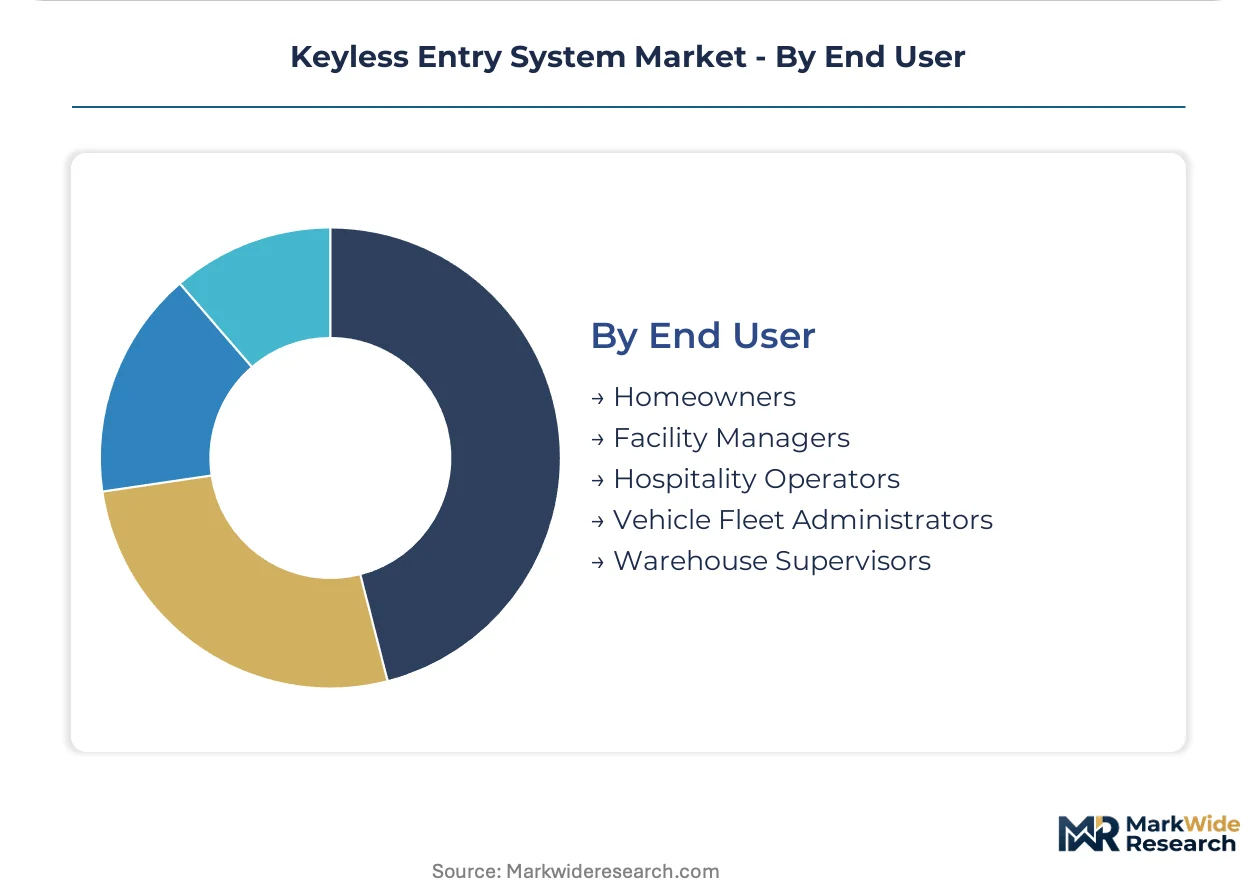
Keyless entry system functionality varies significantly across diverse product types and underlying technologies. This market analysis categorizes solutions based on their operational mechanisms, target environments, and user profiles. Understanding these distinctions clarifies the varied adoption patterns and specific security requirements across the industry.
Product Type:
The product type segmentation captures the maturity spectrum of keyless access solutions, ranging from established hardware-based systems to advanced software-driven credentials.
- Remote Key:Traditional handheld transmitters send radio signals to unlock and lock vehicles from a distance.
- Smart Key:These devices incorporate advanced cryptographic chips for secure authentication, often supporting passive entry and engine start functions. Germany's automotive sector extensively integrates smart keys as premium standard features, enhancing vehicle security and user convenience.
- Key Card:Physical cards, typically utilizing RFID or NFC, provide access to buildings and hotel rooms.
- Biometric Scanner:These systems authenticate users through unique biological characteristics like fingerprints or facial recognition.
- Mobile App:This segment utilizes smartphone applications for credential management and access authorization via BLE or NFC protocols. Commercial buildings in major European cities are rapidly deploying mobile app systems, driven by demand for flexible access and streamlined facility management.
Remote Key handles the majority of throughput in vehicle access; Mobile App is the fastest mover on share in commercial applications.
Technology:
Technology differentiation often correlates with varying cost structures and security levels, influencing deployment decisions across the market.
- RFID:Radio-frequency identification systems use electromagnetic fields to automatically identify and track tags attached to objects.
- Bluetooth:Bluetooth Low Energy (BLE) protocols enable secure, short-range wireless communication between access points and authorized devices like smartphones. This technology is a significant enabler for advanced access control in smart building deployments across Europe.
- NFC:Near Field Communication facilitates secure, close-proximity data exchange, commonly used for mobile payments and digital key card emulation. China's expanding smart city infrastructure leverages NFC for public transport and building access solutions.
- Infrared:Infrared keyless systems transmit signals using light, primarily for short-range vehicle unlocking and home security.
- Ultrasonic:Ultrasonic technology employs high-frequency sound waves for proximity detection and basic remote access functions.
RFID drives significant volume in legacy access systems; Bluetooth drives margin expansion through software-defined access services.
Application:
The application segment highlights how keyless entry systems are tailored to meet distinct operational and security needs across diverse environments.
- Residential Doors:Keyless systems provide homeowners with enhanced security and convenient access control for private residences.
- Commercial Buildings:These applications integrate keyless systems into broader building management platforms, enhancing security and operational efficiency for tenants and staff. Demand for integrated solutions is particularly strong in Germany's smart building industry.
- Hotel Rooms:Hospitality operators use keyless entry via key cards or mobile apps to streamline guest check-in and room access.
- Vehicle Access:This segment encompasses passive entry, remote locking, and digital key solutions embedded in new automobiles. Continental AG leverages its automotive integration to embed these systems in new vehicle platforms, meeting consumer demand for convenience.
- Warehouse Entry:These systems manage access for personnel and vehicles in logistics and industrial facilities, improving security and tracking.
Vehicle Access dominates the installed base of keyless systems; Commercial Buildings show the steepest expansion trajectory in new deployments.
End User:
This segmentation categorizes the market by the primary decision-makers and beneficiaries, reflecting distinct procurement patterns and feature priorities.
- Homeowners:Individual consumers adopt keyless entry for personal residences, prioritizing ease of use and smart home integration.
- Facility Managers:These professionals oversee access control for commercial properties, seeking integrated solutions that simplify tenant management and enhance building security. They prioritize systems offering remote management and detailed audit trails.
- Hospitality Operators:Hotel and resort managers implement keyless systems to improve guest experience and operational efficiency for room access.
- Vehicle Fleet Administrators:Responsible for managing vehicle access and security for large fleets, these users require robust, scalable keyless solutions. They focus on digital key integration and seamless credential provisioning for drivers.
- Warehouse Supervisors:These users manage access to industrial facilities, focusing on security, inventory control, and personnel tracking.
Facility Managers account for most revenue in commercial keyless systems; Hospitality Operators show the highest new adoption rates for mobile-based solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global keyless entry system market sees supply-side capabilities heavily concentrated in key manufacturing hubs. This concentration drives cost efficiencies for electronic components, making advanced systems more accessible across diverse applications. Technology developers and manufacturers often cluster in these regions, fostering innovation in secure access solutions.
Germany
Germany's advanced automotive sector and smart building industry generate significant demand for keyless entry systems. Products must adhere to stringent CE marking requirements for safety and electromagnetic compatibility. The Stuttgart region, a hub for automotive innovation, sees extensive integration of smart keys and digital key solutions in new vehicle platforms.
China
China's expanding electronic component manufacturing capacity reduces costs for keyless systems and fuels smart city infrastructure projects. Electronic products must comply with national GB standards for quality and safety. The Yangtze River Delta, a major electronics manufacturing base, accelerates the production and deployment of NFC-based public transport and building access solutions.
United States
Commercial building expansion and penetration into residential smart home segments drive robust demand for keyless entry systems in the United States. Compliance with U.S. Federal Communications Commission (FCC) radio spectrum regulations is mandatory for all wireless devices. Silicon Valley, a technology development hub, focuses on enhancing cryptographic security protocols for app-based solutions.
Japan
Japan's advanced automotive industry and growing smart home market are key demand drivers for sophisticated keyless entry systems. Manufacturers must navigate METI guidelines for industrial products to ensure quality and interoperability. The Tokyo metropolitan area spearheads urban development projects integrating mobile app-based access for commercial and residential properties.
France
France sees strong adoption of keyless systems in commercial building modernization and the hospitality sector. Products require CE marking, and data privacy regulations like GDPR heavily influence system design. The Paris region, a major center for commercial real estate, rapidly deploys mobile app systems for flexible access and streamlined facility management.
Keyless Entry System Market Key Industry Players
Automotive suppliers and specialized security providers split the keyless entry system market, each leveraging distinct core competencies. The market exhibits a tiered structure, with established players dominating specific application segments. Companies engage in portfolio diversification to cover residential and commercial applications, alongside strategic partnerships to integrate new technologies. Technology licensing agreements also shape the competitive dynamics.
Among the prominent entities, Continental AG exemplifies deep automotive integration, embedding keyless systems directly into new vehicle platforms. This approach leverages established relationships within the vehicle manufacturing ecosystem. Robert Bosch GmbH occupies a significant position with its broad security portfolio, spanning residential and commercial applications, demonstrating a commitment to diverse market segments. NXP Semiconductors anchors the market's technological foundation, specializing in the secure connectivity chips that power these advanced devices. These companies collectively represent distinct strategic approaches, from vehicle-centric solutions to comprehensive security offerings and foundational component supply, influencing the market's technological trajectory.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Valeo SA |
| Hella GmbH & Co. KGaA |
| Lear Corporation |
| NXP Semiconductors |
| Alps Alpine Co. Ltd. |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta's cost dynamics for electronic components directly influence supply concentration in Asia, shaping downstream price differentiation across keyless entry system applications. This manufacturing advantage enables competitive pricing for hardware components, impacting overall system costs.
Pricing Analysis
CE marking dictates the pricing tier structure for keyless systems in Europe, emphasizing compliance costs. Subscription-based Access-as-a-Service (AaaS) models represent a dominant pricing structure for commercial applications, bundling software and support. Price differentiation stems from cryptographic security levels and brand premium, with established providers commanding higher rates. Pricing softness for basic hardware components reflects intense competition among component suppliers, particularly from Asian manufacturers. Homeowners exhibit higher price sensitivity for initial hardware investments compared to facility managers seeking integrated solutions.
Supply Chain Analysis
Upstream feedstock for secure connectivity chips primarily sources from specialized manufacturers in China and Taiwan, forming a concentrated supply base. Keyless entry systems depend on a steady supply of radio-frequency modules, microcontrollers, and sensors. Single-source vulnerability for specific secure chip architectures presents a structural supply chain risk. Distribution runs through direct sales channels to automotive OEMs and B2B integrators for commercial building applications, alongside consumer electronics retailers for smart home devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
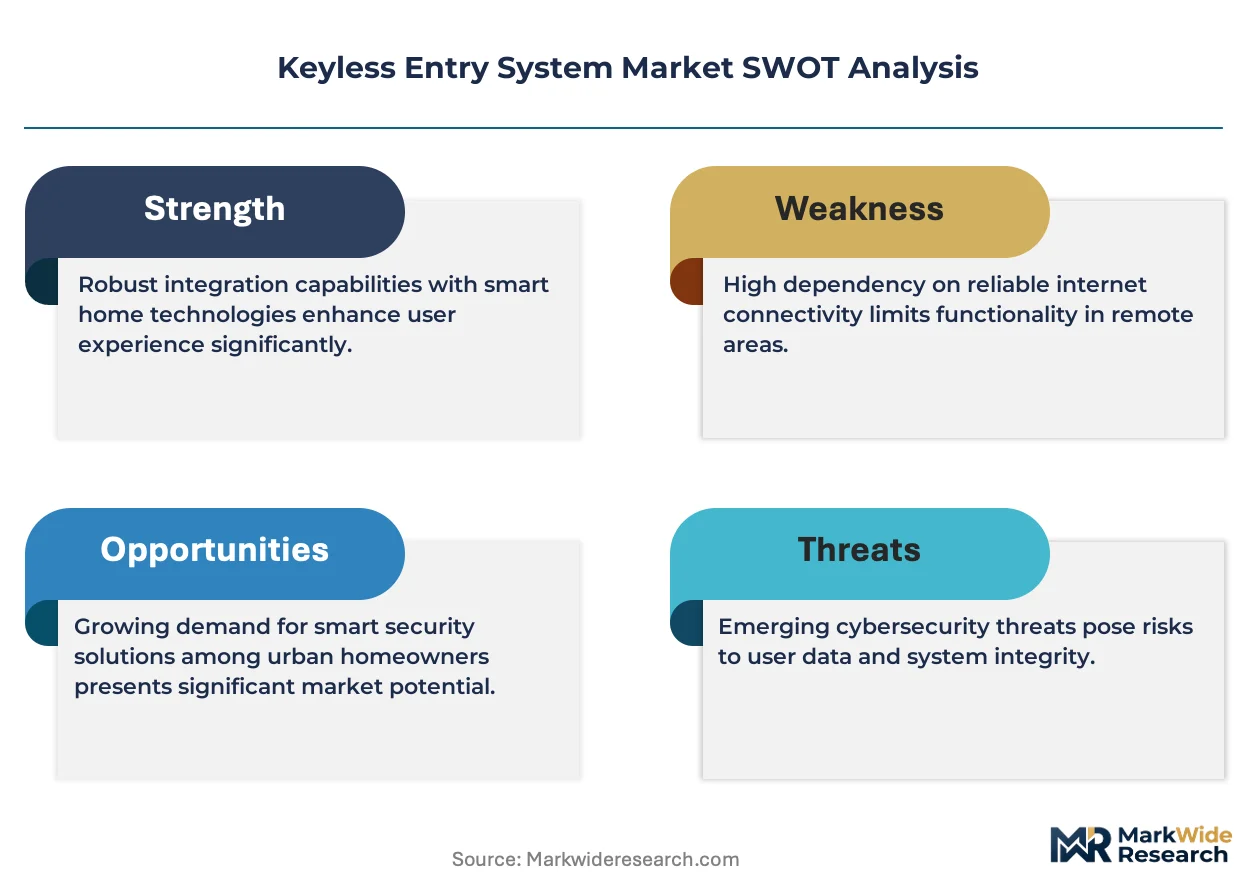
The keyless entry system market stands at a platform-economics inflection, driven by the convergence of secure connectivity protocols with the expanding IoT ecosystem.
For Market Incumbents: Pre-empt emerging cyber threats by investing heavily in advanced cryptographic security protocols and secure hardware development. Deepen vertical integration of secure chip manufacturing to mitigate supply chain risks and control core technology. Foster strategic partnerships with cybersecurity firms to enhance system resilience against sophisticated attacks, maintaining a competitive edge against new entrants.
For New Entrants and Emerging Players: Build out app-based mobile credentialing solutions specifically targeting the multi-family housing segment, which remains underpenetrated. Focus on delivering simplified, user-friendly interfaces with strong data privacy compliance as a core go-to-market angle. Leverage cloud-based management platforms to offer flexible, scalable solutions that appeal to property owners and facility managers seeking operational efficiency.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors companies specializing in software-defined access and secure connectivity. Long-term viability rests with platforms offering seamless integration into broader smart building and automotive ecosystems. Acquisition targets should include firms with robust mobile credentialing IP or expertise in secure IoT integration. The signal to watch is the adoption rate of universal communication standards among manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance Cryptographic Security Protocols | Strengthens system resilience against cyber threats, building user trust in high-security applications. |
| Integrate with Smart Building Systems | Bundles keyless entry with other services, creating unified and automated building environments for commercial clients. |
| Form Strategic Cybersecurity Partnerships | Accesses specialized expertise to combat advanced cyberattacks and maintain a competitive security posture. |
| Acquire Mobile Credentialing Software Firms | Expands software capabilities and accelerates market penetration in the rapidly growing mobile access segment. |
| Target Emerging Market Infrastructure Projects | Captures new large-scale deployment opportunities in smart cities and commercial developments across Asia-Pacific. |
Research Approach
Operator-level perspectives from facility managers, vehicle fleet administrators, hospitality operators, and smart home developers anchored the qualitative base for this analysis. Primary interviews were combined with secondary data from FCC regulations, CE marking requirements, and automotive industry reports to validate market dynamics. This approach ensured robust bottom-up and top-down triangulation of market figures.
Scenario-bracketing framed the forecast over the projection horizon, accounting for various technological adoption rates and regulatory shifts. Segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory clusters. Compound Annual Growth Rate calculations reflected historical trends and future projections, with smartphone integration rates and IoT ecosystem expansion serving as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new technology providers or established automotive players would shift outcomes. Forecasts reflect assumptions regarding cybersecurity advancements and regulatory stability. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Automated Border Control Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Port Security Systems Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
US Access Control Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
North America Access Control Market
Access Control Systems
Europe Airport Passenger Screening Systems Market