
 Shock Sensor Market | 2026-2036
Shock Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Shock Sensor Market Intelligence
The bundling of shock sensors with data logging and wireless connectivity modules is rebalancing buyer preference toward integrated system solutions over discrete components. This strategic shift favors suppliers possessing a broad electronics portfolio. TE Connectivity leverages its extensive connector and sensor expertise to deliver these bundled packages. In contrast, PCB Piezotronics sustains its market position through deep specialization in high-sensitivity piezoelectric sensors for niche scientific and testing environments.
A shock sensor is an electromechanical device designed to detect and measure sudden acceleration or impact, often utilizing materials that generate a voltage proportional to the applied force. Its primary purpose is to trigger an alarm or record data for asset protection and system safety analysis. While piezoelectric sensors maintain a strong presence in demanding aerospace applications, MEMS technology represents the fastest-growing segment, penetrating consumer electronics with its compact and cost-effective design.
Product compliance is shaped by varied end-market requirements, with sensors used in aviation needing to meet stringent criteria from the US FAA. Industrial equipment sold in Japan often adheres to specific JIS standards for quality assurance and interoperability. The ability to navigate this complex web of regional standards while managing the technology transition to MEMS-based architectures will ultimately determine long-term vendor success.
Market Dynamics
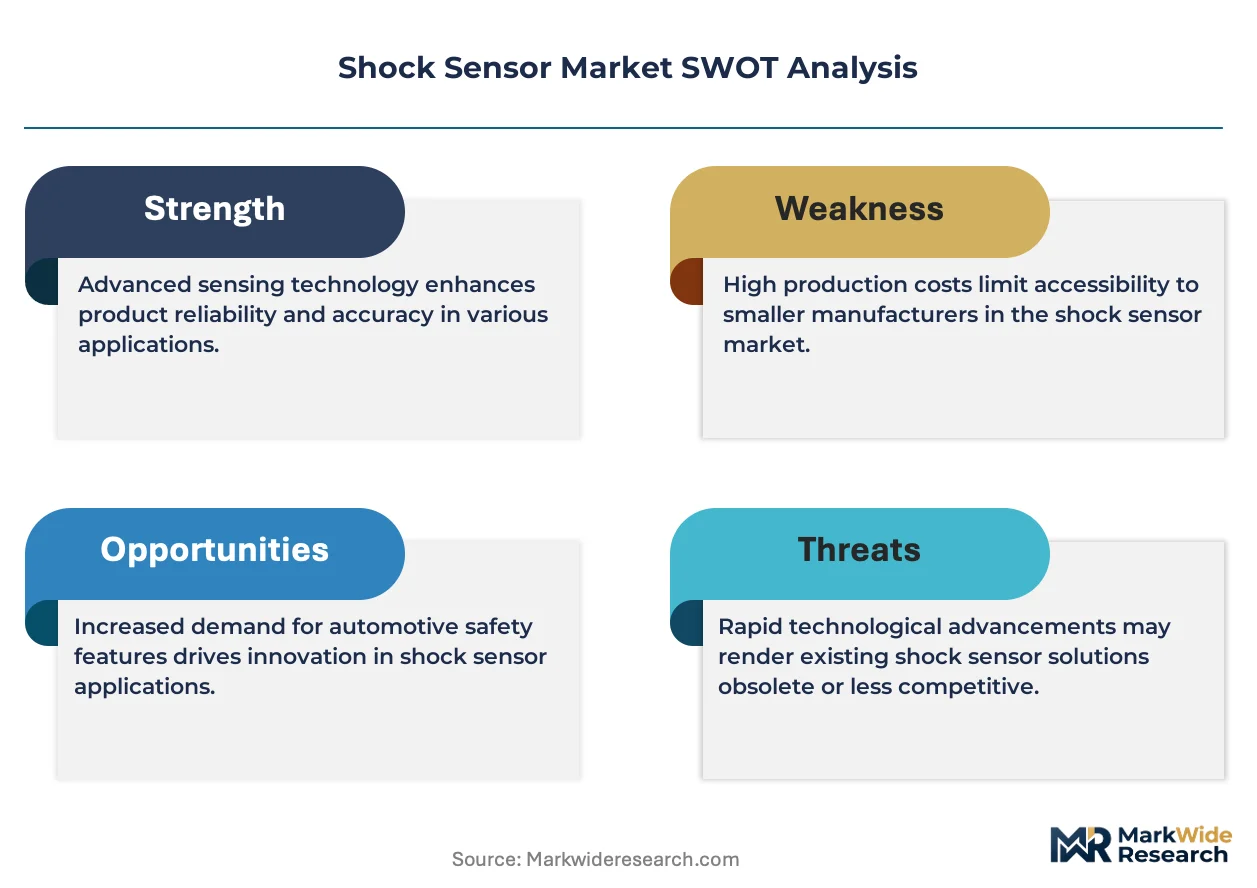
The central dynamic in the shock sensor market is the tension between rapid MEMS-driven miniaturization, which opens new consumer applications, and industrial demand for integrated, ruggedized systems that bundle sensing with wireless data logging for predictive maintenance programs.
Growth Catalysts
- Industrial Automation:Predictive maintenance programs in advanced manufacturing, particularly within Germany's automotive and machinery sectors, rely on shock sensors to monitor equipment health and prevent unplanned downtime, directly stimulating component demand.
- MEMS Advancement:Continuous improvements in Micro-Electro-Mechanical Systems technology are reducing the size, power consumption, and cost of shock sensors, enabling their integration into a wider array of consumer electronics and portable devices.
- Aviation Safety Mandates:Stringent regulations from bodies like the US FAA, which require robust data recording systems on aircraft, create a consistent, high-value demand for durable, high-fidelity shock sensors in aerospace applications.
Market Restraints
- Piezoelectric Material Costs:The high cost and specialized processing of piezoelectric ceramic materials, essential for high-sensitivity sensors, restrict their use to niche scientific, military, and aerospace applications where performance outweighs price considerations.
- Substitution from General Accelerometers:Low-cost, general-purpose accelerometers embedded in smartphones and standard IoT devices can serve as a "good enough" substitute for dedicated shock sensors in non-critical, price-sensitive applications.
- Signal Conditioning Complexity:High-performance piezoelectric sensors generate charge signals that require specialized and often expensive conditioning electronics, creating a technical and cost barrier for system integrators without deep analog expertise.
Strategic Opportunities
- Smart Packaging Integration:Embedding low-cost MEMS shock sensors into logistics and high-value goods packaging allows for continuous monitoring of impacts during transit, creating a new market for supply chain and asset integrity assurance.
- Indian Manufacturing Expansion:Government initiatives like "Make in India" and the Production Linked Incentive (PLI) scheme are fostering growth in automotive and electronics manufacturing, creating new, localized demand for industrial-grade shock sensors.
- AI at the Edge:The convergence of shock sensors with onboard microprocessors running AI algorithms enables real-time impact analysis and event classification at the device level, reducing data transmission loads and enabling faster response.
Industry Challenges
- Divergent Regional Standards:Vendors must navigate a complex web of certifications, from FAA airworthiness criteria in the US to specific JIS industrial standards in Japan, which increases design complexity and can fragment product portfolios.
- Legacy System Integration:Implementing modern wireless shock sensor networks into industrial facilities with older, wired control architectures often requires custom gateways and software development, increasing project costs and timelines for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shock Sensor Market |
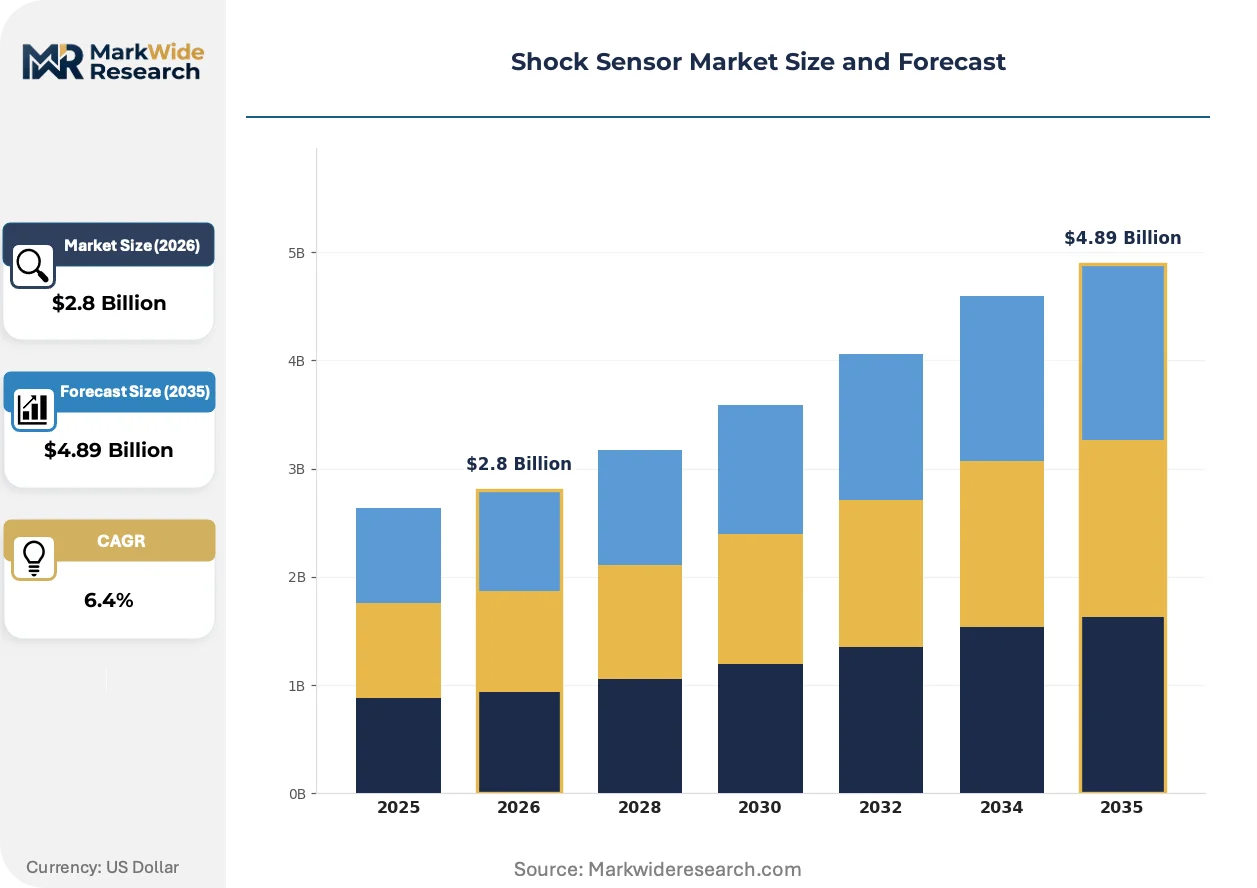
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piezoresistive, Capacitive, Piezoelectric, Optical, Strain Gauge, MEMS Technology: Resonant, Semiconductor, Fiber Optic, Microelectromechanical Systems, Thin Film, Magnetic Application: Consumer Electronics, Industrial Automation, Military Defense, Sports Equipment, Robotics, Aerospace End User: Manufacturing Plants, Defense Contractors, Athletic Equipment Makers, Robotics Firms, Aviation Companies |
| Companies Covered | TE Connectivity, PCB Piezotronics, Honeywell International, Murata Manufacturing, SpotSee, Mobitron AB, Meggitt PLC, Dytran Instruments, SignalQuest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shock Sensor Market Strategic Shifts & Innovations
A fundamental shift from selling discrete components to delivering intelligent sensing systems is redefining value in the shock sensor market. This evolution prioritizes data context and system-level integration over raw sensor performance alone, pushing vendors toward software-defined solutions.
Sensor fusion combines data from shock sensors with inputs from temperature, humidity, and vibration detectors. The logistics and cold chain industries are rapidly adopting these multi-sensor modules for comprehensive asset monitoring. This technology is unifying previously separate data streams into a single, contextualized view of an asset's condition, enabling more sophisticated risk analytics and event reconstruction.
The forthcoming EU AI Act imposes risk-based compliance obligations on systems that use artificial intelligence for critical functions. This directly impacts intelligent shock sensors that use AI for predictive failure analysis in industrial or automotive safety systems. Manufacturers targeting the European Union must now invest in data governance and model explainability to meet these new legal requirements for high-risk applications.
End-users are increasingly purchasing shock monitoring as a service (MaaS) rather than buying sensor hardware outright. This model replaces large capital expenditures with predictable operational subscriptions, appealing to asset managers in logistics and heavy industry. This behavioral shift is most prominent in North America, where third-party logistics providers use these services to offer enhanced supply chain visibility to their clients.
Shock Sensor Market Segmentation
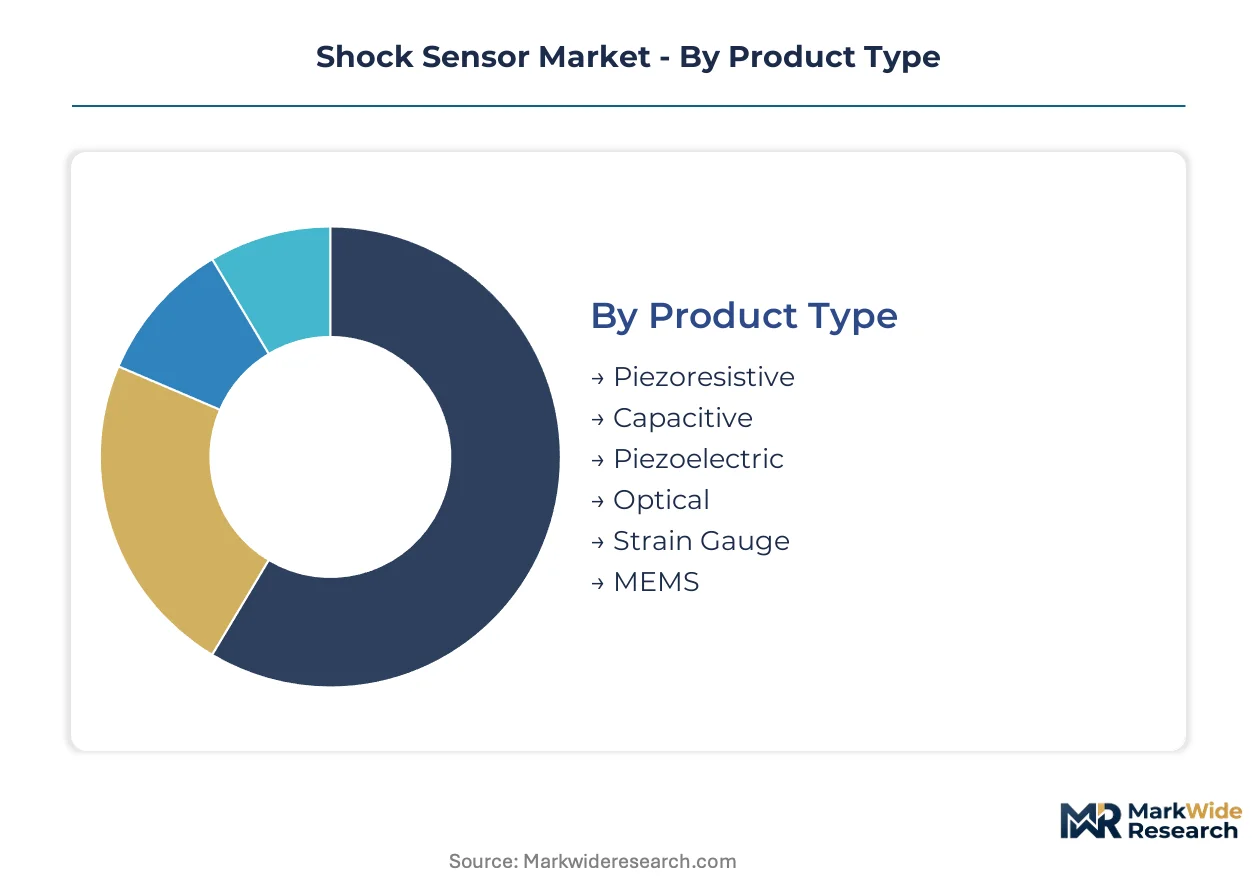
The shock sensor market differentiates across various dimensions, reflecting diverse performance needs and cost structures. Understanding these segments clarifies where specialized engineering capabilities meet specific industrial requirements. This analysis provides a structured view of market composition.
Product Type:
Segments within product type often require varying levels of capital investment for manufacturing, impacting entry barriers and production scale.
- MEMS:Micro-Electro-Mechanical Systems sensors integrate mechanical and electrical components on a single chip, offering compact size and low power consumption. Demand is concentrating in consumer electronics and portable devices, driven by cost-effectiveness and miniaturization.
- Piezoelectric:These sensors utilize materials that generate an electrical charge proportional to mechanical stress, providing high sensitivity and broad frequency response. Demand remains strong in demanding aerospace applications and scientific testing environments, where precision is paramount.
- Piezoresistive:These sensors detect changes in electrical resistance due to applied mechanical stress, finding use in industrial pressure and load measurement.
- Capacitive:Capacitive sensors measure changes in capacitance caused by displacement, suitable for stable, low-frequency shock detection in automotive safety systems.
- Optical:Optical shock sensors use light reflection or transmission changes to detect impacts, often employed in high-voltage or explosive environments.
- Strain Gauge:Strain gauge sensors measure deformation caused by mechanical force, providing robust solutions for structural health monitoring in heavy machinery.
Most installed capacity flows through Piezoresistive sensors. Expansion is steepest in MEMS.
Technology:
Technology choices within shock sensors dictate their suitability for specific application environments, influencing performance and integration capabilities.
- Microelectromechanical Systems:This technology integrates mechanical elements, sensors, and electronics on a common substrate, enabling compact, low-power shock detection. Its versatility allows integration into diverse consumer electronics and industrial IoT devices.
- Fiber Optic:Fiber optic technology uses changes in light transmission or reflection to detect shock, providing immunity to electromagnetic interference and suitability for hazardous areas. Specialized applications include downhole oil and gas exploration.
- Resonant:Resonant technology measures changes in frequency due to applied force, providing highly stable and accurate shock detection in precision instrumentation.
- Semiconductor:Semiconductor-based shock sensors leverage material properties for robust and compact designs, often integrated into automotive crash detection systems.
- Thin Film:Thin film technology allows for miniature, flexible shock sensors, finding use in medical wearables and smart packaging solutions.
- Magnetic:Magnetic shock sensors detect changes in magnetic fields caused by impact, used in certain security systems and vibration monitoring.
The market's technical evolution is most visible in Microelectromechanical Systems, while Fiber Optic maintains its specialized utility.
Application:
Application segments define the primary end-use cases for shock sensors, influencing demand volume and specific performance requirements.
- Industrial Automation:Shock sensors are critical for predictive maintenance programs in advanced manufacturing, monitoring machinery health to prevent unplanned downtime. Germany's automotive and machinery sectors exhibit strong demand.
- Consumer Electronics:Integration into smartphones, wearables, and portable devices drives high-volume demand, leveraging compact and cost-effective MEMS technology for drop detection and activity monitoring.
- Military Defense:Shock sensors provide crucial data for weapon systems, vehicle integrity, and personnel safety in demanding operational environments.
- Sports Equipment:These sensors monitor impact forces in helmets and other gear, enhancing athlete safety and performance analysis.
- Robotics:Shock sensors enable robots to detect collisions and impacts, protecting both the robot and its environment in automated operations.
- Aerospace:Stringent FAA regulations mandate robust shock sensors for flight data recorders and structural health monitoring in aircraft.
Demand concentration remains high in Industrial Automation, with Consumer Electronics demonstrating significant expansion.
End User:
End-user categories reflect distinct procurement patterns and specific integration needs for shock sensor solutions.
- Manufacturing Plants:These users integrate shock sensors into production lines for asset monitoring and predictive maintenance, often requiring bundled solutions with data logging and wireless connectivity.
- Aviation Companies:Subject to strict FAA criteria, these firms procure high-fidelity, durable shock sensors for aircraft safety systems and black box data recording.
- Defense Contractors:These firms require robust, specialized shock sensors for military vehicles, weaponry, and protective gear, often to specific military standards.
- Athletic Equipment Makers:Manufacturers of sports gear use shock sensors to quantify impacts, improving product design for athlete safety and performance.
- Robotics Firms:Robotics companies integrate shock sensors for collision detection and force feedback, enhancing robot autonomy and operational safety.
Procurement by Manufacturing Plants drives significant volume, while Aviation Companies prioritize bespoke, high-reliability solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The shock sensor market's initial growth was significantly propelled by demanding aerospace applications and industrial machinery requirements. Germany's automotive sector and US defense programs established early demand for robust, high-fidelity shock sensors. Subsequent miniaturization advancements have broadened the market's geographical reach into consumer electronics and smart logistics globally.
Germany
Industrial automation in Germany's automotive and machinery sectors drives significant demand for shock sensors, particularly for predictive maintenance. The KBA (Kraftfahrt-Bundesamt) influences sensor specifications for vehicle safety systems. Manufacturing clusters in Bavaria and Baden-Württemberg actively integrate these sensors into advanced production lines.
United States
Aerospace applications and defense programs consistently require high-performance shock sensors in the United States. The FAA mandates robust data recording systems for aviation safety, ensuring steady demand. Technology hubs in California, particularly Silicon Valley, foster MEMS sensor innovation for diverse applications.
Japan
Advanced manufacturing and robotics applications create strong demand for precision shock sensors in Japan. JIS standards often dictate quality assurance and interoperability for industrial equipment, influencing sensor design. Industrial zones around Tokyo and Osaka integrate sophisticated sensors into high-tech machinery.
China
Consumer electronics manufacturing and rapid industrial expansion fuel high-volume demand for shock sensors across China. Policies from the MIIT (Ministry of Industry and Information Technology) support domestic sensor development and adoption. Shenzhen's electronics manufacturing ecosystem drives the integration of compact, cost-effective MEMS sensors.
India
India's expanding automotive and electronics manufacturing sectors, supported by "Make in India" initiatives, generate new demand for industrial-grade shock sensors. The Production Linked Incentive (PLI) scheme encourages local production of electronic components, including sensors. Automotive clusters in Pune and Chennai increasingly deploy shock sensors for equipment monitoring.
Shock Sensor Market Key Industry Players
Premium-margin players sit above commodity-margin players across product performance and application specialization within the shock sensor market. The market structure is tiered, featuring highly specialized component manufacturers alongside integrated system providers. Strategic archetypes include high-sensitivity specialists, broad-portfolio electronics suppliers, and cost-effective volume producers. Portfolio diversification and strategic partnerships represent dominant competitive moves.
Integrated system providers like TE Connectivity leverage extensive electronics portfolios to offer bundled solutions for industrial automation. PCB Piezotronics exemplifies deep specialization in high-sensitivity piezoelectric sensors, serving niche scientific and testing environments. These companies illustrate the market's dual focus on comprehensive solutions and precision performance, catering to distinct customer requirements.
| Leading Market Players |
|---|
| TE Connectivity |
| PCB Piezotronics |
| Honeywell International |
| Murata Manufacturing |
| SpotSee |
| Mobitron AB |
| Meggitt PLC |
| Dytran Instruments |
| SignalQuest |
| Others |
Cost & Logistics Intelligence
The clear performance gap between high-sensitivity piezoelectric sensors and cost-effective MEMS devices creates a tier divergence, manifesting in distinct pricing models and supply chain configurations across the shock sensor market. This bifurcation influences procurement patterns and vendor specialization.
Pricing Analysis
A hybrid pricing model operates within the shock sensor market, combining per-unit transactional sales for high-volume MEMS sensors with project-based contracts for specialized piezoelectric solutions. Price differentiation stems from certification levels, such as US FAA airworthiness criteria, and the sensor's performance specifications like sensitivity range. Pricing softness in the MEMS segment reflects intense competition and high-volume manufacturing efficiencies. Consumer electronics manufacturers exhibit the highest price sensitivity, while aerospace and military end-users prioritize performance over cost.
Supply Chain Analysis
Single-source vulnerability for specialized piezoelectric materials poses a significant supply chain risk, with production often concentrated in a few key regions. Geographic supply concentration for MEMS fabrication centers primarily in China and Taiwan, while Germany contributes specialized industrial automation components. Raw material dependencies include piezoelectric ceramics and advanced semiconductor wafers. Geopolitical tensions affecting rare earth elements for piezoelectric sensors represent a structural supply chain risk. Distribution channels operate through direct sales for high-value industrial and aerospace applications, contrasting with broad distributor networks for consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shock sensor market offers margin expansion opportunities through both MEMS cost reductions and the development of premium integrated system solutions.
For Market Incumbents:Anchor existing high-fidelity sensor portfolios in regulated aerospace and defense markets by emphasizing compliance with stringent criteria like FAA mandates. Counter MEMS substitution threats by bundling advanced analytics and wireless connectivity into integrated system solutions. Invest in deep customer integration and specialized certification to secure long-term, high-value contracts. Expand manufacturing capacity in strategic regions to mitigate supply chain risks and serve localized industrial demand.
For New Entrants and Emerging Players:Small-to-medium logistics providers present an underserved buyer archetype for low-cost, smart packaging integration solutions. Target emerging industrial sectors in India and Southeast Asia with cost-effective, MEMS-based sensors and localized support. Leverage open-source software platforms for easier integration into existing IoT ecosystems. Offer shock monitoring as a service (MaaS) to reduce capital expenditure barriers and attract new customers in asset-intensive industries.
For Investors and Strategic Acquirers:Consolidation pressure builds where specialized IP and comprehensive electronics portfolios offer strategic advantages in the integrated sensing market. Long-term viability favors firms capable of delivering intelligent sensing systems with AI at the edge. Acquisition targets include niche MEMS innovators or software analytics providers specializing in real-time impact analysis. The signal to watch is the accelerated adoption of EU AI Act-compliant sensor systems in critical industrial applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies diverse sensor data streams for comprehensive asset monitoring in logistics. |
| Regional Manufacturing Expansion | Addresses localized demand and mitigates supply chain risks in emerging markets like India. |
| AI Algorithm Development | Enables real-time impact analysis at the device level, reducing data transmission loads. |
| Regulatory Compliance Investment | Secures market access and strengthens competitive advantage in highly regulated sectors like aerospace. |
| Service-Oriented Business Model | Converts capital expenditures into operational subscriptions, appealing to asset managers. |
Research Approach
Multiple input streams — primary interviews, secondary publications, industry databases — were reconciled to construct a robust market view. Stakeholders interviewed included R&D directors, procurement leads, plant engineers, and regulatory compliance officers across various end-user industries. Secondary sources comprised US FAA regulations, Japanese JIS standards, company annual reports, and relevant trade association publications. Bottom-up and top-down triangulation validated market sizing and growth projections.
Reconciliation of historical data and market drivers established the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory environment. Compound annual growth rates were derived from supply-side capacity additions and demand-side adoption rates. Forecast inputs considered MEMS cost reduction trajectories and industrial automation investment cycles.
Underlying measurement precision varies by segment; industrial automation and aerospace applications carry tighter precision than consumer electronics. Forecasts reflect assumptions regarding technological advancements and geopolitical stability affecting supply chains. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Security Inspection Market
Security and Surveillance
Smart Security in Healthcare Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Airport Security Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Maritime Security Market
Security and Surveillance
Specialized Threat Analysis and Protection Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
Security System Integrators Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
Door and Window Alarm Market