
 Global Corporate Travel Security Market | 2026-2036
Global Corporate Travel Security Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corporate Travel Security Market Foresight
Consolidation among Fortune 500 procurement teams is recalibrating vendor selection criteria toward integrated travel risk platforms. International SOS leverages its medical evacuation infrastructure to anchor long-term enterprise contracts across energy and mining sectors. Control Risks specializes in geopolitical intelligence feeds that differentiate its offering from commoditized alert services. Everbridge extends its mass notification technology into traveler tracking, competing directly with traditional security consultancies.
Corporate travel security encompasses the systems, protocols, and services that protect personnel during business-related movement across domestic and international jurisdictions, incorporating real-time GPS tracking, encrypted communication channels, and geopolitical threat feeds with sub-minute alert latency. The primary commercial purpose is to fulfill employer duty-of-care obligations while minimizing operational disruption from medical emergencies, political instability, or criminal activity. Cloud-based deployment models now dominate new implementations as multinationals prioritize scalable API integration with existing HR and expense management systems. Incident management solutions command premium pricing due to their 24/7 operational center requirements and specialized analyst staffing, while identity verification segments face margin compression from commoditized biometric vendors.
The EU AI Act, GDPR, and ISO 31030 travel risk management standard collectively shape product architecture by mandating algorithmic transparency for automated threat scoring and strict data residency controls for employee location tracking. FAA and SEC disclosure requirements in the United States further compel publicly traded firms to document travel security expenditures as material risk mitigation investments. Stakeholders must monitor evolving national data localization laws that could fragment cloud-based platform architectures and force costly regional infrastructure duplication.
Market Dynamics
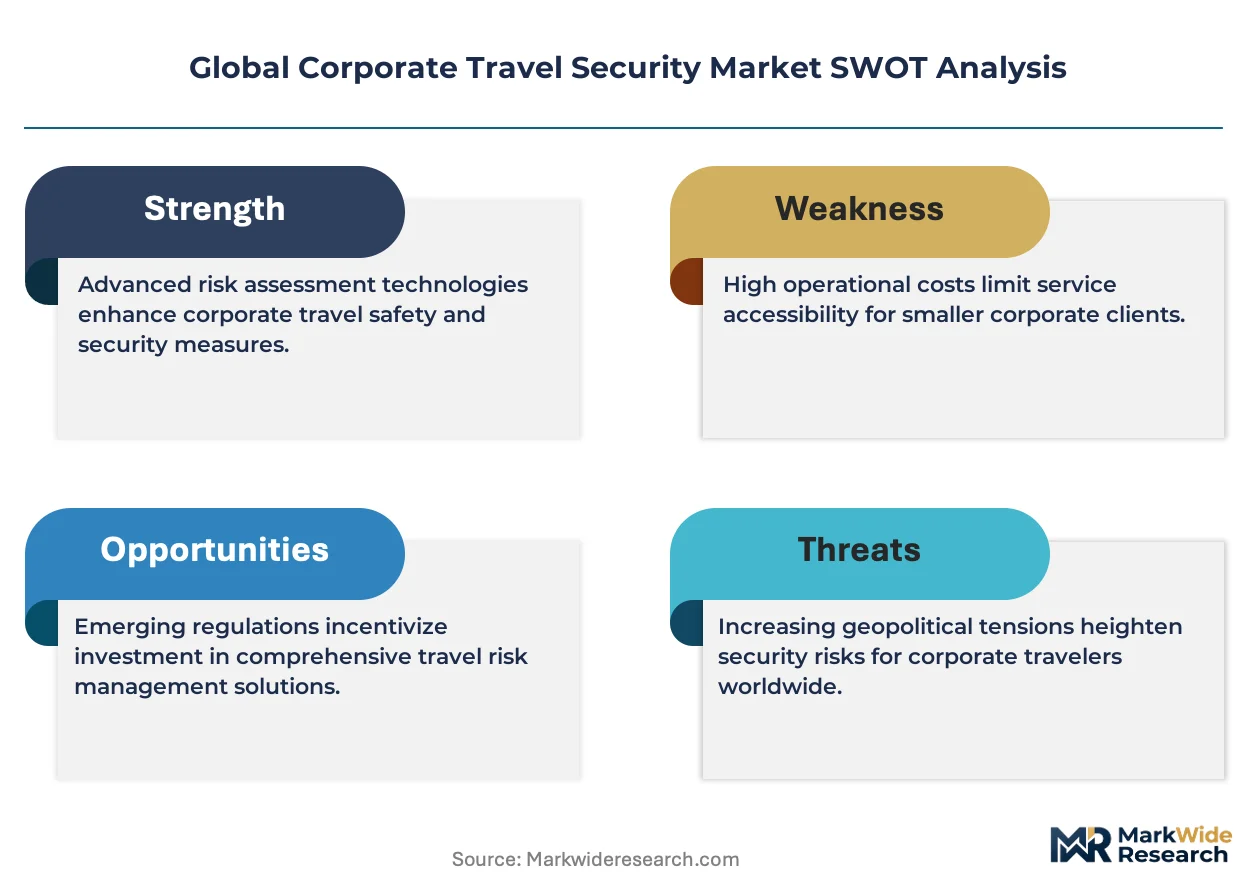
Cloud-based API integration with HR and expense management systems is compressing deployment timelines and forcing legacy on-premise vendors to rearchitect their platforms or exit the mid-market entirely.
Growth Catalysts
- ISO 31030 compliance mandates:European multinationals are retrofitting travel risk management frameworks to meet the international standard's duty-of-care documentation requirements.
- Biometric identity verification:Airports in Singapore and Dubai are deploying facial recognition corridors that reduce friction for business travelers and lower security staffing costs.
- Energy sector capital deployment:Oil and gas majors are expanding security budgets for remote site rotations in West Africa and Central Asia.
Market Restraints
- Data residency fragmentation:China's cybersecurity law and Russia's data localization requirements force platform providers to duplicate infrastructure across sovereign cloud zones.
- Analyst staffing costs:24/7 operations centers require multilingual geopolitical analysts, creating fixed cost structures that scale poorly in price-sensitive segments.
- Commoditized biometric hardware:Fingerprint and facial recognition modules from Shenzhen suppliers are eroding margins in identity verification segments.
Strategic Opportunities
- India's manufacturing corridor expansion:German automotive suppliers are establishing Pune and Chennai operations, creating demand for localized travel security protocols.
- AI-driven predictive threat modeling:Machine learning platforms are converging with satellite imagery feeds to anticipate route disruptions before they materialize.
- Embedded insurance products:Parametric medical evacuation coverage is being bundled into corporate travel bookings through GDS channel partnerships.
Industry Challenges
- Geopolitical analyst retention:Competition from intelligence agencies and investment banks is draining the talent pipeline for regional expertise in Arabic, Mandarin, and Russian.
- Legacy system integration:SAP and Oracle HR environments require custom middleware development, extending implementation cycles and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corporate Travel Security Market |
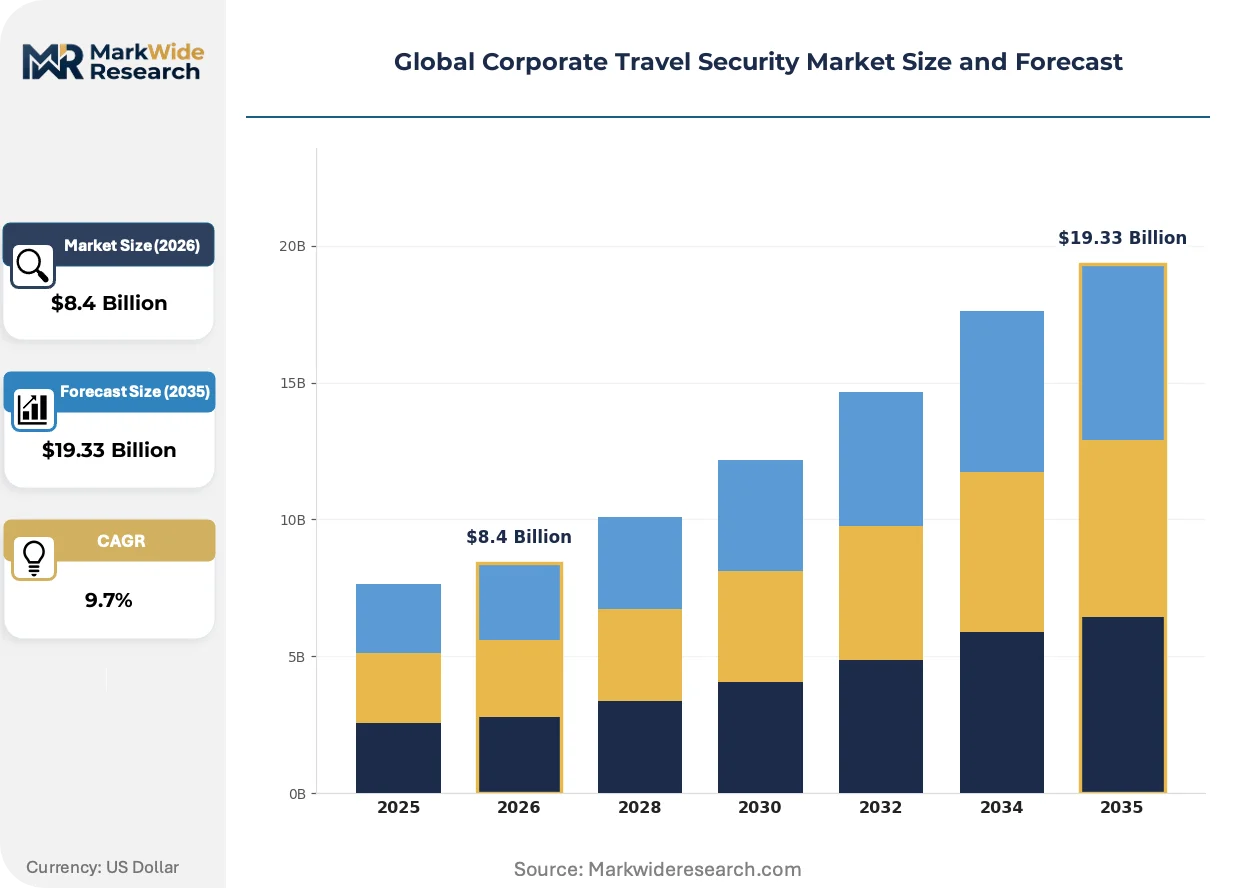
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Risk Assessment, Incident Management, Threat Detection, Emergency Response, Identity Verification Application: Employee Monitoring, Compliance Management, Travel Risk Analysis, Health & Safety, Crisis Management Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS, Managed Services End User Segment: Multinational Corporations, Insurance Firms, Government Agencies, Non-Governmental Organizations, Consulting Firms |
| Companies Covered | Global Guardian, Safeture, International SOS, AXA Assistance, Crisis24, Control Risks, Healix International, Europ Assistance, Everbridge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corporate Travel Security Market Shifts & Advancements
Real-time location intelligence is migrating from standalone security applications into unified employee safety platforms that consolidate medical, security, and travel disruption monitoring.
Edge computing nodes deployed on aircraft and vessels are absorbing satellite bandwidth constraints by processing threat data locally before transmitting compressed alerts to ground operations centers. Maritime and aviation sectors are adopting these ruggedized units fastest, with energy companies retrofitting offshore supply fleets. This distributed architecture is absorbing the latency penalties that previously hampered remote asset protection.
The EU AI Act's algorithmic transparency requirements are compelling travel risk platforms to document automated threat scoring logic and maintain human-in-the-loop override capabilities. Vendors must now maintain audit trails for machine learning model decisions affecting traveler safety classifications. Incident management solution providers face the steepest compliance burden, as their automated escalation protocols fall under high-risk AI system definitions.
Fortune 500 procurement teams are consolidating vendor relationships and demanding outcome-based contracts that tie fees to measurable traveler safety metrics rather than seat licenses or alert volumes. This restructures competitive dynamics toward integrated platform providers capable of spanning medical, security, and logistics functions. The shift is most pronounced in United States-headquartered technology and financial services firms with globally distributed workforces.
Global Corporate Travel Security Market Segmentation
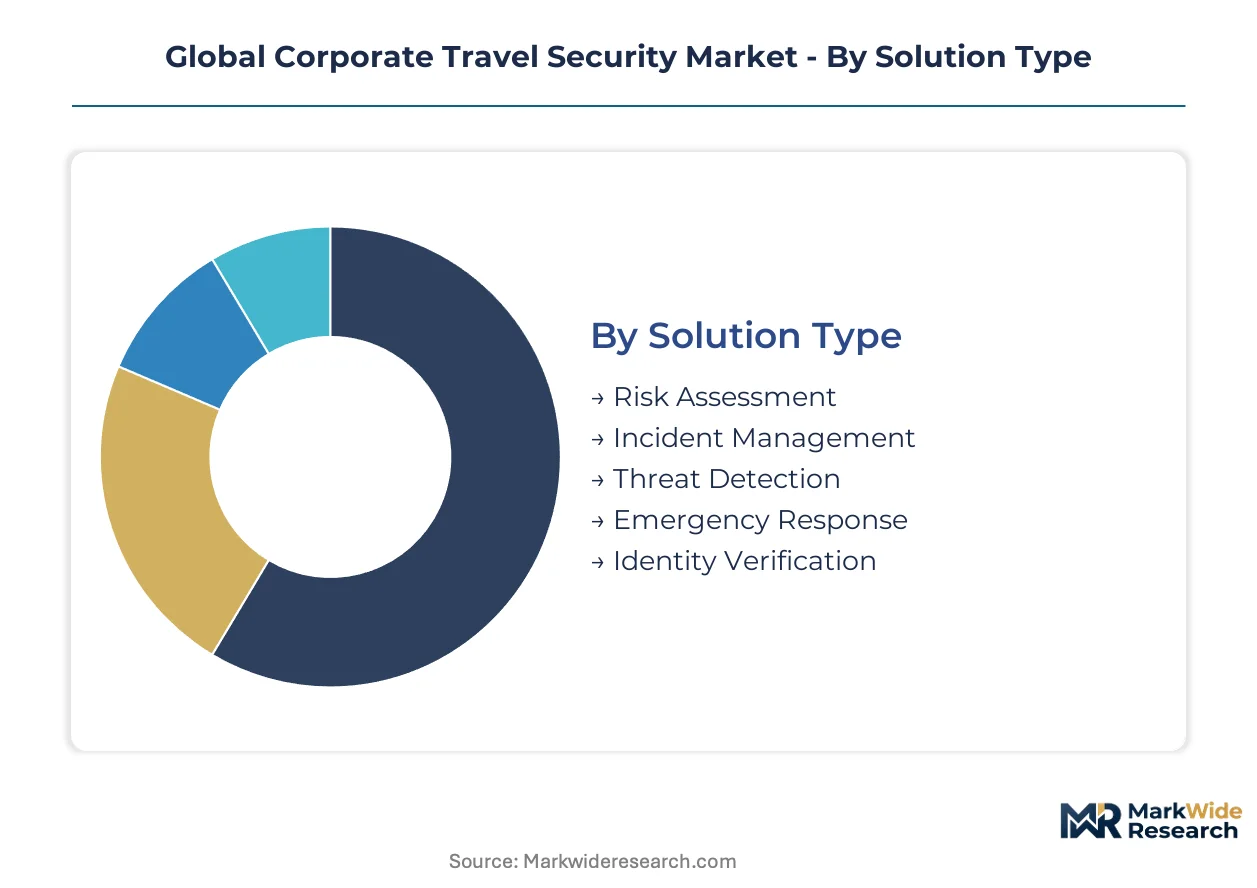
Corporate travel security procurement follows distinct technical and operational logics across solution architectures, creating divergent margin profiles and vendor specialization patterns. Understanding these segment boundaries clarifies where platform consolidation yields economies of scope versus where point solutions retain pricing power.
Solution Type:
Capital intensity clusters sharply in segments requiring 24/7 operational infrastructure and specialized analyst staffing, separating asset-heavy offerings from software-native competitors.
- Incident Management:Real-time crisis coordination platforms integrate encrypted communication channels, GPS tracking, and medical evacuation logistics through dedicated operations centers. Energy and mining majors in West Africa and Central Asia anchor demand as remote site rotations mandate guaranteed response timelines.
- Threat Detection:Automated systems ingest satellite imagery, social media feeds, and geopolitical intelligence to generate sub-minute alert latency for route disruptions. Singapore and Dubai airports drive adoption as biometric corridor deployments reduce friction for high-frequency business travelers.
- Risk Assessment:Pre-travel evaluation tools aggregate medical, security, and logistical data into traveler safety classifications. ISO 31030 compliance documentation requirements in European multinationals sustain enterprise licensing.
- Emergency Response:Medical evacuation and security extraction services leverage fixed-wing and rotary assets positioned at regional hubs. Fixed cost structures from aircraft leasing and crew retainers create high barriers to scale.
- Identity Verification:Biometric authentication modules for traveler credentialing face margin compression from Shenzhen hardware suppliers. Facial recognition corridors in Singapore and Dubai lower security staffing costs for airport operators.
Incident Management absorbs the bulk of installed capacity; Threat Detection is expanding most quickly as AI-driven predictive models converge with satellite feeds.
Application:
Functional deployment patterns track organizational maturity in duty-of-care frameworks, with integrated platforms displacing siloed point solutions in Fortune 500 environments.
- Travel Risk Analysis:Route-specific threat evaluation combines geopolitical intelligence, medical infrastructure mapping, and transportation reliability data. German automotive suppliers establishing Pune and Chennai operations drive localized protocol development for India's manufacturing corridor.
- Crisis Management:Coordinated response protocols activate across medical, security, and communications functions during traveler emergencies. EU AI Act algorithmic transparency requirements compel audit trails for automated escalation decisions.
- Employee Monitoring:Continuous location tracking via mobile applications and wearable devices feeds centralized safety dashboards. GDPR data residency controls restrict cloud architectures for European-headquartered employers.
- Compliance Management:Documentation systems satisfy ISO 31030, SEC disclosure, and internal audit requirements for travel security expenditure. FAA reporting obligations for publicly traded US firms elevate procurement scrutiny.
- Health & Safety:Medical advisory services and vaccination protocols integrate with security operations for comprehensive traveler protection. International SOS anchors long-term contracts through evacuation infrastructure guarantees.
Travel Risk Analysis commands the largest share of enterprise licensing; Crisis Management is climbing the fastest as outcome-based contracts tie fees to measurable safety metrics.
Deployment Model:
Technical architecture choices determine integration complexity with legacy HR and expense management systems, compressing timelines for cloud-native implementations.
- Cloud-Based:Scalable API integration enables real-time data exchange with SAP and Oracle environments without on-premise infrastructure. China's cybersecurity law and Russia's data localization requirements force sovereign cloud zone duplication.
- SaaS:Subscription pricing models reduce upfront capital expenditure for mid-market enterprises while delivering continuous platform updates. Multinational corporations prioritize this model for globally distributed workforce coverage.
- Managed Services:Outsourced operations centers deliver 24/7 monitoring through vendor-staffed analyst teams. Multilingual geopolitical expertise in Arabic, Mandarin, and Russian faces talent competition from intelligence agencies and investment banks.
- Hybrid:Split architectures process sensitive personnel data on-premise while leveraging cloud analytics for threat intelligence. Government agencies mandate this configuration for classified traveler movements.
- On-Premises:Legacy installations persist in defense and intelligence sectors with strict air-gapping requirements. Custom middleware development for SAP and Oracle integration extends implementation cycles and inflates professional services costs.
Cloud-Based deployment dominates new implementations; Managed Services is gaining share fastest as staffing cost pressures push enterprises toward outsourced analyst pools.
End User Segment:
Procurement sophistication varies dramatically across buyer categories, with consolidated vendor relationships and outcome-based contracting concentrated in specific sectors.
- Multinational Corporations:Integrated platform demands span medical, security, and logistics functions across technology and financial services firms with globally distributed workforces. United States-headquartered enterprises lead the shift toward consolidated vendor relationships.
- Insurance Firms:Parametric medical evacuation coverage products embed into corporate travel bookings through GDS channel partnerships. Munich Re and AIG underwrite specialized policies for energy sector remote site rotations.
- Government Agencies:National security and diplomatic travel protocols require cleared personnel and air-gapped infrastructure. Defense departments mandate hybrid or on-premise deployments for classified movements.
- Consulting Firms:Advisory services bundle travel security assessments with broader risk management engagements. Control Risks and similar providers differentiate through geopolitical intelligence feeds rather than commoditized alert services.
- Non-Governmental Organizations:Humanitarian operations in conflict zones require specialized evacuation protocols and local security network access. Cost constraints favor SaaS delivery models over asset-heavy incident management.
Multinational Corporations represent the dominant revenue base; Insurance Firms are scaling fastest through embedded product partnerships with travel management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Executive talent mobility concentrates where multinational headquarters cluster and where extractive industries deploy remote workforces. Duty-of-care litigation exposure and data sovereignty mandates reshape platform architecture across these jurisdictions.
United States
SEC disclosure requirements and FAA reporting obligations compel publicly traded firms to document travel security expenditures as material risk mitigation investments. New York and California anchor financial services and technology headquarters, driving consolidated procurement of integrated medical-security-logistics platforms.
Germany
ISO 31030 compliance documentation requirements and the EU AI Act's algorithmic transparency mandates reshape vendor selection criteria. Stuttgart and Munich automotive clusters generate specialized demand for India manufacturing corridor rotations, requiring localized Pune and Chennai security protocols.
Singapore
Changi Airport's biometric corridor deployments reduce friction for high-frequency business travelers while lowering security staffing costs. The Monetary Authority of Singapore's operational resilience guidelines elevate travel risk management to board-level governance priorities for regional headquarters operations.
China
Cybersecurity law data localization requirements force platform providers to duplicate infrastructure across sovereign cloud zones. Shanghai and Beijing multinational regional headquarters navigate strict employee location tracking restrictions while maintaining duty-of-care obligations for outbound executive travel.
United Arab Emirates
Dubai's aviation hub status and Abu Dhabi sovereign wealth fund portfolio companies drive premium incident management contract demand. The UAE's central bank operational risk frameworks extend to travel security expenditure disclosure for financial institutions with significant cross-border personnel movements.
Global Corporate Travel Security Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-driven predictive analytics and embedded insurance partnerships. The vendor base stratifies between asset-heavy evacuation infrastructure operators and software-native threat intelligence platforms. Medical evacuation specialists and geopolitical intelligence consultancies represent distinct strategic archetypes. Consolidation pressures favor integrated platform providers capable of spanning medical, security, and logistics functions.
Within the integrated platform tier, International SOS and Everbridge exemplify contrasting strategic positions. International SOS anchors long-term enterprise relationships through fixed-wing and rotary asset networks positioned at regional hubs. Everbridge extends mass notification technology into traveler tracking, competing directly with traditional security consultancies. Control Risks occupies a specialist position, differentiating through geopolitical intelligence feeds rather than commoditized alert services.
| Leading Market Players |
|---|
| Global Guardian |
| Safeture |
| International SOS |
| AXA Assistance |
| Crisis24 |
| Control Risks |
| Healix International |
| Europ Assistance |
| Everbridge |
| Others |
Supply & Pricing Matrix
Jet fuel price indices cascade through aviation-dependent security operations, compressing margins on emergency response contracts while amplifying cost differentials between asset-heavy evacuation providers and software-native threat intelligence platforms. This commodity exposure stratifies vendor economics across premium guaranteed-response tiers and standard alert-only services.
Pricing Analysis
Warranty and service-bundling arrangements separate guaranteed medical evacuation with fixed-wing assets from unbundled threat alert subscriptions. Three-tier pricing structure across premium, standard, and economy levels reflects response time guarantees, analyst language coverage, and ISO 31030 compliance documentation depth. Cost compression in biometric identity verification intensifies because Shenzhen hardware suppliers flood the component market. Mid-market enterprises exhibit highest price sensitivity; energy sector majors with West Africa and Central Asia remote rotations demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Singapore, Dubai, and Frankfurt anchor hub-and-spoke deployment of satellite communication terminals and ruggedized edge computing nodes. Critical hardware draws from Taiwan semiconductors, Shenzhen biometric modules, and German precision manufacturing for aviation-certified equipment. Single-source vulnerability concentrates in satellite bandwidth providers serving maritime and aviation sectors. Distribution runs through certified channel partners with sovereign cloud zone clearances for data residency compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analyst staffing bottlenecks for multilingual geopolitical expertise prop pricing power for vendors with captive talent pools, constraining supply expansion faster than demand growth across 24/7 operations centers.
For Market Incumbents: To counter AI-driven predictive analytics entrants, anchor enterprise relationships through fixed-wing and rotary asset networks positioned at regional hubs. Deepen backward integration into satellite communication infrastructure to secure bandwidth allocation priority during crisis congestion. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for algorithmic transparency audit tools that document automated threat scoring logic for incumbent platforms. White-space targets include ISO 31030 compliance documentation automation for German automotive suppliers and embedded parametric insurance partnerships through GDS channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-native threat intelligence platforms with API-first architectures in the United States and Singapore regional headquarters clusters. Monitor sovereign cloud zone duplication requirements as inflection indicator for infrastructure cost escalation forcing vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Predictive Threat Modeling | Machine learning platforms converging with satellite imagery feeds anticipate route disruptions before materialization. |
| Sovereign Cloud Zone Expansion | Data localization mandates in China and Russia force costly regional infrastructure duplication for compliance. |
| Embedded Insurance Partnerships | Parametric medical evacuation coverage bundles into corporate travel bookings through GDS channel integrations. |
| Biometric Corridor Integration | Facial recognition deployments at Singapore Changi and Dubai airports reduce friction for high-frequency travelers. |
| Geopolitical Analyst Talent Acquisition | Multilingual expertise in Arabic, Mandarin, and Russian faces competition from intelligence agencies and investment banks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with security operations center directors, corporate travel managers at Fortune 500 firms, geopolitical intelligence analysts, and aviation logistics coordinators combined with FAA incident reports, EU AI Act implementation guidance, and ISO 31030 certification databases. Bottom-up deployment model sizing and top-down duty-of-care expenditure estimates triangulated market dimensions.
Granularity-level modeling segmented solution types, deployment architectures, end-user categories, and geographic regulatory clusters across the analysis window. CAGRs derived from weighted scenario analysis incorporating energy sector capital deployment cycles, biometric hardware commoditization curves, and data localization law proliferation. Forecast inputs included jet fuel price volatility indices and multilingual analyst wage inflation trends.
The model assumes a particular technology adoption path; alternative pathways for edge computing node deployment on aircraft and vessels would alter the outlook. Forecasts reflect documented assumptions around ISO 31030 compliance adoption rates and sovereign cloud infrastructure buildout timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
Air Cargo Screening Systems Market
Security and Surveillance
Sirens Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Resale Authentication Services Market
Security and Surveillance
Smart Security Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
Situational Awareness System Market