
 Europe Security Screening Market | 2026-2036
Europe Security Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Security Screening Market Foresight
Buyer concentration across European airport operators is recalibrating procurement leverage toward multi-site framework agreements. Thales leverages its systems integration heritage to dominate French aviation security tenders. Smiths Detection Group Ltd. anchors the explosives trace detection segment through sustained R&D investment in ion mobility spectrometry. OSI Systems, Inc. competes aggressively on airport baggage handling integration, particularly in German-speaking markets.
Security screening encompasses technologies and systems designed to detect weapons, explosives, contraband, and unauthorized materials across controlled access points, typically employing X-ray transmission imaging, millimeter wave reflectance, or chemical trace analysis with detection thresholds measured in parts per billion. These systems serve critical infrastructure protection, commercial aviation safety, and border control operations where throughput rates and false alarm ratios determine operational viability. X-ray machines occupy the largest installed base but face margin compression as commodity baggage scanner demand saturates across tier-two European airports. Advanced imaging technology represents the fastest-expanding product category, driven by EU-mandated passenger privacy standards that prohibit backscatter X-ray deployment in favor of passive millimeter wave systems. Biometric systems command premium pricing in government facility applications where multimodal identity verification fuses facial recognition with document authentication.
The EU Aviation Security Regulation establishes baseline performance standards for checkpoint equipment deployed across member states, while EASA issues implementing acts that specify technical protocols for explosive detection systems. France's CNIL enforces GDPR-aligned constraints on biometric data retention, directly shaping system architecture for facial recognition deployments in Paris and Lyon transit hubs. The EU AI Act introduces risk-classification requirements for automated screening decision systems, compelling vendors to redesign algorithmic transparency features. Stakeholders must monitor how forthcoming harmonized standards under the Cyber Resilience Act reshape connected screening device certification timelines.
Market Dynamics
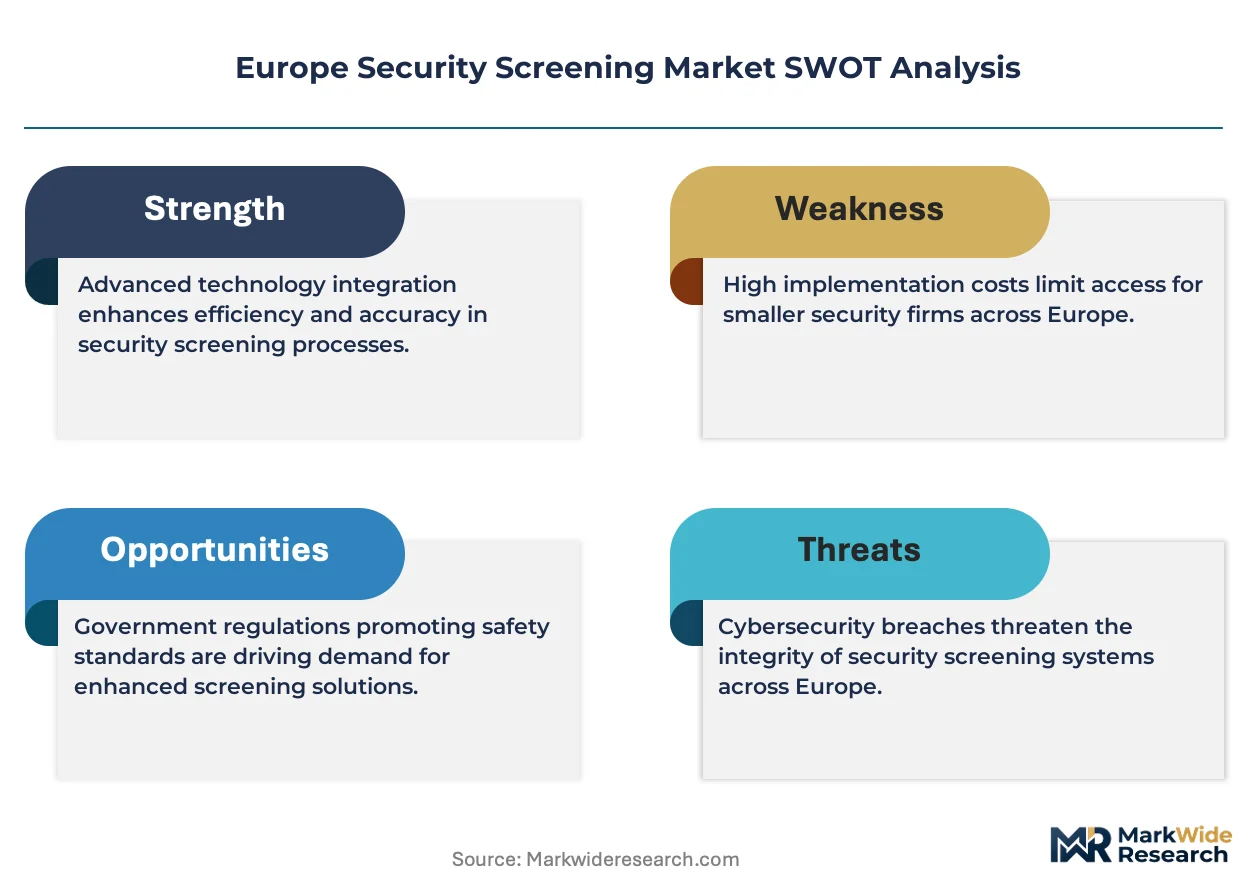
The EU AI Act's risk-classification requirements for automated decision systems are forcing vendors to redesign algorithmic transparency features, compressing product development cycles and elevating compliance costs across the European security screening supply base.
Growth Catalysts
- Aviation Security Regulation modernization:The EU's revised Aviation Security Regulation mandates equipment replacement cycles that accelerate procurement of millimeter wave imaging portals at major hub airports.
- France:Paris-Charles de Gaulle and Orly airports are executing multi-year terminal renovation programs that concentrate visible demand for integrated checkpoint solutions.
- Millimeter wave reflectance systems:GDPR-aligned privacy standards prohibiting backscatter X-ray deployment are channeling investment toward passive millimeter wave technology with superior passenger acceptance profiles.
Market Restraints
- GDPR biometric data constraints:France's CNIL enforces strict retention limits on facial recognition deployments, adding architectural complexity and compliance overhead to multimodal identity verification systems.
- Commodity baggage scanner saturation:X-ray machines face margin compression as tier-two European airports complete baseline equipment installation, limiting pricing power for legacy transmission imaging vendors.
- Technical limitation:Ion mobility spectrometry explosives trace detectors require frequent calibration and consumable replacement, elevating total cost of ownership and constraining deployment flexibility.
Strategic Opportunities
- Germany:German-speaking markets show underpenetrated demand for integrated baggage handling and screening systems, creating white space for vendors with automation engineering capabilities.
- Cyber Resilience Act harmonization:Forthcoming connected device certification standards under this EU framework will favor early-mover vendors who pre-integrate cybersecurity architecture into screening equipment.
- Millimeter wave and biometric convergence:Fusing passive imaging with facial recognition at passenger checkpoints enables premium pricing in government facility applications requiring multimodal verification.
Industry Challenges
- Algorithmic audit expertise scarcity:The EU AI Act's transparency requirements demand specialized machine learning interpretability skills that security hardware vendors struggle to recruit.
- Legacy system integration friction:Modern millimeter wave portals must interface with decades-old airport infrastructure, complicating deployment timelines and elevating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Security Screening Market |
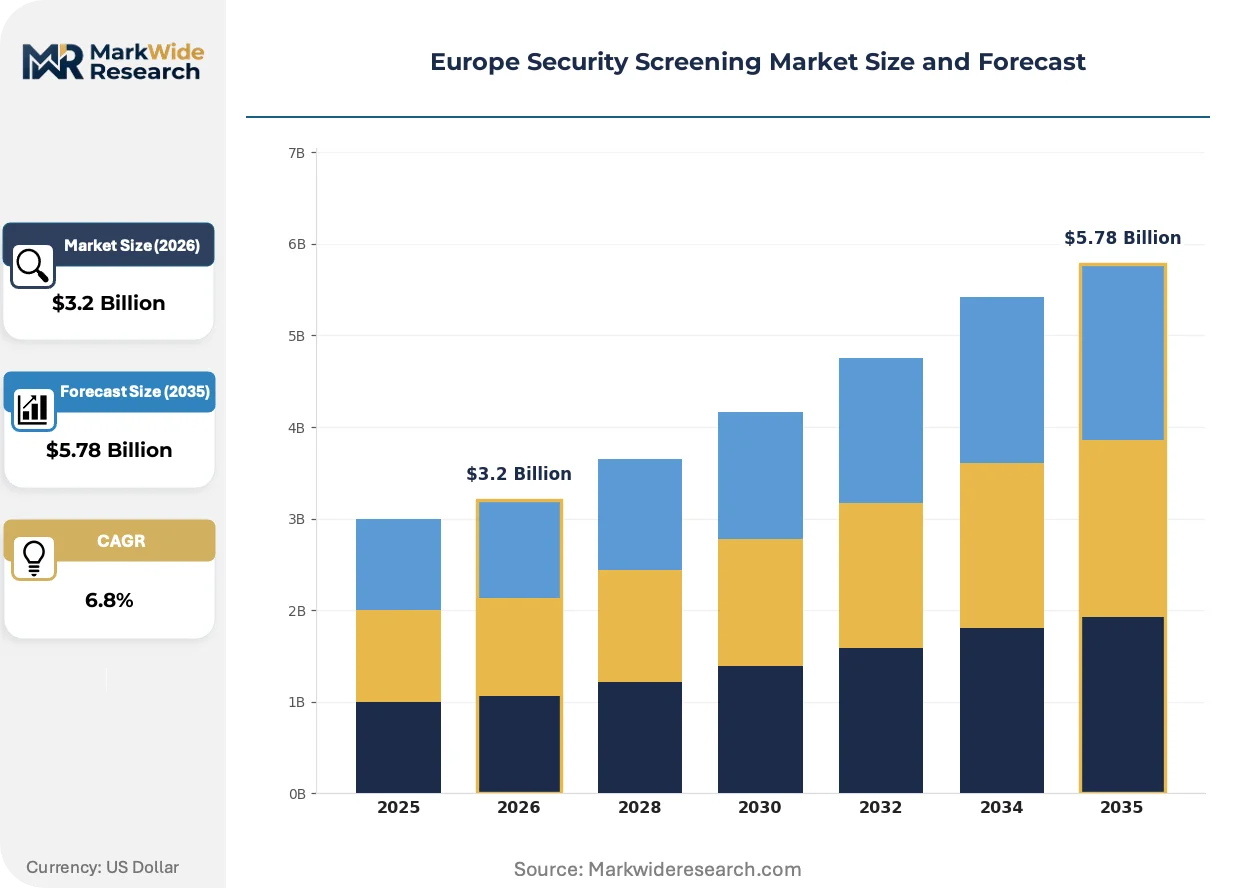
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Machines, Metal Detectors, Scanners, Explosives Trace Detection Application: Airport Security, Government Facilities, Transportation, Critical Infrastructure End User: Transportation Authorities, Law Enforcement, Public Sector, Private Security Technology: Millimeter Wave Imaging, Advanced Imaging Technology, Ground Penetrating Radar, Biometric Systems |
| Companies Covered | Smiths Detection Group Ltd., OSI Systems, Inc., Leidos Holdings, Inc., Teledyne Technologies Incorporated, Thales, Analogic Corporation, Nuctech Company Limited, Vanderlande Industries B.V., NEC Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Security Screening Market Shifts & Advancements
Regulatory technology mandates and privacy-preserving hardware architectures are reshaping competitive positioning across European aviation security, elevating systems integration capabilities above standalone equipment performance.
Millimeter wave reflectance imaging is integrating privacy-by-design architectures that process raw sensor data locally without storing passenger images. German and French hub operators are adopting these systems at accelerated pace to preempt GDPR enforcement actions. The technology is integrating with existing baggage handling infrastructure, compressing deployment timelines and reducing total project risk for airport operators.
The EU AI Act introduces formal risk classification for automated screening decision systems, compelling vendors to document algorithmic training data provenance and decision logic. This industrial consequence elevates compliance costs but creates differentiation for vendors with established audit trails. Explosives trace detection systems with embedded AI classification are most affected, with vendors redesigning firmware to expose decision thresholds for regulatory inspection.
Framework agreements spanning multiple airport sites are displacing single-site procurement as the dominant commercial model across European aviation authorities. This buyer concentration compresses vendor margins while extending contract durations and service obligations. The shift is most visible in France, where ADP Group's consolidated purchasing power shapes tender specifications across Paris-Charles de Gaulle, Orly, and regional airports.
Europe Security Screening Market Segmentation
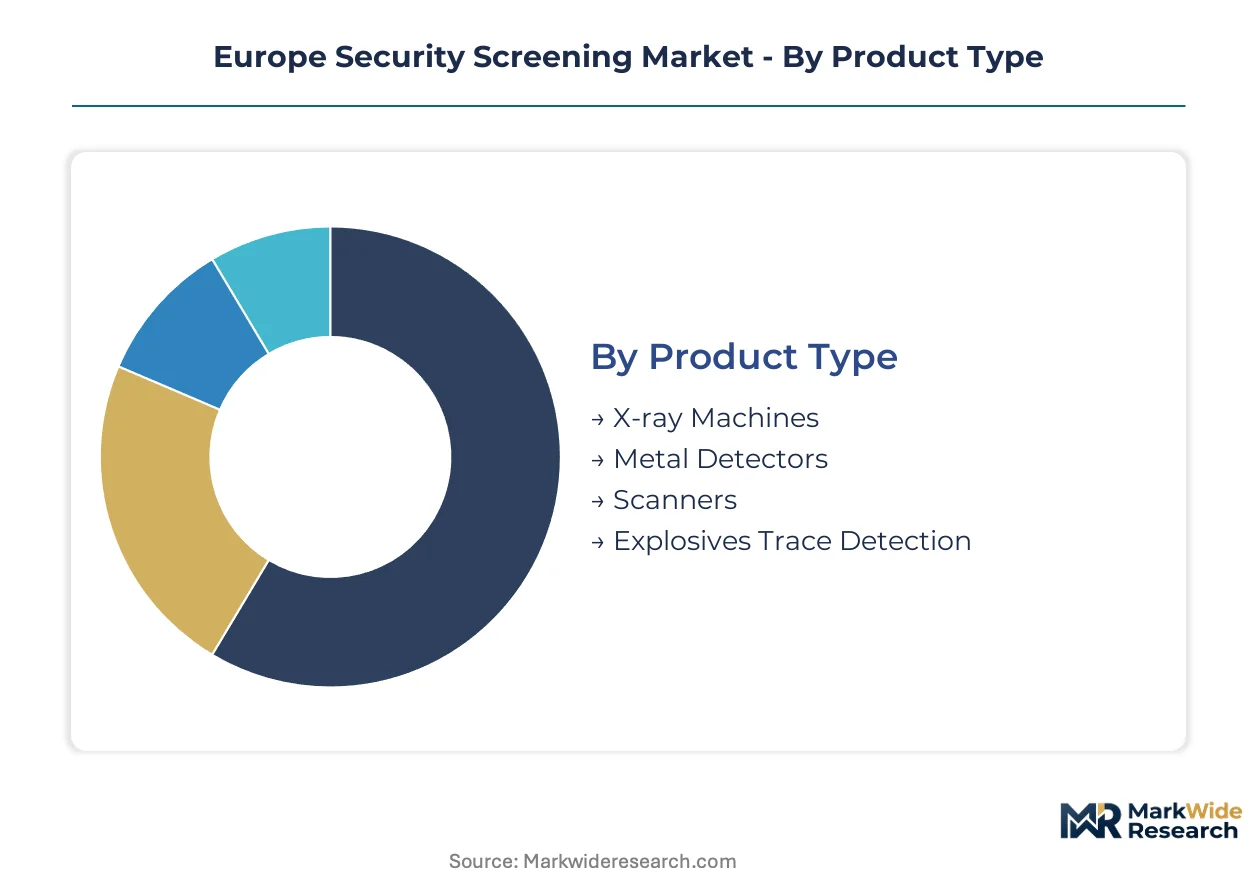
Technology differentiation and regulatory compliance requirements fragment the European security screening landscape across hardware specifications, deployment contexts, and operational architectures. Each segmentation axis reveals distinct procurement patterns shaped by EU mandates, privacy frameworks, and infrastructure modernization cycles.
Product Type:
Equipment specifications range from legacy transmission imaging to emerging chemical trace modalities, with procurement decisions increasingly governed by replacement timelines under EU Aviation Security Regulation.
- X-ray Machines:Transmission imaging systems utilizing dual-energy differentiation for material discrimination dominate baggage and cargo inspection installations. Tier-two European airports are completing baseline deployment, compressing margins for vendors supplying standard conveyor-fed configurations.
- Explosives Trace Detection:Ion mobility spectrometry and mass spectrometry devices detect vapor and particulate residues at parts-per-billion sensitivity. French and German aviation authorities are accelerating procurement of automated sampling systems to comply with EASA implementing acts on hold baggage screening.
- Metal Detectors:Walk-through and handheld electromagnetic induction systems provide primary screening at access control points.
- Scanners:Millimeter wave and backscatter imaging portals for personnel inspection.
X-ray Machines lead on scale; Explosives Trace Detection leads on momentum.
Application:
Deployment contexts vary dramatically in throughput requirements, threat models, and regulatory oversight intensity across European member states.
- Airport Security:Passenger checkpoints, hold baggage screening, and air cargo inspection represent the highest-value deployment environment. Paris-Charles de Gaulle and London Heathrow are executing multi-year terminal renovations that concentrate visible demand for integrated checkpoint solutions.
- Government Facilities:Ministries, embassies, and parliamentary complexes require multimodal verification fusing biometric identity with physical screening. France's CNIL enforces strict GDPR constraints on facial recognition retention, adding architectural complexity to system design.
- Transportation:Rail, metro, and maritime port security applications.
- Critical Infrastructure:Energy, telecommunications, and data center protection.
Airport Security captures the largest procurement volumes; Government Facilities commands the steepest expansion trajectory.
End User:
Buyer organizational structure determines contract scale, service obligation duration, and technical specification authority across European procurement frameworks.
- Transportation Authorities:Airport operators, rail networks, and port administrations with consolidated purchasing power. ADP Group in France and Fraport in Germany are shifting toward multi-site framework agreements that compress vendor margins while extending contract durations.
- Law Enforcement:Police and gendarmerie units requiring mobile and fixed-site screening for tactical operations and custody facilities.
- Public Sector:Municipal and regional government facility security.
- Private Security:Contract guarding firms and corporate security departments.
Transportation Authorities dominate contract value; Law Enforcement shows the fastest uptake of portable screening systems.
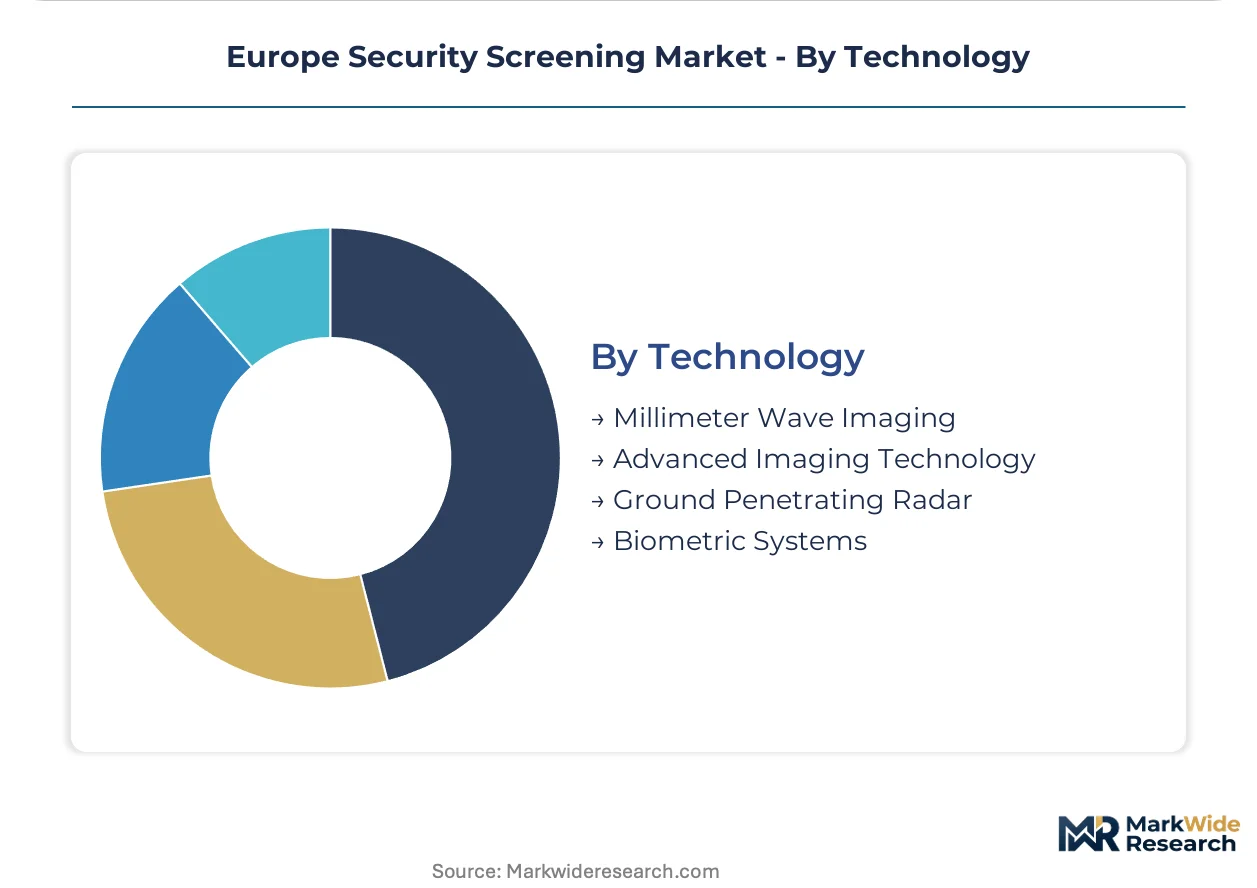
Technology:
Sensor architectures and algorithmic processing capabilities define competitive differentiation as EU AI Act compliance requirements reshape vendor development priorities.
- Millimeter Wave Imaging:Passive reflectance systems operating at 24-300 GHz frequencies generate anonymized passenger avatars without storing raw images. GDPR-aligned privacy standards prohibiting backscatter X-ray deployment are channeling investment toward this modality across German and French hub airports.
- Biometric Systems:Multimodal identity verification combining facial recognition, iris scanning, and document authentication commands premium pricing in high-assurance applications. Algorithmic transparency requirements under the EU AI Act are forcing vendors to redesign firmware for regulatory auditability.
- Advanced Imaging Technology:Automated target recognition software for threat detection.
- Ground Penetrating Radar:Subsurface scanning for vehicle and perimeter inspection.
Millimeter Wave Imaging leads on deployment velocity; Biometric Systems leads on pricing premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in German automation hubs, French systems integration centers, and British aviation technology corridors anchor security screening development across the continent.
Germany
Frankfurt Airport's terminal expansion and Munich's baggage handling modernization drive procurement of integrated screening systems. The KBA enforces strict vehicle safety standards that extend to airport ground support equipment certification. Bavaria's automation engineering cluster around Nuremberg supplies conveyor-integrated checkpoint solutions to Fraport's multi-site framework.
France
Paris-Charles de Gaulle and Orly airports execute concurrent terminal renovation programs requiring millimeter wave portal deployment. CNIL enforces GDPR-aligned biometric data retention limits that constrain facial recognition system architecture. Île-de-France's systems integration corridor hosts vendors serving ADP Group's consolidated purchasing authority across ten airport sites.
United Kingdom
Heathrow's checkpoint consolidation and Gatwick's security zone reconfiguration generate demand for passenger throughput optimization. The Civil Aviation Authority implements EASA-aligned explosive detection mandates for hold baggage screening. London's security technology cluster supplies integration services to British Airways' hub operations and government facility networks.
Italy
Rome-Fiumicino's terminal upgrade and Milan Malpensa's cargo screening expansion accelerate equipment replacement cycles. ENAC transposes EU Aviation Security Regulation requirements into national technical specifications for checkpoint equipment. Lombardy's precision manufacturing base produces X-ray scanner components for Mediterranean airport operators.
Netherlands
Amsterdam Schiphol's automated checkpoint pilot programs test biometric-integrated passenger flow management. The Human Environment and Transport Inspectorate enforces EASA implementing acts on explosive detection system performance. Randstad's logistics technology corridor develops baggage handling integration modules for Benelux airport networks.
Europe Security Screening Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a moderately consolidated vendor landscape. Systems integration capabilities and regulatory compliance architecture now outweigh standalone equipment performance as procurement criteria. Three archetypes dominate: aerospace-defense conglomerates leveraging cross-sector technology transfer, security-focused specialists with deep ion mobility spectrometry expertise, and automation engineering firms with baggage handling integration heritage. Competitive moves center on multi-site framework agreement capture and algorithmic transparency feature development for EU AI Act compliance.
Within the systems integration tier, Thales and Smiths Detection Group Ltd. exemplify contrasting strategic positions. Thales occupies a position shaped by French aviation heritage and cross-sector defense technology application. Smiths Detection Group Ltd. anchors the explosives trace detection segment through sustained specialization in chemical sensing modalities. OSI Systems, Inc. sits within the automation-integrated screening archetype, with its corporate structure suggesting baggage handling engineering capabilities relevant to German-speaking market penetration.
| Leading Market Players |
|---|
| Smiths Detection Group Ltd. |
| OSI Systems, Inc. |
| Leidos Holdings, Inc. |
| Teledyne Technologies Incorporated |
| Thales |
| Analogic Corporation |
| Nuctech Company Limited |
| Vanderlande Industries B.V. |
| NEC Corporation |
| Others |
Supply & Pricing Matrix
ADP Group's consolidated purchasing authority across ten French airport sites is compressing vendor margins and forcing suppliers toward multi-year framework agreements with extended service obligations. This buyer concentration shifts pricing power toward transportation authorities while elevating total cost of ownership calculations for screening equipment vendors.
Pricing Analysis
Capacity additions in German automation engineering clusters are reshaping price floors for baggage-integrated checkpoint solutions. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by EASA certification tier and after-sales service bundling. Cost compression in standard X-ray configurations is intensifying because tier-two European airports complete baseline equipment installation. Transportation authorities exhibit highest price sensitivity due to consolidated purchasing power, while government facilities show lowest sensitivity given multimodal verification requirements.
Supply Chain Analysis
EASA implementing acts and EU AI Act conformity assessment procedures create qualification gates that filter component suppliers. Manufacturing concentrates in Germany, France, and the Netherlands, with sensor modules drawing from Bavarian precision engineering clusters and software development resting on Île-de-France systems integration capabilities. Supply chain risk centers on single-source vulnerability for millimeter wave transmitter arrays. Distribution runs through direct vendor-airport operator contracts with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Security Screening Market functions as a stable compounder, with regulatory-mandated replacement cycles under EU Aviation Security Regulation generating predictable procurement visibility across the projection horizon.
For Market Incumbents: Anticipate margin compression from framework agreement consolidation by embedding cybersecurity architecture early for Cyber Resilience Act compliance. Prioritize algorithmic transparency feature development to capture EU AI Act audit-ready positioning. Vertical integration into millimeter wave sensor production offers cost control against transmitter array supply constraints.
For New Entrants and Emerging Players: Launch via baggage handling automation partnerships in German-speaking markets where Fraport's multi-site procurement creates white space. Target underpenetrated rail and metro security applications with portable explosives trace detection systems. Emphasize GDPR-aligned privacy-by-design architectures to differentiate against legacy backscatter X-ray vendors.
For Investors and Strategic Acquirers: Asymmetric upside sits with automation engineering specialists possessing baggage handling integration heritage and established EASA certification pathways. Long-term viability favors vendors with recurring service revenue streams from multi-year framework agreements. Watch for EU harmonized standards under Cyber Resilience Act as inflection trigger for cybersecurity-preintegrated equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Investment | EU AI Act compliance creates audit-ready differentiation for explosives trace detection vendors. |
| Multi-Site Framework Capture | ADP Group consolidated purchasing compresses margins but locks in decade-long service revenue streams. |
| Millimeter Wave Sensor Backward Integration | Captive supply of transmitter arrays mitigates single-source vulnerability in German manufacturing clusters. |
| Biometric-GDPR Architectural Redesign | CNIL retention limits force firmware restructuring for French government facility deployments. |
| Cybersecurity Pre-Integration | Cyber Resilience Act certification timelines favor early-mover vendors with embedded security architecture. |
Research Methodology
Direct dialogue with airport procurement directors, EASA certification specialists, systems integration engineers, and CNIL compliance officers grounded qualitative findings. Secondary validation drew from EASA implementing acts, EU Aviation Security Regulation amendments, ADP Group tender documentation, and SEC filings from listed screening equipment vendors. Bottom-up equipment deployment estimates triangulated against top-down market sizing from regulatory replacement cycle analysis.
Bottom-up modeling segmented the market across product type, application context, end-user organizational structure, and technology modality throughout the forecast period. CAGRs derived from regression analysis of historical procurement patterns against regulatory mandate timelines. Industry-specific inputs included EASA explosive detection system performance standards and EU AI Act risk classification implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under delayed Cyber Resilience Act harmonization or accelerated GDPR enforcement actions. Forecasts reflect documented assumptions on regulatory implementation timelines and airport capital expenditure cycles. A model refresh is warranted upon material change in EU AI Act delegated act publication schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Prison Management Systems Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
Airport Baggage Screening Systems Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Private Security Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Intelligent Fencing Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Global Firearm Sight Market