
 Latin America Security Services Market | 2026-2036
Latin America Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Security Services Market Insights
Modular service bundling is pivoting how Latin American enterprises purchase security, with buyers mixing on-site guarding, remote monitoring, and cyber defense into single contracts rather than procuring each layer separately. Securitas anchors its regional footprint through integrated facility management offerings that combine physical patrols with access control technology. Palo Alto Networks competes by extending cloud-native cybersecurity platforms into mid-market accounts across Mexico and Chile. IBM Corporation differentiates through AI-powered threat detection services tailored to financial institutions in Brazil.
Latin America security services encompass the design, deployment, and ongoing management of protective systems spanning physical infrastructure and digital networks, incorporating specifications such as real-time video analytics, biometric authentication protocols, and encrypted data transmission standards to safeguard assets, personnel, and information. The primary commercial purpose centers on risk mitigation for organizations facing elevated crime rates, cyber intrusion attempts, and regulatory compliance obligations. Access control and video surveillance command the largest share of service revenue due to persistent demand from retail and banking sectors upgrading legacy installations. Cloud security within the technology dimension represents the fastest-expanding segment as enterprises migrate operations to distributed architectures requiring continuous monitoring. Cybersecurity application services capture concentrated margin pools because specialized talent scarcity allows providers to command premium pricing for incident response and vulnerability management.
Brazil's LGPD enforcement by the national data protection authority shapes cybersecurity service demand by mandating breach notification and data governance protocols for companies processing personal information. Mexico's Federal Telecommunications Institute and Colombia's national data protection authority impose complementary standards that drive cross-border compliance investments by multinational corporations operating across Andean and Southern Cone markets. ANVISA in Brazil adds healthcare-specific security requirements for pharmaceutical and medical device supply chains. Stakeholders must monitor how regulatory fragmentation across national jurisdictions affects service standardization and whether harmonization efforts through regional trade mechanisms alter compliance cost structures.
Market Dynamics
LGPD enforcement in Brazil is compressing procurement cycles for cybersecurity services as enterprises race to meet data governance mandates before penalty thresholds activate, creating immediate demand for compliance-oriented security bundles.
Growth Catalysts
- Biometric authentication protocols:Banking institutions across São Paulo and Rio de Janeiro are retrofitting branch networks with fingerprint and facial recognition systems to reduce fraud exposure. This hardware refresh pulls integrated service contracts for installation and monitoring.
- LGPD breach notification requirements:Brazil's national data protection authority mandates 72-hour disclosure windows for personal data incidents, forcing enterprises to retain incident response retainers and continuous monitoring services.
- Cloud migration acceleration:Mid-market manufacturers in Mexico are relocating ERP and customer databases to distributed architectures, requiring cloud-native security posture management that legacy on-premise providers cannot supply.
Market Restraints
- Specialized talent scarcity:Certified ethical hackers and cloud security architects command 40-60% salary premiums over general IT staff, inflating service delivery costs for providers and compressing margins on fixed-price contracts.
- Import dependency for hardware:Video surveillance cameras and access control panels concentrate sourcing from East Asian manufacturing clusters, exposing Brazilian integrators to currency volatility and extended lead times.
- Legacy system incompatibility:Decades-old analog CCTV installations in Colombian retail chains resist integration with AI-powered analytics platforms, forcing expensive rip-and-replace cycles that delay upgrade decisions.
Strategic Opportunities
- Andean corridor underpenetration:Peru and Ecuador maintain security service spending at roughly one-third of Brazilian per-enterprise levels, presenting first-mover expansion potential for integrated facility management providers.
- Healthcare-specific compliance:ANVISA's pharmaceutical supply chain security requirements create a regulated niche for temperature monitoring, track-and-trace, and facility access services that generalist competitors cannot address.
- Convergence of physical and cyber monitoring:Unified threat management platforms that correlate badge-swipe anomalies with network intrusion attempts are electrifying interest among financial institutions seeking single-pane visibility.
Industry Challenges
- Certification timeline compression:LGPD compliance audits require documented security controls that many Brazilian SMEs lack, stretching provider implementation capacity and delaying revenue recognition.
- Integration complexity with fragmented vendor stacks:Enterprises running Palo Alto firewalls alongside legacy HID access control systems demand custom API development that erodes standardization benefits and extends project durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Security Services Market |
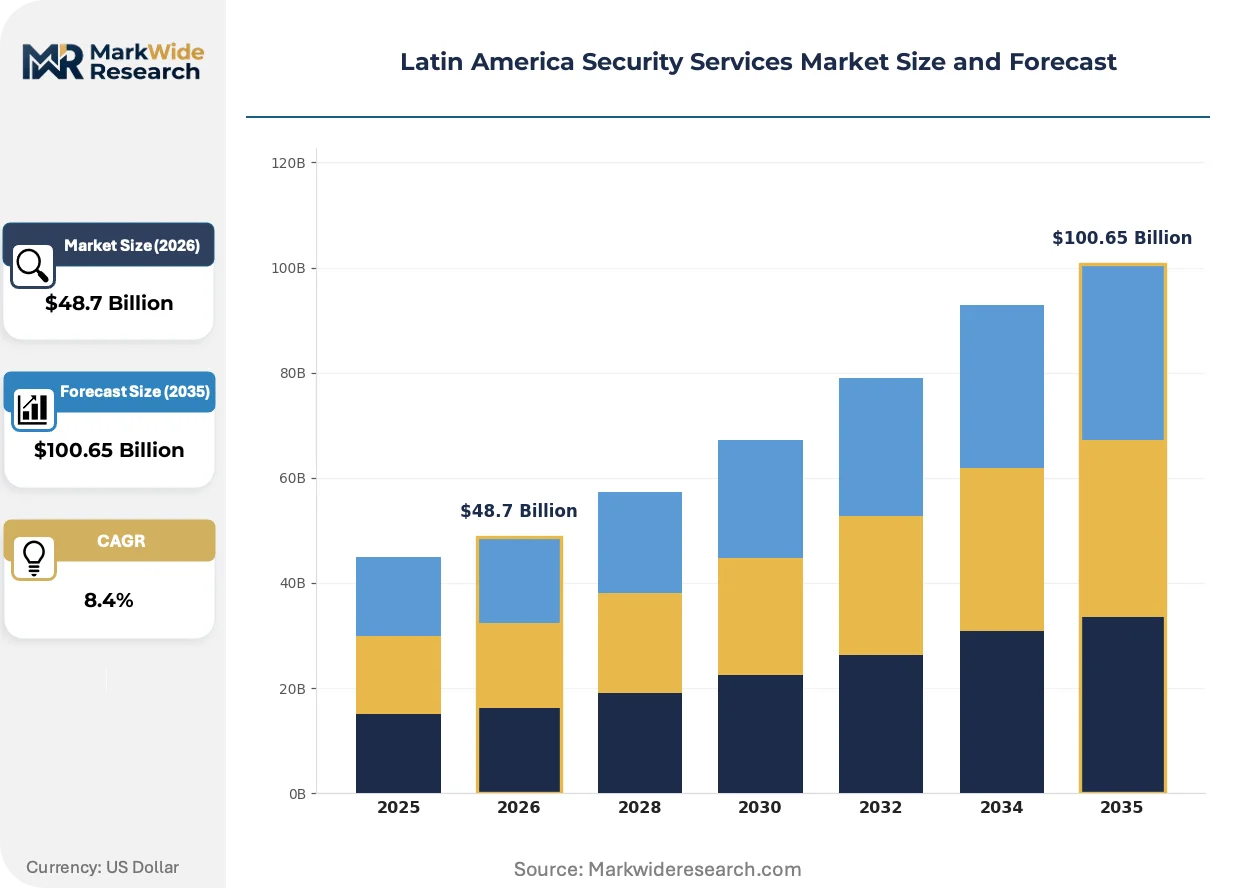
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Access Control, Video Surveillance, Intrusion Detection, Fire Safety End User: Government, Retail, Healthcare, Hospitality Technology: Biometric Systems, RFID, IP Cameras, Cloud Security Application: Home Security, Business Security, Transportation Security, Cybersecurity |
| Companies Covered | Akati Sekurity, Fortra, Securitas, Wipro, Broadcom, Allied Universal, IBM Corporation, Palo Alto Networks, G4S, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Security Services Market Trends and Innovations
Security service delivery across Latin America is pivoting from reactive incident response toward predictive threat neutralization, with artificial intelligence and regulatory automation compressing detection-to-remediation intervals.
Edge-deployed video analytics with real-time behavioral recognition is electrifying perimeter security effectiveness. Brazilian critical infrastructure operators in oil and gas are adopting these systems to automate intrusion detection without human monitor latency. The technology compresses false alarm rates while enabling guard force reduction at remote facility locations.
Colombia's national data protection authority is tightening cross-border data transfer documentation requirements, compelling multinational corporations to localize security operations centers within national boundaries. Financial services firms with Andean operations are responding by establishing Bogotá-based monitoring hubs rather than centralizing through Miami or São Paulo.
Enterprise buyers are unbundling long-term guarding contracts into discrete service modules with separate pricing for technology, personnel, and software licensing. Mexican automotive manufacturers near Monterrey pioneered this approach, forcing incumbents to compete on individual component margins rather than bundled relationship value. The pattern is spreading to Chilean mining operations seeking operational transparency in security spend.
Latin America Security Services Market Segmentation
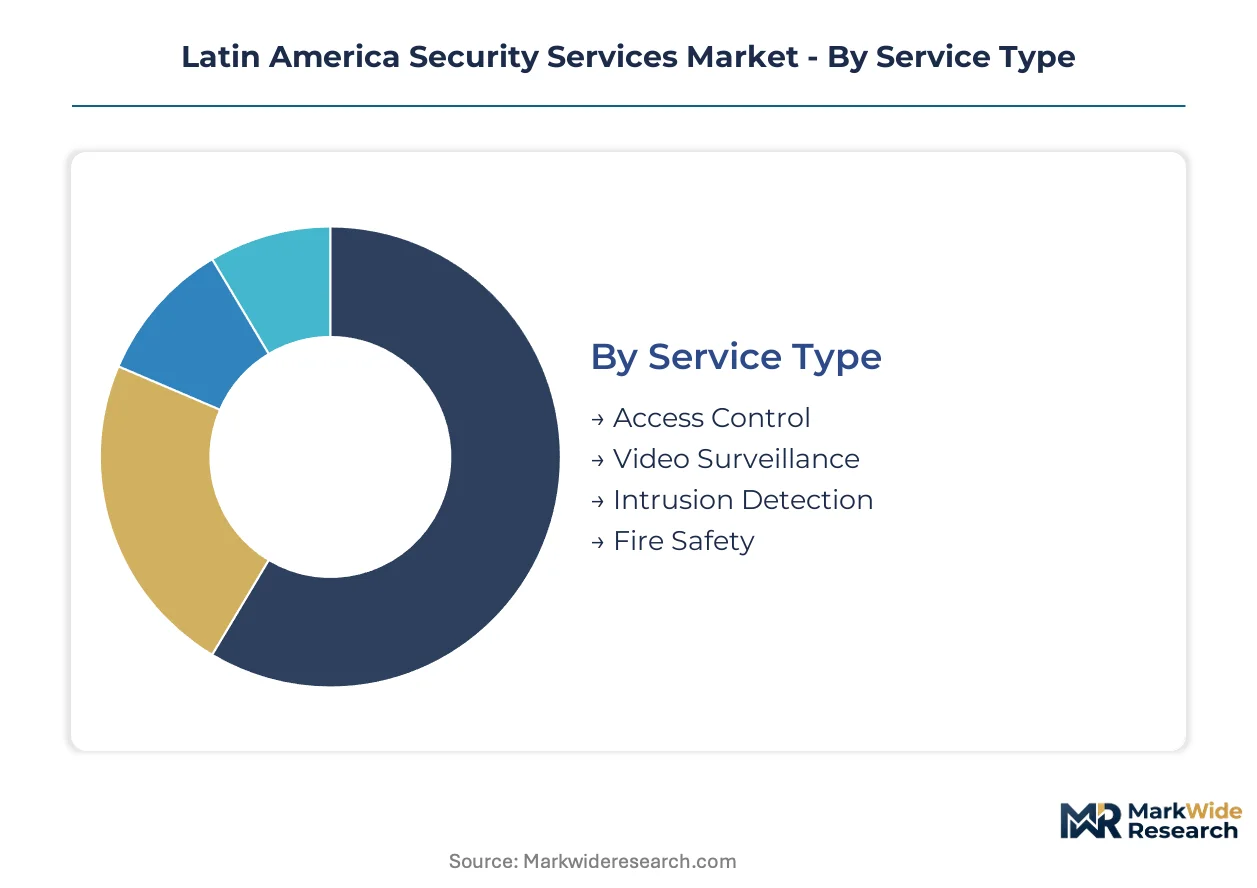
Latin American enterprises purchase security services through distinct procurement lenses that shape contract structures and vendor selection. Service type determines whether buyers seek integrated facility management or specialized point solutions. End user verticals impose sector-specific compliance requirements that filter provider eligibility. Technology choices reflect infrastructure maturity and talent availability across national markets.
Service Type:
Customization intensity varies sharply across protective service categories, with some segments demanding bespoke integration while others operate through standardized deployment playbooks.
- Access Control:Electronic credentialing systems combining card readers, biometric scanners, and centralized management platforms. Banking networks across São Paulo and Rio de Janeiro are retrofitting branches with multi-factor authentication to meet LGPD data governance mandates, pulling integrated installation and monitoring contracts.
- Video Surveillance:Real-time monitoring infrastructure spanning analog upgrades, IP camera networks, and AI-powered analytics engines. Colombian retail chains face expensive rip-and-replace cycles as decades-old CCTV installations resist integration with modern platforms, delaying upgrade decisions.
- Intrusion Detection:Perimeter sensors and alarm systems for facility protection.
- Fire Safety:Suppression systems and emergency response protocols for asset protection.
Most installed capacity flows through Video Surveillance. Expansion is steepest in Access Control.
End User:
Contract value and renewal patterns diverge significantly across buyer categories, with regulated industries commanding premium pricing and longer engagement terms.
- Government:Public infrastructure protection and municipal surveillance networks. Federal procurement across Mexico and Brazil concentrates in critical facility guarding and border monitoring, though budget cycles create payment delays that strain provider cash flow.
- Retail:Loss prevention and customer safety systems. Shopping centers in Santiago and Buenos Aires are unbundling long-term guarding contracts into discrete modules with separate technology and personnel pricing, forcing margin compression on incumbents.
- Healthcare:Patient data protection and facility access management. ANVISA's pharmaceutical supply chain requirements create a regulated niche for temperature monitoring and track-and-trace services that generalist competitors cannot address.
- Hospitality:Guest safety and property protection services.
Revenue concentration sits with Government accounts. Healthcare is gaining share fastest as compliance requirements tighten.
Technology:
Adoption velocity correlates directly with local technical talent availability and import infrastructure for hardware components.
- Biometric Systems:Fingerprint, facial recognition, and behavioral authentication protocols. Financial institutions are deploying these for fraud reduction, though hardware sourcing from East Asian manufacturing clusters exposes Brazilian integrators to currency volatility and extended lead times.
- Cloud Security:Distributed architecture protection and continuous monitoring services. Mid-market manufacturers in Mexico are relocating ERP systems to cloud environments, requiring native security posture management that legacy on-premise providers cannot supply.
- RFID:Wireless identification and asset tracking technologies.
- IP Cameras:Network-connected video capture and transmission devices.
Hardware deployment dominates current infrastructure. Cloud Security is climbing the fastest as migration accelerates.
Application:
Solution complexity scales with asset criticality, from residential monitoring through national infrastructure protection.
- Cybersecurity:Network defense, incident response, and vulnerability management. LGPD's 72-hour breach notification mandate forces Brazilian enterprises to retain continuous monitoring services and incident response retainers, creating immediate demand compression.
- Business Security:Integrated physical and digital protection for commercial facilities. Corporate headquarters in São Paulo and Mexico City are converging physical access logs with network intrusion monitoring through unified threat management platforms.
- Home Security:Residential monitoring and alarm services.
- Transportation Security:Logistics protection and cargo monitoring systems.
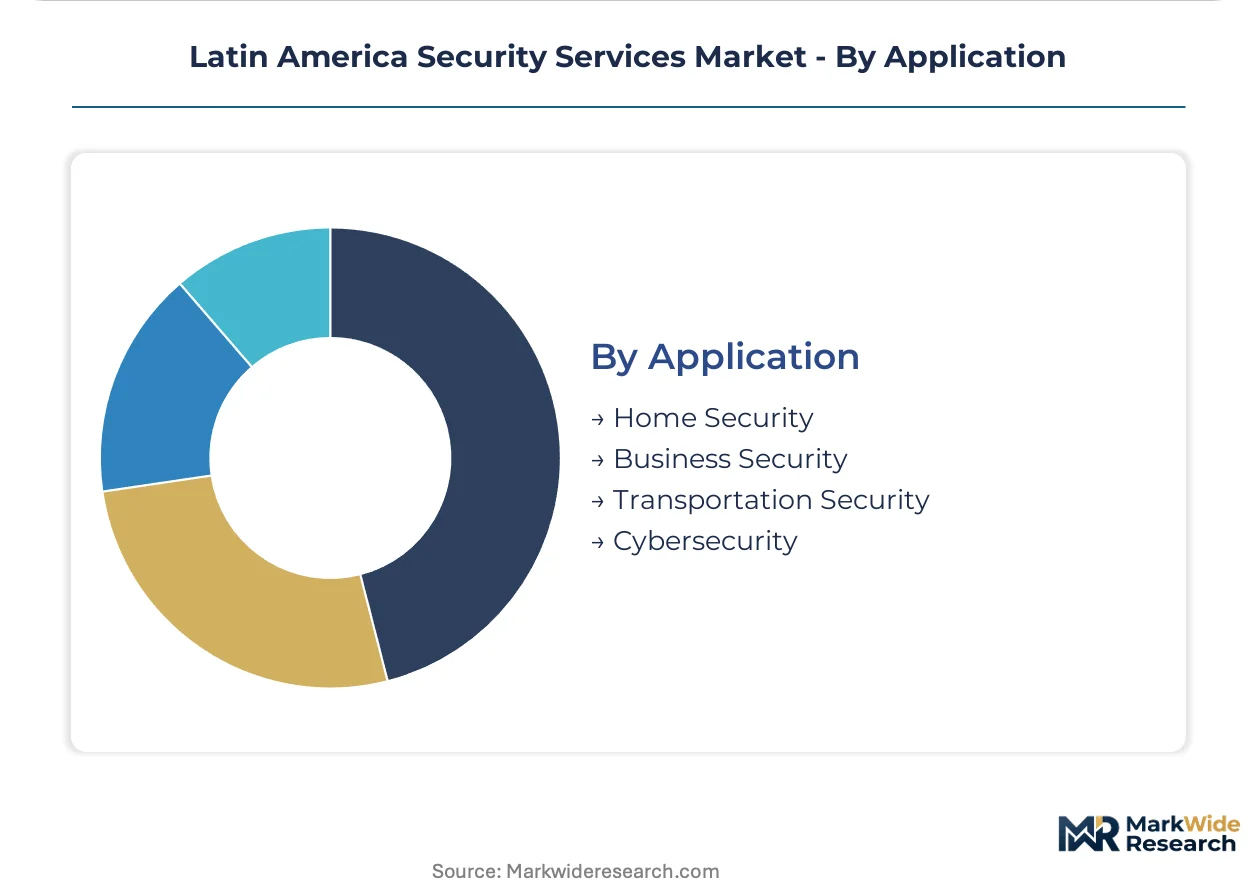
Business Security commands the largest contract values. Cybersecurity shows the steepest expansion trajectory as regulatory enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Physical security contracting in Latin America originated with multinational mining and oil operations establishing guarded perimeters in remote extraction zones. Brazilian conglomerates later professionalized facility management services for corporate headquarters and banking networks. Regulatory frameworks governing data protection and critical infrastructure protection now shape procurement patterns across national markets.
Brazil
Banking networks in São Paulo and Rio de Janeiro are retrofitting branches with biometric authentication systems to meet LGPD data governance mandates. ANVISA imposes pharmaceutical supply chain security requirements that create regulated niches for temperature monitoring and track-and-trace services. Corporate headquarters clustering in São Paulo's Faria Lima district are converging physical access logs with network intrusion monitoring through unified threat management platforms.
Mexico
Mid-market manufacturers near Monterrey are relocating ERP systems to cloud environments, requiring native security posture management that legacy on-premise providers cannot supply. The Federal Telecommunications Institute imposes data protection standards that drive cross-border compliance investments by multinational corporations operating across Andean and Southern Cone markets. Automotive production facilities in Nuevo León are unbundling long-term guarding contracts into discrete service modules with separate technology and personnel pricing.
Colombia
Retail chains face expensive rip-and-replace cycles as decades-old CCTV installations resist integration with AI-powered analytics platforms. The national data protection authority is tightening cross-border data transfer documentation requirements, compelling financial services firms to establish Bogotá-based monitoring hubs rather than centralizing through Miami. Critical infrastructure operators in oil and gas are adopting edge-deployed video analytics with real-time behavioral recognition to automate intrusion detection.
Chile
Mining operations in the Atacama Desert are seeking operational transparency in security spend through modular contract structures. The national cybersecurity strategy imposes sector-specific requirements for critical mineral extraction facilities. Santiago-based corporate headquarters are driving demand for cloud-native security posture management as enterprises migrate customer databases to distributed architectures.
Argentina
Financial institutions in Buenos Aires are deploying fingerprint and facial recognition systems to reduce fraud exposure in branch networks. Central bank regulations mandate documented security controls for institutions processing personal financial information. Shopping centers in the Buenos Aires metropolitan area are fragmenting procurement across specialized providers rather than relying on integrated facility management contracts.
Latin America Security Services Market Competitive Landscape
The competitive structure tilts toward integrated facility management providers with established physical security footprints. Tiered specialization separates multinational cybersecurity platforms from regional guarding contractors and niche compliance consultants. Three archetypes dominate: integrated facility managers bundling on-site patrols with access control technology, cloud-native cybersecurity specialists serving mid-market migration needs, and AI-powered threat detection providers targeting financial institution accounts. M&A activity concentrates on acquiring certified ethical hacker teams, while geographic expansion targets underpenetrated Andean markets.
Within the integrated facility management tier, Securitas and Allied Universal exemplify providers combining physical patrols with technology deployment. G4S occupies a position bridging guarding services with critical infrastructure protection. Among cybersecurity specialists, Palo Alto Networks and IBM Corporation represent cloud-native and AI-powered archetypes respectively. Fortra and Broadcom sit within the technology infrastructure layer supplying underlying platforms. Akati Sekurity and Wipro exemplify regional and offshore delivery models competing on implementation capacity.
| Leading Market Players |
|---|
| Akati Sekurity |
| Fortra |
| Securitas |
| Wipro |
| Broadcom |
| Allied Universal |
| IBM Corporation |
| Palo Alto Networks |
| G4S |
| Others |
Pricing and Supply Chain Analysis
Certified ethical hacker labor costs cascade through Latin American security service tiers, with São Paulo-based talent premiums compressing margins on fixed-price contracts while Colombian and Peruvian delivery centers capture arbitrage value on remote monitoring engagements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes the Latin American security services market, with premium tiers commanding certification-grade premiums for LGPD-compliant incident response retainers and standard tiers competing on per-guard-hour rates for facility management. Price differentiation rests on compliance certification depth and geographic delivery cost, with Bogotá-based operations undercutting São Paulo rates by meaningful margins. Cost compression in standard-tier guarding intensifies as Mexican automotive buyers unbundle contracts into discrete modules. Retail chains in Santiago exhibit highest price sensitivity, while ANVISA-regulated pharmaceutical facilities show lowest sensitivity due to mandated service specifications.
Supply Chain Analysis
Brazil's local-content mandates for critical infrastructure protection are reshaping sourcing patterns, compelling integrators to substitute domestic assembly for direct hardware imports. Video surveillance cameras and biometric scanners draw from East Asian manufacturing clusters in China, Taiwan, and South Korea, with access control panels similarly concentrated. Currency volatility against the Brazilian real creates persistent margin risk for hardware-dependent contracts. Distribution runs through São Paulo and Mexico City logistics hubs serving national integrator networks, with final-mile deployment handled by regional facility management providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America security services function as a geographic-arbitrage play where talent cost differentials between São Paulo and Andean delivery centers create 40-60% service delivery cost spreads, while regulatory fragmentation across LGPD, Mexico's Federal Telecommunications Institute standards, and Colombian data protection mandates forces compliance investment localization.
For Market Incumbents: Extend platform convergence capabilities by integrating physical access logs with network intrusion monitoring through unified threat management architectures, defending against cloud-native cybersecurity specialists capturing mid-market manufacturing accounts. Backward integration into certified ethical hacker training programs in Colombia and Peru reduces talent cost exposure while creating captive capability for incident response retainers. For New Entrants and Emerging Players: Enter via healthcare-specific compliance services targeting ANVISA-regulated pharmaceutical supply chains, where temperature monitoring and track-and-trace requirements create defensible niches against generalist competitors. The Andean corridor presents most penetrable geography, with Peruvian and Ecuadorian security service spending at roughly one-third Brazilian per-enterprise levels. Go-to-market leverage through cloud-native security posture management partnerships with mid-market manufacturers migrating ERP systems. For Investors and Strategic Acquirers: Roll-up economics work for regional facility management providers because fragmented vendor stacks across Palo Alto firewalls and legacy HID access control systems demand custom API development that erodes standardization benefits, creating consolidation value through platform integration. Long-term viability centers on AI-powered threat detection capabilities serving financial institution accounts. Watch for LGPD penalty threshold activation as inflection indicator compressing procurement cycles toward compliance-oriented bundles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified threat management correlating physical badge-swipe anomalies with network intrusion attempts electrifies financial institution demand. |
| Acquisition of Specialist Firm | Certified ethical hacker teams in Colombia and Peru capture arbitrage value on remote monitoring and incident response delivery. |
| Geographic Expansion | Bogotá-based monitoring hubs address Colombian cross-border data transfer documentation requirements for Andean financial services. |
| Product Launch | Edge-deployed video analytics with real-time behavioral recognition automates intrusion detection for Brazilian oil and gas operators. |
| Strategic Partnership | Cloud-native security posture management alliances with mid-market manufacturers address ERP migration requirements in Monterrey corridors. |
Research Methodology
Multiple input streams — primary interviews with security operations directors, IT procurement officers, and compliance leads at financial institutions and pharmaceutical manufacturers; regulatory filings from Brazil's national data protection authority and ANVISA; and customs data on security hardware imports — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC disclosures of listed security service providers, hyperscaler cloud security capex reports, and sector-specific trade association publications across Latin American markets.
Data-stream reconciliation anchored the analytical framework across the analysis window, with segmentation dimensions spanning service type, end-user vertical, technology deployment, and application complexity. CAGRs were derived through trend extrapolation of procurement cycle compression and cloud migration velocity, incorporating LGPD enforcement timelines and ANVISA regulatory expansion as industry-specific forecast inputs.
Inputs from primary stakeholder interviews and regulatory authority publications were available through the study window; gaps in real-time breach incident reporting and private contract value disclosures introduce uncertainty bands around service revenue estimates. Forecasts reflect documented assumptions regarding compliance timeline adherence and hardware import cost stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Global Security As a Service Market
Security and Surveillance
Security and Surveillance Equipment Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Global Acoustic Hailing Devices Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Shock Sensor Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Integrated Security Solutions Market