
 Cellulosic Fire Protection Market | 2026-2036
Cellulosic Fire Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulosic Fire Protection Market Outlook
Multi-source procurement among specialty chemical buyers is hardening as a dominant sourcing pattern across the cellulosic fire protection supply base. Akzo Nobel N.V. leverages its European manufacturing footprint to sustain consistent specification-grade output for infrastructure tenders. Sika AG anchors its position through deep channel relationships with applicator networks in commercial construction. PPG Industries, Inc. competes by extending its protective coatings portfolio into complementary fire-retardant chemistries.
Cellulosic fire protection denotes passive fire-resistance systems derived from plant-based fibers, typically incorporating intumescent additives that expand under thermal exposure to form insulating char layers exceeding 50 times original thickness. These systems protect structural steel, timber assemblies, and composite substrates by delaying temperature rise to critical failure thresholds during compartment fires. Sprays and coatings command the largest share of product-type revenue, though sealants represent a faster-growing margin pool as joint-system specifications tighten in high-occupancy buildings. Construction absorbs the dominant application volume, while aerospace qualifies as a premium segment where certification cycles and material traceability requirements sustain elevated pricing.
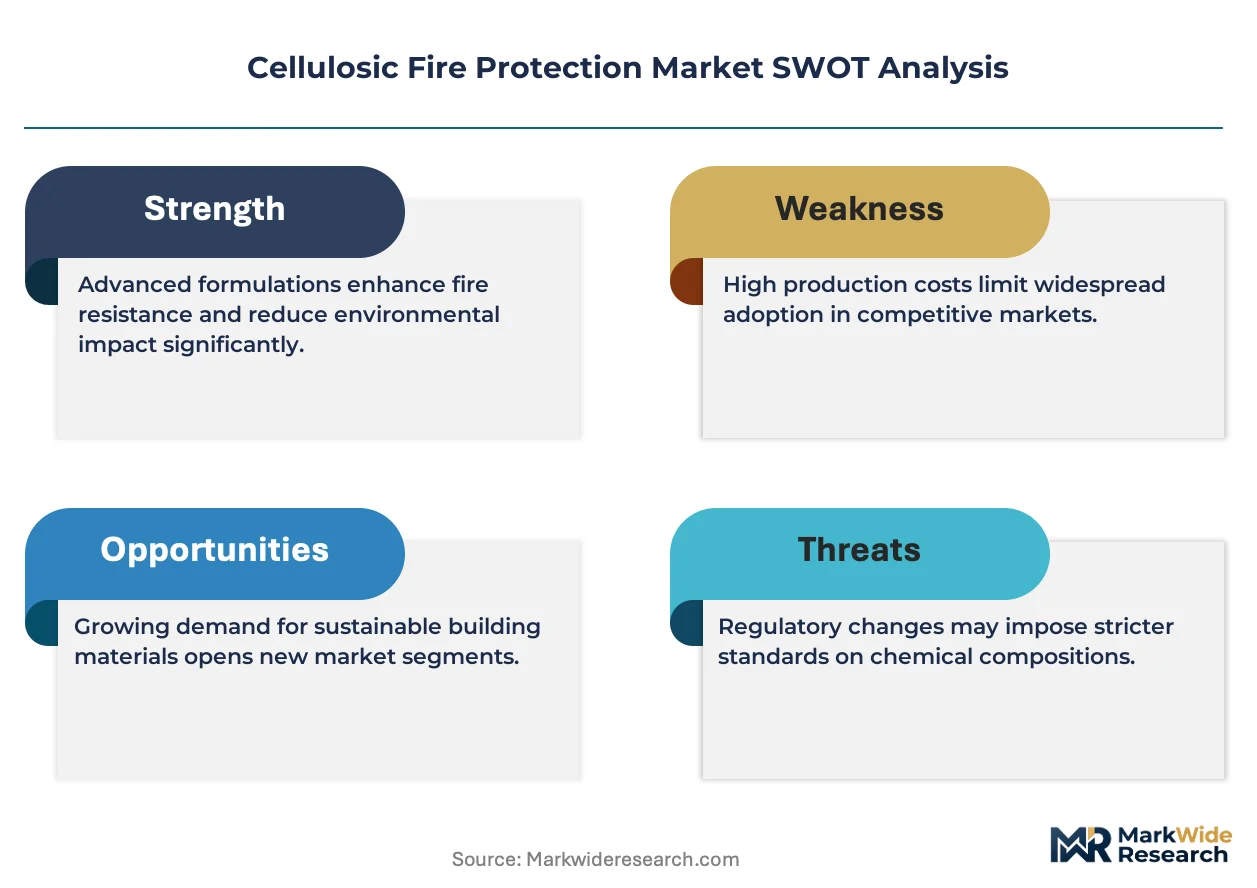
Building codes enforced by national regulators—including the EPA's VOC emission limits on architectural coatings, the EU Construction Products Regulation's CE marking requirements for fire-reaction performance, and Germany's KBA-influenced standards for transport infrastructure—collectively elevate compliance costs while filtering subscale suppliers. ASTM E119 and ISO 834 time-temperature curves function as de facto global benchmarks for product qualification, creating harmonized testing barriers that favor laboratories with multi-jurisdiction accreditation. Stakeholders must monitor evolving bio-based content thresholds and carbon-accounting rules that threaten to recategorize traditional cellulosic formulations ahead of anticipated regulatory revisions.
Market Dynamics
Steel-frame commercial construction in Germany is tightening passive fire protection mandates under KBA-influenced building codes, compressing specification windows and elevating compliance burdens for coating applicators and raw material suppliers alike.
Growth Catalysts
- EU Construction Products Regulation CE marking:Harmonized fire-reaction performance standards are filtering subscale coating suppliers and consolidating procurement toward accredited manufacturers.
- High-rise commercial construction:Intumescent coating systems are expanding specification share as steel-frame building heights increase across urban cores.
- Timber assembly protection:Cross-laminated timber building codes are mandating upgraded char-layer performance for structural composite substrates.
Market Restraints
- Epoxy resin input cost volatility:Petrochemical feedstock fluctuations compress margin stability for intumescent coating formulators.
- Laboratory accreditation concentration:Multi-jurisdiction ASTM E119 and ISO 834 testing capability clusters in Western European facilities, creating qualification bottlenecks.
- Cementitious spray substitution:Lower-cost passive fire protection alternatives capture specification share in cost-sensitive infrastructure tenders.
Strategic Opportunities
- Aerospace certification premium:Material traceability requirements and extended qualification cycles sustain elevated pricing in aircraft interior applications.
- Sealant joint-system specifications:High-occupancy building codes are tightening penetration and movement-joint firestopping standards faster than coating specifications.
- Bio-based content thresholds:Anticipated carbon-accounting rule revisions threaten to recategorize traditional cellulosic formulations, opening reformulation windows for plant-fiber innovators.
Industry Challenges
- Applicator certification gaps:Specialized spray equipment training and intumescent thickness verification skills are scarce in emerging construction markets.
- Multi-jurisdiction testing timelines:Simaneous ASTM E119, ISO 834, and EN 13381 qualification cycles extend product launch schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulosic Fire Protection Market |
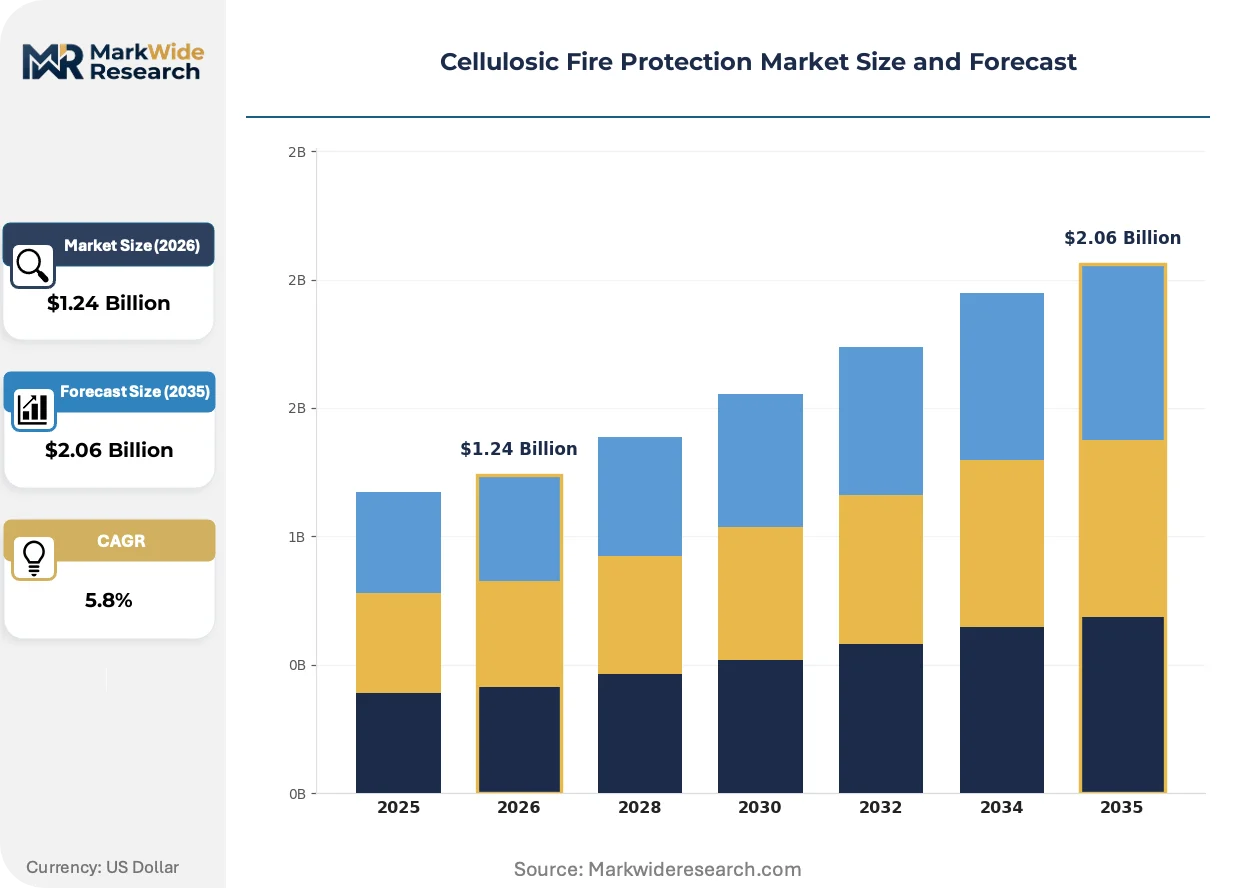
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Coatings, Binders, Sealants Application: Construction, Shipping, Automotive, Aerospace End User: Manufacturers, Contractors, Architects, Engineers Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | The Sherwin-Williams Company, Sika AG, Akzo Nobel N.V., Contego International Inc., Isolatek International, Jotun Group, PPG Industries, Inc., International Cellulose Corporation, Hempel A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulosic Fire Protection Market Strategic Shifts
Formulation chemistry and testing protocols are converging to compress product development cycles while elevating performance verification standards across substrate categories.
Water-borne intumescent coatings are overtaking solvent-based systems in commercial steel protection. German applicator networks are specifying low-VOC platforms for high-rise infrastructure tenders. This transition is compressing solvent-system margin pools while elevating R&D spend for resin compatibility and shelf-life extension.
REACH Annex XVII restrictions on halogenated flame retardants are forcing reformulation of legacy intumescent additive packages. Coating manufacturers are pivoting toward phosphorus-nitrogen synergist systems. The construction segment bears the highest switching costs as existing specifications require requalification under EN 1363-1 protocols.
Specification-grade buyers are consolidating vendor panels to reduce qualification overhead. Tier-one applicators in France and Germany now require dual ISO 9001 and ISO 14001 certification from coating suppliers. This concentration is visible most acutely in transport infrastructure tenders where KBA-influenced standards mandate extended supply chain documentation.
Cellulosic Fire Protection Market Segmentation
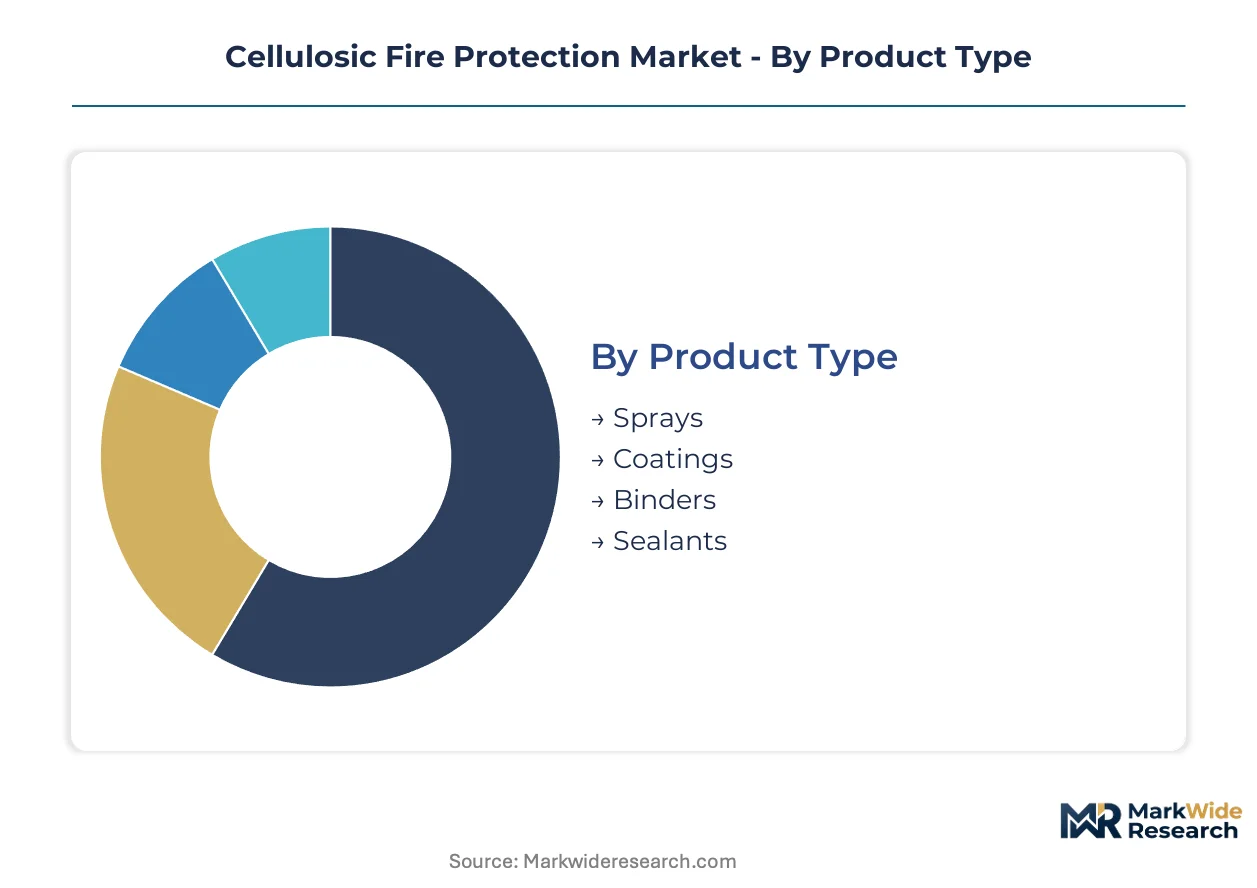
Segmentation in cellulosic fire protection reveals how capital deployment, regulatory compliance burdens, and specification complexity concentrate value capture across distinct product categories and customer interfaces. Understanding these fault lines enables suppliers to align R&D spend and channel investments with segments offering sustainable margin structures.
Product Type:
Sprays and coatings demand substantial upfront capital for intumescent formulation equipment and multi-jurisdiction testing facilities, while sealants require lower fixed investment but higher ongoing certification maintenance.
- Sprays:Cementitious and fiber-spray systems deliver thick-film protection through automated application equipment. German steel-frame infrastructure tenders specify spray systems for high-rise commercial cores where ASTM E119 ratings exceed two-hour resistance thresholds.
- Coatings:Intumescent paint systems expand under thermal exposure to form insulating char layers. Water-borne platforms are displacing solvent-based formulations in French and German commercial construction as REACH Annex XVII restrictions tighten halogenated additive use.
- Binders:Adhesive matrices secure fire-resistant facings to structural substrates. Manufacturers serving cross-laminated timber assemblies specify modified starch and acrylic binders for char-layer adhesion under EN 1363-1 protocols.
- Sealants:Penetration and movement-joint compounds stop fire propagation through service openings. High-occupancy building codes in urban Germany mandate upgraded sealant performance for electrical and mechanical penetrations.
Sprays absorb the bulk of installed capacity; sealants are expanding most quickly as joint-system specifications tighten faster than coating requirements.
Application:
Construction applications dominate volume throughput, yet aerospace and automotive segments command pricing premiums tied to material traceability and extended qualification cycles.
- Construction:Steel-frame commercial buildings, timber assemblies, and composite structures require passive fire protection meeting national building codes. German KBA-influenced standards mandate upgraded protection for transport infrastructure adjacent to commercial development.
- Shipping:Marine vessels specify cellulosic systems for accommodation spaces and engine room boundaries. International Maritime Organization fire safety codes drive specification toward low-smoke, low-toxicity formulations.
- Automotive:Electric vehicle battery enclosures and interior components incorporate intumescent barriers. German automotive manufacturers specify traceable supply chains for flame-retardant materials under transport safety regulations.
- Aerospace:Aircraft cabin linings and cargo compartments demand certified fire-blocking performance. Extended FAA and EASA qualification cycles sustain elevated pricing through material traceability requirements and lot-specific testing documentation.
Construction commands absolute volume; aerospace delivers the steepest margin expansion trajectory through certification-protected pricing.
End User:
Specification authority concentrates with architects and engineers in early project phases, while contractors control application quality and final compliance verification.
- Manufacturers:Coating formulators and substrate producers integrate fire protection into finished building products. German CLT manufacturers specify pre-applied intumescent systems to streamline on-site assembly and code compliance.
- Contractors:Applicator networks execute spray and coating installation with specialized equipment. French and German commercial contractors require ISO 9001 and ISO 14001 certification from coating suppliers to maintain tender eligibility.
- Architects:Design professionals specify fire-resistance ratings in construction documents. High-rise commercial projects in urban Germany increasingly mandate low-VOC intumescent coatings from project inception.
- Engineers:Structural and fire protection engineers calculate load-bearing capacity during fire exposure. Steel-frame designs in Germany require engineer-stamped documentation of intumescent thickness calculations under KBA-influenced protocols.
Contractors absorb the bulk of specification-grade procurement volume; architects are gaining influence fastest as sustainable design criteria reshape early-phase material selection.
Distribution Channel:
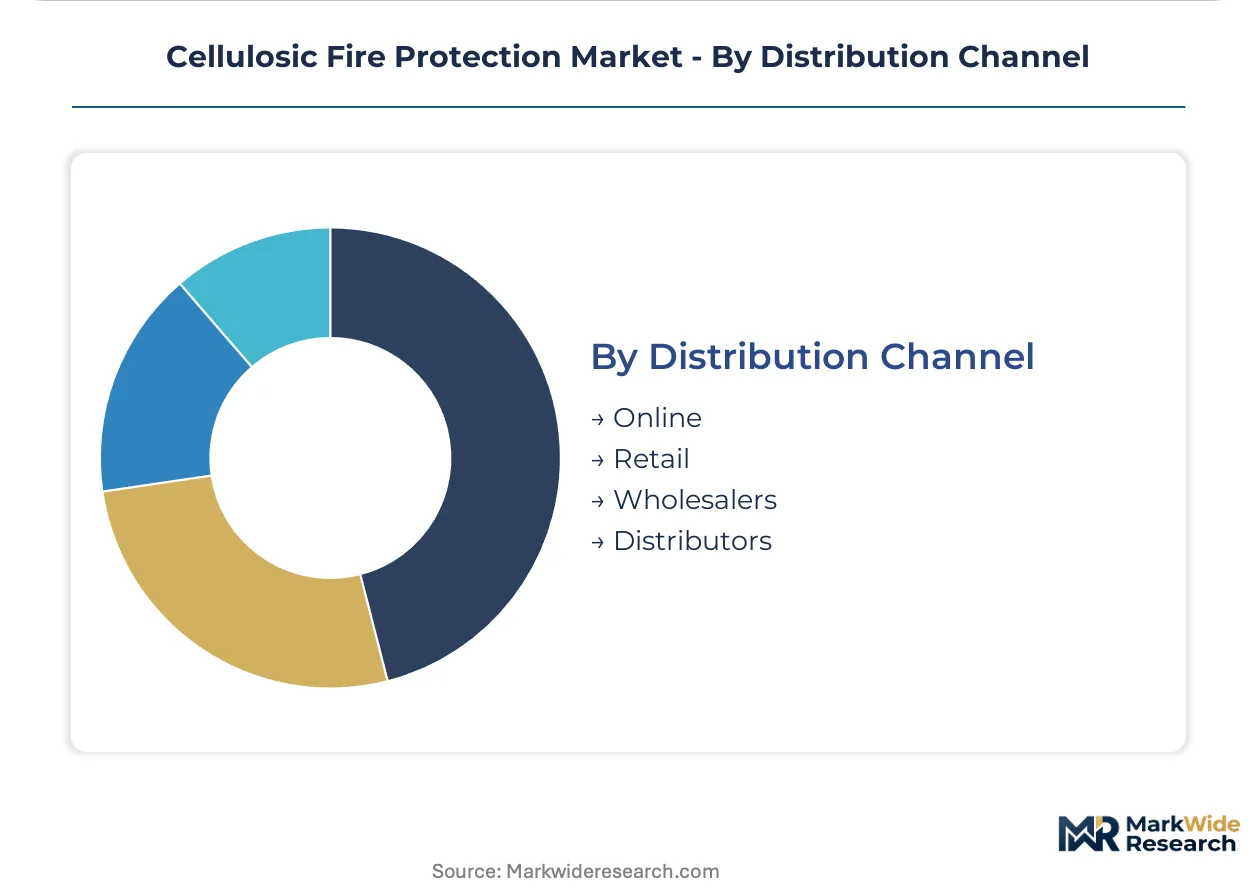
Wholesalers and distributors capture value through technical specification support and inventory consolidation, while online channels remain confined to standardized ancillary products.
- Online:Digital procurement serves small contractors and maintenance operations with catalog-grade sealants and repair kits. Specification-grade coatings require technical consultation unavailable through self-service interfaces.
- Retail:Building supply outlets stock consumer-facing fire-retardant paints and sprays. German hardware chains carry limited intumescent SKUs targeting residential renovation and small commercial maintenance.
- Wholesalers:Regional building material wholesalers aggregate volume across multiple coating categories. French commercial construction wholesalers maintain dedicated fire protection specialists for contractor specification support.
- Distributors:Specialty chemical distributors deliver technical service and just-in-time logistics. German industrial distributors serving steel fabrication shops provide applicator training and thickness verification equipment alongside coating supply.
Distributors command the bulk of specification-grade throughput; online channels are climbing fastest in maintenance and repair segments where product substitution carries lower compliance risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany where steel-frame building codes mandate upgraded passive fire protection, while high-rise commercial construction in France and specification-grade procurement in the United States drive complementary growth vectors across distinct regulatory environments.
Germany
KBA-influenced transport infrastructure standards and commercial high-rise mandates compress specification windows for intumescent coating applicators. The EU Construction Products Regulation's CE marking requirements filter subscale suppliers from infrastructure tenders. Applicator networks in Frankfurt and Munich specify low-VOC water-borne platforms for steel-frame cores exceeding two-hour ASTM E119 ratings.
France
Commercial construction in Paris and Lyon drives specification-grade procurement of intumescent systems for steel-frame buildings. REACH Annex XVII restrictions on halogenated flame retardants force reformulation toward phosphorus-nitrogen synergist packages. French commercial wholesalers maintain dedicated fire protection specialists to support contractor specification compliance.
United States
High-rise commercial development in New York and Chicago expands intumescent coating specification share as steel-frame heights increase. EPA VOC emission limits on architectural coatings elevate compliance costs for solvent-based formulations. ASTM E119 time-temperature curves function as de facto qualification benchmarks, consolidating procurement toward multi-jurisdiction accredited laboratories.
United Kingdom
Cross-laminated timber building codes mandate upgraded char-layer performance for structural composite substrates in London and Birmingham construction. Harmonized EN standards under the EU Construction Products Regulation tighten fire resistance testing protocols. UK-based structural engineers calculate load-bearing capacity during fire exposure under EN 1363-1 protocols.
China
Urban commercial construction in Shanghai and Beijing absorbs substantial passive fire protection volume for steel-frame high-rises. GB standards for building fire safety establish domestic testing benchmarks that diverge from ASTM and ISO protocols. Chinese coating manufacturers face qualification bottlenecks for export markets lacking multi-jurisdiction laboratory accreditation.
Cellulosic Fire Protection Market Competitive Environment
Portfolio diversification dominates the current landscape as coating specialists extend protective chemistries into complementary fire-retardant categories. The vendor base clusters around three strategic archetypes: diversified chemical conglomerates with European manufacturing footprints, applicator-anchored specialists with deep channel relationships, and timber-focused innovators serving cross-laminated substrate protection. M&A activity and geographic expansion through distribution partnerships constitute the primary competitive moves, with certification-protected pricing in aerospace and automotive segments offering margin refuge from construction commoditization pressures.
Among diversified coating conglomerates, Akzo Nobel N.V. and PPG Industries, Inc. exemplify scale-driven positioning through protective coatings portfolio breadth, while Sika AG anchors the applicator-integrated tier through channel depth in commercial construction networks. These three entities collectively represent the concentration trajectory as specification-grade buyers consolidate vendor panels to reduce qualification overhead and dual ISO 9001 and ISO 14001 certification requirements filter subscale competitors from transport infrastructure tenders.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Sika AG |
| Akzo Nobel N.V. |
| Contego International Inc. |
| Isolatek International |
| Jotun Group |
| PPG Industries, Inc. |
| International Cellulose Corporation |
| Hempel A/S |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between specification-compliant and commodity-grade intumescent coatings creates a bifurcated pricing architecture that simultaneously concentrates procurement toward accredited manufacturers and fragments supply chain configurations across distinct raw material sourcing tiers. Premium formulations command substantial markups through multi-jurisdiction testing documentation while commodity alternatives compete on epoxy resin input costs, compressing margin pools for undifferentiated suppliers.
Pricing Analysis
Volume concentrates in construction-grade sprays and coatings where per-project tender pricing dominates, while aerospace and automotive segments sustain margin premiums through extended qualification cycles and material traceability requirements. Three-tier pricing structure across premium certification-protected, standard specification-compliant, and economy cementitious-substitute levels separates buyers by compliance burden tolerance. Cost compression in standard-tier water-borne formulations is intensifying because REACH Annex XVII reformulation expenses and low-VOC resin compatibility R&D are elevating fixed cost absorption. General contractors in cost-sensitive infrastructure tenders exhibit highest price sensitivity; aircraft interior specification authorities demonstrate lowest sensitivity due to lot-specific testing documentation requirements.
Supply Chain Analysis
Direct-to-applicator channels handle specification-grade coating demand through German and French distributor networks that provide technical consultation and thickness verification equipment. Manufacturing concentration clusters in Germany, the Netherlands, and Belgium where multi-jurisdiction ASTM E119 and ISO 834 testing facilities anchor qualification capability. Raw material sourcing draws from petrochemical feedstock suppliers for epoxy resin backbones, phosphorus-nitrogen synergist additive producers, and modified starch suppliers serving timber assembly binders. Single-source vulnerability concentrates around Western European laboratory accreditation for fire-resistance testing, creating qualification bottlenecks that extend product launch schedules. Distribution runs through specialty chemical distributors and regional building material wholesalers with dedicated fire protection specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellulosic fire protection market functions as a vertical-integration race where control over multi-jurisdiction testing accreditation and raw material formulation capabilities determines sustainable margin capture. Players are pursuing backward integration into phosphorus-nitrogen synergist additive production to offset petrochemical feedstock volatility and REACH-driven reformulation costs.
For Market Incumbents: Deepen applicator network certification programs in Germany and France to lock in specification-grade procurement volume before KBA-influenced building codes tighten further. Cementitious spray substitution in cost-sensitive infrastructure tenders threatens coating specification share; counter by securing dual ISO 9001 and ISO 14001 accreditation for transport infrastructure eligibility. Prioritize captive supply of intumescent additive packages to defend margin stability against epoxy resin input cost volatility. For New Entrants and Emerging Players: Enter via aerospace sealant joint-system specifications where penetration and movement-joint firestopping standards are tightening faster than coating requirements, creating white-space before incumbent consolidation accelerates. Timber assembly protection for cross-laminated timber buildings offers penetrable entry with lower capital barriers than steel-frame commercial construction. Pursue partnerships with German CLT manufacturers seeking pre-applied intumescent systems to streamline on-site assembly compliance. For Investors and Strategic Acquirers: Re-rating potential sits with timber-focused innovators possessing EN 1363-1 char-layer performance validation given anticipated carbon-accounting rule revisions that threaten to recategorize traditional cellulosic formulations. Long-term viability over the next decade hinges on bio-based content thresholds and plant-fiber formulation capabilities that align with sustainable construction procurement criteria. Monitor REACH Annex XVII restriction expansion timelines and German KBA building code amendment cycles as inflection indicators for reformulation windows and specification disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Production | Captive phosphorus-nitrogen synergist supply insulates margin stability from petrochemical feedstock volatility under REACH restrictions. |
| Multi-Jurisdiction Testing Accreditation | Simultaneous ASTM E119, ISO 834, and EN 13381 capability compresses competitor product launch schedules by 18-24 months. |
| Applicator Certification Program Expansion | Specialized spray equipment training and thickness verification skills scarcity in emerging markets creates channel lock-in with German contractor networks. |
| Pre-Applied Intumescent System Development | Integration with cross-laminated timber manufacturer workflows streamlines EN 1363-1 compliance for on-site assembly. |
| Low-VOC Water-Borne Platform R&D | Resin compatibility and shelf-life extension investments capture German high-rise commercial tender specifications ahead of solvent-system displacement. |
Study Parameters
Multi-period observation of intumescent coating specification rates, applicator certification density, and building code amendment trajectories anchored the trend analysis, supplemented by interviews with coating formulator R&D directors, commercial contractor procurement leads, structural fire protection engineers, and specialty chemical distribution channel managers. Secondary validation incorporated EU Construction Products Regulation CE marking databases, German KBA transport infrastructure tender documentation, ASTM and ISO fire-resistance testing accreditation records, and REACH Annex XVII regulatory filing archives. Bottom-up segmentation modeling triangulated against top-down construction spending forecasts across steel-frame commercial and timber assembly end-uses.
Input-output matrices mapped intumescent formulation chemistry through raw material cost structures, application labor intensity, and certification maintenance expenditures across the projection horizon. Segmentation dimensions encompassed product type hierarchy, substrate category, end-use industry vertical, specification authority archetype, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves reflecting code-mandated protection upgrades and substitution dynamics between coating and cementitious systems. Industry-specific forecast inputs included cross-laminated timber building permit volumes and electric vehicle battery enclosure flame-barrier adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH restriction expansion or German KBA code acceleration scenarios. Forecasts reflect documented assumptions regarding laboratory accreditation capacity constraints and applicator certification gap persistence. Practitioners should monitor bio-based content threshold proposal timelines and carbon-accounting rule revision drafts for early signals of formulation recategorization risk.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Global Fire Barrier Sealant Market