
 Global Home Security Systems Market | 2026-2036
Global Home Security Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Security Systems Market Foresight
Residential end-user composition is shifting as property managers and real estate agencies displace individual homeowners as the fastest-growing procurement segment. ADT Inc. leverages its nationwide installer network to sustain recurring revenue density in North America. Johnson Controls International anchors commercial-grade fire detection expertise into residential portfolios. Hangzhou Hikvision Digital Technology Co. Ltd. dominates camera hardware supply through manufacturing scale and cost positioning.
Home security systems encompass integrated sensor networks, control panels, and communication interfaces designed to detect intrusion, environmental hazards, and unauthorized access, typically operating on radio frequencies between 300 MHz and 900 MHz for wireless components with battery backup protocols spanning 24 to 72 hours. Their primary commercial purpose centers on risk mitigation, insurance premium reduction, and remote property oversight for distributed real estate portfolios. Surveillance cameras command the largest product-type revenue pool while cloud-based platforms capture the fastest technology growth trajectory due to subscription monetization and over-the-air update capabilities. Smart residences represent the highest-margin application segment as buyers integrate lighting, climate, and access control through unified dashboards.
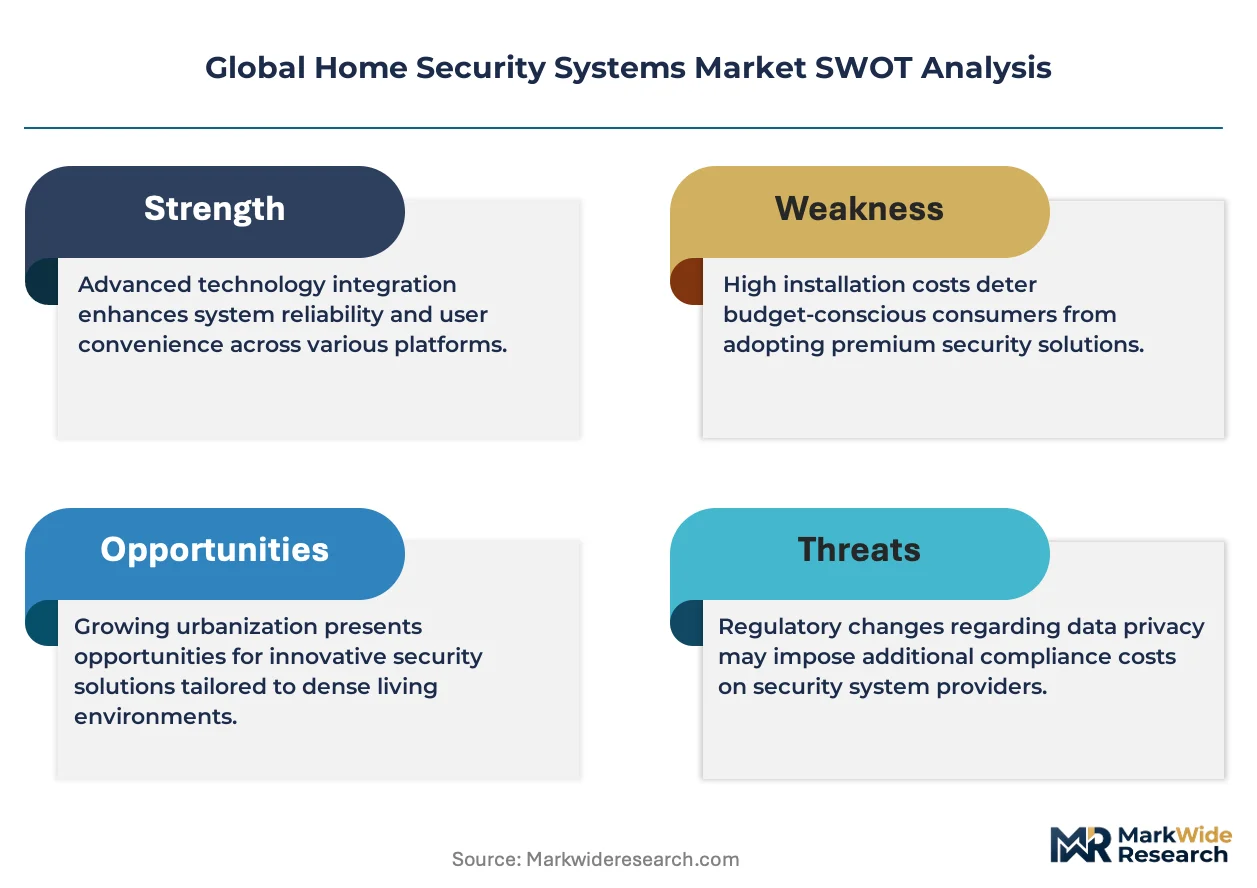
FCC equipment authorization governs radio-frequency emissions for wireless devices sold in the United States, while CE marking mandates electromagnetic compatibility and safety compliance across European Economic Area markets. China's MIIT enforces GB standards for network-connected security hardware, creating divergent certification burdens for multinational suppliers. GDPR and analogous data-protection frameworks in Europe constrain cloud video storage architectures and cross-border data flows. Stakeholders must weigh regulatory fragmentation against platform standardization when allocating R&D budgets and regional go-to-market resources.
Market Dynamics
AI-powered video analytics is compressing response times and displacing human-monitoring contracts across residential and commercial deployments, while cloud-native architectures enable over-the-air firmware updates that extend hardware replacement cycles.
Growth Catalysts
- GDPR-compliant cloud storage mandates:European data-protection frameworks accelerate demand for EU-sovereign data centers and localized processing nodes.
- Multi-family property management platforms:Real estate investment trusts and institutional landlords consolidate vendor relationships through integrated access-control and surveillance dashboards.
- Edge computing on camera SoCs:On-device inference chips reduce bandwidth costs and enable real-time anomaly detection without continuous cloud uplink.
Market Restraints
- Semiconductor supply concentration:Advanced image sensors and AI accelerators depend on TSMC and Samsung foundry capacity concentrated in Taiwan and South Korea.
- GB standard certification timelines:China's MIIT network-security testing adds six to nine months to product launch schedules for imported hardware.
- DIY installation substitution:Self-monitored wireless kits from consumer electronics retailers displace professional installation contracts in single-family segments.
Strategic Opportunities
- India's smart city infrastructure:Municipal surveillance tenders and residential tower mandates create procurement pipelines for integrated security-as-a-service models.
- IRA energy-efficiency credits:US tax incentives for building electrification extend to smart thermostats and sensor networks bundled with security packages.
- Matter protocol convergence:Unified connectivity standards between access control, lighting, and climate systems reduce integration friction for unified residential dashboards.
Industry Challenges
- FCC equipment authorization bottlenecks:Radio-frequency certification queues for new wireless protocols delay product launches by four to six months.
- Cybersecurity talent scarcity:Firmware security auditing and penetration testing functions face recruitment gaps that slow secure-by-design implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Security Systems Market |
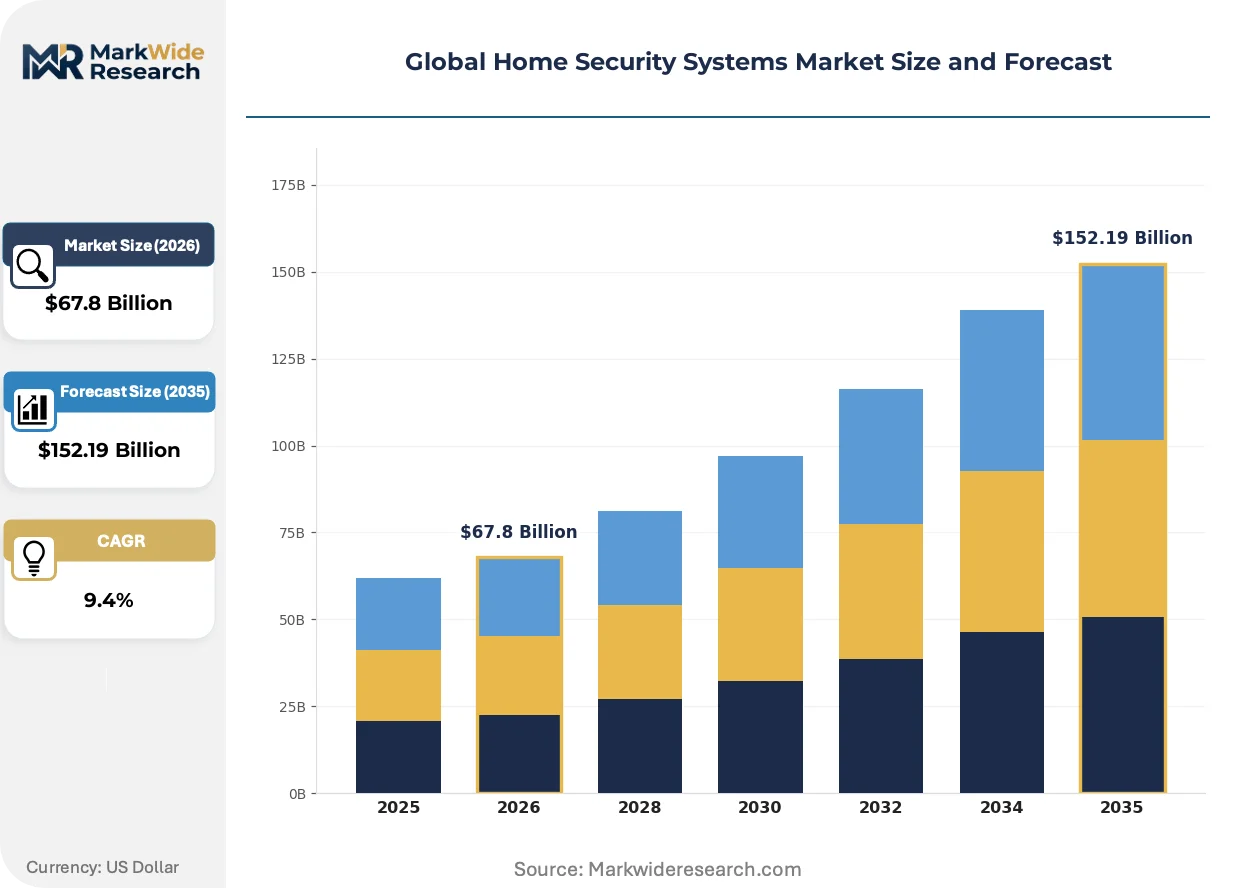
| Market Size in 2026 | $67.8 Billion |
| Market Size in 2035 | $152.19 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrusion Alarms, Surveillance Cameras, Access Control Systems, Fire Detection, Environmental Sensors Technology: Wireless, Wired, Hybrid, Cloud-Based, AI-Powered Application: Single-Family Homes, Multi-Family Dwellings, Vacation Properties, Rental Units, Smart Residences End User: Homeowners, Property Managers, Real Estate Agencies, Security Providers, Facility Operators |
| Companies Covered | ADT Inc., Johnson Controls International, Honeywell International Inc., Resideo Technologies Inc., Hangzhou Hikvision Digital Technology Co. Ltd., ASSA ABLOY AB, Robert Bosch GmbH, SimpliSafe Inc., Vivint Smart Home Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Security Systems Market Shifts & Advancements
Computational photography and on-device machine learning are redefining hardware specifications and service monetization models across the installed base.
On-camera AI accelerators are electrifying the competitive landscape by enabling facial recognition, package detection, and behavioral analysis without continuous cloud dependency. Property managers in Germany and the United States deploy these systems to reduce false-alarm dispatch fees and insurance deductibles. The shift compresses recurring revenue from central monitoring stations while expanding software subscription attach rates.
GDPR's data-localization requirements and the EU AI Act's risk-classification framework constrain biometric analytics deployment across European residential markets. Hardware suppliers must maintain separate firmware branches for EU and non-EU deployments, fragmenting engineering resources. Cloud providers respond by establishing Paris and Frankfurt data centers with ISO 27001 certification to retain financial services and government-adjacent contracts.
Subscription bundling is consolidating buyer relationships as property managers prefer single-vendor contracts covering hardware, installation, monitoring, and maintenance. Professional installer networks in the United States and China displace direct-to-consumer channels for multi-unit dwellings. This concentration favors vendors with captive service capabilities over pure-play equipment manufacturers.
Global Home Security Systems Market Segmentation
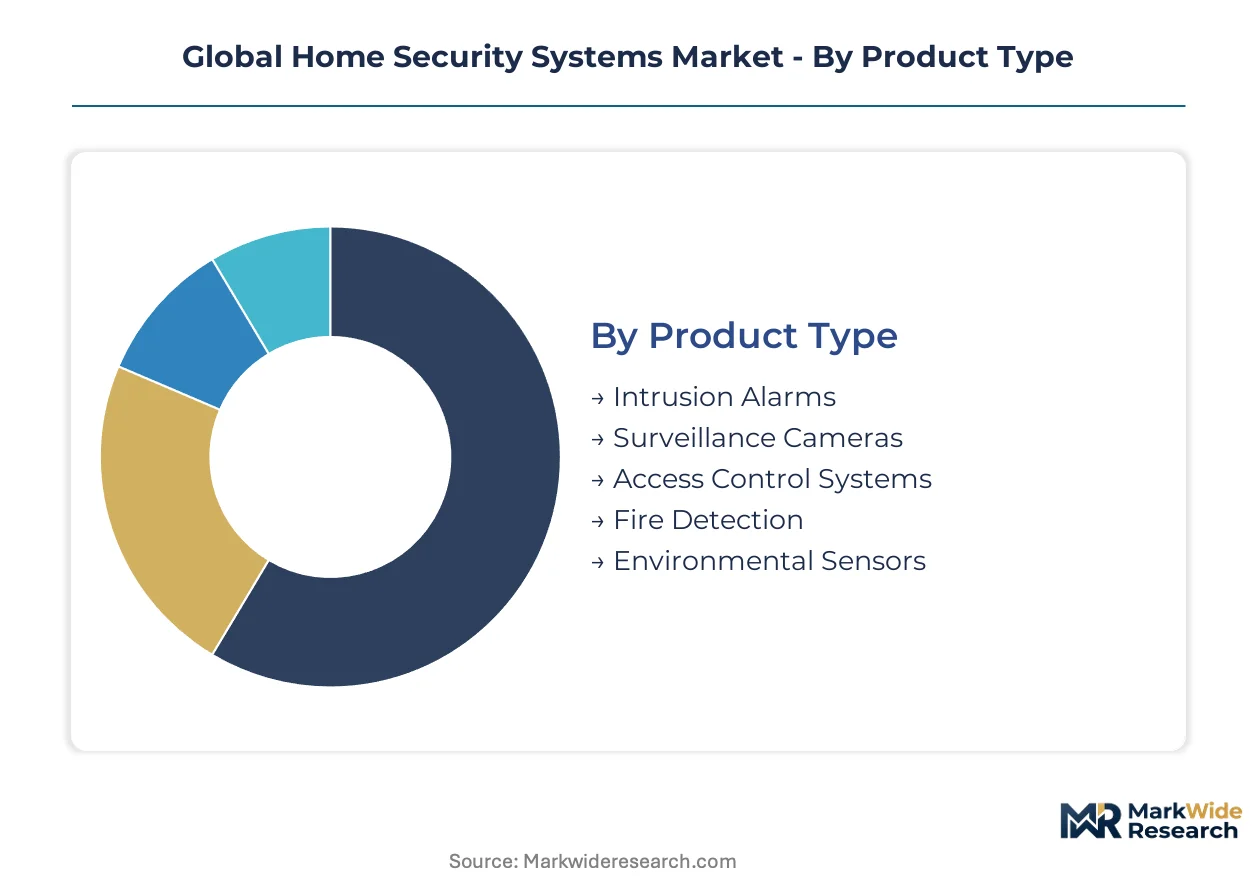
Home security procurement varies sharply across buyer types and installation contexts. Property managers prioritize centralized dashboards while individual homeowners weigh upfront cost against monthly fees. Understanding these divergent selection criteria illuminates where vendors must adapt hardware specifications and service bundling.
Product Type:
Buyer budgets and risk profiles determine hardware composition, with insurance requirements and false-alarm penalties shaping category prioritization.
- Surveillance Cameras:Image sensors with 1080p to 4K resolution and night-vision infrared arrays dominate hardware spending. Multi-family property managers in Germany and the United States deploy these systems to reduce guard staffing and liability exposure.
- Intrusion Alarms:Door and window sensors, motion detectors, and glass-break microphones form the foundational detection layer. Single-family homeowners in suburban markets favor these systems for lower equipment costs and simpler installation.
- Access Control Systems:Keycard readers, biometric scanners, and mobile credential platforms secure entry points.
- Fire Detection:Smoke, heat, and carbon monoxide sensors integrate with building management systems.
- Environmental Sensors:Water leak, temperature, and humidity monitors protect against property damage.
Surveillance cameras lead on scale; environmental sensors lead on momentum.
Technology:
Installation labor availability and retrofit constraints drive technology selection more than feature differentiation alone.
- Cloud-Based:Remote access platforms with subscription billing and over-the-air firmware updates redefine vendor economics. Real estate investment trusts across China consolidate portfolios onto these systems for centralized oversight of dispersed assets.
- AI-Powered:On-device inference chips enable facial recognition, package detection, and behavioral analysis without continuous uplink. GDPR and the EU AI Act constrain biometric deployment in France and Germany, forcing separate firmware branches.
- Wireless:Radio-frequency mesh networks operating between 300 MHz and 900 MHz simplify retrofit installation.
- Wired:Ethernet and power-over-ethernet configurations serve new construction with integrated cabling.
- Hybrid:Combinations of wireless sensors and wired backbone infrastructure balance reliability with flexibility.
Cloud-based systems capture the steepest expansion trajectory; wired installations retain share in new construction pipelines.
Application:
Property ownership structure and tenant turnover frequency determine monitoring service requirements and hardware durability specifications.
- Smart Residences:Unified dashboards integrating lighting, climate, access control, and security command premium pricing. High-net-worth homeowners in California and Florida drive demand for Matter-compatible ecosystems with voice activation.
- Multi-Family Dwellings:Apartment towers and condominium complexes require lobby access control, elevator restrictions, and shared-area surveillance. Institutional landlords in Texas and Florida negotiate enterprise contracts covering hundreds of units.
- Single-Family Homes:Detached residences with dedicated alarm panels and perimeter sensors.
- Vacation Properties:Seasonal residences with remote monitoring and environmental alerts.
- Rental Units:Transient-occupancy installations with portable hardware and minimal infrastructure.
Smart residences command the highest margins; multi-family dwellings deliver the fastest volume expansion.
End User:
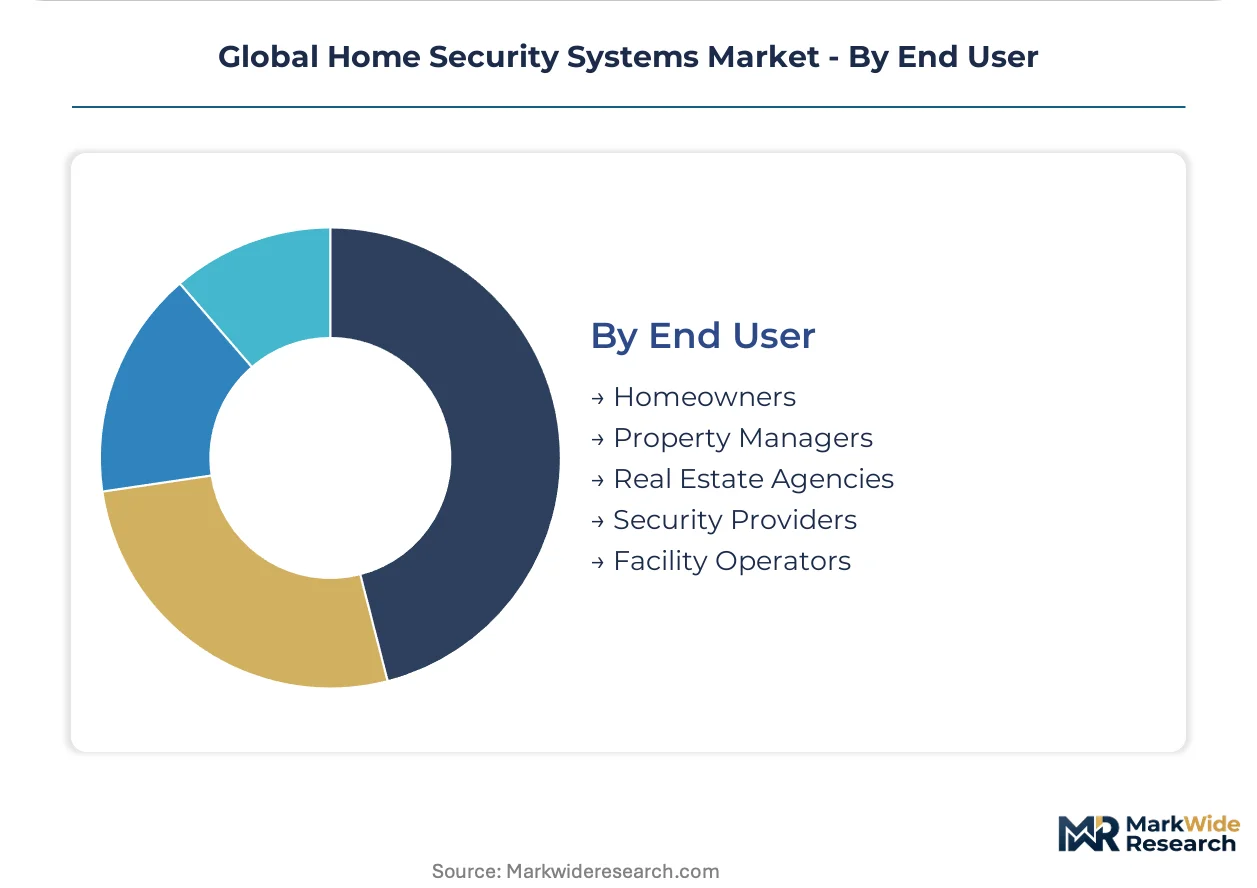
Procurement authority is shifting from individual consumers to institutional buyers with consolidated purchasing power and technical staff.
- Property Managers:Real estate investment trusts and institutional landlords negotiate multi-year service contracts covering installation, monitoring, and maintenance. These buyers in Illinois and Georgia displace fragmented homeowner purchases through vendor consolidation.
- Real Estate Agencies:Brokerage networks and property staging services install temporary or transferable systems for showing security and transaction protection. Pre-listing camera deployments in Arizona and Nevada accelerate closing timelines.
- Homeowners:Individual consumers purchasing through retail channels or direct-to-consumer brands.
- Security Providers:Monitoring stations and installation contractors serving as intermediaries.
- Facility Operators:Commercial property managers extending security coverage to residential-adjacent spaces.
Property managers lead on contract value concentration; real estate agencies lead on customer acquisition velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as suppliers migrate production to jurisdictions with streamlined certification pathways. The divergence between FCC, CE marking, and MIIT compliance timelines creates cost-of-compliance gaps that influence regional investment flows.
United States
Multi-family property managers in Texas and Florida are consolidating vendor relationships through enterprise contracts covering hundreds of units. FCC equipment authorization governs radio-frequency emissions for wireless devices, with certification queues delaying product launches by four to six months. The installer networks concentrated in Illinois and Georgia sustain recurring revenue density for integrated monitoring platforms.
Germany
GDPR-compliant cloud storage mandates accelerate demand for EU-sovereign data centers and localized processing nodes. The EU AI Act's risk-classification framework constrains biometric analytics deployment, forcing hardware suppliers to maintain separate firmware branches. Industrial clusters around Munich and Stuttgart anchor manufacturing capacity for surveillance cameras with on-device inference chips.
China
MIIT enforces GB standards for network-connected security hardware, adding six to nine months to product launch schedules for imported equipment. Real estate investment trusts consolidate portfolios onto cloud-native platforms for centralized oversight of dispersed assets. Manufacturing scale concentrates in Hangzhou and Shenzhen, driving cost positioning for camera hardware supply.
India
Municipal surveillance tenders and residential tower mandates in Maharashtra and Karnataka create procurement pipelines for integrated security-as-a-service models. The country's national electronics regulator enforces compulsory registration for wireless equipment, extending time-to-market for foreign suppliers. Smart city infrastructure investments in Delhi-NCR and Telangana accelerate demand for unified access-control dashboards.
Japan
METI standards for network-connected devices shape product specifications for residential security deployments. Aging demographics in Tokyo and Osaka drive demand for remote monitoring solutions that reduce institutional care costs. The Kanto region's electronics manufacturing base supplies advanced image sensors for AI-powered video analytics systems.
Global Home Security Systems Market Competitive Landscape
Subscription bundling dominates the current landscape as vendors consolidate buyer relationships through single-vendor contracts covering hardware, installation, monitoring, and maintenance. The market structure tilts toward tiered concentration, with national installer networks and captive manufacturing scale occupying distinct competitive positions. Three archetypes define the field: integrated service providers with recurring revenue platforms, hardware specialists leveraging manufacturing scale, and cloud-native entrants monetizing software subscriptions. Geographic expansion and technology licensing represent the dominant competitive moves as players seek to bridge regional certification gaps.
Within the integrated service tier, ADT Inc. and Vivint Smart Home Inc. exemplify the North American model of recurring revenue density through captive installer networks. Johnson Controls International occupies a position that bridges commercial-grade fire detection expertise with residential portfolio expansion. Hangzhou Hikvision Digital Technology Co. Ltd. anchors the manufacturing-scale archetype, with its corporate domicile signaling cost-positioning advantages in camera hardware supply. These three entities collectively represent the divergence between service-centric and hardware-centric competitive strategies.
| Leading Market Players |
|---|
| ADT Inc. |
| Johnson Controls International |
| Honeywell International Inc. |
| Resideo Technologies Inc. |
| Hangzhou Hikvision Digital Technology Co. Ltd. |
| ASSA ABLOY AB |
| Robert Bosch GmbH |
| SimpliSafe Inc. |
| Vivint Smart Home Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FCC-authorized and MIIT-certified hardware tiers shapes both margin structures and manufacturing footprints across the home security systems value chain. Premium-tier suppliers absorb six-to-nine-month GB standard testing timelines into landed costs, while commodity wireless sensor producers bypass regulatory complexity through unlicensed frequency bands.
Pricing Analysis
Installer network margins and direct-to-consumer channel discounts structure the dominant pricing architecture across hardware and subscription bundles. Three-tier pricing stratifies across enterprise property-management contracts, professional residential installations, and DIY retail kits, with FCC and CE certification tiers commanding 15-25 point premiums over uncertified alternatives. Cost compression in wireless sensor modules intensifies as TSMC capacity constraints ease, squeezing component suppliers while platform vendors expand software attach rates. Multi-family property managers exhibit lowest price sensitivity due to insurance deductible and liability reduction calculus; suburban single-family homeowners drive retail kit commoditization through Amazon and big-box substitution.
Supply Chain Analysis
Refurbishment flows for edge-computing camera SoCs and battery-backup control panels create secondary revenue streams for certified remanufacturers in Shenzhen and Dallas-Fort Worth. Manufacturing gravity centers on Hangzhou, Shenzhen, and Dongguan for image sensors and AI accelerators, with final assembly drawing from Mexico and Vietnam to mitigate Section 301 tariff exposure. Advanced CMOS sensors and on-device inference chips rest on TSMC and Samsung foundry capacity concentrated in Taiwan and South Korea, creating single-source vulnerability for facial-recognition hardware. Distribution runs through ADT and Vivint captive installer networks in North America, Alibaba and JD.com marketplace channels in China, and European security integrators with CE marking authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in home security systems rests on cloud-native platform economics displacing hardware-centric revenue pools, with on-device AI inference reducing bandwidth costs and extending replacement cycles.
For Market Incumbents: Extend recurring revenue density through Matter protocol integration and captive installer network consolidation in Texas and Florida multi-family markets. Defend against SimpliSafe and Ring direct-to-consumer substitution by embedding environmental sensors and access control into unified property-management dashboards, leveraging Johnson Controls' fire detection certification as a cross-sell wedge. For New Entrants and Emerging Players: Edge-AI camera platforms with GDPR-compliant on-device processing offer the most penetrable technology-first wedge for European residential deployments fragmented by data-localization mandates. Target German and French smart-city infrastructure tenders with security-as-a-service models, bypassing incumbent hardware lock-in through subscription-only pricing and ISO 27001-certified Frankfurt data centers. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-native software stacks lack captive manufacturing scale or regional certification expertise. Long-term viability favors vendors with integrated hardware-software-service economics and MIIT or FCC authorization pipelines. Monitor GB standard certification queue lengths and EU AI Act biometric risk-classification enforcement as inflection signals for hardware supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Unifies access control, surveillance, and environmental monitoring through single-vendor contracts for REITs. |
| On-Device AI Acceleration | Reduces bandwidth costs and enables real-time anomaly detection without continuous cloud dependency. |
| Regional Certification Investment | Accelerates time-to-market in China through MIIT pre-approval partnerships and localized testing labs. |
| Installer Network Expansion | Captures multi-family enterprise contracts in Texas and Florida through captive service capabilities. |
| Matter Protocol Adoption | Reduces integration friction between lighting, climate, and security systems in smart residence deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with property management executives, security systems integrators, cloud platform engineers, and FCC certification consultants with secondary validation. Regulatory filings with the FCC Equipment Authorization Database, MIIT GB standard announcements, and EU AI Act implementation guidance anchored compliance timeline assumptions. SEC 10-K disclosures from ADT, Resideo, and Johnson Controls provided recurring revenue and R&D allocation benchmarks. Bottom-up unit economics for camera hardware and cloud storage tiers triangulated against top-down market size estimates.
Comparable-period anchoring linked projection assumptions to historical adoption curves for wireless sensor networks and cloud-monitoring transitions across the analysis window. Segmentation dimensions modeled include product type, technology architecture, application context, and end-user procurement authority, with regional regulatory clusters treated as distinct market boundaries. CAGRs derived from logistic diffusion curves for smart home penetration and multi-family institutional investment cycles, incorporating semiconductor supply constraints and certification queue lengths as supply-side modifiers.
The model holds under stable regulatory enforcement and continued cloud infrastructure investment; deviation in MIIT certification timelines or EU AI Act biometric prohibitions would shift hardware supplier market shares. Practitioners should monitor TSMC and Samsung foundry utilization rates and GDPR data-localization audit enforcement for early signals of supply constraint or compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
Border Security System Market
Access Control Systems
Automated Barriers and Bollards Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Car Security System Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Vehicle Security System Market