
 Europe Baggage and Parcel Screening Market | 2026-2036
Europe Baggage and Parcel Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Baggage and Parcel Screening Market Insights
REACH is expanding the cost-of-entry calculus for baggage and parcel screening equipment across Europe, forcing manufacturers to reformulate detector materials and supply chain chemistry. Smiths Detection Group leverages its integrated R&D pipeline to navigate these compliance thresholds. Rapiscan Systems anchors its European position through manufacturing scale and channel control in aviation security installations. Gilardoni SpA specializes in compact X-ray architectures that occupy niche deployments at regional railway terminals.
Baggage and parcel screening encompasses automated inspection systems that detect contraband, explosives, and hazardous materials in luggage and courier shipments using ionizing radiation, computed tomography, or trace chemical analysis, with throughput rates typically exceeding 1,800 items per hour at major transport nodes. The primary purpose is to prevent threats from entering critical infrastructure while maintaining passenger and cargo flow efficiency. CT technology leads the technology segment due to its three-dimensional imaging capability and automated detection algorithms that reduce operator dependency. Aviation security dominates the application segment as EASA mandates drive replacement cycles across European hub airports. The service type segment shows fastest expansion in maintenance contracts, where margin pools deepen as equipment complexity rises and uptime guarantees tighten.
EMA, EASA, and the EU AI Act collectively shape product standards, software validation requirements, and market access protocols for screening systems deployed across European member states. EASA certification timelines directly determine which manufacturers can bid on airport security tenders, while the EU AI Act imposes algorithmic transparency obligations on automated threat-detection software. Stakeholders must monitor how forthcoming CE marking revisions under the Machinery Regulation affect CT scanner radiation enclosure standards and software update protocols.
Market Dynamics
EASA's accelerated certification timelines for computed tomography scanners are compressing replacement cycles across European hub airports, forcing incumbent vendors to recalibrate R&D pipelines and service architectures around faster throughput validation.
Growth Catalysts
- EU Green Deal procurement mandates:Carbon footprint thresholds in public tenders now favor energy-efficient CT architectures, redirecting capital toward low-dose screening systems at major transport nodes.
- Germany:Frankfurt and Munich airports are executing synchronized modernization programs, creating concentrated demand spikes for automated threat-detection platforms.
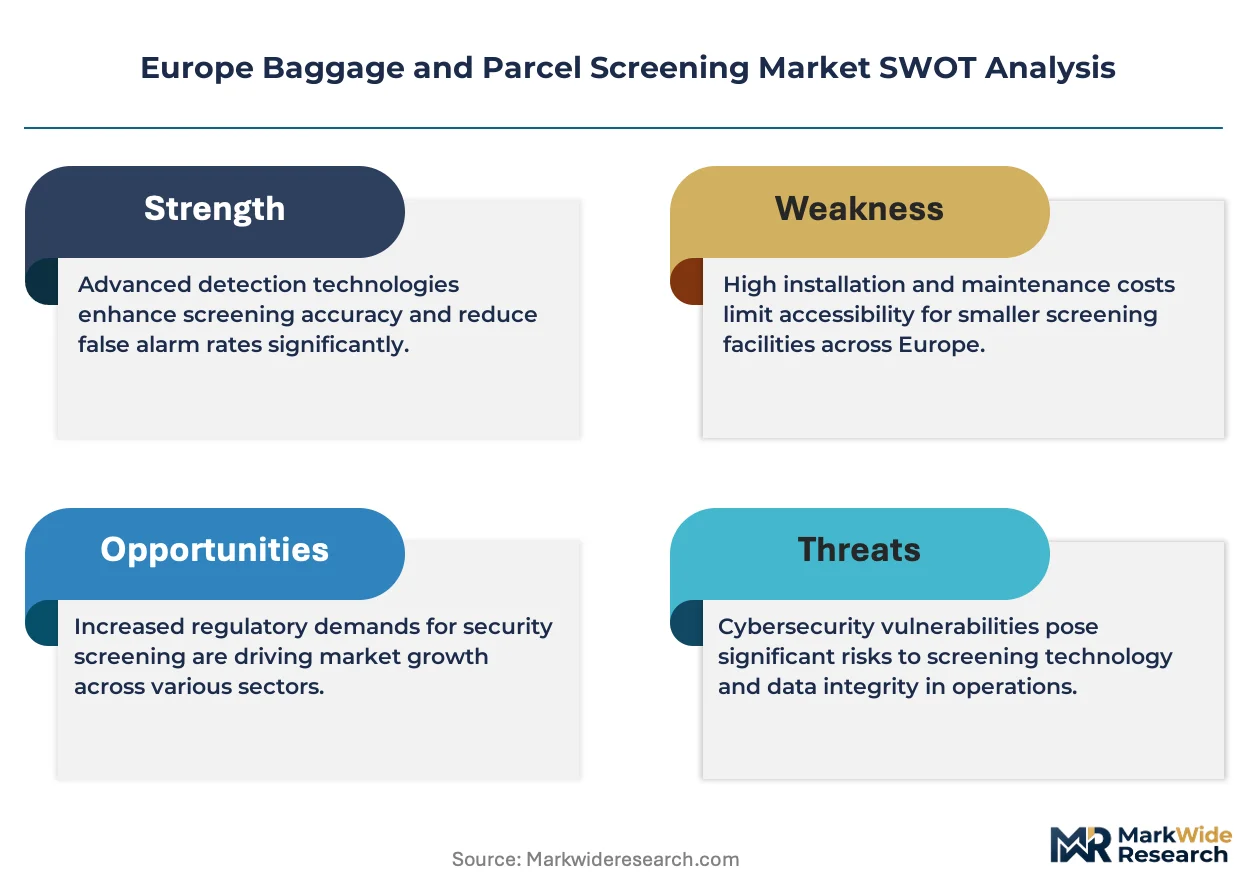
- Deep learning algorithms:Neural network-based image classification is reducing false alarm rates below legacy dual-energy thresholds, accelerating operator acceptance and deployment velocity.
Market Restraints
- Detector material cost volatility:Cadmium zinc telluride crystal supply concentrates with three Asian refiners, exposing European OEMs to input price swings and qualification delays.
- REACH compliance friction:ECHA's expanding restricted substance list forces reformulation of scintillator coatings and radiation shielding compounds, extending product development cycles.
- Technical limitation:Current CT systems struggle with dense agricultural products in air cargo, creating inspection blind spots that manual secondary screening cannot fully resolve.
Strategic Opportunities
- Poland and Romania:Underpenetrated regional airport networks lack automated screening infrastructure, presenting first-mover advantages for vendors with localized service partnerships.
- Railway terminal integration:High-speed cross-border corridors require parcel screening at intermodal hubs, an application segment currently served by outdated X-ray architectures.
- EU AI Act algorithmic transparency rules:Early compliance with explainable AI mandates for threat-detection software creates differentiation against non-compliant imports from outside the bloc.
Industry Challenges
- Certification timeline compression:EASA's reduced type-approval windows strain engineering teams attempting simultaneous hardware and software validation.
- Integration complexity with legacy analog systems:Retrofitting digital CT platforms into 1990s-era baggage handling infrastructure demands custom mechanical interfaces that erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Baggage and Parcel Screening Market |
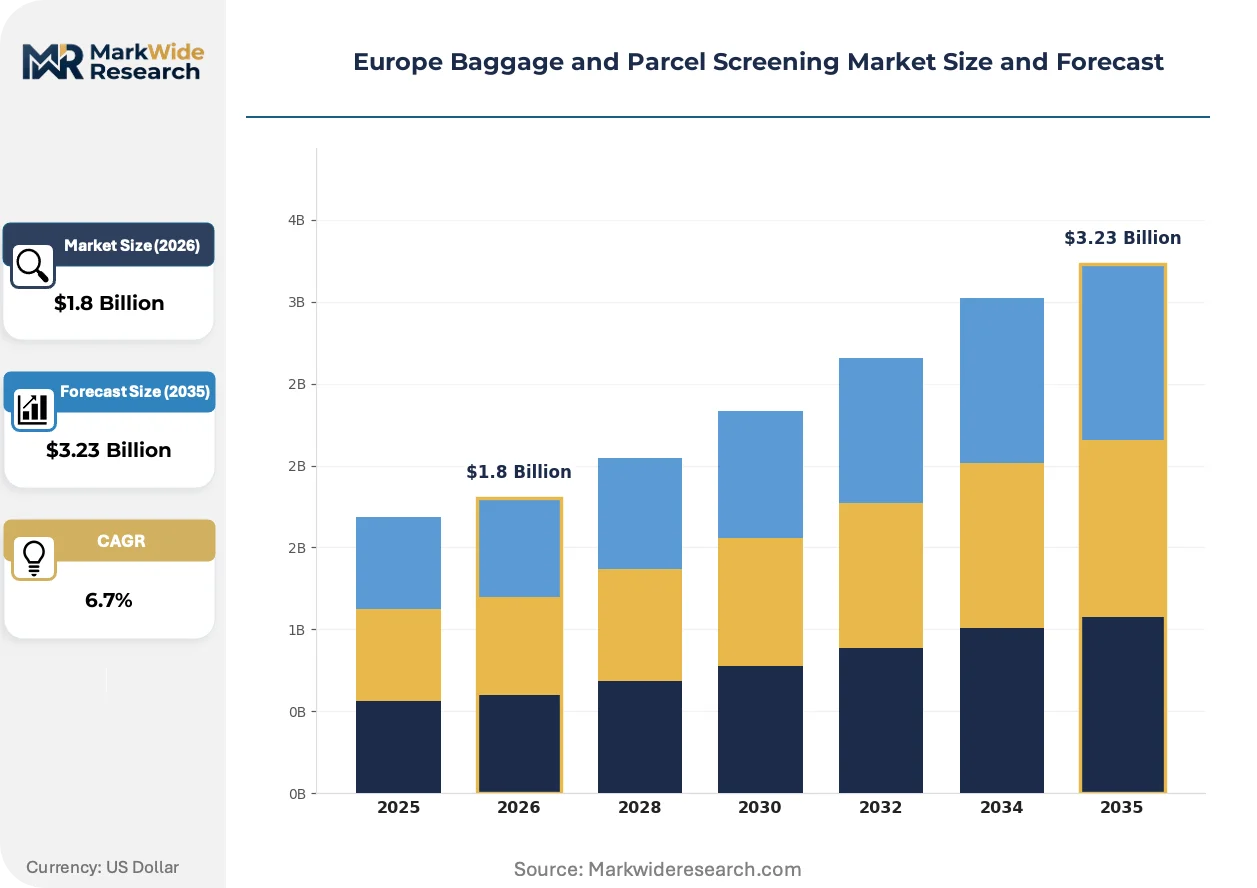
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-Ray, CT, Metal Detectors, Explosive Detection Systems Application: Aviation Security, Public Transport, Government Facilities, Event Security End User: Airports, Railway Stations, Customs Authorities, Event Organizers Service Type: Installation, Maintenance, Consulting, Training |
| Companies Covered | Smiths Detection Group, Rapiscan Systems, Nuctech Company Limited, Leidos, Teledyne ICM, Gilardoni SpA, 3DX-Ray, Analogic Corporation, LINEV Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Baggage and Parcel Screening Market Trends and Innovations
Computational imaging and regulatory algorithmic governance are converging to redefine performance benchmarks and procurement criteria across European aviation security infrastructure.
Computed tomography with automated threat recognition is automating the detection of liquid explosives and improvised devices without human image interpretation. Tier-one European hub airports in the United Kingdom and France are adopting these platforms under compressed EASA-mandated replacement schedules. This automation is compressing staffing requirements at security checkpoints while raising capital intensity per lane.
REACH substance restrictions are forcing detector manufacturers to eliminate cadmium-based compounds from scintillator formulations and radiation shielding assemblies. Industrial consequence includes extended qualification periods for new material stacks and supply chain requalification costs passed through to airport operators. Germany's KBA and France's ASN are coordinating enforcement timelines, creating synchronized compliance windows that favor integrated R&D operations over modular suppliers.
Airport operators are unbundling maintenance contracts from initial equipment procurement, treating uptime guarantees as separate competitive variables. Traditional bundled sales models at major European hubs face displacement by performance-based service agreements with penalty clauses for throughput degradation. This shift is most visible in the Netherlands and Belgium, where Schiphol and Brussels Airport have piloted availability-linked payment structures with primary screening vendors.
Europe Baggage and Parcel Screening Market Segmentation
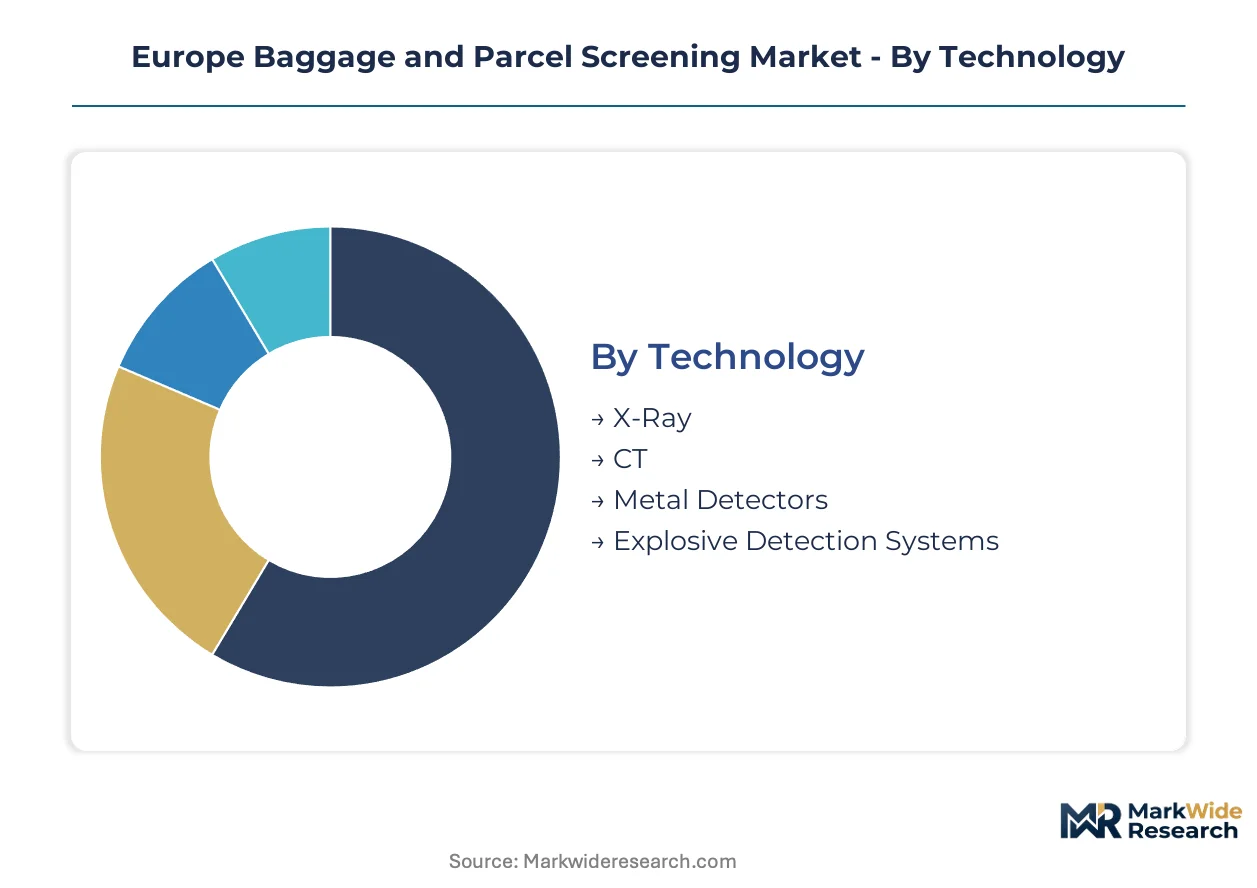
Segmentation in the Europe baggage and parcel screening market reveals how capital allocation, regulatory mandates, and operational requirements concentrate demand across distinct technology platforms and service categories. Understanding these divisions exposes where procurement budgets flow and which infrastructure owners drive replacement cycles.
Technology:
Capital intensity varies sharply across detection platforms, with CT systems demanding multiples of X-ray unit investment while delivering automated threat-recognition capabilities that reduce long-term staffing costs.
- CT:Computed tomography generates three-dimensional volumetric images with automated explosive-detection algorithms. Frankfurt Airport and Paris-Charles de Gaulle are deploying these systems under compressed EASA replacement timelines to eliminate liquid restrictions and reduce manual bag checks.
- X-Ray:Dual-energy transmission systems remain the workhorse for checked baggage and parcel flows at regional airports. Germany's KBA enforces radiation enclosure standards that extend qualification periods for new X-ray platform certifications.
- Metal Detectors:Walk-through and handheld units provide primary screening at lower-throughput checkpoints.
- Explosive Detection Systems:Trace chemical analyzers using ion mobility spectrometry or mass spectrometry detect residue on surfaces and in vapor samples.
CT absorbs the bulk of installed capacity at tier-one European hubs; explosive detection systems are expanding most quickly at customs checkpoints and event perimeters.
Application:
Operational tempo and threat profile determine equipment specification, with aviation checkpoints requiring continuous high-throughput performance while event security demands rapid deployment flexibility.
- Aviation Security:Checkpoint and hold baggage screening must sustain throughput above 1,800 items per hour with false alarm rates below specified thresholds. EASA mandates are forcing synchronized replacement waves across United Kingdom and French hub airports.
- Public Transport:Railway terminals and metro systems require compact architectures that integrate with constrained platform geometries. High-speed corridors through Belgium and the Netherlands are driving demand for parcel screening at intermodal transfer points.
- Government Facilities:Courthouses and administrative buildings prioritize visitor screening with minimal footprint.
- Event Security:Temporary deployments for sports and cultural gatherings favor mobile screening units with rapid setup protocols.
Aviation security commands the dominant share of equipment procurement value; public transport is climbing the fastest as railway modernization programs accelerate.
End User:
Procurement authority and budget scale diverge significantly between centralized national operators and fragmented local authorities, shaping vendor sales strategies and service model design.
- Airports:Hub operators bundle multi-lane screening procurements with decade-long maintenance agreements. Munich and Frankfurt airports are executing synchronized modernization programs that concentrate demand spikes.
- Customs Authorities:Border inspection posts require cargo-scale systems with agricultural product discrimination capabilities. Poland and Romania are expanding automated screening infrastructure at underpenetrated regional entry points.
- Railway Stations:Station operators face integration complexity with legacy baggage handling infrastructure.
- Event Organizers:Rental-based procurement models dominate this fragmented customer base.
Airports absorb the bulk of installed capacity; customs authorities are gaining share fastest as external border controls tighten.
Service Type:
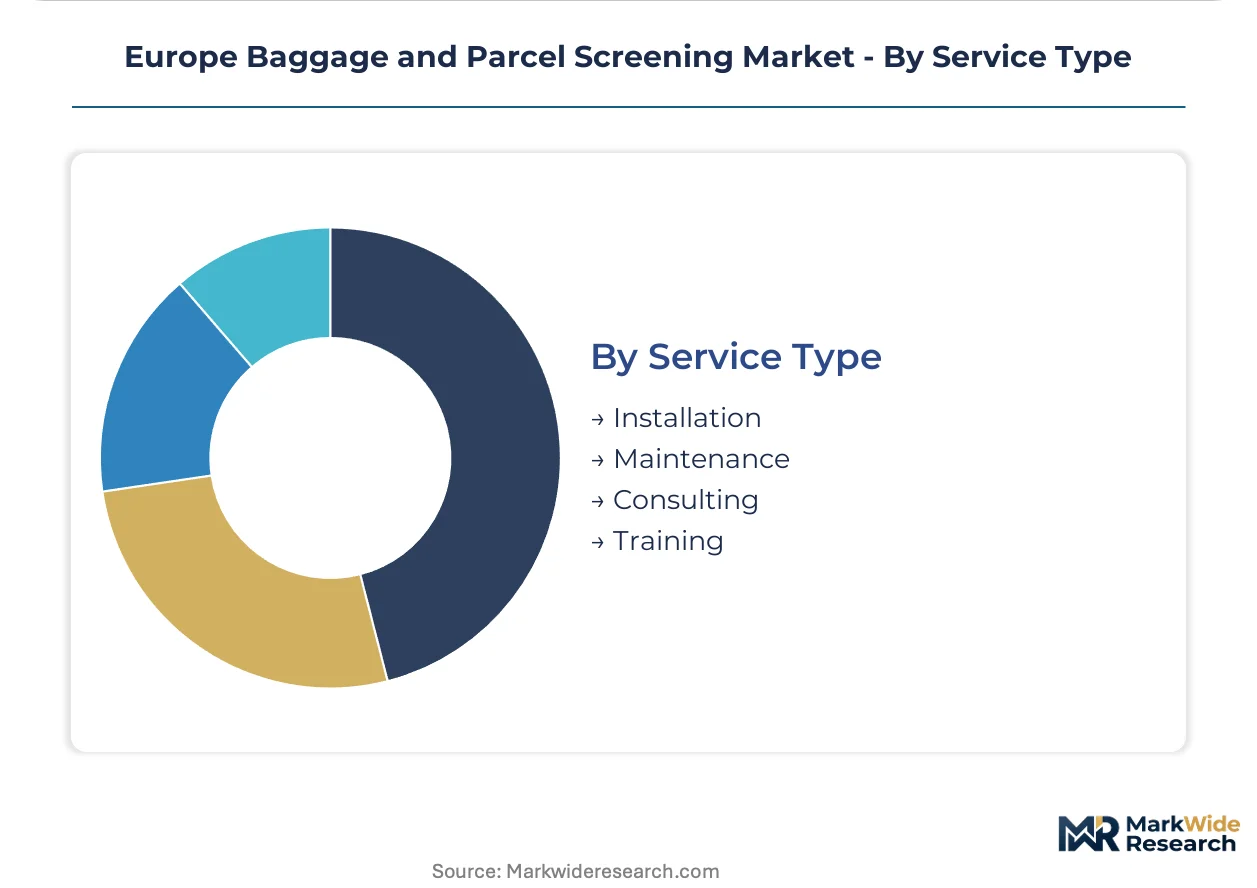
Margin structure shifts dramatically from one-time installation revenue toward recurring maintenance streams as equipment complexity rises and uptime guarantees become contractual obligations.
- Maintenance:Performance-based contracts with penalty clauses for throughput degradation are displacing traditional bundled sales. Schiphol and Brussels Airport have piloted availability-linked payment structures that deepen vendor margin pools.
- Installation:Mechanical integration with 1990s-era baggage handling systems demands custom engineering that erodes project margins at European hub retrofits.
- Consulting:Threat assessment and system design services support greenfield airport expansions.
- Training:Operator certification programs address EASA-mandated competency requirements for automated threat-recognition systems.
Maintenance captures the bulk of service revenue; consulting is expanding most quickly as greenfield airport projects proliferate in Eastern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, France, and the United Kingdom as these nations modernize critical transport nodes. EASA mandates and EU Green Deal procurement criteria redirect capital toward energy-efficient screening architectures. The regional market spans mature hub airports and underpenetrated eastern networks.
Germany
Frankfurt and Munich airports execute synchronized modernization programs, creating concentrated demand spikes for automated threat-detection platforms. KBA enforces radiation enclosure standards that extend qualification periods for new X-ray certifications. Bavaria's industrial corridor hosts integrated R&D operations that navigate REACH compliance thresholds.
France
Paris-Charles de Gaulle deploys CT systems under compressed EASA replacement timelines to eliminate liquid restrictions. ASN coordinates enforcement windows with Germany's KBA, creating synchronized compliance periods. The Île-de-France aviation cluster drives procurement for high-throughput screening lanes.
United Kingdom
Heathrow and Gatwick accelerate adoption of automated threat-recognition platforms under post-Brexit security regime updates. The UK Civil Aviation Authority aligns certification protocols with EASA timelines to maintain equipment interoperability. London's hub airports pilot availability-linked payment structures with primary screening vendors.
Netherlands
Schiphol Airport advances performance-based service agreements that unbundle maintenance from initial procurement. The Dutch Human Environment and Transport Inspectoration enforces stringent uptime guarantees in security tenders. The Randstad logistics corridor drives parcel screening demand at intermodal transfer points.
Poland
Regional airport networks lack automated screening infrastructure, presenting first-mover advantages for vendors with localized service partnerships. Polish customs authorities expand automated infrastructure at underpenetrated eastern border entry points. Warsaw's emerging aviation hub attracts greenfield screening deployments.
Europe Baggage and Parcel Screening Market Competitive Landscape
UK and German producers anchor one tier; Italian specialists hold compact architecture niches. The vendor base organizes around three strata: integrated multinationals with full R&D pipelines, regional fabricators with manufacturing scale, and compact-system specialists serving constrained deployments. Two dominant competitive moves are reshaping positioning: backward integration into detector material supply chains, and performance-based service contracts that displace traditional bundled sales.
Within the integrated multinational tier, Smiths Detection Group and Rapiscan Systems exemplify divergent geographic anchoring strategies. Gilardoni SpA occupies a specialist position serving constrained-platform deployments. Nuctech Company Limited represents the scale-driven archetype with manufacturing breadth. Leidos and Teledyne ICM sit within the diversified technology conglomerate segment, leveraging cross-sector imaging competencies. These five anchors illustrate how procurement concentration at tier-one hubs favors integrated R&D operations, while regional railway terminals sustain niche specialists.
| Leading Market Players |
|---|
| Smiths Detection Group |
| Rapiscan Systems |
| Nuctech Company Limited |
| Leidos |
| Teledyne ICM |
| Gilardoni SpA |
| 3DX-Ray |
| Analogic Corporation |
| LINEV Systems |
| Others |
Pricing and Supply Chain Analysis
Family-owned Italian specialists anchor the mid-tier detector supply base, compressing pricing discipline through generational capital patience while European hub operators exploit this fragmentation to extract service concessions on CT platform procurement. This ownership structure feeds into supply chain rigidity, as these producers resist capacity expansion that would dilute founder equity, propping equipment pricing at tier-one airports.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent EASA-mandated replacements from planned fleet renewals, with Frankfurt and Munich airports paying premiums for accelerated CT scanner delivery while regional Polish facilities capture discounts on spot X-ray inventory. The dominant structure is project-based equipment procurement bundled with decade-long maintenance agreements, though Schiphol and Brussels Airport are piloting unbundled availability-linked contracts. Price differentiation hinges on EASA certification tier and after-sales service bundling, with fully certified CT platforms commanding substantial premiums over provisional approvals. Pricing pressure stems from cadmium zinc telluride crystal cost volatility, which compresses margins on detector assemblies. Customs authorities in Eastern Europe exhibit the highest price sensitivity due to budget constraints, while German hub operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
EASA certification timelines and REACH substance qualifications gate entry for detector materials and radiation shielding compounds, extending supplier onboarding to 18-24 months for new scintillator formulations. Manufacturing concentrates in Germany, the United Kingdom, and Italy for integrated system assembly, while cadmium zinc telluride crystal feedstock draws from three Asian refiners concentrated in China and Japan. Critical inputs include rare-earth scintillator substrates, precision-machined tungsten collimators, and lead-free radiation shielding polymers. Single-source vulnerability pervades the detector crystal tier, where European OEMs lack captive supply alternatives. Distribution runs through direct vendor-airport procurement channels at tier-one hubs, with regional railway terminals served by specialized distributors holding localized service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in certified detector materials prop pricing discipline, as EASA-mandated replacement waves at European hub airports outstrip qualified manufacturing capacity.
For Market Incumbents: Hedge against REACH compliance friction by accelerating in-house production of lead-free scintillator formulations before Germany's KBA and France's ASN synchronize enforcement windows. Lock in long-term offtake agreements with the three Asian cadmium zinc telluride refiners to neutralize input price volatility, while expanding performance-based service contracts to capture maintenance margin pools that deepen as equipment complexity rises. For New Entrants and Emerging Players: System integrators with legacy baggage handling expertise represent the most viable channel partnership for penetrating Poland and Romania's underpenetrated regional airport networks. Target customs checkpoint deployments at Poland's eastern border entry points, where automated screening infrastructure gaps coincide with EU external border tightening. Pursue white-label CT platform assembly for established vendors struggling with EASA certification timeline compression. For Investors and Strategic Acquirers: Distressed-cycle entries favor compact-system specialists with REACH-compliant detector architectures in Italy's industrial corridor, where family ownership transitions create acquisition windows. Long-term viability centers on vendors with integrated R&D pipelines capable of navigating EASA and EU AI Act algorithmic transparency mandates. Watch for EASA certification backlog clearance as the inflection signal indicating capacity normalization and pricing pressure resumption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Materials | Captive scintillator production insulates Smiths Detection and Rapiscan Systems from Asian refiner price volatility. |
| Performance-Based Service Contract Expansion | Availability-linked payment structures at Schiphol and Brussels Airport deepen vendor margin pools beyond equipment sales. |
| EU AI Act Algorithmic Compliance Investment | Explainable AI development for automated threat-detection software creates differentiation against non-compliant imports. |
| Regional Service Partnership Localization | Polish and Romanian airport networks demand on-site maintenance capabilities that foreign vendors lack. |
| Railway Terminal Integration Development | High-speed cross-border corridors through Belgium and the Netherlands require compact screening architectures for intermodal hubs. |
Research Methodology
Trade association filings, EASA certification registries, and EU customs import records formed the secondary backbone, cross-referenced against primary interviews with airport security directors, EASA compliance officers, CT platform engineering leads, and aftermarket service heads at major European hubs. Bottom-up triangulation validated equipment deployment counts at tier-one airports against top-down market sizing from procurement budget disclosures.
Bottom-up volume modeling segmented the market by technology platform, application vertical, and end-user procurement authority, while top-down validation anchored on national aviation security budget allocations across Germany, France, and the United Kingdom. CAGRs derived from replacement cycle analysis under EASA-mandated timelines, incorporating EU Green Deal energy-efficiency procurement criteria and REACH substance restriction phase-in schedules. Forecast inputs included EASA type-approval pipeline data and detector material supply qualification timelines.
Caveats apply where EASA certification timeline compression or REACH substance list expansion could materially shift the outlook for CT platform deployment velocity. Forecasts embed assumptions around EASA-EU AI Act regulatory coordination and cadmium zinc telluride supply stability. A model refresh is warranted upon material change in EASA type-approval throughput or Asian refiner supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Airport Security Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Radar Security Market
Security and Surveillance
Global Security As a Service Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Middle East Manned Security Services Market