
 Canada Surveillance Camera Market | 2026-2036
Canada Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Surveillance Camera Market Insights
Modular hardware-software bundles is decoupling across the Canada Surveillance Camera Market, forcing buyers to evaluate video management platforms separately from camera hardware. Axis Communications AB sustains channel control through open-architecture partnerships with Canadian systems integrators. Avigilon Corporation anchors its position in high-resolution analytics for critical infrastructure. Bosch Sicherheitssysteme GmbH differentiates through in-house production of image sensors and edge-computing chipsets.
Canada surveillance cameras encompass fixed and pan-tilt-zoom imaging devices capturing visible-light or thermal spectra, typically employing CMOS sensors with resolutions from two to twelve megapixels and H.265 compression for bandwidth efficiency, serving security monitoring, traffic management, and operational intelligence functions. IP cameras now lead product-type revenue due to Power-over-Ethernet deployment flexibility in retrofits across aging commercial buildings. Cloud-based technology segments capture fastest expansion as Canadian enterprises shift capital expenditure to subscription models for multi-site visibility. Wired installations still dominate margin pools in banking and government verticals where latency tolerance approaches zero.
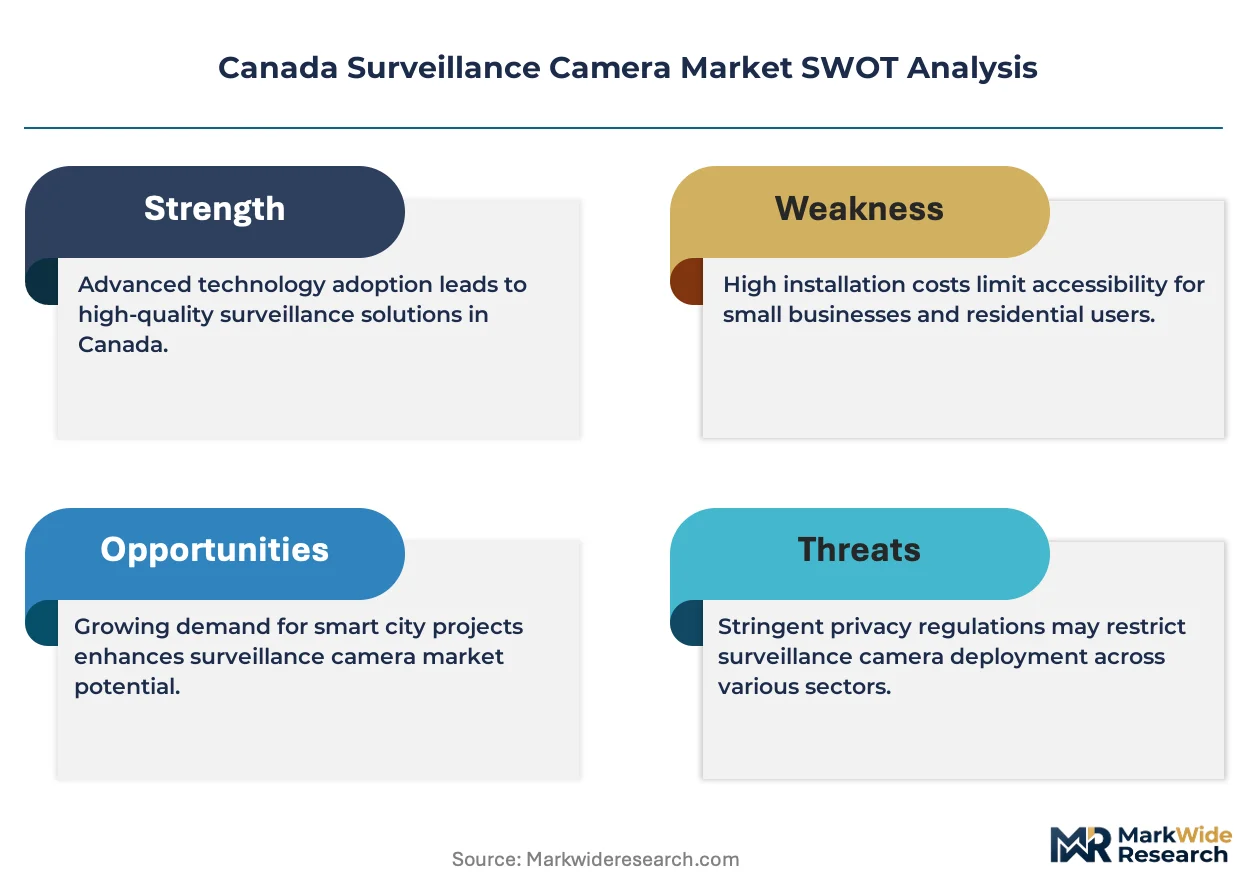
Health Canada and the Office of the Privacy Commissioner of Canada enforce PIPEDA compliance and data-breach notification protocols that compel vendors to certify encryption standards and local data residency. Provincial regulators in Ontario and Quebec layer additional freedom-of-information and municipal procurement rules that extend sales cycles but favor established suppliers with compliance documentation. Stakeholders must monitor forthcoming federal artificial-intelligence legislation affecting automated facial-recognition deployments in public spaces.
Market Dynamics
The Canada Surveillance Camera Market is restructuring around modular procurement architectures that separate video management software from camera hardware, forcing legacy bundled suppliers to defend integration margins while pure-play analytics vendors capture value upstream.
Growth Catalysts
- PIPEDA Compliance Mandates:Health Canada's encryption and data-residency requirements under federal privacy law are accelerating replacement cycles for non-compliant legacy installations across Ontario municipal corridors.
- Power-over-Ethernet Retrofit Economics:IP camera deployment flexibility is unlocking upgrade demand in aging commercial building stock across Toronto and Vancouver where rewiring costs previously blocked modernization.
- Port Security Modernization:Vancouver's container terminal operators are deploying thermal-analytics arrays for perimeter intrusion detection under Transport Canada maritime security directives.
Market Restraints
- CMOS Sensor Supply Concentration:Image sensor fabrication capacity concentrates among East Asian foundries, exposing Canadian integrators to lead-time volatility and currency-hedging costs.
- Provincial Procurement Fragmentation:Ontario and Quebec maintain divergent municipal tendering rules under separate freedom-of-information statutes, extending sales cycles for national vendors.
- Edge Computing Thermal Constraints:On-camera processing chipsets face performance degradation in sub-zero prairie deployments, limiting analytics reliability outside coastal British Columbia and southern Ontario.
Strategic Opportunities
- Atlantic Canada Underpenetration:Halifax and St. John's smart-city initiatives lag Ontario and British Columbia by three to five years in video-analytics deployment, creating first-mover whitespace for systems integrators.
- Healthcare Facility Convergence:Hospital networks in Alberta and Manitoba are piloting unified physical-cyber security platforms that merge surveillance with access control and patient-flow analytics.
- Federal AI Legislation Tailwind:Forthcoming parliamentary restrictions on automated facial recognition in public spaces will advantage vendors with explainable-analytics certifications and audit-trail capabilities.
Industry Challenges
- Video Forensics Talent Scarcity:Law enforcement agencies and corporate security departments face acute shortages of analysts trained in evidentiary chain-of-custody protocols for cloud-archived footage.
- Multi-Site Integration Complexity:Enterprises with hybrid on-premise and cloud deployments struggle to maintain consistent latency and failover redundancy across prairie, coastal, and northern remote facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Surveillance Camera Market |
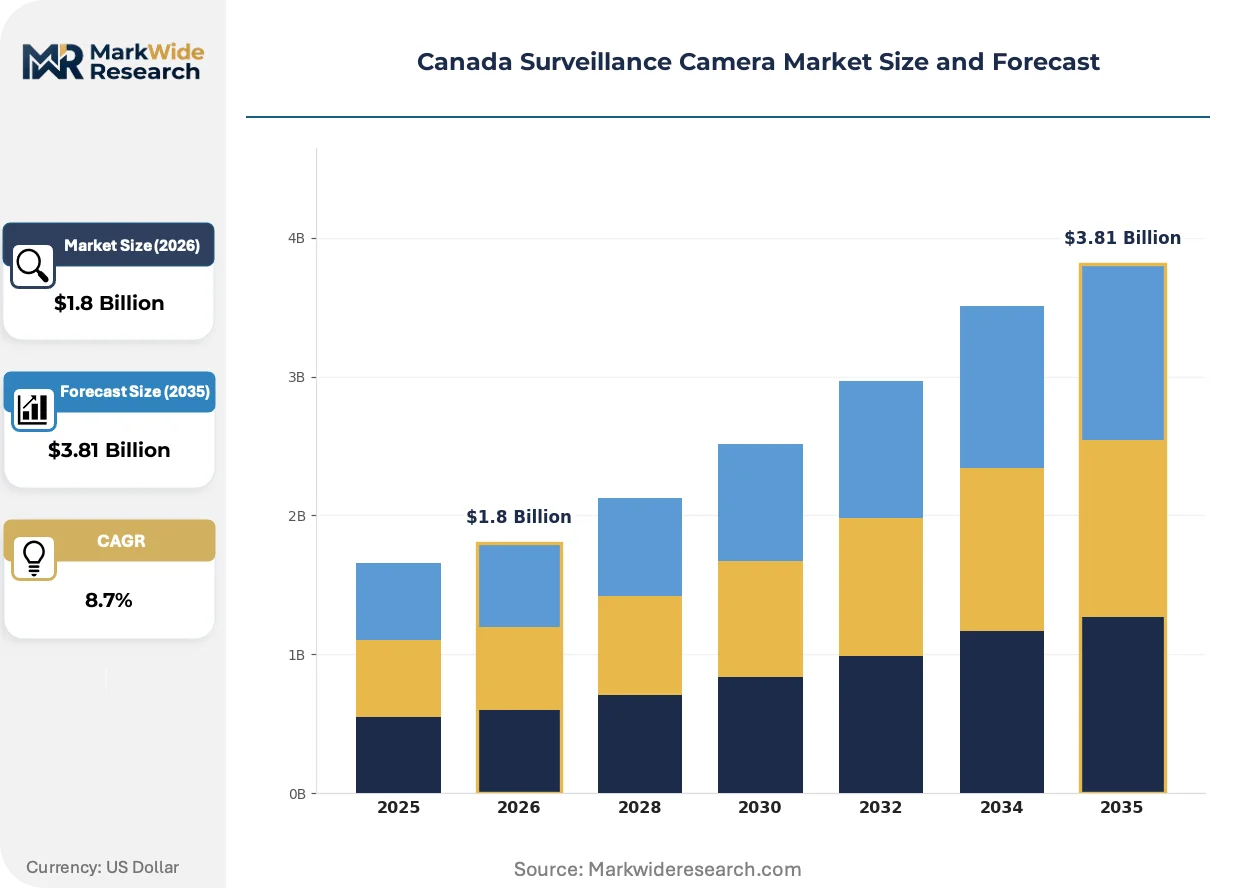
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Cameras, IP Cameras, PTZ Cameras, Thermal Cameras Technology: Wired, Wireless, Cloud-Based, Hybrid End User: Retail, Transportation, Banking, Government Installation Type: Indoor, Outdoor, Covert, Mounted |
| Companies Covered | Axis Communications AB, Hangzhou Hikvision Digital Technology Co., Ltd., Hanwha Vision, Dahua Technology, Bosch Sicherheitssysteme GmbH, Avigilon Corporation, Honeywell Security, Vivotek Inc., March Networks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Surveillance Camera Market Trends and Innovations
Canadian surveillance infrastructure is pivoting from passive recording to predictive analytics, with procurement criteria increasingly weighted toward software-defined architectures and subscription-based service models that shift capital expenditure to operational budgets.
Edge-based artificial intelligence inference is converging with thermal imaging sensors to enable real-time threat classification without cloud latency. Critical infrastructure operators in Alberta's oil sands and British Columbia's hydroelectric facilities are deploying these fused systems for perimeter monitoring. This convergence is compressing the market for centralized video analytics servers while elevating demand for ruggedized on-camera processing chipsets rated for extreme temperature ranges.
The Office of the Privacy Commissioner of Canada is enforcing stricter breach-notification timelines under PIPEDA amendments, compelling vendors to certify end-to-end encryption and local data residency. This regulatory pressure is disqualifying offshore cloud providers from government and healthcare tenders. Banking and telecommunications verticals are responding by mandating Canadian-hosted video management platforms with sovereign data controls.
Buyers are unbundling hardware procurement from software licensing, negotiating video management platforms through separate RFP processes. Large retail and logistics chains are displacing traditional integrator-led bundles with direct relationships to cloud-native analytics providers. This pattern is most pronounced in Toronto's commercial real estate sector, where property management firms now benchmark camera hardware on interoperability scores rather than bundled software features.
Canada Surveillance Camera Market Segmentation
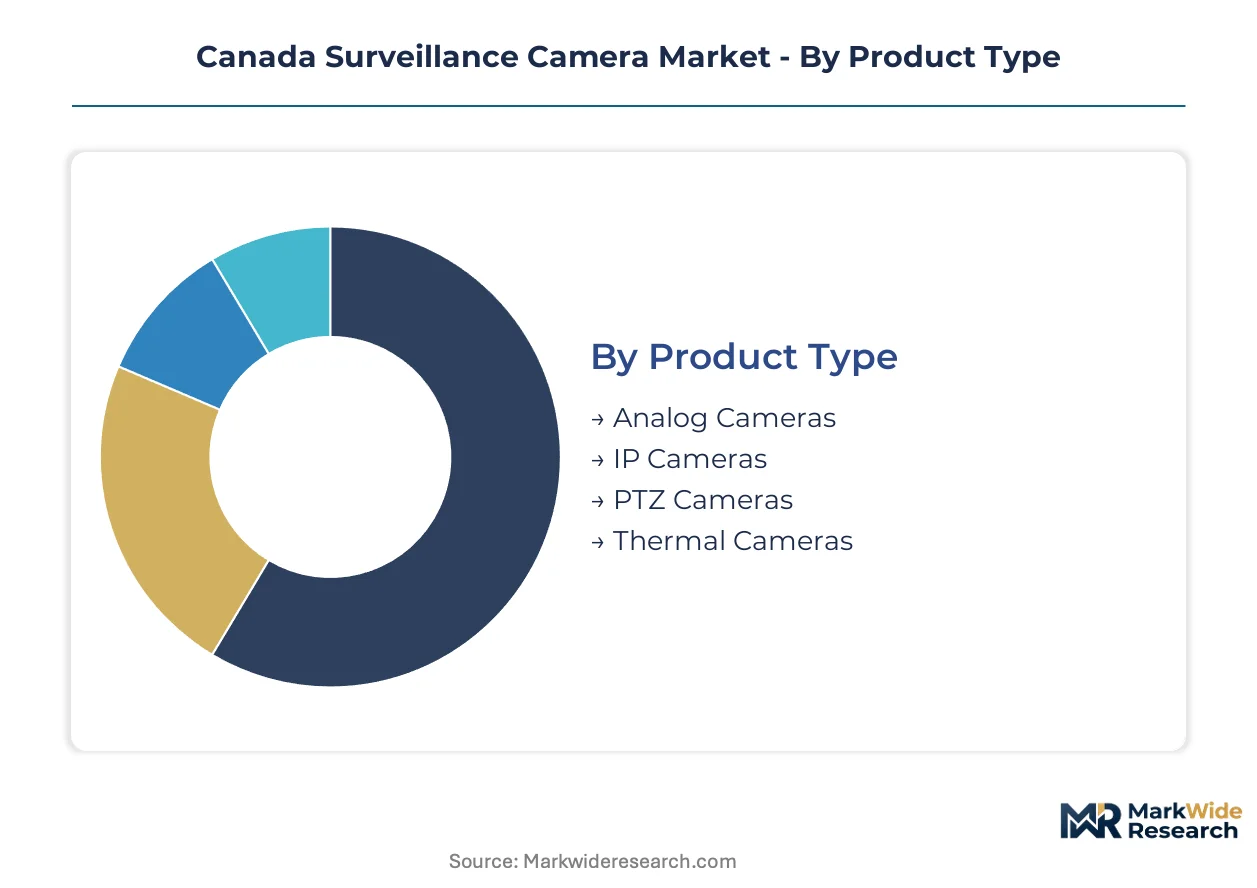
Segmentation in the Canada Surveillance Camera Market reveals how procurement architectures are unbundling across hardware, connectivity, and service layers. Buyers now evaluate each dimension separately, reshaping vendor relationships and margin pools.
Product Type:
Integration depth varies sharply: IP and thermal cameras embed analytics at the edge, while analog and PTZ units often feed centralized processing architectures.
- IP Cameras:CMOS sensors with Power-over-Ethernet connectivity deliver two to twelve megapixel resolution with H.265 compression. Demand clusters in Toronto's aging commercial building retrofits where rewiring costs previously blocked upgrades.
- Thermal Cameras:Uncooled microbolometer arrays detect infrared signatures for perimeter intrusion detection without visible-light illumination. Vancouver's port security zones under Transport Canada directives are deploying these for maritime perimeter monitoring.
- Analog Cameras:Coaxial-cable legacy infrastructure persists in budget-constrained municipal installations across Atlantic Canada.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms enable operator-directed tracking in Ontario casino and stadium deployments.
Volume placements concentrate in IP Cameras; the faster expansion belongs to Thermal Cameras.
Technology:
Cost tier stratification separates capital-intensive wired installations from subscription-driven cloud models.
- Cloud-Based:Video-management platforms hosted in Canadian data centers shift capital expenditure to operational budgets. Banking and telecommunications verticals in Toronto mandate sovereign data controls under PIPEDA amendments.
- Wired:Fiber and Ethernet installations deliver sub-ten-millisecond latency for government and banking verticals where failover tolerance approaches zero. Federal procurement in Ottawa favors these for classified facility monitoring.
- Wireless:Wi-Fi and cellular backhaul serve temporary construction sites and remote northern resource operations across Alberta and Saskatchewan.
- Hybrid:Edge recording with cloud burst capacity addresses prairie enterprises with intermittent connectivity.
Revenue margins peak in Wired deployments; Hybrid architectures are climbing the fastest as multi-site enterprises reconcile latency with flexibility.
End User:
Application criticality drives specification divergence: transportation and government demand ruggedized hardware, while retail prioritizes software-defined analytics.
- Government:Municipal, provincial, and federal procurement spans smart city corridors, correctional facilities, and border infrastructure. Ontario and British Columbia video analytics programs are expanding under freedom-of-information statutes that favor encrypted storage certification.
- Transportation:Airports, rail terminals, and maritime ports require thermal-analytics arrays for perimeter detection. Vancouver container terminals are modernizing under Transport Canada security directives.
- Banking:Branch networks and data centers mandate zero-latency wired installations with sovereign cloud controls.
- Retail:Loss prevention and customer-flow analytics drive demand for interoperable video management platforms separable from camera hardware.
Contract values peak in Government; Retail is gaining share fastest as property management firms unbundle procurement.
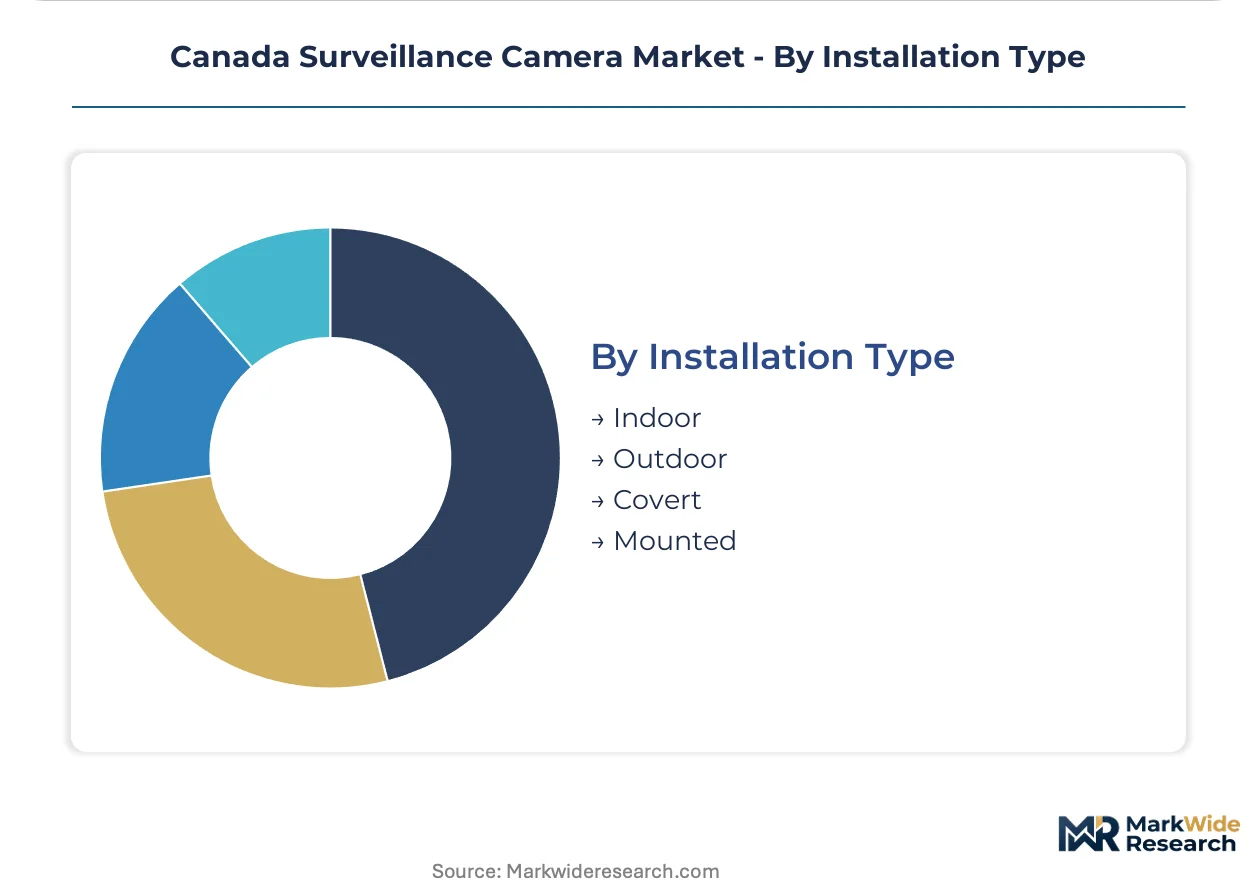
Installation Type:
Environmental exposure dictates ruggedization requirements and maintenance economics across Canadian climate zones.
- Outdoor:IP66-rated enclosures with heater-blower assemblies withstand prairie temperature swings from minus forty to plus thirty-five Celsius. Alberta oil sands operators deploy these for perimeter monitoring.
- Indoor:Standard dome and bullet form factors serve office, healthcare, and educational facilities where thermal management is simplified.
- Mounted:Pole and wall installations dominate traffic management and urban surveillance in Toronto and Vancouver corridors.
- Covert:Disguised form factors support law enforcement and casino security applications with strict chain-of-custody protocols.
Unit shipments dominate in Outdoor; Covert installations show the steepest expansion trajectory as facial-recognition legislation tightens audit requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian surveillance camera deployment concentrates in provinces with dense urban corridors and critical infrastructure, while manufacturing supply relies on East Asian sensor foundries. Provincial procurement fragmentation creates divergent compliance landscapes across Ontario, Quebec, British Columbia, Alberta, and Atlantic Canada.
Ontario
Toronto's smart city corridors and aging commercial building stock drive Power-over-Ethernet retrofit demand. Municipal procurement under Ontario's freedom-of-information statutes mandates encrypted storage certification for video analytics programs. The Greater Toronto Area anchors enterprise and banking verticals requiring zero-latency wired installations.
Quebec
Montreal's healthcare networks pilot unified physical-cyber security platforms merging surveillance with patient-flow analytics. Provincial procurement rules under Quebec's municipal tendering framework extend sales cycles but favor established suppliers with compliance documentation. The province's video analytics deployment lags Ontario by two to three years.
British Columbia
Vancouver's port security zones deploy thermal-analytics arrays for maritime perimeter intrusion detection under Transport Canada directives. Health Canada's PIPEDA guidelines reshape procurement criteria for encrypted storage and data sovereignty in coastal municipalities. The Lower Mainland concentrates government and transportation vertical demand.
Alberta
Oil sands operators deploy ruggedized outdoor cameras with heater-blower assemblies for perimeter monitoring in extreme temperature ranges. Edge computing thermal constraints limit analytics reliability in sub-zero prairie deployments outside southern corridor facilities. Calgary and Edmonton anchor enterprise demand for hybrid cloud-edge architectures.
Atlantic Canada
Halifax and St. John's smart-city initiatives lag Ontario and British Columbia by three to five years in video-analytics deployment. Budget-constrained municipal installations sustain analog camera demand in coaxial-cable legacy infrastructure. The region presents first-mover whitespace for systems integrators targeting underpenetrated Atlantic corridors.
Canada Surveillance Camera Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integrated system tiers. Market structure consolidates around three strategic archetypes: open-architecture platform vendors, vertically integrated sensor manufacturers, and cloud-native analytics providers. Competitive moves center on unbundling hardware-software procurement and certifying sovereign data residency for government tenders.
Within the open-architecture tier, Axis Communications AB and Avigilon Corporation exemplify divergent positioning strategies. Bosch Sicherheitssysteme GmbH anchors the vertically integrated manufacturer archetype through in-house image sensor production. Hanwha Vision and Hangzhou Hikvision Digital Technology Co., Ltd. occupy positions in the scale-driven hardware supply segment. Honeywell Security represents the diversified conglomerate approach spanning building systems integration.
| Leading Market Players |
|---|
| Axis Communications AB |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Hanwha Vision |
| Dahua Technology |
| Bosch Sicherheitssysteme GmbH |
| Avigilon Corporation |
| Honeywell Security |
| Vivotek Inc. |
| March Networks |
| Others |
Pricing and Supply Chain Analysis
Edge-computing chipset miniaturization is simultaneously compressing hardware production costs and concentrating procurement leverage among Canadian systems integrators capable of certifying Health Canada encryption standards. This dual effect rewards vendors with sovereign data residency capabilities while penalizing offshore cloud providers facing PIPEDA disqualification from government tenders.
Pricing Analysis
Margin tightening in mid-tier camera hardware reflects CMOS sensor supply concentration among East Asian foundries and currency-hedging costs passed through to Canadian buyers. Three-tier pricing structure across premium analytics-integrated, standard PoE-enabled, and economy analog-replacement levels separates vendors by certification grade and after-sales service bundling. Cost-down pressure accelerates as municipal procurement unbundles software licensing from hardware procurement. Government and banking verticals show lowest price sensitivity due to zero-latency requirements; retail chains exhibit highest sensitivity as they benchmark interoperability scores across multi-site deployments.
Supply Chain Analysis
Refurbishment flows for legacy analog installations in Atlantic Canada create secondary market circulation that tempers new equipment demand in budget-constrained municipal corridors. CMOS image sensor fabrication concentrates in Taiwan, South Korea, and China, drawing Canadian integrators into lead-time volatility exposure. Supply chain risk centers on single-source vulnerability for thermal microbolometer arrays used in Vancouver port security deployments. Distribution runs through Toronto and Vancouver-based systems integrators holding Health Canada compliance certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PIPEDA data-residency mandates under Health Canada guidelines erect a compliance moat that favors established vendors with sovereign cloud infrastructure, systematically excluding offshore competitors from government and healthcare procurement channels.
For Market Incumbents: To counter unbundling pressure from cloud-native analytics providers, deepen channel control through open-architecture certification programs with Ontario and British Columbia systems integrators. Prioritize backward integration into edge-computing chipsets rated for Alberta prairie temperature extremes. Anchor procurement relationships by pre-certifying encrypted storage solutions for municipal freedom-of-information tender requirements. For New Entrants and Emerging Players: Direct-to-integrator SaaS platforms bypass legacy bundling margins and unlock first-mover positioning in Halifax and St. John's smart-city corridors lagging Ontario deployment by three to five years. Target healthcare facility convergence in Alberta and Manitoba where unified physical-cyber security pilots merge surveillance with patient-flow analytics. Lead with explainable-analytics certifications that anticipate federal AI legislation restrictions on automated facial recognition. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified building-systems conglomerates seeking video analytics capabilities. Long-term viability hinges on regulatory compliance durability rather than hardware scale. Target acquisition archetypes: Canadian-hosted cloud-native platforms with PIPEDA certification and audit-trail capabilities. Monitor forthcoming federal artificial-intelligence legislation as inflection signal for explainable-analytics valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| PIPEDA Compliance Certification | Health Canada encryption standards unlock government and healthcare procurement channels. |
| Edge-AI Chipset Integration | On-camera inference enables real-time threat classification for Alberta oil sands perimeter monitoring. |
| Atlantic Canada Geographic Expansion | Halifax and St. John's smart-city whitespace offers three-to-five-year first-mover advantage. |
| Healthcare Facility Convergence | Alberta hospital networks pilot unified physical-cyber platforms merging surveillance with patient-flow analytics. |
| Explainable-Analytics Development | Federal AI legislation tailwind advantages vendors with audit-trail capabilities for facial-recognition deployments. |
Research Methodology
Multi-period observation of municipal procurement volumes, PoE retrofit deployment rates, and cloud-subscription adoption anchored the trend analysis, supplemented by interviews with security systems integrators, municipal procurement officers, healthcare facility managers, and video management platform engineers. Secondary validation drew from Health Canada PIPEDA guidance documents, Office of the Privacy Commissioner enforcement bulletins, Transport Canada maritime security directives, and provincial freedom-of-information statute amendments. Bottom-up camera shipment estimates and top-down infrastructure spending forecasts underwent triangulation.
Segment-weighting across product type, technology deployment model, end-user vertical, and installation environment dimensions structured the analytical framework across the projection horizon. CAGRs derived from logistic adoption curves fitted to cloud-subscription penetration patterns and thermal-analytics deployment trajectories in critical infrastructure. Forecast inputs incorporated CMOS sensor lead-time volatility indices and provincial procurement cycle duration differentials between Ontario and Quebec tendering frameworks.
The model holds under stable PIPEDA enforcement intensity and sustained municipal smart-city capital allocation; deviation in federal AI legislation timing or East Asian foundry capacity constraints would shift replacement cycle assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Middle East and Africa Video Surveillance Storage Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Commercial Aircraft Video Surveillance Systems Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
Wireless Security Camera Market
Video Surveillance Systems
China Surveillance IP Camera Market