
 Maritime Security Market | 2026-2036
Maritime Security Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Security Market Analysis
Premium integrated command-and-control suites is rebalancing away from standalone perimeter sensors as navies and port operators prioritize fused data architectures over point solutions. Northrop Grumman leverages its shipborne radar heritage to anchor high-end naval contracts across multiple allied fleets. Leonardo competes through specialized underwater acoustic systems that dominate Mediterranean and Middle Eastern markets. Thales Group extends its geographic footprint through port security integration projects spanning three continents.
Maritime security encompasses layered protection of vessels, port infrastructure, and coastal zones through surveillance, access control, and threat detection systems operating across surface, subsurface, and aerial domains. These systems typically integrate radar returns, electro-optical feeds, and automatic identification system data into unified operational pictures for real-time decision support. Surveillance Systems leads solution spending as legacy analog networks undergo digital retrofit cycles across major harbors. IoT Solutions within the technology dimension captures the fastest expansion, driven by sensor-to-cloud architectures that reduce cabling costs on aging vessel fleets. Port Authorities represent the most mature end-user segment with standardized procurement frameworks, while Offshore Facilities present concentrated margin pools due to bespoke integration requirements in harsh environments.
The International Maritime Organization's ISPS Code mandates security assessments that directly shape product certification requirements for port access control vendors. The EU Green Deal's port electrification provisions are creating parallel demand for integrated cyber-physical security at shore power facilities. The US Coast Guard's domestic port security regulations enforce layered technology deployments that sustain replacement cycles for intrusion detection hardware. Stakeholders must monitor how NATO's maritime domain awareness data-sharing protocols reshape interoperability standards before committing to proprietary platform architectures.
Market Dynamics
Naval modernization programs across NATO member states are compressing procurement cycles for integrated surveillance platforms, forcing vendors to abandon standalone sensor sales in favor of fused data architectures that unify radar, electro-optical, and automatic identification system feeds into single operational pictures.
Growth Catalysts
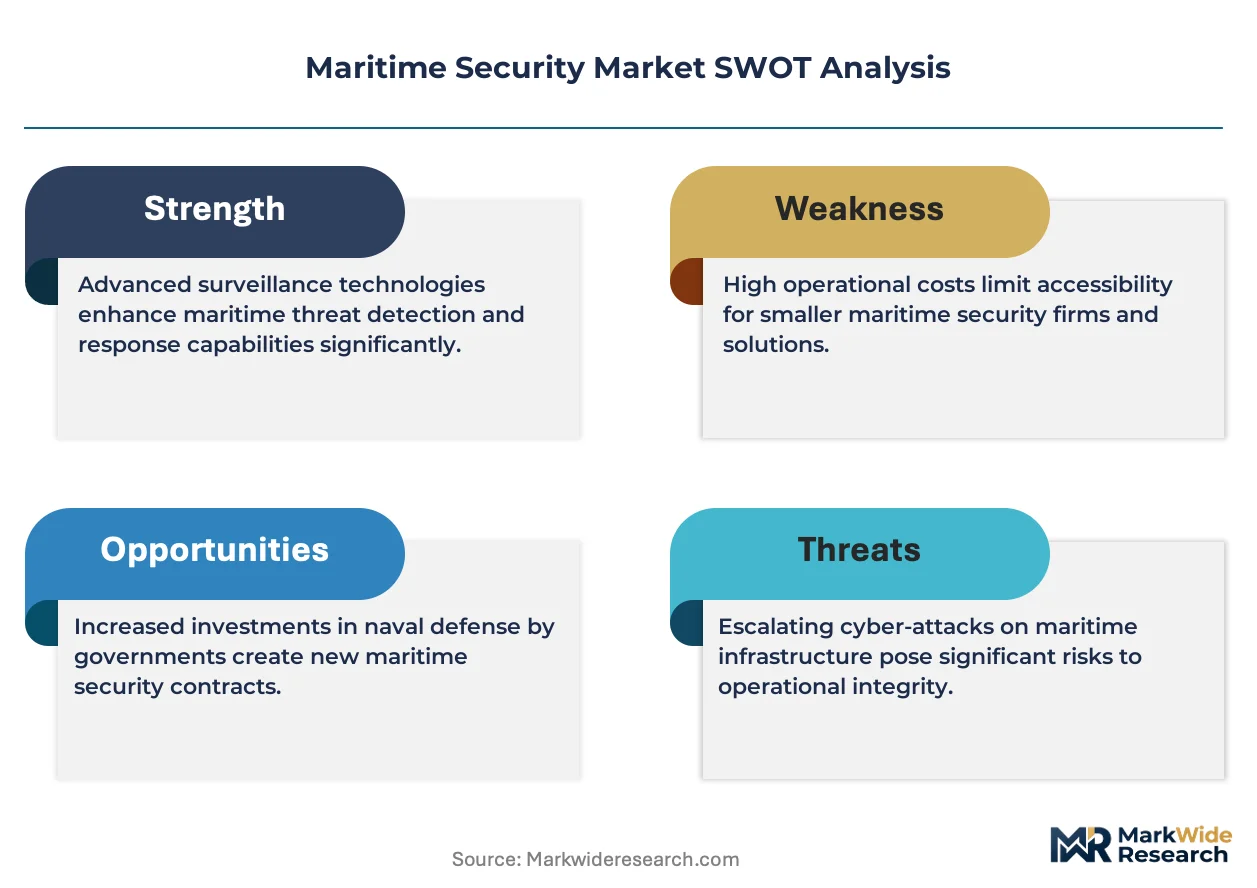
- ISPS Code Amendments:The International Maritime Organization's updated port facility security assessments mandate enhanced access control systems, driving replacement demand at major harbors worldwide.
- Coastal Southeast Asia:Piracy threats and territorial disputes in waters around Indonesia, Malaysia, and the Philippines sustain investment in maritime domain awareness systems for littoral patrol fleets.
- Sensor-to-Cloud Architectures:IoT solutions reduce cabling costs on aging vessel fleets, accelerating digital retrofit cycles for commercial shipping operators managing legacy analog networks.
Market Restraints
- Specialized Component Concentration:Gallium nitride semiconductor substrates for next-generation naval radar face supply bottlenecks concentrated among a limited supplier base in East Asia.
- Proprietary Platform Lock-In:NATO's maritime domain awareness data-sharing protocols remain incomplete, creating interoperability uncertainty that delays procurement commitments to single-vendor architectures.
- Extended Certification Timelines:Type approval for underwater acoustic systems under IEC 60565 testing protocols stretches eighteen to thirty-six months, freezing working capital for specialized manufacturers.
Strategic Opportunities
- EU Green Deal Tailwinds:Port electrification provisions create parallel demand for integrated cyber-physical security at shore power facilities across Rotterdam, Hamburg, and Antwerp.
- Offshore Facility Expansion:Bespoke integration requirements for floating production storage and offloading vessels in harsh North Sea and Gulf of Mexico environments command concentrated margin pools.
- AI-Enhanced Acoustic Fusion:Convergence of machine learning classification algorithms with passive sonar arrays enables real-time submarine detection without dedicated operator stations.
Industry Challenges
- Systems Integration Talent Scarcity:Vendors struggle to recruit engineers proficient in both legacy naval combat management systems and modern API-based data architectures.
- Multi-Domain Certification Burden:Products must simultaneously satisfy IEC maritime standards, NATO STANAG interoperability requirements, and national cryptographic accreditation processes.
- Legacy Vessel Retrofit Complexity:Physical constraints of hull-mounted sensor installation on 1980s-era frigates limit upgrade paths without drydock structural modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Security Market |
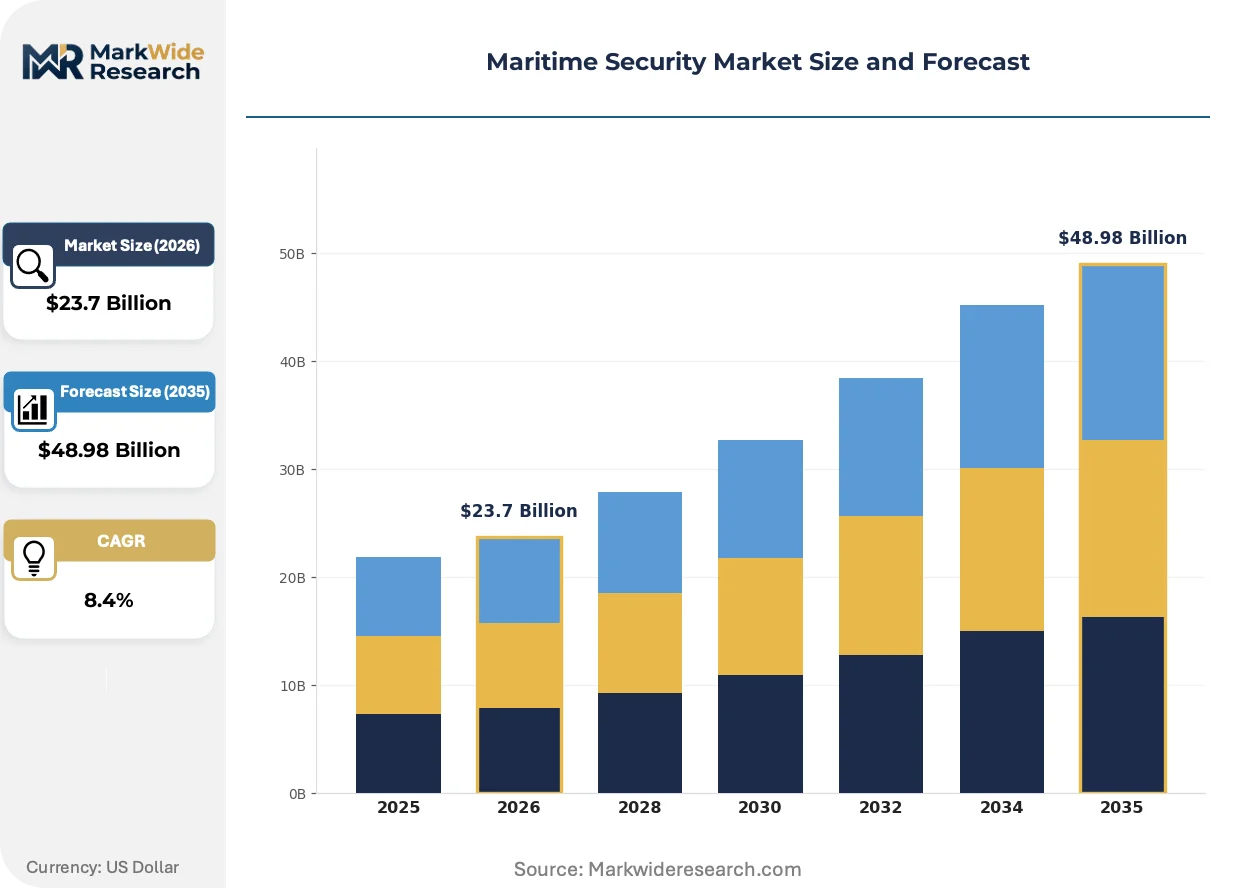
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Surveillance Systems, Access Control, Intrusion Detection, Alarm Systems End User: Shipping Companies, Port Authorities, Coast Guard, Offshore Facilities Technology: Biometrics, IoT Solutions, Drones, Radar Systems Deployment: On-Premises, Cloud-Based, Hybrid, Remote Monitoring |
| Companies Covered | Northrop Grumman, Leonardo, Thales Group, Raytheon Technologies, General Dynamics, Lockheed Martin, Saab AB, Smiths Detection Group Limited, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Security Market Emerging Trajectories
Artificial intelligence inference at the network edge is compressing detection-to-response timelines from minutes to seconds, eliminating the latency of cloud-reliant architectures in contested electromagnetic environments.
Hyperspectral electro-optical sensors paired with onboard GPU clusters is consolidating the market for standalone infrared and visible-light cameras into unified multi-spectrum turrets. Port authorities in Singapore and Rotterdam are adopting these integrated payloads for perimeter surveillance, reducing maintenance overhead from multiple discrete systems. The structural consequence is collapsing procurement budgets for point-solution vendors unable to deliver fused spectral analysis.
The EU Green Deal's port electrification provisions are mandating shore power infrastructure upgrades that must incorporate physical security against sabotage and cyber intrusion. Terminal operators in Hamburg and Antwerp are layering access control and anomaly detection into high-voltage connection points. This regulatory pressure most acutely affects brownfield ports with decades-old electrical distribution lacking integrated monitoring.
Naval procurement offices are consolidating vendor relationships through framework agreements that bundle hardware, software, and through-life support into single accountability structures. The Royal Navy and French Navy have both moved to ten-year availability contracts, displacing traditional transactional equipment purchases. This behavioral shift concentrates contract awards among systems integrators with sovereign maintenance capabilities, visible across NATO's major surface combatant programs.
Maritime Security Market Segmentation
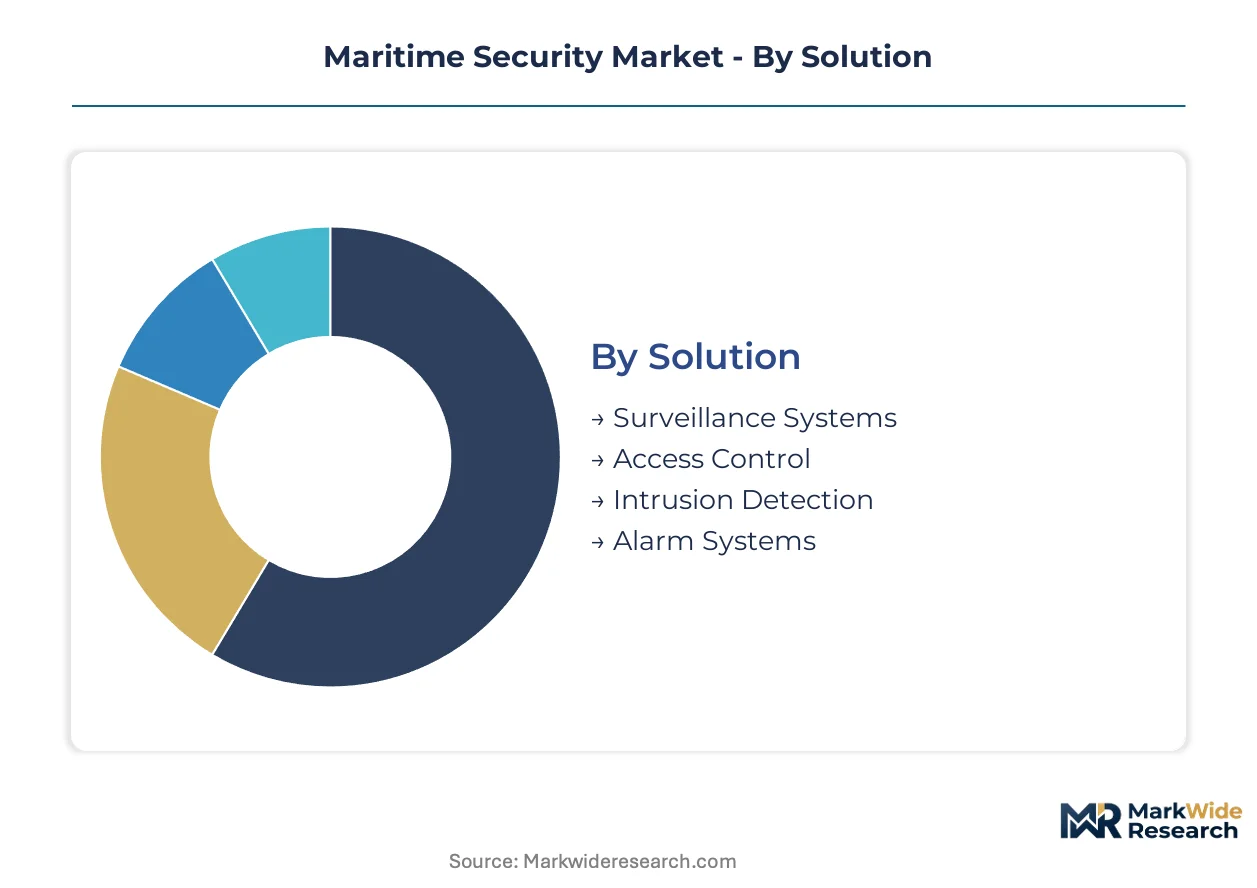
Maritime security procurement bifurcates between standardized port infrastructure packages and bespoke naval combat system integrations. Vendors must calibrate product architectures across this spectrum to capture both volume-driven harbor retrofits and margin-rich fleet modernization programs.
Solution:
Customization intensity varies sharply across this category, from commoditized perimeter hardware to mission-specific naval sensor suites requiring hull-integrated engineering.
- Surveillance Systems:Multi-domain sensor fusion platforms integrating radar, electro-optical, and automatic identification system data into unified operational pictures. NATO naval modernization programs in Norway, the Netherlands, and Poland are compressing procurement cycles for these integrated architectures as fleets retire 1980s-era analog networks. Most installed capacity flows through Surveillance Systems. Expansion is steepest in Access Control.
- Access Control:Biometric and credential-based port entry systems governed by International Maritime Organization ISPS Code certification requirements. Rotterdam, Singapore, and Long Beach port authorities are mandating multi-factor authentication upgrades at container terminal gates, driving replacement demand for legacy card-reader infrastructure.
- Intrusion Detection:Perimeter sensors and underwater acoustic monitors for critical maritime infrastructure protection.
- Alarm Systems:Automated alert distribution networks linking vessel crews with shore-based response coordination centers.
Surveillance Systems absorbs the largest share of naval capital expenditure. Access Control is climbing the fastest as port electrification under the EU Green Deal forces security retrofits at shore power facilities.
End User:
Contracting sophistication and procurement cycle length distinguish mature institutional buyers from fragmented commercial operators across this dimension.
- Port Authorities:Standardized tender frameworks with multi-year maintenance agreements dominate procurement in Hamburg, Antwerp, and Singapore. These entities leverage scale to enforce interoperability mandates that fragment vendor lock-in strategies. Coast Guard and Offshore Facilities concentrate the steepest expansion trajectories.
- Offshore Facilities:Floating production storage and offloading vessels and fixed platforms in the North Sea and Gulf of Mexico require bespoke integration of explosion-proof sensors with harsh-environment cabling systems. Bespoke engineering specifications command premium pricing unavailable in standardized port deployments.
- Shipping Companies:Commercial fleet operators managing legacy vessel retrofits prioritize sensor-to-cloud architectures that minimize drydock time.
- Coast Guard:Littoral patrol fleets in Indonesia, Malaysia, and the Philippines sustain demand for compact maritime domain awareness systems.
Port Authorities deploy the most installed base. Offshore Facilities and Coast Guard are expanding most quickly.
Technology:
Hardware-software integration depth separates legacy sensor vendors from platform-native competitors in this category.
- IoT Solutions:Sensor-to-cloud architectures reducing cabling costs on aging commercial fleets through wireless data transmission and edge computing nodes. Mediterranean and Southeast Asian shipping operators are accelerating digital retrofits as satellite connectivity costs decline. Radar Systems and Drones are gaining share fastest.
- Radar Systems:Next-generation active electronically scanned arrays utilizing gallium nitride semiconductors for enhanced target discrimination in cluttered coastal environments. Supply bottlenecks for specialized substrates concentrated among East Asian foundries are constraining procurement timelines for NATO frigate programs.
- Biometrics:Facial recognition and fingerprint authentication systems for crew identity verification at port entry points.
- Drones:Unmanned aerial platforms extending perimeter surveillance coverage beyond fixed camera networks.
Radar Systems carries the heaviest installed investment. IoT Solutions is expanding most quickly.
Deployment:
Data sovereignty requirements and connectivity reliability dictate architecture selection across naval, commercial, and port environments.
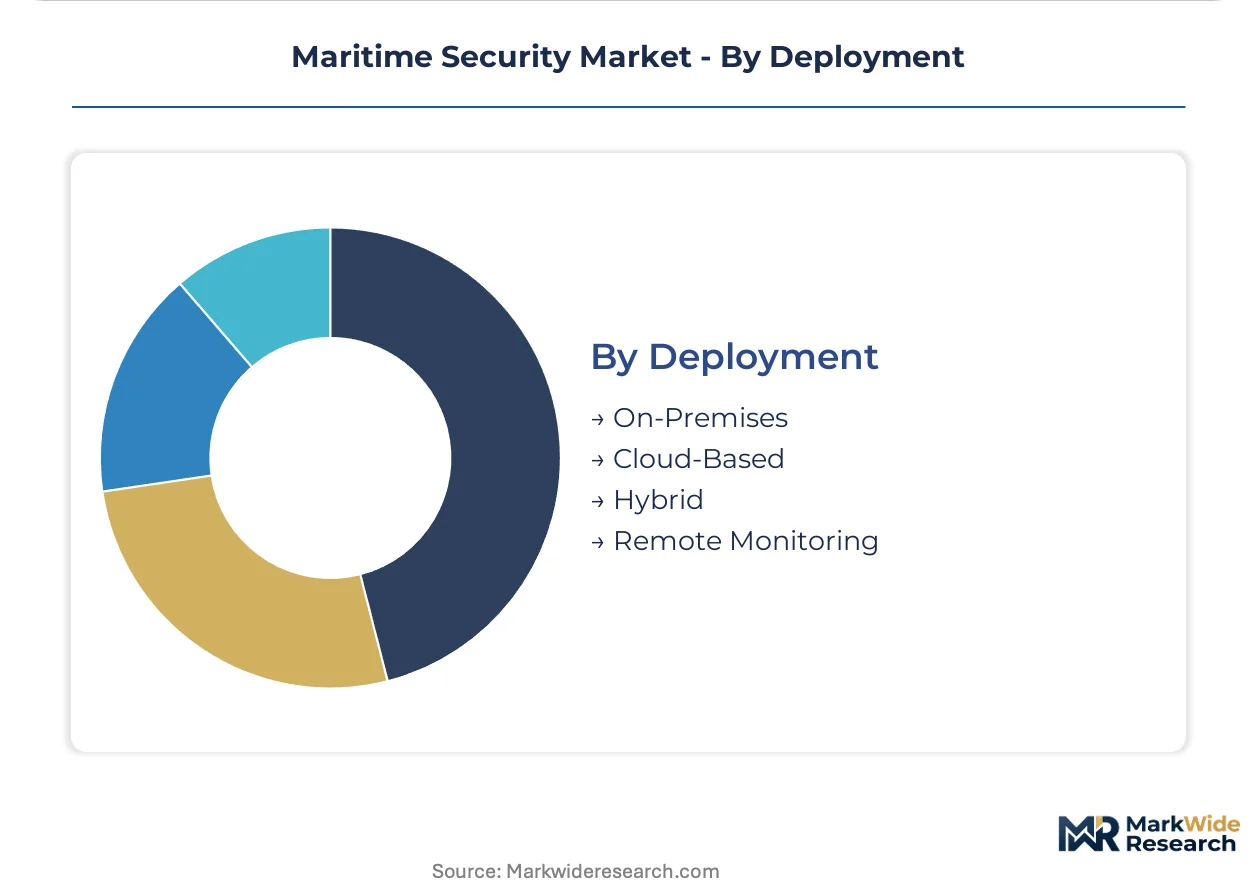
- On-Premises:Air-gapped command-and-control systems mandatory for classified naval operations and critical infrastructure protection against cyber intrusion. French and British nuclear deterrent patrol vessels require fully isolated combat management systems precluding any external network dependency. Cloud-Based and Hybrid are climbing the fastest.
- Hybrid:Architectures combining local sensor processing with cloud-based analytics for commercial shipping fleets operating across variable bandwidth conditions. Singapore-flagged container lines are piloting these configurations to balance real-time threat response with fleet-wide data aggregation.
- Cloud-Based:Centralized analytics platforms for multi-port operators seeking unified security dashboards.
- Remote Monitoring:Shore-based operator stations managing autonomous vessel surveillance in reduced-crew configurations.
On-Premises retains dominant installed capacity in naval applications. Hybrid and Cloud-Based are expanding most quickly in commercial shipping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Systems integration engineers cluster around naval shipyards and major port complexes, concentrating technical capacity in coastal metropolitan areas with established maritime industrial ecosystems.
United States
The US Coast Guard's layered port security regulations sustain replacement cycles for intrusion detection hardware at container terminals in Long Beach and New York-New Jersey. The Maritime Transportation Security Act enforcement drives certification demand for access control vendors serving critical infrastructure. Norfolk and San Diego naval bases anchor procurement for integrated combat management systems on surface combatants.
United Kingdom
Royal Navy ten-year availability contracts concentrate vendor accountability in Portsmouth and Glasgow shipbuilding corridors. The UK Maritime and Coastguard Agency enforces ISPS Code compliance assessments at Felixstowe and Southampton. Scottish waters host underwater acoustic testing for North Sea offshore facility protection systems.
Germany
EU Green Deal port electrification timelines accelerate cyber-physical security deployment at Hamburg and Bremerhaven shore power facilities. The Federal Maritime and Hydrographic Agency coordinates NATO STANAG interoperability certification for naval radar suppliers. Kiel and Wilhelmshaven anchor frigate modernization programs demanding fused sensor architectures.
Singapore
The Maritime and Port Authority mandates multi-factor authentication upgrades at Pasir Panjang and Tuas container terminals under revised ISPS Code frameworks. Littoral patrol fleet procurement in the Singapore Navy drives compact maritime domain awareness system demand. The city-state's shipyards service regional commercial fleet retrofits with sensor-to-cloud architectures.
Indonesia
Piracy threats in the Malacca Strait and Sulawesi Sea sustain investment in coastal surveillance radars for Bakamla maritime patrol units. The national port authority implements biometric access control at Tanjung Priok and Surabaya under IMO security directives. Batam island clusters shipyard capacity for regional vessel security retrofit programs.
Maritime Security Market Vendor Landscape
Top-tier vendors anchor naval combat system integration, while mid-tier specialists compete on port infrastructure retrofits and commercial fleet sensor packages. The vendor base stratifies between sovereign maintenance capabilities and technology licensing partnerships. Three archetypes dominate: systems integrators with through-life support contracts, component specialists in underwater acoustics and electro-optics, and platform-agnostic software vendors. Consolidation pressures favor M&A activity among sensor fusion developers, while framework agreements displace transactional equipment sales.
Within the integrated systems tier, Northrop Grumman and Thales Group occupy positions reflecting shipborne radar heritage and port security integration footprints respectively. Leonardo represents the specialized acoustic systems archetype dominant in Mediterranean and Middle Eastern markets. These three exemplify competitive positioning around sovereign maintenance networks and multi-decade naval procurement relationships.
| Leading Market Players |
|---|
| Northrop Grumman |
| Leonardo |
| Thales Group |
| Raytheon Technologies |
| General Dynamics |
| Lockheed Martin |
| Saab AB |
| Smiths Detection Group Limited |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's port electrification mandates gate both qualified supply and premium-tier pricing access, as terminal operators in Hamburg and Rotterdam must source IEC-certified cyber-physical security systems for shore power infrastructure that command 40-60% pricing premiums over standard perimeter hardware.
Pricing Analysis
Bundled ten-year availability contracts versus unbundled transactional equipment sales split the market into divergent pricing architectures. The Royal Navy and French Navy framework agreements consolidate hardware, software, and through-life support into single accountability structures that eliminate point-solution vendor pricing power. Price differentiation hinges on sovereign maintenance capability and NATO STANAG interoperability certification tier. Cost compression in standalone sensor tiers is intensifying because naval procurement offices favor fused data architectures over discrete radar or electro-optical purchases. Commercial shipping operators exhibit highest price sensitivity, while coast guard agencies prioritize performance over unit economics.
Supply Chain Analysis
Certification and qualification gating under IEC 60565 and NATO STANAG protocols constrain vendor participation, as eighteen-to-thirty-six month type approval timelines freeze working capital and filter out undercapitalized competitors. Gallium nitride semiconductor substrates draw from concentrated East Asian foundries, while specialized underwater acoustic transducers rest on European and North American precision manufacturing. Supply chain risk centers on single-source vulnerability for naval-grade gallium nitride components amid geopolitical trade restrictions. Distribution runs through sovereign shipyard maintenance networks and port authority tender frameworks that fragment direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maritime security represents a margin-expansion story as sensor-to-cloud architectures reduce cabling costs and enable premium-tier pricing for integrated command-and-control suites.
For Market Incumbents: Hedge against proprietary platform obsolescence by accelerating API-native data architecture development before NATO maritime domain awareness protocols finalize interoperability standards. Secure backward integration into gallium nitride substrate supply through long-term offtake agreements with East Asian foundries. Deepen sovereign maintenance capabilities in Portsmouth, Kiel, and Singapore shipyard corridors to defend framework contract positioning. For New Entrants and Emerging Players: Enter via coast guard littoral patrol modernization programs in Indonesia, Malaysia, and the Philippines, where procurement sophistication lags NATO naval standards and price-performance trade-offs favor compact maritime domain awareness systems over integrated combat suites. Target commercial fleet retrofit demand for wireless sensor-to-cloud architectures that minimize drydock downtime. Pursue sensor fusion software licensing partnerships with established radar hardware vendors as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for underwater acoustic specialists because fragmented Mediterranean and Middle Eastern markets lack scale players with multi-regional service networks. Long-term viability hinges on positioning for NATO frigate modernization program awards and EU Green Deal port security retrofits. Watch for completion of NATO maritime domain awareness data-sharing protocols as the inflection signal triggering consolidation among sensor fusion developers.| Strategic Initiative | Industry Significance |
|---|---|
| Framework Agreement Consolidation | Royal Navy and French Navy ten-year contracts displace transactional equipment sales among NATO allies. |
| Gallium Nitride Supply Security | Long-term substrate offtake agreements with East Asian foundries mitigate procurement timeline risk for naval radar programs. |
| Sensor-to-Cloud Architecture Deployment | Mediterranean and Southeast Asian shipping operators accelerate digital retrofits as satellite connectivity costs decline. |
| Underwater Acoustic Specialist Acquisition | Machine learning classification convergence with passive sonar arrays enables real-time submarine detection without dedicated operator stations. |
| Shore Power Security Integration | Hamburg and Antwerp terminal operators layer access control into high-voltage connection points under EU Green Deal mandates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with naval procurement officers, port authority security directors, coast guard fleet managers, and systems integration engineers with secondary validation against IMO ISPS Code filings, NATO STANAG documentation, EU Green Deal implementation timelines, and customs trade data for gallium nitride semiconductor flows. Bottom-up vessel retrofit demand estimates and top-down defense budget allocation analysis provided cross-verification.
Segment-weighting across solution type, end-user category, technology platform, and deployment architecture anchored the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles, naval modernization program schedules, and regulatory compliance deadline clustering. Forecast inputs incorporated NATO maritime domain awareness protocol development status and EU port electrification timeline commitments.
Inputs from naval procurement offices and port authority tender databases were available through the study window; gaps in classified combat system specification detail introduce uncertainty bands around integrated platform revenue estimates. Deviation in NATO interoperability standard finalization or gallium nitride export control expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Cargo and Vehicle Screening Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
Integrated Security Solutions Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Specialized Threat Analysis and Protection Market
Security and Surveillance
Security and Surveillance Equipment Market
Security and Surveillance
Residential Security Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Global Firearm Sight Market