
 Explosive Trace Detection Market | 2026-2036
Explosive Trace Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Explosive Trace Detection Market Analysis
Enhanced sensitivity specifications for picogram-level detection is reorganizing competitive dynamics across the Explosive Trace Detection landscape. Smiths Detection Group Ltd. leverages its installed base at major aviation hubs to sustain long-term service contracts. FLIR Systems Inc. anchors its position through integrated thermal and trace detection platforms for layered security architectures. Morphix Technologies differentiates via colorimetric chemical detection strips that complement electronic systems in resource-constrained environments.
Explosive trace detection encompasses analytical systems designed to identify residual quantities of explosive materials—typically at nanogram to picogram thresholds—through sampling of surfaces, vapors, or particulate matter collected via swabs or ambient air intake. Ion mobility spectrometry dominates current deployments due to its rapid response cycle and operational simplicity in high-throughput screening environments, though mass spectrometry is gaining traction where forensic-grade specificity is required. Portable detectors command premium pricing in the form factor dimension because military and law enforcement end users prioritize field mobility over laboratory precision.
FAA certification standards and TSA qualification protocols govern system eligibility for US aviation applications, while EU aviation security regulations under EASA coordination mandate equivalent performance benchmarks across member state airports. India's BIS certification requirements and DGFT import classifications create additional compliance layers for foreign equipment suppliers seeking defense or homeland security contracts. Stakeholders must monitor evolving fragmentation between civil aviation mandates and military specifications as dual-use procurement pathways diverge in technical requirements.
Market Dynamics
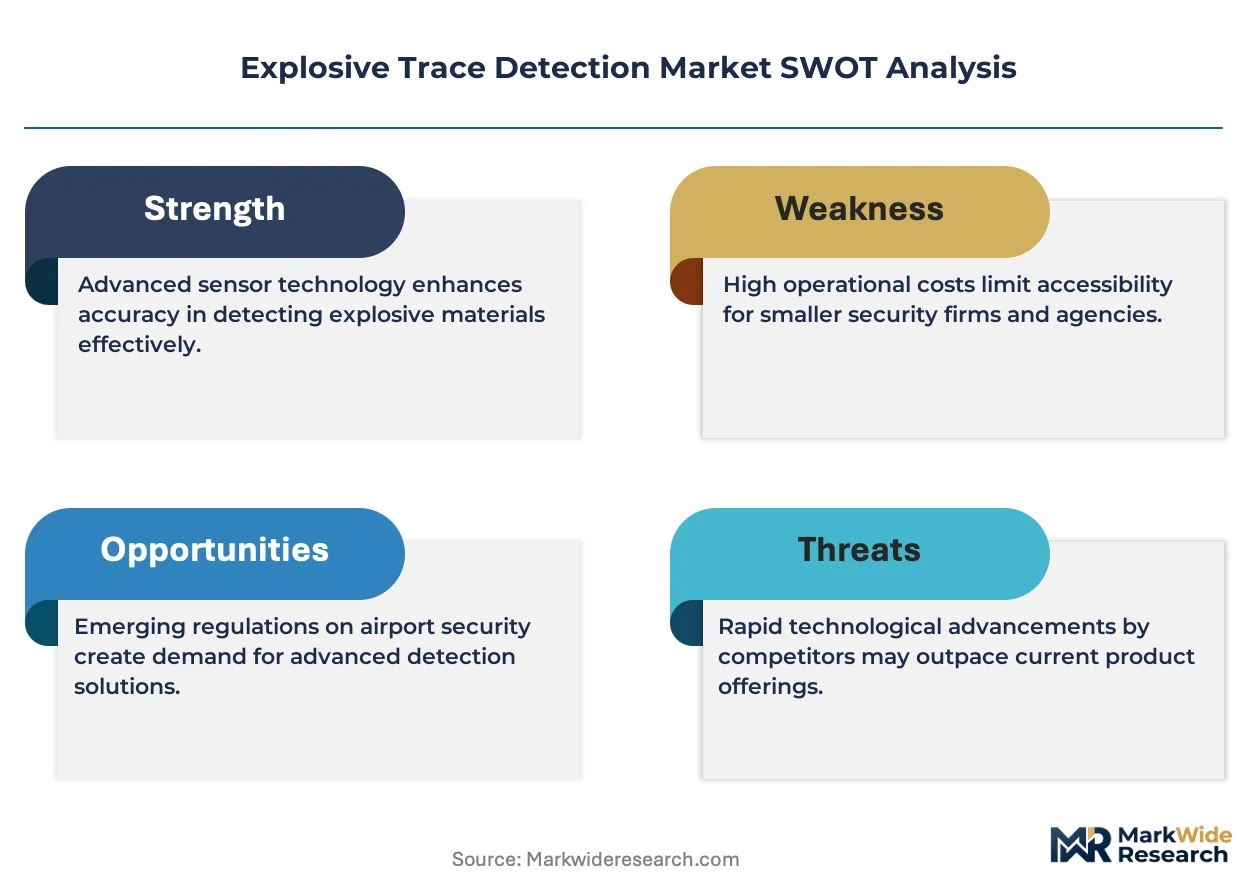
Picogram-level sensitivity mandates from TSA and EASA are compressing product refresh cycles and forcing incumbents to accelerate R&D timelines. Detection technology vendors now face simultaneous pressure from certification complexity and end-user demand for faster throughput.
Growth Catalysts
- Ion Mobility Spectrometry:Aviation security agencies in the United States and Germany favor IMS systems for sub-10-second analysis cycles at passenger checkpoints. The technology's operational simplicity drives replacement of older chemiluminescence units.
- EASA Coordination Mandates:EU aviation security regulations require member states to harmonize detection sensitivity thresholds across major hubs. This creates standardization pull for certified equipment suppliers.
- India:DGFT import classifications and BIS certification requirements for defense procurement are stimulating domestic assembly partnerships. Foreign suppliers establish local technical centers to meet homeland security contract eligibility.
Market Restraints
- Mass Spectrometry Cost Structure:Forensic-grade specificity requires vacuum pumps and precision ion optics that inflate unit economics. Budget-constrained municipal law enforcement agencies defer procurement.
- Calibration Consumables:Reference standard kits for picogram validation originate from a concentrated supplier base in Germany and Switzerland. Logistics bottlenecks extend field maintenance intervals.
- False Positive Rates:Nitrogen-rich consumer products trigger IMS alarms, necessitating secondary screening protocols that erode throughput at high-volume aviation facilities.
Strategic Opportunities
- Mass Spectrometry-Ion Mobility Hybrid Architectures:Converged platforms combine rapid IMS front-end screening with MS confirmation for contested samples. Forensic laboratories and elite military units represent early adopters.
- Colorimetric Strips:Resource-constrained environments in South Asia and Sub-Saharan Africa deploy chemical detection strips as primary screening tools. Disposable formats bypass capital equipment constraints.
- PLI Scheme:India's production-linked incentive scheme for electronics manufacturing offers tariff advantages to domestic trace detector assembly. Component suppliers establish captive operations near Bengaluru and Hyderabad.
Industry Challenges
- FAA Certification Timelines:TSA qualification protocols require 18-24 months of operational testing before aviation deployment approval. Product development roadmaps must incorporate extended regulatory gates.
- Spectroscopy Talent Scarcity:Ion mobility and mass spectrometry engineering expertise concentrates at a handful of university laboratories and national research institutes. Vendors compete aggressively for experienced analytical chemists.
- Legacy System Integration:Airport security networks operate mixed fleets of detection technologies with incompatible data protocols. New equipment procurement requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosive Trace Detection Market |
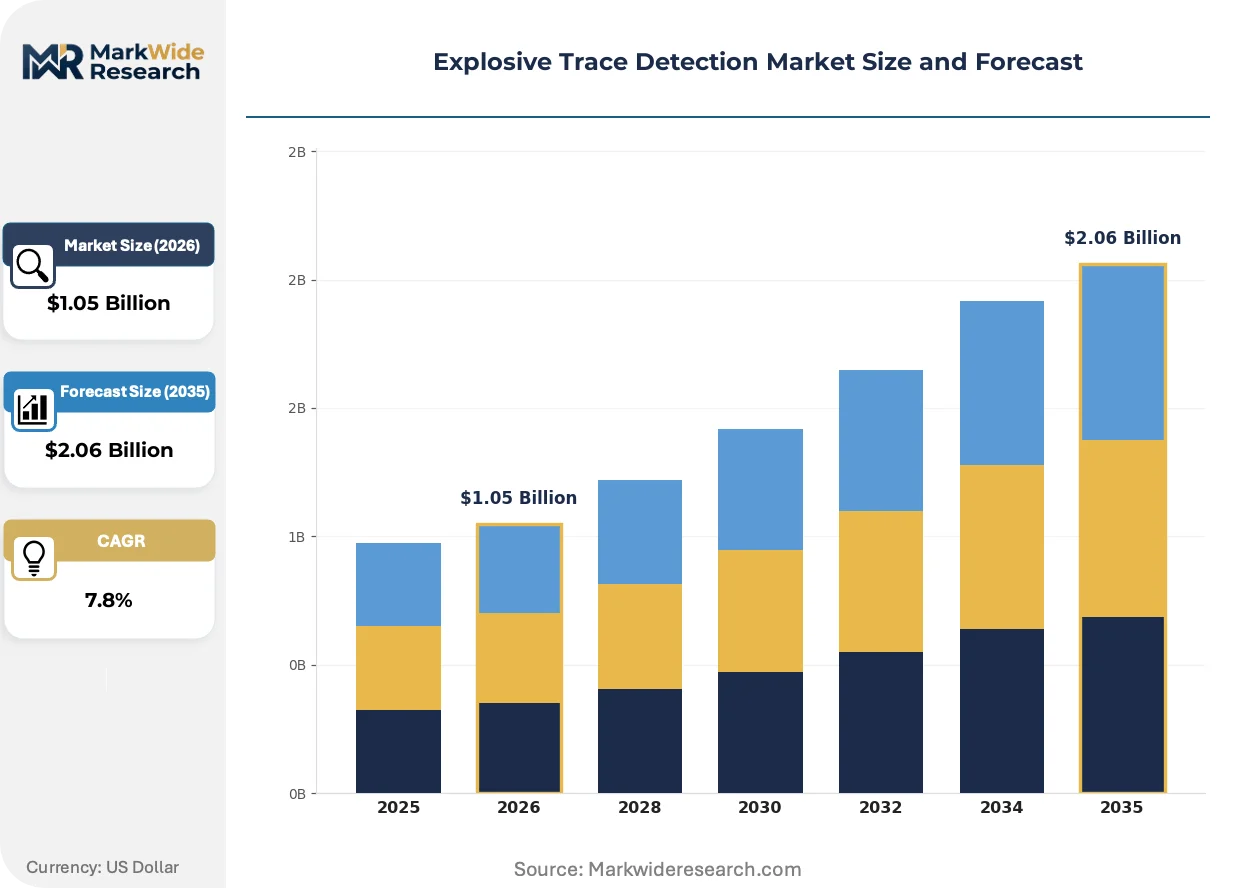
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ion Mobility Spectrometry, Mass Spectrometry, Gas Chromatography, Laser Induced Breakdown Spectroscopy End User: Military, Transportation Security, Law Enforcement, Event Security Application: Airport Security, Military Checkpoints, Public Events, Cargo Inspection Form Factor: Portable Detectors, Fixed Systems, Handheld Devices, Desktop Instruments |
| Companies Covered | FLIR Systems Inc., Analogic Corporation, Smiths Detection Group Ltd., DetectaChem, Morphix Technologies, Leidos Holdings Inc., Bruker Corporation, RS Dynamics, OSI Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosive Trace Detection Market Emerging Trajectories
Detection modality diversification is fragmenting the historical dominance of ion mobility spectrometry. Vendors now engineer platform-agnostic architectures that accommodate multiple analytical techniques within unified hardware enclosures.
Mass spectrometry is fragmenting the high-sensitivity segment previously monopolized by IMS variants. Forensic laboratories and military explosive ordnance disposal units adopt portable quadrupole and ion trap systems for definitive compound identification. The technology's higher capital cost compresses addressable market scope to specialized end-uses with evidentiary requirements.
REACH chemical registration requirements in Europe are reshaping consumables supply chains for calibration standards. Reference material suppliers must document full substance composition and toxicity profiles, extending lead times for explosive simulant kits. Aviation security contractors in Germany, France, and the Netherlands stockpile validated consumables to ensure operational continuity.
Service contract unbundling is altering procurement economics for airport authorities. Maintenance and recalibration agreements now separate from hardware acquisition, enabling competitive bidding for multi-vendor fleet support. United States hub operators pioneered this model; German and Indian aviation security agencies are adopting similar structures.
Explosive Trace Detection Market Segmentation
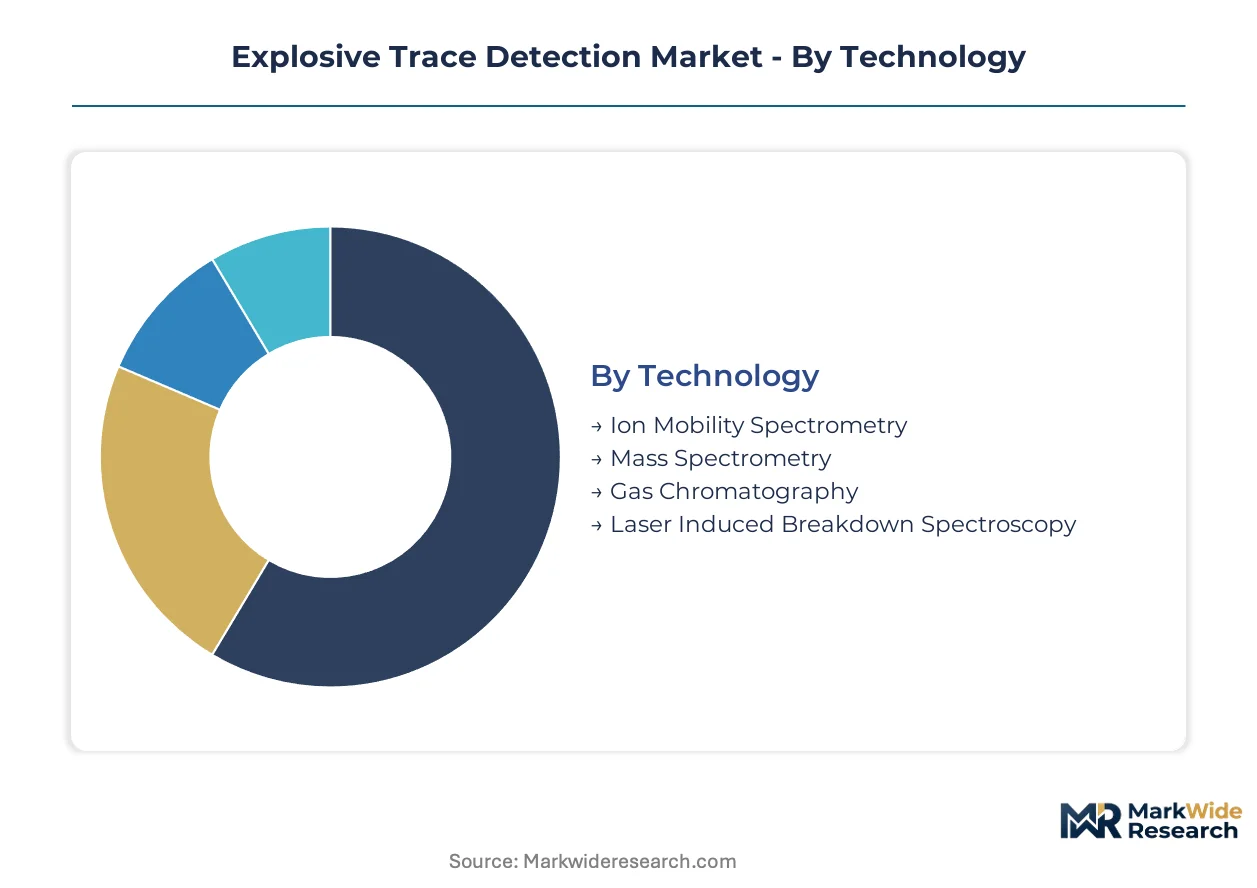
Explosive trace detection procurement channels diverge sharply by operational context. Aviation security agencies favor fixed installations with service contracts, while military and law enforcement units drive portable and handheld volumes through defense procurement frameworks.
Technology:
Ion mobility spectrometry and mass spectrometry flow through certified aviation channels requiring TSA or EASA validation, while gas chromatography and laser-based systems serve forensic laboratories and research institutes with less standardized procurement pathways.
- Ion Mobility Spectrometry:IMS systems detect explosives through ion drift time measurement in electric fields, achieving sub-10-second response cycles. Aviation security agencies in the United States and Germany specify IMS for passenger checkpoint throughput, though nitrogen-rich consumer products generate false positives requiring secondary screening protocols.
- Mass Spectrometry:MS platforms employ vacuum ionization and mass-to-charge ratio analysis for forensic-grade compound identification. Military explosive ordnance disposal units and elite law enforcement agencies absorb premium unit costs to obtain evidentiary certainty unavailable from IMS screening.
- Gas Chromatography:GC separates explosive vapors through column chromatography for laboratory confirmation workflows.
- Laser Induced Breakdown Spectroscopy:LIBS uses pulsed laser ablation for elemental analysis of suspicious residues without consumable reagents.
By volume, ion mobility spectrometry leads. By growth pace, mass spectrometry is gaining share fastest in specialized end-uses.
End User:
Cost tier stratification separates military and transportation security buyers—who absorb six-figure system investments—from municipal law enforcement and event security operators constrained by annual capital budgets.
- Military:Defense procurement frameworks prioritize field portability, ruggedized enclosures, and interoperability with command networks. Forward operating bases and checkpoint units drive replacement cycles tied to deployment rotation schedules.
- Transportation Security:Aviation authorities mandate certified detection sensitivity thresholds that compress product refresh timelines. TSA and EASA qualification protocols govern eligibility for passenger screening lane deployment.
- Law Enforcement:Municipal agencies face budget constraints that favor lower-cost IMS units over mass spectrometry confirmation systems.
- Event Security:Temporary deployment models favor rental and lease structures for major sporting and political gatherings.
Transportation security commands the largest installed base. Military end-uses show the steepest expansion trajectory as counter-IED programs modernize.
Application:
Application concentration tracks threat assessment protocols—airport security and military checkpoints operate continuous screening regimes, while public events and cargo inspection deploy episodically with surge staffing models.
- Airport Security:Passenger checkpoint lanes require high-throughput systems with 99% uptime guarantees under FAA oversight. Calibration consumables and service contracts generate recurring revenue streams exceeding initial hardware acquisition.
- Military Checkpoints:Forward base perimeter screening demands battery-operated portability and rapid ambient air sampling without consumable swabs.
- Public Events:Stadium and convention center operators deploy temporary screening architectures for discrete threat windows.
- Cargo Inspection:Maritime container and air freight facilities integrate trace detection with X-ray and radiation screening for layered security.
Airport security represents the mature revenue core. Cargo inspection is climbing the fastest as supply chain security mandates tighten.
Form Factor:
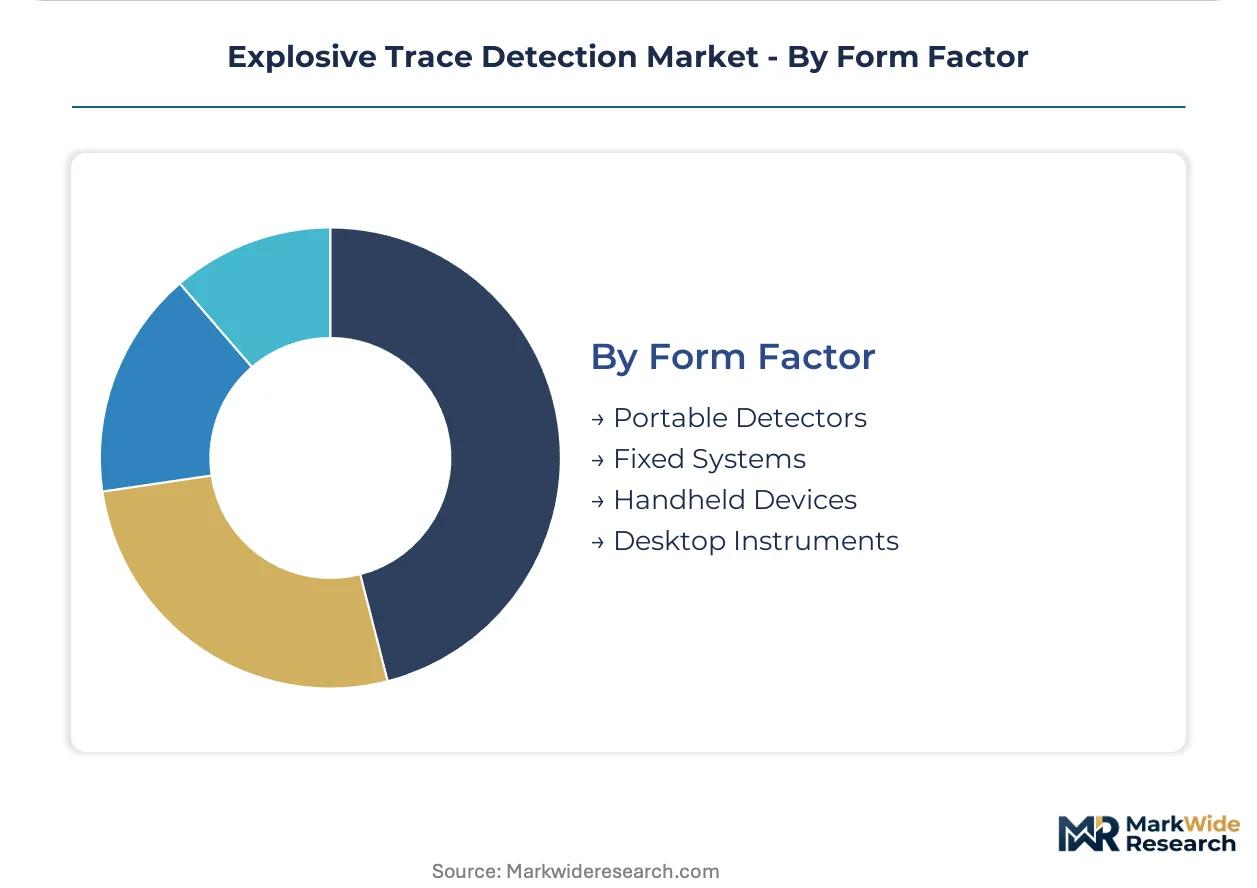
Margin structure inverts across form factors—portable and handheld devices command premium pricing per unit of detection capability, while fixed systems amortize hardware costs across decade-long service agreements.
- Portable Detectors:Battery-powered units weighing under 5 kilograms enable dismounted military operations and rapid law enforcement response. Premium pricing reflects miniaturized vacuum pumps and reduced false positive algorithms.
- Fixed Systems:Permanent installations at aviation checkpoints integrate with baggage handling and access control networks. TSA qualification protocols and EASA coordination mandates govern deployment eligibility.
- Handheld Devices:Single-operator swab-based screening tools serve secondary inspection roles in resource-constrained environments.
- Desktop Instruments:Laboratory-grade systems support forensic confirmation and calibration standard development.
Fixed systems dominate cumulative revenue. Portable detectors are expanding most quickly as military procurement prioritizes dismounted operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import asymmetries in explosive trace detection equipment concentrate manufacturing in Germany and the United States while India and the Middle East absorb inbound shipments. Aviation security procurement in recipient markets drives localized assembly partnerships to circumvent tariff barriers.
United States
TSA certification protocols govern system eligibility for passenger screening lanes at Atlanta, Dallas-Fort Worth, and Denver hubs. FAA oversight mandates 18-24 month qualification timelines that compress vendor R&D cycles. Boston and Washington DC corridors host calibration standard suppliers serving domestic aviation security contractors.
Germany
EASA coordination harmonizes detection sensitivity thresholds across Frankfurt, Munich, and Hamburg airports. REACH chemical registration requirements extend lead times for explosive simulant kits used in equipment validation. Baden-Württemberg and Bavaria industrial clusters manufacture precision ion optics and vacuum pump components.
India
DGFT import classifications and BIS certification requirements stimulate domestic assembly partnerships for defense and homeland security contracts. The PLI scheme for electronics manufacturing offers tariff advantages to trace detector assembly near Bengaluru and Hyderabad. Delhi-Mumbai aviation corridors drive checkpoint modernization procurement.
United Kingdom
Heathrow and Gatwick procurement specifications align with EU aviation security benchmarks post-Brexit transition arrangements. The national aviation regulator maintains equivalent performance thresholds for detection sensitivity. London and Southeast England concentrate service contract providers supporting mixed-vendor airport fleets.
United Arab Emirates
Dubai and Abu Dhabi aviation authorities deploy layered security architectures combining trace detection with thermal screening platforms. Federal transportation security mandates prioritize high-throughput systems for passenger checkpoint volume. Jebel Ali logistics corridors integrate cargo inspection protocols with maritime container screening.
Explosive Trace Detection Market Vendor Landscape
Listed leaders compete with private specialists across certification complexity and service contract tenure. Tier-one aviation security vendors leverage installed bases at major hubs to sustain decade-long maintenance agreements. Three archetypes dominate: integrated security conglomerates with multi-modal detection portfolios, analytical instrumentation specialists with mass spectrometry expertise, and niche providers of colorimetric consumables. M&A activity concentrates on calibration standard suppliers and middleware developers bridging incompatible data protocols.
Within the integrated detection tier, Smiths Detection Group Ltd. and FLIR Systems Inc. occupy positions anchored by aviation security service contracts. Bruker Corporation exemplifies the analytical instrumentation archetype with forensic-grade mass spectrometry platforms. Morphix Technologies represents the consumables-specialist vector through colorimetric chemical detection strips deployed in resource-constrained environments.
| Leading Market Players |
|---|
| FLIR Systems Inc. |
| Analogic Corporation |
| Smiths Detection Group Ltd. |
| DetectaChem |
| Morphix Technologies |
| Leidos Holdings Inc. |
| Bruker Corporation |
| RS Dynamics |
| OSI Systems Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts with decade-long recalibration agreements lock in supply access for aviation security agencies while anchoring price visibility for detection system vendors. TSA-certified equipment suppliers in the United States and EASA-coordinated procurement in Germany bundle hardware acquisition with mandatory maintenance protocols, compressing spot-market exposure for critical ion mobility spectrometry components.
Pricing Analysis
Aviation security procurement teams anchor tiered pricing structures across premium forensic-grade, standard checkpoint, and economy handheld tiers. Certification grade under TSA and EASA protocols commands substantial premiums over municipal law enforcement specifications, while volume scale discounts compress unit economics for hub operators replacing entire passenger screening lanes. Cost compression in standard-tier IMS systems intensifies as domestic assembly partnerships in India under the PLI scheme introduce tariff-advantaged competition. Municipal law enforcement agencies exhibit highest price sensitivity, deferring mass spectrometry confirmation systems for lower-cost IMS alternatives.
Supply Chain Analysis
Strategic stockpiling of calibration reference standards dominates inventory strategy as REACH registration requirements in Germany and Switzerland extend lead times for explosive simulant kits. Precision ion optics and vacuum pump components concentrate manufacturing in Baden-Württemberg and Bavaria industrial clusters, while consumable reagent production draws from concentrated supplier bases in Germany and Switzerland. Single-source vulnerability permeates picogram-validation reference kits, with aviation security contractors stockpiling validated consumables to ensure operational continuity. Distribution runs through certified channel partners holding TSA and EASA maintenance credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling transforms procurement economics, with maintenance and recalibration agreements expanding faster than hardware revenue as airport authorities competitively bid multi-vendor fleet support.
For Market Incumbents: Secure decade-long recalibration agreements at major aviation hubs before middleware developers bridge incompatible data protocols between mixed detection fleets. Invest in captive ion optics manufacturing to reduce dependency on Baden-Württemberg component suppliers facing REACH-related lead time extensions. Certification investment for next-generation picogram sensitivity thresholds represents the critical defensive lever against mass spectrometry hybrid architectures. For New Entrants and Emerging Players: Anchor in colorimetric chemical detection strips for resource-constrained environments in South Asia and Sub-Saharan Africa, where capital equipment constraints favor disposable formats over electronic systems. Military explosive ordnance disposal units seeking field-portable confirmation tools present the most penetrable segment for portable quadrupole mass spectrometry platforms. Partner with established calibration standard suppliers to bypass 18-24 month TSA qualification timelines. For Investors and Strategic Acquirers: Middleware developers resolving legacy system integration across incompatible aviation security data protocols present the highest-value acquisition archetype. Long-term viability rests on service contract tenure rather than hardware refresh cycles, with recurring revenue multiples expanding as procurement unbundling accelerates. Watch for EASA coordination mandates tightening detection sensitivity thresholds as the inflection indicator for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment for Picogram Sensitivity | TSA and EASA threshold tightening forces R&D acceleration across incumbent vendors. |
| Domestic Assembly Partnership | India's PLI scheme offers tariff advantages for trace detector assembly near Bengaluru. |
| Calibration Standard Stockpiling | REACH registration bottlenecks in Germany necessitate strategic consumable reserves. |
| Middleware Development | Legacy protocol bridging unlocks multi-vendor fleet support contracts at mixed-installation hubs. |
| Hybrid Architecture Convergence | IMS-MS platforms capture forensic laboratories and elite military units seeking evidentiary certainty. |
Methodological Framework
Operator-level perspectives from aviation security procurement directors, TSA certification engineers, military explosive ordnance disposal specialists, and calibration standard suppliers anchored the qualitative base. Primary interviews combined with secondary validation against FAA certification databases, EASA coordination mandates, DGFT import classifications, and SEC filings from listed detection technology vendors. Bottom-up equipment shipment tracking across aviation hubs and defense procurement frameworks triangulated against top-down market sizing.
Sensitivity analysis across technology adoption curves, certification timeline scenarios, and procurement unbundling rates informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include detection modality, end-user procurement framework, application environment, and form factor mobility tier. CAGRs derived from equipment replacement cycle compression and service contract revenue expansion. Forecast inputs incorporated TSA qualification protocol timelines and EASA sensitivity threshold harmonization mandates.
Material uncertainties — regulatory certification delays, REACH-related consumable supply disruptions, and military procurement budget reallocations — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued aviation security modernization and counter-IED program expansion. Revision becomes warranted when picogram sensitivity mandate implementation crosses acceleration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Latin America Security Services Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Private Security Market
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
Intrusion Alarm System Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
Cargo Container X-Ray Inspection Systems Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Global Acoustic Hailing Devices Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Specialized Threat Analysis and Protection Market