
 Private Military Security Services Market | 2026-2036
Private Military Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Private Military Security Services Market Analysis
EU corporate human rights due diligence mandates is hardening requirements for security contractors operating in extractive industry zones. DynCorp leverages its aviation maintenance integration to sustain government logistics contracts across contingency theaters. Constellis anchors protective services for diplomatic missions through its consolidated training infrastructure. Aegis Defence Services differentiates via risk intelligence platforms that compete on predictive threat assessment capabilities.
Private military security services encompass armed and unarmed protective operations performed by non-state entities under contract to governments, corporations, or international organizations, typically involving personnel vetted to military or law enforcement standards with capabilities spanning static site defense, mobile convoy protection, and intelligence support. The sector's primary commercial purpose centers on filling capability gaps where national military forces face political or resource constraints. Tactical service lines capture premium margins in conflict zone deployments where armed response protocols apply. Government client channels dominate contract value through multi-year overseas contingency arrangements. Long-term contract deployment models exhibit the most stable revenue predictability despite higher working capital requirements.
The US State Department's Directorate of Defense Trade Controls administers ITAR licensing frameworks that constrain foreign ownership thresholds and technology transfer protocols for American-registered security firms. The UK Foreign, Commonwealth and Development Office maintains parallel oversight through its private security company certification scheme under the 2001 International Code of Conduct. Stakeholders must monitor how emerging national legislation around mercenary activity definitions reshapes operational legality across jurisdictions where services deploy.
Market Dynamics
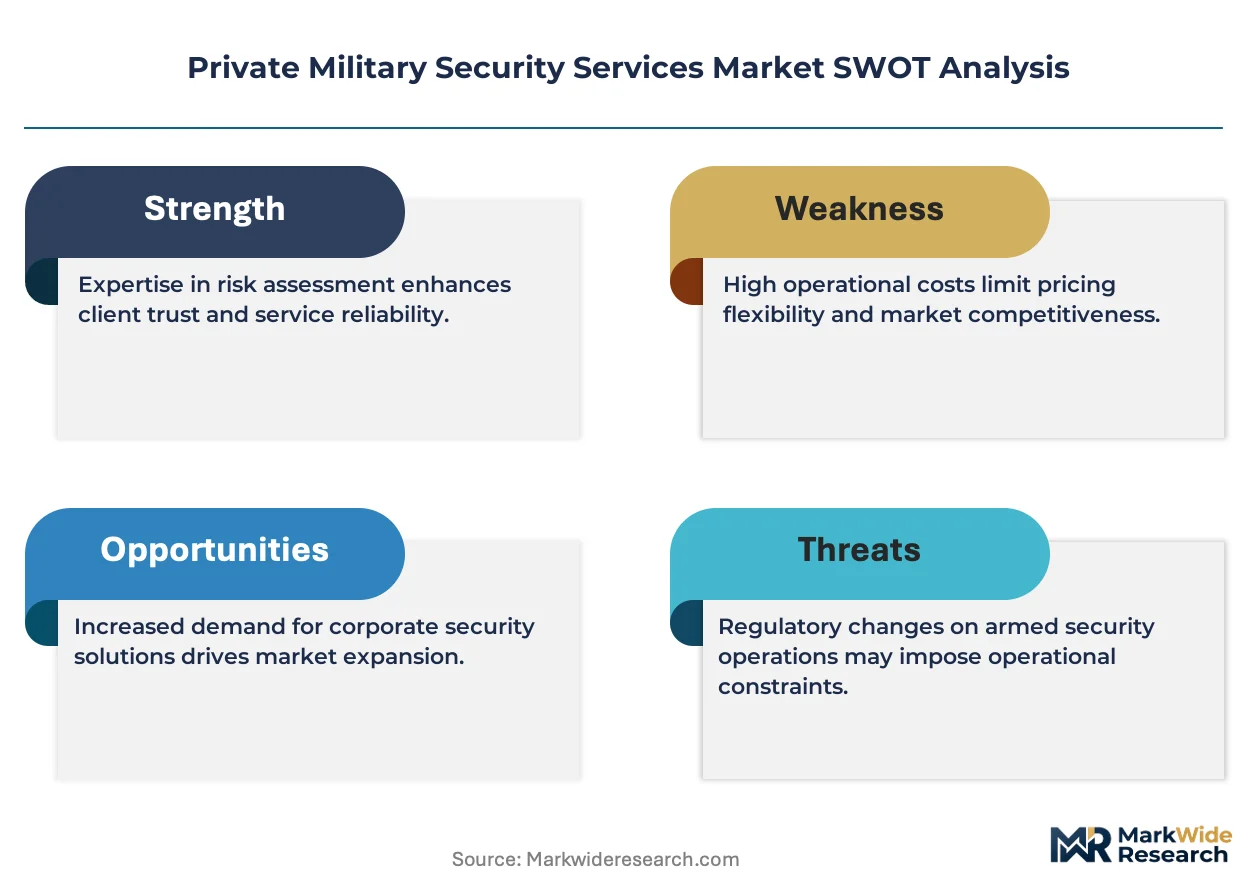
Government contingency contracting is hardening procurement standards across volatile regions, with compliance regimes like ITAR creating structural barriers to cross-border service provision while concentrating contract awards among vetted domestic providers.
Growth Catalysts
- ITAR Licensing Frameworks:The US Directorate of Defense Trade Controls administers export controls that privilege American-registered firms for embassy protection contracts, creating protected demand channels.
- Extractive Industry Due Diligence:EU corporate human rights mandates require security vetting for mining and energy operations in conflict zones, expanding contractable service scope.
- Middle East Tactical Deployment:Sustained instability in Iraq and Yemen sustains multi-year armed convoy and site defense arrangements with predictable revenue streams.
Market Restraints
- Foreign Ownership Thresholds:ITAR compliance constrains capital access for non-American investors seeking to acquire US-registered security firms.
- Personnel Vetting Costs:Military and law enforcement standard background checks impose fixed per-contractor costs that compress margins on smaller engagements.
- Legal Definition Uncertainty:Emerging national legislation around mercenary activity creates operational legality risk across multiple deployment jurisdictions.
Strategic Opportunities
- Risk Intelligence Platforms:Predictive threat assessment capabilities differentiate service offerings and command premium pricing in diplomatic protection segments.
- Aviation Maintenance Integration:Combined air and ground logistics capabilities open government contingency theater contracts beyond pure security provision.
- Consolidated Training Infrastructure:Centralized certification facilities reduce per-contractor compliance costs while accelerating deployment readiness.
Industry Challenges
- Specialized Personnel Scarcity:Military and law enforcement veterans with active security clearances represent a finite talent pool with competing demand from government re-employment.
- Cross-Jurisdictional Compliance Complexity:Simultaneous adherence to US ITAR, UK Foreign Office certification, and host-nation mercenary laws fragments legal oversight.
- Working Capital Intensity:Long-term deployment models require upfront personnel mobilization and equipment positioning before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Military Security Services Market |
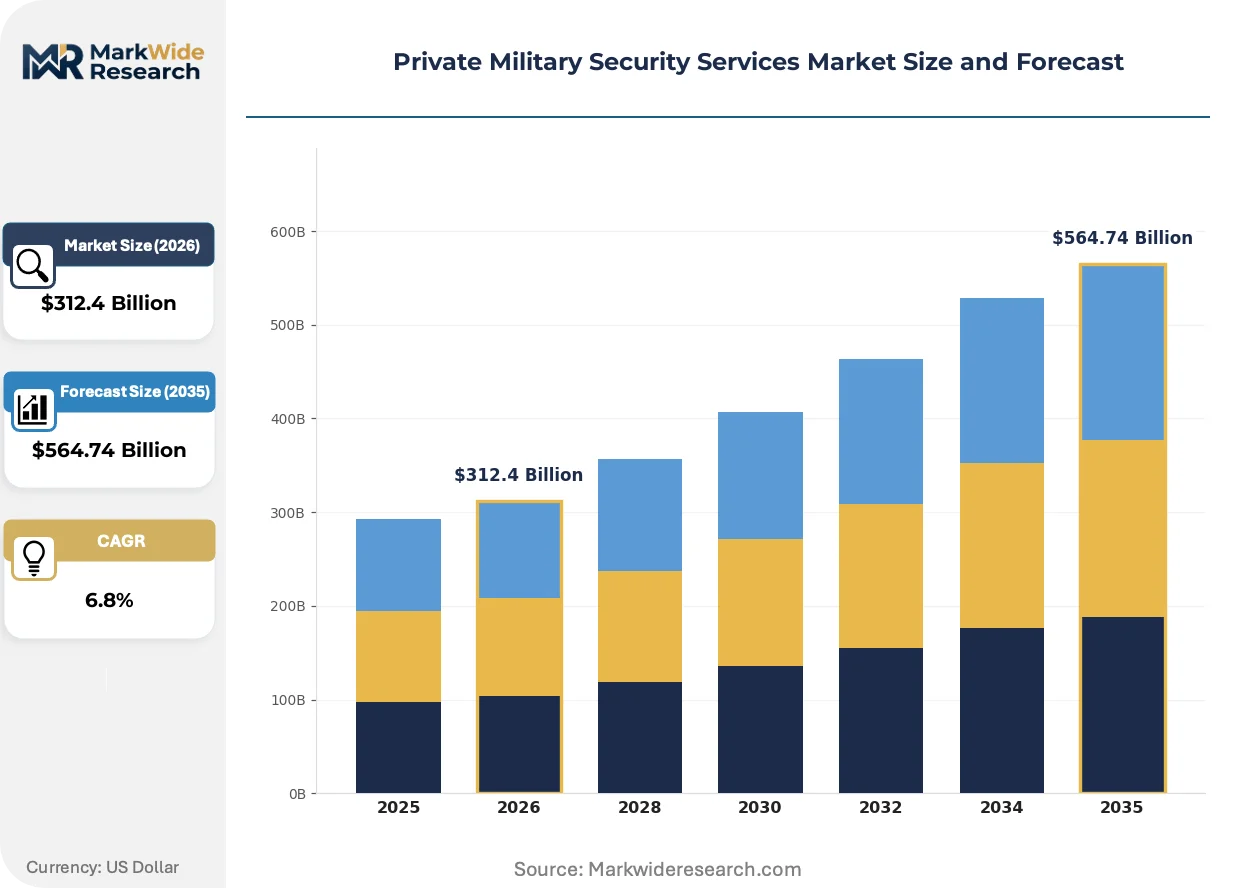
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Logistics, Training, Tactical Client Type: Government, Corporations, NGOs, Individuals Deployment Model: Onshore, Offshore, Rapid Response, Long-term Contract Operational Area: Urban, Rural, Conflict Zones, Protected Areas |
| Companies Covered | DynCorp, Aegis Defence Services, G4S, MAG Aerospace, KBR, Inc., Academi, Northrop Grumman, AKE Group, Constellis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Military Security Services Market Emerging Trajectories
Technology integration is reshaping how protective services are delivered, with digital platforms compressing the value chain between threat detection and armed response while regulatory convergence forces standardization across historically fragmented national frameworks.
Unmanned aerial surveillance systems is consolidating tactical reconnaissance capabilities previously performed by human patrols. Government clients in contingency theaters are adopting drone-supported convoy protection at accelerated procurement cycles. This consolidation is compressing headcount requirements per contract while elevating technical operator skill premiums.
The UK Foreign, Commonwealth and Development Office certification scheme under the 2001 International Code of Conduct is tightening operational accountability standards. Firms must now document use-of-force protocols and incident reporting chains to maintain licensing eligibility. European diplomatic missions are extending these requirements to subcontractor networks, forcing cascade compliance investments.
Fixed-price multi-year service agreements are displacing cost-plus reimbursement structures in government contracting. Defense and State Department procurement officers are transferring performance risk to contractors while demanding guaranteed availability metrics. This shift is most visible in US overseas contingency arrangements, where penalty clauses for non-deployment now accompany base contract awards.
Private Military Security Services Market Segmentation
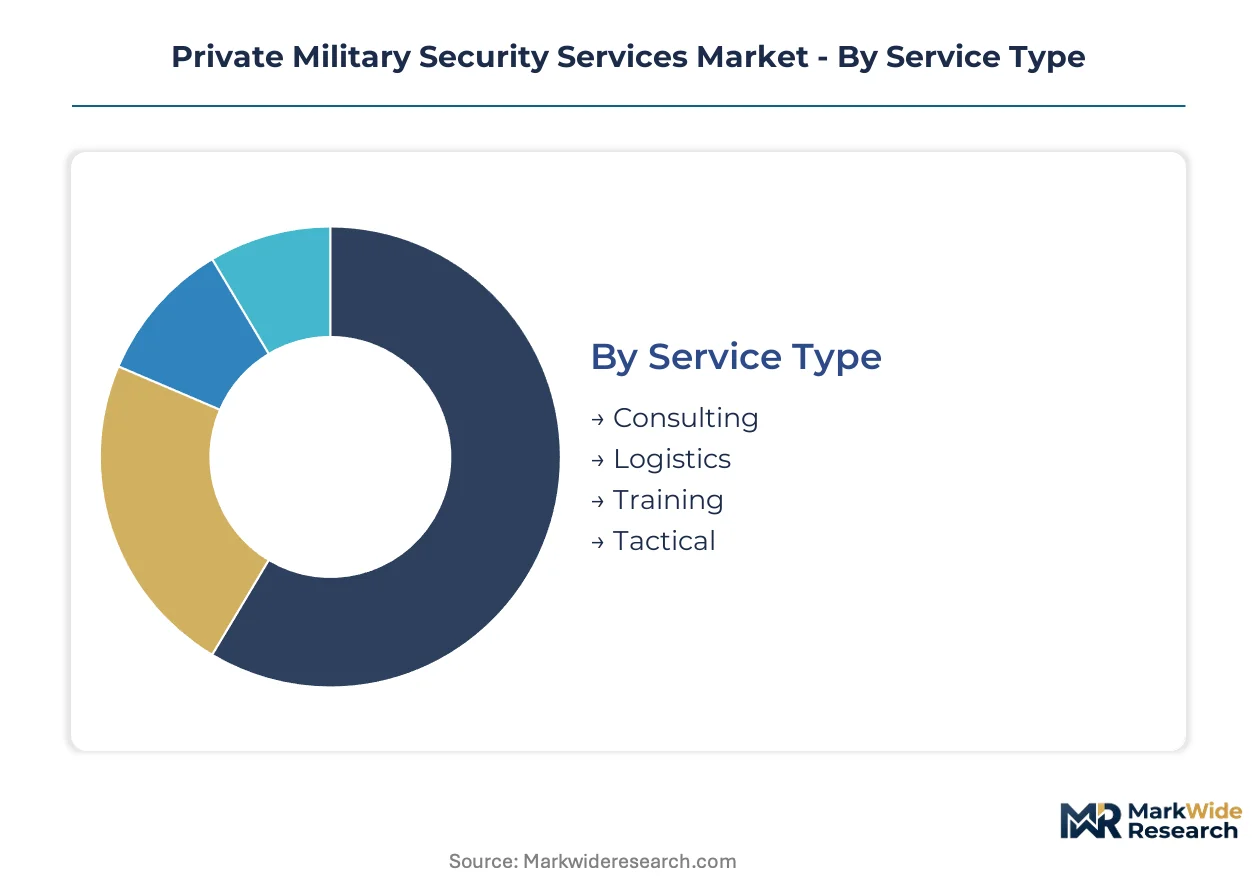
Segmentation in private military security services reveals how contract structures, client risk profiles, and operational environments create distinct capability requirements and margin profiles. Each dimension shapes procurement standards, personnel vetting intensity, and regulatory compliance burdens differently.
Service Type:
Service type segmentation tracks how military-grade capabilities translate into commercial offerings, with upgrade cycles driven by threat evolution and client technology refresh demands.
- Consulting:Risk assessment and security planning services delivered by former intelligence and special operations personnel. Demand concentrates in extractive industry pre-entry evaluations for operations in Iraq and Yemen, where advance threat mapping determines insurance and investment viability.
- Logistics:Integrated supply chain and aviation maintenance support extending beyond armed protection into theater sustainment. US State Department contingency contracts in the Middle East drive adoption, where combined air-ground capabilities reduce vendor management complexity.
- Training:Vetting and certification programs for local security forces and corporate protective details. EU corporate human rights due diligence mandates expand contractable scope for extractive zone preparation.
- Tactical:Armed site defense, convoy protection, and direct response operations requiring active security clearances. Premium margins attach to conflict zone deployments where ITAR compliance restricts eligible providers.
Tactical services sit at the top of the volume ranking, with logistics climbing the fastest as government clients consolidate vendor relationships.
Client Type:
Client segmentation reflects divergent procurement sophistication, with government channels demanding multi-year availability guarantees while commercial buyers prioritize flexible mobilization.
- Government:Embassy protection, overseas contingency, and diplomatic mission security contracted through defense and state departments. US ITAR licensing frameworks privilege American-registered firms, creating protected demand channels with predictable revenue streams.
- Corporations:Mining, energy, and infrastructure operators requiring site defense and executive protection in volatile regions. EU human rights due diligence mandates harden vetting requirements for extractive industry security contractors.
- NGOs:Humanitarian and development organizations operating in insecure environments with constrained budgets. Demand clusters in rapid response mobilization rather than long-term static deployments.
- Individuals:High-net-worth personal protection and family security services, typically unarmed or low-profile. Premium pricing attaches to discreet operations in urban centers with established legal frameworks.
Government contracts dominate absolute revenue, with corporate security services gaining share fastest as extractive investment returns to conflict-affected regions.
Deployment Model:
Deployment structure determines working capital intensity and revenue recognition timing, with contract duration directly correlating to personnel retention and equipment amortization strategies.
- Onshore:Domestic operations within the client's home country jurisdiction, typically involving lower regulatory complexity and unarmed or limited-arm protocols. Stable demand from corporate headquarters protection and critical infrastructure defense.
- Offshore:International deployment to client operations abroad, requiring multi-jurisdictional compliance and often armed capabilities. ITAR and UK Foreign Office certification schemes constrain eligible providers.
- Rapid Response:Short-notice mobilization for crisis evacuation, site reinforcement, or emergency extraction. Premium pricing reflects personnel standby costs and accelerated deployment logistics.
- Long-term Contract:Multi-year arrangements with guaranteed availability metrics and penalty clauses for non-deployment. US overseas contingency arrangements increasingly favor fixed-price structures transferring performance risk to contractors.
Long-term contracts anchor revenue predictability, with rapid response commanding the steepest expansion trajectory as geopolitical volatility accelerates client demand for crisis mobility.
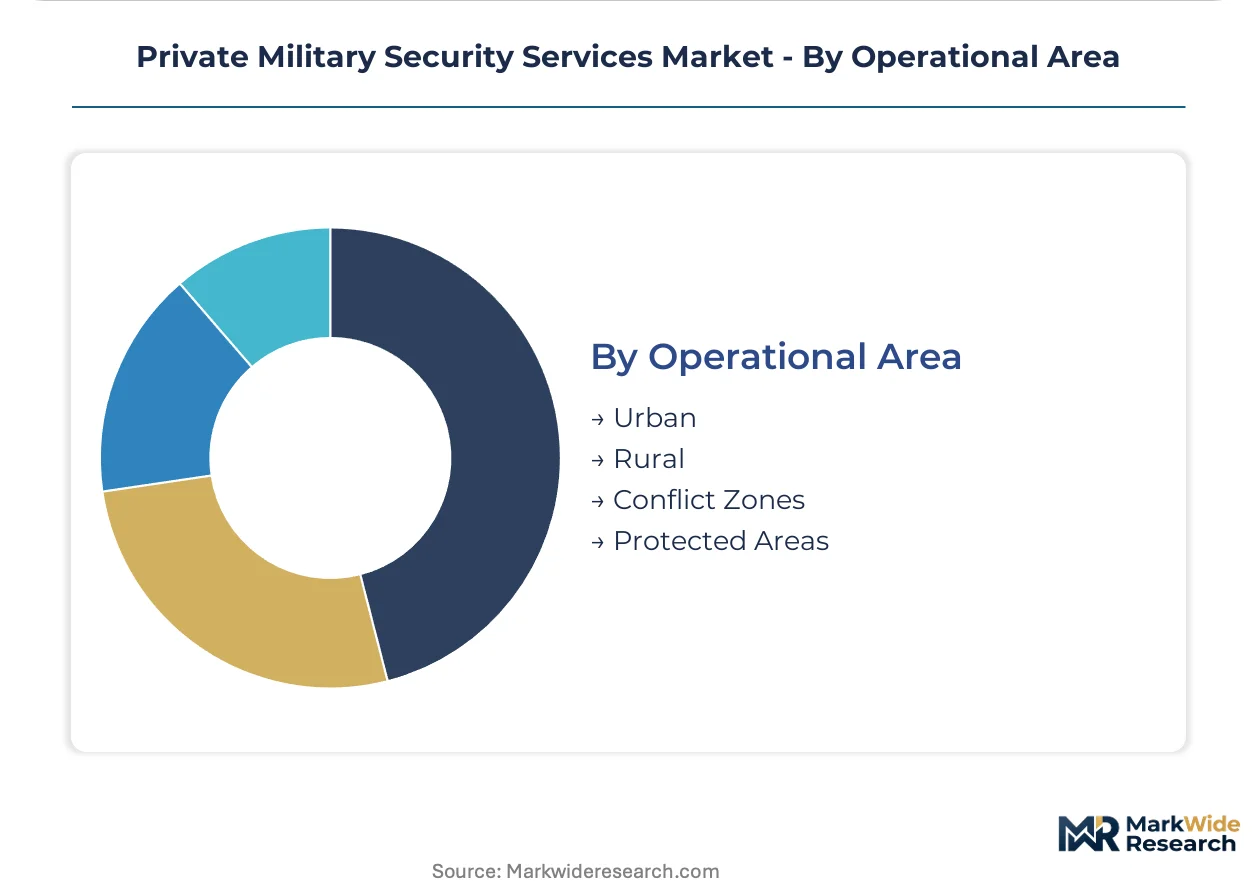
Operational Area:
Geographic operating environment shapes threat profiles, equipment requirements, and legal risk exposure, with each terrain category demanding specialized tactical adaptation.
- Urban:Dense population center operations requiring low-profile techniques and local law enforcement coordination. Corporate headquarters and diplomatic compound protection concentrate demand in capital cities.
- Rural:Remote site defense for pipelines, mining installations, and agricultural operations with extended supply lines. Extractive industry contracts in isolated regions sustain deployment models.
- Conflict Zones:Active hostilities environments including Iraq and Yemen where armed response protocols apply and casualty risk elevates personnel costs. Government contingency contracting dominates this segment.
- Protected Areas:Conservation and heritage sites requiring anti-poaching and asset protection with restricted rules of engagement. NGO and government park authority contracts populate this niche.
Conflict zones generate the highest contract values per deployment, with urban protective services expanding most quickly as corporate security spending professionalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The private military security services industry traces its modern commercial lineage to post-Cold War contingency contracting, with operational scale first achieved through US government overseas engagements. This foundation established procurement frameworks that now structure demand across multiple national jurisdictions.
United States
US State Department embassy protection contracts and Pentagon contingency theater arrangements sustain the largest national market. The Directorate of Defense Trade Controls administers ITAR licensing that restricts foreign ownership in American-registered security firms. Virginia-based contractors cluster around Washington DC procurement corridors, securing multi-year fixed-price agreements with guaranteed availability clauses.
United Kingdom
UK Foreign Office certification under the 2001 International Code of Conduct shapes operational standards for diplomatic mission security. London-headquartered firms leverage historical Commonwealth relationships to secure extractive industry contracts in African and Middle Eastern conflict zones. The certification scheme tightens use-of-force documentation requirements across subcontractor networks.
Iraq
Sustained instability sustains tactical deployment demand for armed convoy protection and static site defense. Host-nation regulatory frameworks remain fragmented alongside international contractor oversight. Baghdad and Basra corridor operations concentrate contract value for logistics-integrated security providers.
Yemen
Protracted conflict generates rapid response and long-term contract deployment opportunities for humanitarian protection and government contingency support. Saudi and UAE contracting channels dominate procurement flows. Aden and Hodeidah operational zones exhibit elevated personnel risk premiums.
Germany
EU corporate human rights due diligence mandates harden vetting requirements for security contractors serving German extractive multinationals. The Supply Chain Due Diligence Act imposes liability for subcontractor compliance failures. Industrial security demand clusters around Frankfurt corporate headquarters and Rhine-Ruhr energy infrastructure.
Private Military Security Services Market Vendor Landscape
Premium-margin players sit above commodity-margin players across compliance certification and integrated capability dimensions. The vendor base concentrates among American and British firms holding ITAR or Foreign Office credentials, with tiered differentiation between tactical specialists and logistics-integrated providers. Two strategic archetypes dominate: risk intelligence platform operators commanding diplomatic protection premiums, and aviation maintenance integrators securing theater sustainment contracts. Consolidation through acquisition and backward integration into training infrastructure represent the primary competitive moves.
Within the logistics-integrated tier, DynCorp exemplifies combined air-ground capability positioning, while Constellis occupies a central position in protective services consolidation. Aegis Defence Services anchors the risk intelligence differentiation vector. These three firms represent distinct strategic postures within a procurement environment that privileges multi-year government relationships and certified compliance infrastructure.
| Leading Market Players |
|---|
| DynCorp |
| Aegis Defence Services |
| G4S |
| MAG Aerospace |
| KBR, Inc. |
| Academi |
| Northrop Grumman |
| AKE Group |
| Constellis |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists dominate the competitive landscape, concentrating contract awards among consolidated training infrastructure owners while compressing pricing discipline through scale-based procurement leverage against smaller tactical providers.
Pricing Analysis
Fixed-price multi-year service agreements anchor contract structures across diplomatic protection and contingency theater segments. Premium-mid-economy pricing differentiation separates ITAR-certified providers from uncertified competitors, with compliance grade and personnel clearance level as primary price drivers. Cost compression in rapid response tiers intensifies as standby personnel expenses outpace contract frequency. Government channels exhibit lowest price sensitivity due to mission-critical requirements, while NGO clients face acute budget constraints.
Supply Chain Analysis
Veteran talent pools in the United States, United Kingdom, and South Africa feed specialized personnel pipelines for conflict zone deployments. Active security clearances, military-grade equipment, and aviation maintenance capabilities constitute critical input dependencies. Single-source vulnerability concentrates in cleared personnel recruitment, where competing government re-employment drains finite supply. Distribution runs through prime contractor relationships with State Department and Foreign Office procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private military security services constitute a late-cycle quality story, with demand shifting toward predictive threat intelligence platforms that command sustained premium pricing in diplomatic protection segments.
For Market Incumbents: Acquire risk intelligence platform capabilities to counter technology-driven entrants. Consolidate backward integration into centralized training infrastructure, reducing per-contractor compliance costs while accelerating deployment readiness. Defensive positioning requires locking multi-year ITAR-privileged government relationships before certification requirements tighten further. For New Entrants and Emerging Players: Enter via rapid response mobilization services for underpenetrated NGO humanitarian channels, where budget constraints favor flexible short-notice contracts over incumbent long-term structures. Target corporate extractive industry security planning in German-headquartered multinationals facing EU due diligence liability exposure. Lead with subscription-based risk assessment consulting to establish credentialing before tactical service expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among logistics-integrated providers lacking aviation maintenance differentiation, where government theater sustainment contracts offer defensive revenue visibility. Long-term viability centers on multi-jurisdictional compliance infrastructure that resists regulatory fragmentation. Watch for ITAR ownership threshold relaxation as signal for cross-border consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Risk Intelligence Platform | Predictive threat capabilities differentiate diplomatic protection bids from commodity tactical providers. |
| Consolidated Training Infrastructure Buildout | Centralized certification reduces EU due diligence compliance costs for extractive industry contracts. |
| Aviation Maintenance Integration | Combined air-ground logistics secures State Department contingency theater awards beyond pure security. |
| Rapid Response Capability Investment | Standby personnel pools capture NGO humanitarian evacuation demand with premium crisis pricing. |
| ITAR Certification Pathway Acceleration | Foreign ownership compliance unlocks protected US government embassy protection contract channels. |
Methodological Framework
Direct dialogue with government procurement officers, security firm operations directors, extractive industry risk managers, and diplomatic mission facility managers grounded qualitative assessment, cross-referenced against ITAR licensing databases, UK Foreign Office certification registries, EU corporate due diligence filings, and contingency theater contract award records. Bottom-up personnel deployment estimates and top-down government spending allocations were triangulated to anchor market sizing.
Segment-level outputs across service type, client category, deployment model, and operational geography were generated through the projection horizon. CAGRs were derived from contract renewal velocity and procurement budget trajectories, incorporating Middle East theater sustainment patterns and EU regulatory compliance cost inflation as industry-specific inputs.
Inputs from classified government procurement channels were available through the study window; gaps in real-time contract value disclosure introduce uncertainty bands around tactical deployment estimates. Forecasts reflect documented assumptions regarding ITAR enforcement continuity and host-nation mercenary law stability. Material deviation in US-UK regulatory convergence or Middle East conflict intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Prison Management Systems Market
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
Lawful Interception Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Latin America Security Services Market
Security and Surveillance
Smart Security Market
Security and Surveillance
Smart Security in Healthcare Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Global Police and Law Enforcement Equipment Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Asia-Pacific Security Services Market