
 Regenerative Therapies Market | 2026-2036
Regenerative Therapies Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerative Therapies Market Intelligence
Personalized treatment planning software is hardening the link between therapeutic delivery and long-term patient outcome monitoring. This shift benefits companies with integrated diagnostic and therapeutic platforms. Novartis AG leverages its deep expertise in cell and gene therapy manufacturing to maintain a competitive edge. Stryker specializes in orthopedic applications, aligning its regenerative products with its established surgical device portfolio.
Regenerative therapies encompass a range of advanced medical treatments designed to repair, replace, or regenerate human cells, tissues, or organs. These therapies often utilize biological materials, such as living cells or their components, to restore normal function lost due to disease, injury, or aging. Stem cell therapy and tissue engineering currently dominate the product landscape due to extensive research and clinical validation. Within applications, orthopedics represents a mature segment, while neurological repair is an area of high-growth potential.
Market access is governed by stringent regulatory frameworks, including the U.S. FDA's RMAT designation and the European Medicines Agency's PRIME scheme. These programs, along with Japan's PMDA regulations for regenerative products, shape clinical trial requirements and commercialization timelines. Stakeholders must now decide how to balance rapid innovation with the complex, evolving demands of global regulatory harmonization and reimbursement.
Market Dynamics
Accelerated regulatory pathways are the central force shaping the market, with frameworks like the U.S. FDA's RMAT designation fundamentally altering development timelines and investment priorities for companies pursuing novel cell and gene therapies.
Growth Catalysts
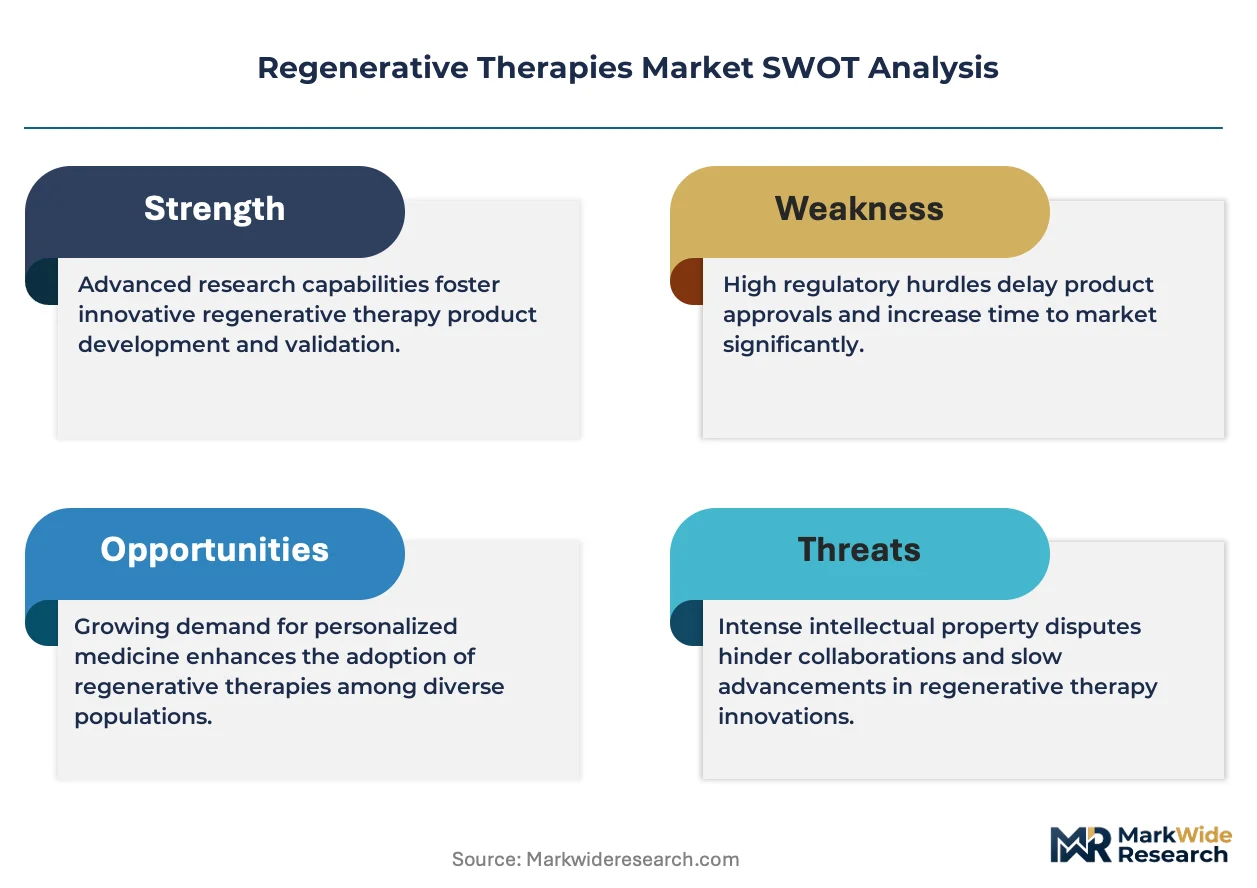
- Accelerated Regulatory Pathways:Programs such as the FDA's RMAT designation and the EMA's PRIME scheme reduce clinical development timelines, encouraging investment in novel therapies by providing a clearer and faster route to market.
- Orthopedic Applications:The pronounced need for joint and cartilage repair solutions, driven by sports injuries and an aging population, creates a large and established patient pool for clinically validated regenerative treatments.
- Demographic Shifts:An aging population in developed nations, particularly the United States and Japan, is increasing the prevalence of degenerative diseases, directly expanding the addressable market for restorative therapies.
Market Restraints
- Reimbursement Complexity:High upfront costs for regenerative therapies face significant resistance from payers, with inconsistent and complex reimbursement policies across different healthcare systems acting as a major barrier to patient access.
- Manufacturing Scalability:The production of patient-specific autologous cell therapies is logistically complex and difficult to scale, creating a significant bottleneck that limits treatment availability and increases cost.
- Regulatory Divergence:A lack of global regulatory harmonization between bodies like the FDA, EMA, and Japan's PMDA creates duplicative requirements and administrative hurdles for companies seeking international market approval.
Strategic Opportunities
- Neurological Repair:While orthopedics is a mature segment, developing therapies for neurodegenerative diseases like Parkinson's or for spinal cord injury represents a significant area of untapped clinical and commercial opportunity.
- AI in Treatment Planning:The integration of artificial intelligence with diagnostic imaging offers a pathway to create highly personalized treatment planning software, improving therapeutic precision and long-term outcome monitoring.
- Emerging Market Expansion:Establishing clinical trial sites and commercial operations in Asia-Pacific countries with modernizing regulatory frameworks provides an opportunity to access new patient populations and diversify geographic revenue.
Industry Challenges
- Specialized Talent Shortage:A critical lack of skilled personnel in bioprocessing, cell therapy manufacturing, and regulatory affairs impedes the ability of companies to scale operations and navigate complex approval processes.
- Standardization Deficits:The absence of universally accepted standards for cell sourcing, characterization, and potency assays creates variability in product quality and complicates the comparison of data across clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerative Therapies Market |
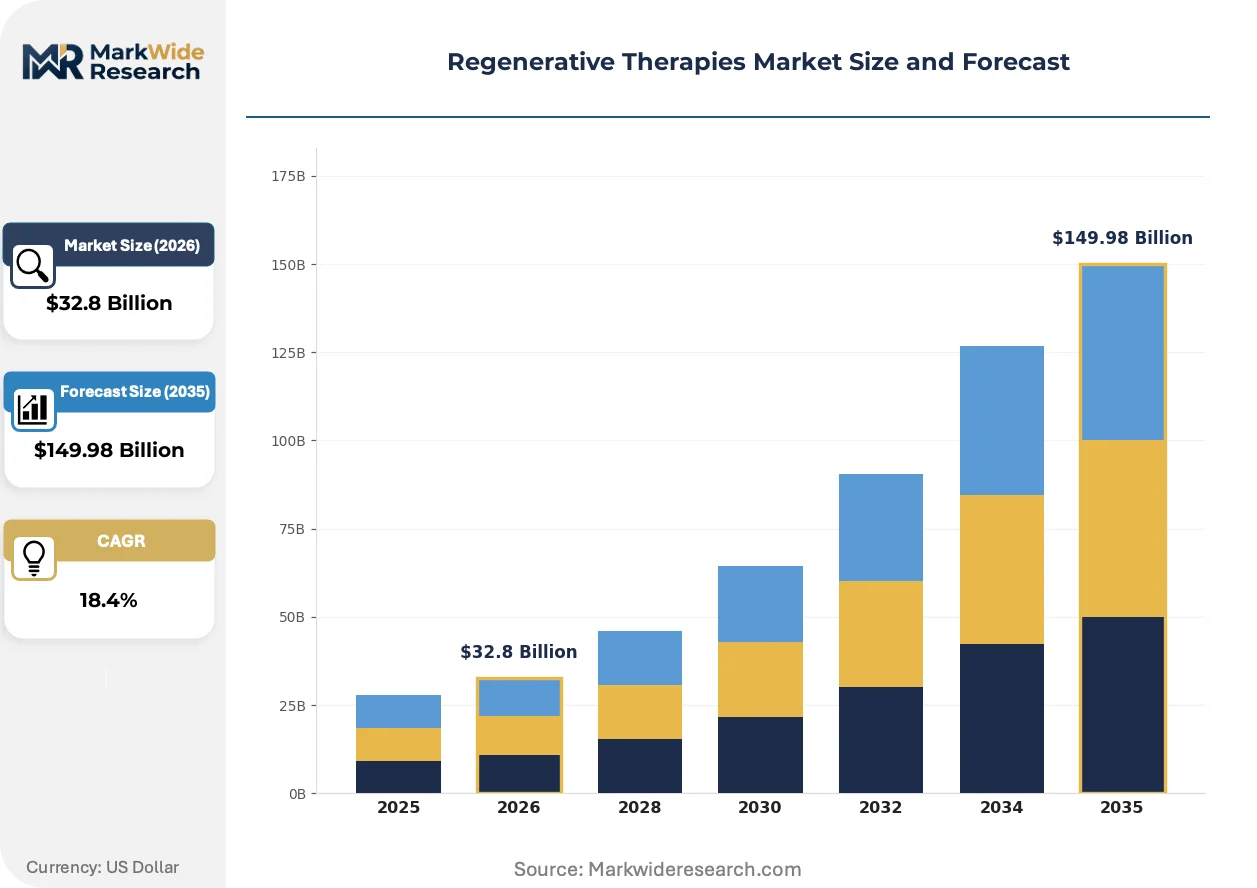
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $149.98 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stem Cell Therapy, Tissue Engineering, Gene Therapy, Platelet-Rich Plasma, Extracellular Vesicles Application: Orthopedics, Cardiovascular Repair, Neurological Repair, Wound Healing, Burn Treatment End User: Research Institutes, Biotechnology Firms, Pharmaceutical Companies, Specialized Clinics, Rehabilitation Centers Delivery Mode: Injectables, Scaffold-Based, Cell Suspension, Gene Delivery Systems, Topical Formulations |
| Companies Covered | Novartis AG, Medtronic, AbbVie Inc., Pfizer Inc., Integra LifeSciences Corporation, Stryker, Bristol-Myers Squibb, Thermo Fisher Scientific Inc., Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerative Therapies Market Strategic Shifts & Innovations
Industrialization of cell and gene therapy manufacturing is converging with data-driven personalization. This shift is redefining therapeutic development from bespoke laboratory processes into scalable, commercially viable clinical solutions with predictable outcomes.
Allogeneic stem cell therapies, designed as "off-the-shelf" products, offer scalable manufacturing and immediate availability for treatment. Biopharmaceutical firms and large hospital systems are investing in allogeneic platforms to overcome the logistical challenges of patient-specific approaches. This off-the-shelf model is overtaking the autologous model in high-volume applications, compressing treatment timelines and reducing per-patient costs.
The European Medicines Agency's PRIME scheme provides enhanced scientific and regulatory support for developers of innovative medicines. This framework facilitates earlier and more frequent dialogue with regulators, helping to optimize clinical trial design for advanced therapy medicinal products (ATMPs). Developers targeting rare diseases are particularly affected, leveraging the program to accelerate their path to the European Union market.
A shift toward value-based healthcare models is tying reimbursement for regenerative therapies to documented long-term patient outcomes. This focus moves the financial evaluation from the high initial procedure cost to the total cost of care over time, disrupting traditional fee-for-service payment structures. This trend is most visible within specialized orthopedic clinics in the United States, where payers and providers collaborate on tracking post-treatment results.
Regenerative Therapies Market Segmentation
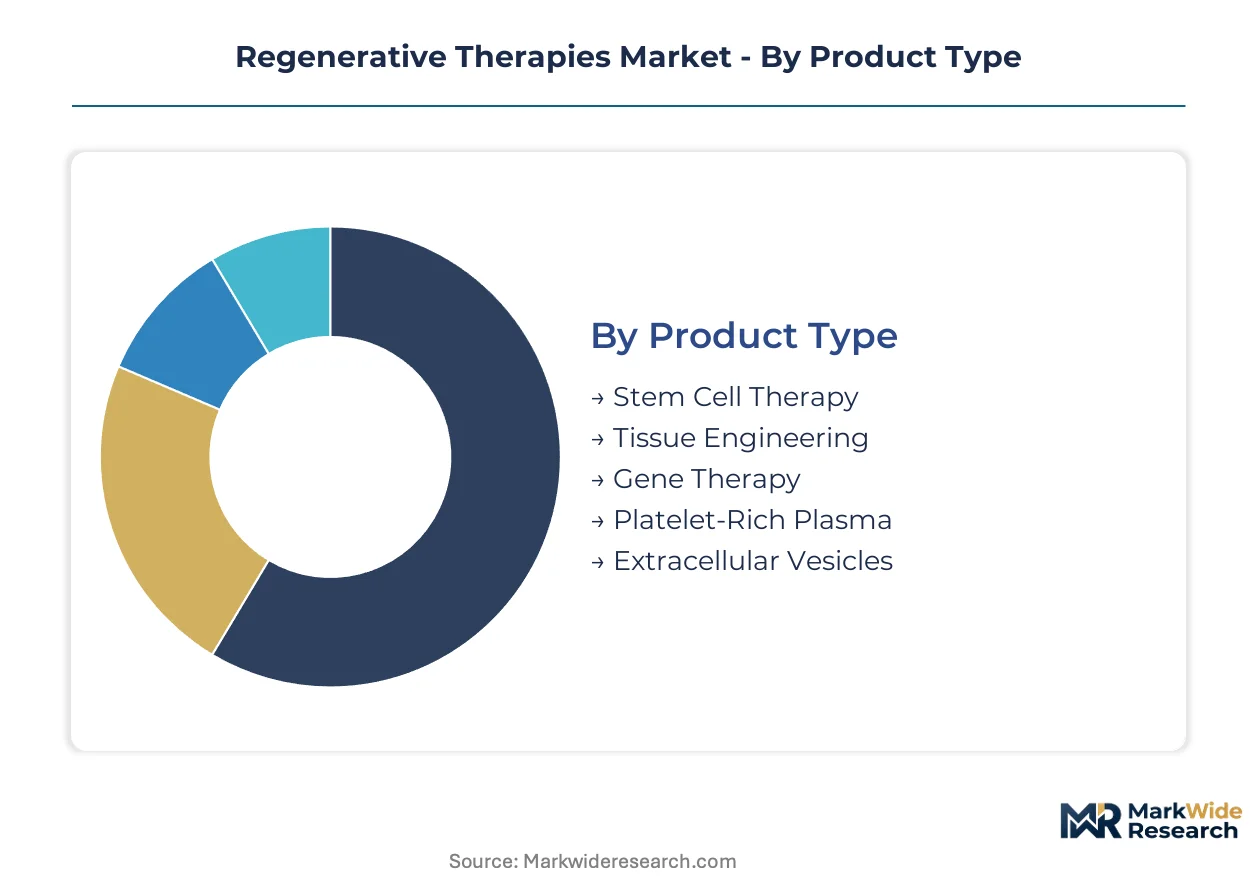
Understanding the Regenerative Therapies Market through segmentation reveals how diverse product types, applications, and end-user requirements shape demand. This detailed classification helps stakeholders identify specific growth pockets and tailor strategic investments for maximum impact. Each category highlights distinct commercial pathways and technological dependencies within the broader market.
Product Type:
Buyers in the regenerative therapies market differentiate their product choices based on the underlying biological mechanism and complexity of the therapeutic approach.
- Stem Cell Therapy:This product type involves using undifferentiated cells with self-renewal and differentiation capabilities to repair or replace damaged tissues. Demand concentrates within specialized clinics in the United States, driven by research and clinical validation in orthopedic and neurological applications.
- Tissue Engineering:This field combines scaffolds, cells, and biologically active molecules to create functional tissues for medical purposes, replacing or enhancing biological function. Orthopedic applications, particularly for joint and cartilage repair, represent a significant area of demand, benefiting from established surgical device portfolios.
- Gene Therapy:This approach modifies or introduces genetic material into a patient's cells to treat or prevent disease, often targeting inherited disorders or certain cancers.
- Platelet-Rich Plasma:Derived from a patient's own blood, this concentrated plasma contains growth factors that promote healing and is widely used in musculoskeletal injury treatment.
- Extracellular Vesicles:These nanovesicles, including exosomes, mediate cell-to-cell communication and are explored for their therapeutic potential in tissue repair and regeneration.
Volume sits with Stem Cell Therapy; growth tilts toward Gene Therapy.
Application:
Application choices are often dictated by the specific medical need and target organ system requiring restoration.
- Orthopedics:This segment focuses on repairing and regenerating musculoskeletal tissues, including cartilage, bone, ligaments, and tendons, addressing sports injuries and degenerative conditions. The pronounced need for joint and cartilage repair solutions creates a large, established patient pool.
- Neurological Repair:This area targets the regeneration of damaged nervous system tissues, including spinal cord injuries and neurodegenerative diseases like Parkinson's. This segment represents a significant area of untapped clinical and commercial opportunity.
- Cardiovascular Repair:Therapies in this category aim to restore heart muscle function or blood vessel integrity, often after ischemic events or congenital defects.
- Wound Healing:Regenerative approaches accelerate the closure and improve the quality of chronic or acute wounds, leveraging cells or growth factors to enhance tissue regeneration.
- Burn Treatment:These therapies focus on regenerating skin and underlying tissues damaged by severe burns, often utilizing tissue-engineered skin substitutes or cellular grafts.
Demand for regenerative therapies varies significantly by application area, with established clinical pathways in some segments and nascent opportunities in others.
End User:
The end-user landscape for regenerative therapies reflects the diverse institutional settings involved in research, development, and clinical deployment.
- Biotechnology Firms:These companies specialize in the research, development, and commercialization of novel biological products, including cell and gene therapies. Novartis AG leverages its deep expertise in cell and gene therapy manufacturing to maintain a competitive edge.
- Specialized Clinics:These healthcare facilities focus exclusively on delivering regenerative treatments, often for specific conditions like orthopedic injuries or chronic pain. Demand is concentrating within these clinics in the United States, driven by an aging population.
- Research Institutes:Academic and non-profit organizations conduct fundamental and translational research into regenerative medicine principles and applications.
- Pharmaceutical Companies:Large pharmaceutical firms increasingly invest in regenerative therapies, integrating them into broader treatment portfolios through acquisitions or internal development.
- Rehabilitation Centers:These facilities integrate regenerative treatments with physical therapy and other rehabilitative services to optimize patient recovery and functional outcomes.
Specialized clinics and biotechnology firms drive much of the market's commercial activity, while research institutes underpin foundational advancements.
Delivery Mode:
Delivery mode selection is critical for ensuring therapeutic efficacy and patient safety, influencing both product design and clinical protocols.
- Injectables:These involve direct administration of therapeutic cells or biological agents into the target tissue or bloodstream using syringes or catheters. Injectables offer broad applicability and minimally invasive delivery for many regenerative treatments.
- Gene Delivery Systems:These specialized vectors, often viral or non-viral, transport genetic material into target cells to achieve therapeutic protein expression or gene correction. These systems are gaining share for their targeted cellular modifications.
- Scaffold-Based:This mode uses biomaterial structures to provide mechanical support and a suitable environment for cell attachment, proliferation, and tissue formation.
- Cell Suspension:Therapeutic cells are prepared in a liquid medium for direct transplantation into the body, allowing for even distribution within a target area.
- Topical Formulations:These involve applying regenerative agents directly to the skin surface for localized treatment of wounds, burns, or dermatological conditions.
Injectable formats offer broad applicability, while gene delivery systems are gaining share for their targeted cellular modifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston-Cambridge, Massachusetts, stands as a prominent hub for regenerative therapies, driving significant advancements in biotech research and clinical development. This cluster benefits from a dense network of academic institutions, specialized clinics, and pharmaceutical companies. Demand for these innovative treatments is expanding across key global markets, influenced by diverse demographic shifts and regulatory environments.
United States
An aging population and the high incidence of sports injuries fuel the demand for regenerative therapies in the United States. The U.S. FDA's Regenerative Medicine Advanced Therapy (RMAT) designation accelerates clinical development pathways for novel treatments. Major research universities and biotech firms in the San Francisco Bay Area actively pursue stem cell and gene therapy breakthroughs.
Germany
Germany's robust healthcare infrastructure and high prevalence of degenerative diseases contribute to strong demand for orthopedic regenerative solutions. The European Medicines Agency's (EMA) PRIME scheme supports expedited review for advanced therapy medicinal products (ATMPs). The Munich biotech cluster is a center for academic research and clinical trials in tissue engineering.
Japan
Japan's rapidly aging population creates a significant patient pool for restorative therapies, particularly in neurological and orthopedic applications. The country's PMDA regulations for regenerative products provide a clear framework for market approval. Kyoto remains a global leader in induced pluripotent stem cell (iPSC) research and clinical application development.
United Kingdom
The United Kingdom sees sustained demand for regenerative treatments in both established orthopedic segments and emerging neurological repair. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees the approval and monitoring of advanced therapies. London's vibrant biotech scene fosters numerous startups and research institutions focused on cell and gene therapy innovation.
China
China presents a vast addressable market for regenerative therapies, driven by its large population and increasing investment in healthcare infrastructure. The National Medical Products Administration (NMPA) is streamlining regulatory pathways for innovative biological products. Shanghai's numerous biotech parks are becoming key centers for manufacturing and clinical research in regenerative medicine.
Regenerative Therapies Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the regenerative therapies market, creating a tiered competitive structure. The market sees a mix of large pharmaceutical firms, specialized biotechnology companies, and established medical device manufacturers. Strategic partnerships and significant R&D investments are dominant competitive moves among industry participants.
At the scale-driven end of the market, Novartis AG exemplifies a large pharmaceutical firm leveraging deep expertise in cell and gene therapy manufacturing. Pfizer Inc. also occupies a position among major players, integrating regenerative medicine into broader treatment portfolios through internal development. Stryker represents a medical device specialist, aligning regenerative products with its established orthopedic surgical device portfolio.
| Leading Market Players |
|---|
| Novartis AG |
| Medtronic |
| AbbVie Inc. |
| Pfizer Inc. |
| Integra LifeSciences Corporation |
| Stryker |
| Bristol-Myers Squibb |
| Thermo Fisher Scientific Inc. |
| Smith & Nephew plc |
| Others |
Cost & Logistics Intelligence
Venture-capital-funded biotech specialists, driven by the need for high returns, influence both supply behavior and the premium pricing observed in the regenerative therapies market. This dynamic reflects significant upfront R&D investments and the specialized nature of raw material sourcing and manufacturing.
Pricing Analysis
Value-based pricing, tied to documented long-term patient outcomes, increasingly anchors reimbursement for regenerative therapies. Pricing models often combine an initial procedure cost with performance-based payments. Price differentiation stems from clinical validation, the degree of customization for patient-specific treatments, and the specific regulatory approvals achieved. Pricing pressure stems from the high R&D costs and specialized manufacturing requirements. Payers exhibit high price sensitivity due to significant upfront costs, while patients with chronic or debilitating conditions often show lower sensitivity.
Supply Chain Analysis
The availability of specialized talent in bioprocessing and cell therapy manufacturing drives supply chain concentration in key geographic hubs. These include the United States, particularly Boston-Cambridge, and Germany, with its Munich biotech cluster. The supply chain draws from critical raw materials such as specialized cell lines, viral vectors for gene delivery, and advanced biomaterials for tissue engineering. Manufacturing scalability presents a structural supply chain risk, limiting treatment availability. Distribution channels primarily run through specialized clinics and major hospital systems equipped for advanced therapeutic administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with allogeneic stem cell therapies increasingly displacing patient-specific autologous approaches due to their scalable nature.
For Market Incumbents:Cement leadership in advanced manufacturing techniques for allogeneic therapies, leveraging existing expertise in large-scale bioproduction. Acquire smaller biotech firms with promising clinical assets in neurological repair to counter emerging gene-editing technologies. Invest in regulatory pathway expertise, particularly for RMAT designations, to accelerate market access. Expand capacity in the United States and Germany to meet growing demand.
For New Entrants and Emerging Players:Launch via strategic partnerships with specialized orthopedic clinics or academic research institutions to gain clinical validation and patient access. Target white-space opportunities in neurological repair, leveraging orphan drug designations for faster regulatory pathways. Focus on developing AI-driven personalized treatment planning software as a unique go-to-market angle. Penetrate Asia-Pacific emerging markets with less stringent regulatory environments.
For Investors and Strategic Acquirers:Distressed-cycle entries favor well-capitalized pharmaceutical firms in the United States and Germany, seeking to integrate advanced therapeutic platforms. The long-term viability of this market rests on addressing significant unmet medical needs in an aging population. Target specialized biotech firms with validated clinical assets or unique manufacturing intellectual property. Regulatory approvals for novel allogeneic therapies serve as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up for Allogeneic Therapies | Reduces per-patient costs and expands treatment availability across global markets. |
| Clinical Trial Advancement in Neurological Repair | Unlocks significant untapped commercial opportunities with high unmet patient needs. |
| Integration of AI-Driven Treatment Planning | Enhances therapeutic precision and optimizes long-term patient outcome monitoring. |
| Regulatory Pathway Optimization (RMAT/PRIME) | Accelerates market entry for innovative therapies by streamlining clinical development. |
| Strategic Partnerships in Asia-Pacific | Provides access to new patient populations and diversifies geographic revenue streams. |
Research Approach
ClinicalTrials.gov, U.S. FDA filings, and European Medicines Agency (EMA) submissions formed the secondary backbone for this analysis, complemented by academic research databases. This data was triangulated with primary interviews conducted with cell therapy scientists, regulatory affairs specialists, orthopedic surgeons, and hospital procurement managers. Both bottom-up and top-down approaches ensured comprehensive market sizing and validation.
A bottom-up approach quantified market segments by product type, application, end user, and delivery mode, further segmented by specific disease indications. The forecast framework projected market growth across the analysis window, deriving compound annual growth rates through regression analysis and weighted averages. Clinical trial success rates and the evolution of reimbursement policies served as key industry-specific forecast inputs.
Regulatory policy changes, clinical trial outcomes, and manufacturing breakthroughs are the dominant revision risks for market forecasts. These projections reflect a set of carefully considered assumptions regarding technological adoption and market dynamics. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
Gene Vector Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market