
 Cell Therapy Biomanufacturing Market | 2026-2036
Cell Therapy Biomanufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Therapy Biomanufacturing Market Analysis
GMP-grade vector production is collapsing the gap between clinical-scale and commercial-scale manufacturing. Thermo Fisher Scientific leverages its integrated supply chain to control raw material consistency across viral vector programs. Lonza sustains capacity leadership through dedicated cell therapy suites in strategically located manufacturing hubs. Sartorius AG specializes in single-use bioreactor technologies that reduce cross-contamination risks during patient-specific batch runs.
Cell therapy biomanufacturing encompasses the scalable production of living therapeutic products derived from autologous or allogeneic cell sources, requiring sterile isolation, genetic modification, and cryopreservation at controlled viability thresholds exceeding 80 percent post-thaw. Its primary purpose is to deliver consistent, patient-ready cellular interventions for indications where traditional small-molecule or biologic approaches have failed. Autologous manufacturing occupies the largest revenue share due to established CAR-T commercialization, while allogeneic platforms represent the fastest-expanding segment as off-the-shelf therapies promise reduced vein-to-vein timelines. Contract Manufacturing Organizations capture concentrated margin pools as biopharmaceutical companies outsource capital-intensive cleanroom infrastructure rather than building captive facilities.
FDA guidance on chemistry, manufacturing, and controls for gene therapy products shapes facility design standards and batch release protocols across the United States. EMA's ATMP classification and the EU GMP Annex 2 revisions dictate viral vector qualification requirements and environmental monitoring specifications for European market access. Japan's PMDA regenerative medicine framework accelerates conditional approval pathways while enforcing stringent donor cell traceability standards. Stakeholders must monitor evolving comparability guidelines as process analytical technology replaces end-point testing in real-time release strategies.
Market Dynamics
Process analytical technology is compressing batch release timelines from weeks to days, forcing facility retrofits and real-time data infrastructure investments across commercial manufacturing networks.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase II-to-commercial gaps, pulling forward capacity investments for CAR-T programs targeting earlier oncology lines.
- Electroporation systems:Non-viral gene delivery is displacing lentiviral dependency, reducing vector manufacturing bottlenecks in allogeneic workflows.
- Germany:Cluster concentration around Heidelberg and Leipzig creates specialized labor pools and shared logistics infrastructure for European supply.
Market Restraints
- Plasmid DNA scarcity:GMP-grade plasmid suppliers concentrate in North America, exposing European and Asian programs to cross-border shipment delays and cold-chain failures.
- Cleanroom capex intensity:ISO-7 suite construction runs $15-25 million per 10,000 square feet, locking out mid-tier biopharma from captive manufacturing.
- EMA Annex 2 revisions:Viral vector qualification requirements extend facility qualification timelines by 12-18 months for European market entry.
Strategic Opportunities
- Japan:PMDA's regenerative medicine framework offers conditional approval with reduced Phase III requirements, opening earlier revenue capture for allogeneic platforms.
- Point-of-care manufacturing:Decentralized cleanroom modules at academic medical centers are collapsing vein-to-vein timelines for autologous therapies.
- AI-driven release testing:Machine learning models trained on multi-parameter in-process data are enabling real-time potency assays, replacing end-point analytics.
Industry Challenges
- Cell therapy process engineers:The specialized workforce crosses GMP biologics expertise with immunology and gene editing, creating recruitment bottlenecks in Boston, Basel, and Singapore.
- Legacy MES integration:Paper-based batch records at established biologics facilities resist digitization, slowing PAT deployment and real-time release adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Therapy Biomanufacturing Market |
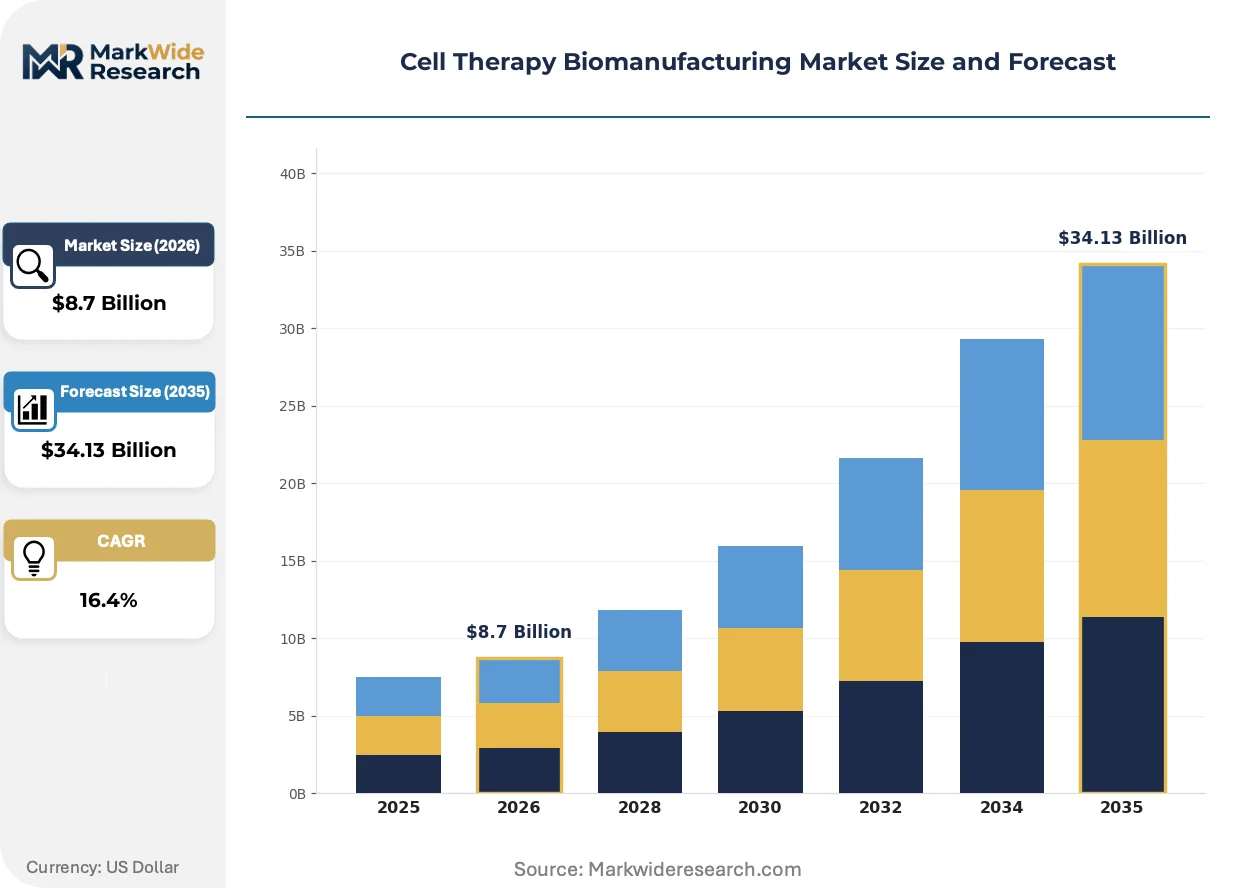
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous, Allogeneic, CAR-T, TCR-T Technology: Transfection, Viral Vector, Electroporation, CRISPR Application: Oncology, Rare Diseases, Autoimmune Disorders, Regenerative Medicine End User: Biopharmaceutical Companies, Research Institutes, Contract Manufacturing Organizations, Hospitals |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Lonza, Sartorius AG, Bio-Techne, Becton, Dickinson and Company, Catalent, Inc, Cytiva, Miltenyi Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Therapy Biomanufacturing Market Emerging Trajectories
Closed-system automation is eliminating open manipulations that previously demanded ISO-5 hoods and extensive environmental monitoring, reshaping facility design economics and contamination risk profiles.
Closed, automated bioreactors with integrated sampling and perfusion control are supplanting static flask cultures and manual media exchanges in commercial-scale manufacturing. CDMOs in Singapore and the Netherlands are adopting these systems to reduce operator-induced variability and expand batch throughput per square foot. The shift is compressing facility footprints by 40-60 percent while raising viable cell density thresholds for harvest.
EMA's ATMP classification and associated GMP Annex 2 revisions are mandating viral vector qualification standards that exceed prior voluntary industry guidelines. European manufacturers must now demonstrate replication-competent virus clearance and extended stability data before batch release. Allogeneic programs with lentiviral-dependent gene editing are most affected, driving investment in alternative non-viral delivery platforms.
Biopharma procurement teams are consolidating supplier relationships from fragmented raw material vendors to integrated supply agreements with full-service CDMOs. Thermo Fisher and Lonza are capturing these consolidated contracts by bundling plasmid, media, and manufacturing services. The pattern is most visible in United States-based oncology programs where sponsor companies lack captive vector production.
Cell Therapy Biomanufacturing Market Segmentation
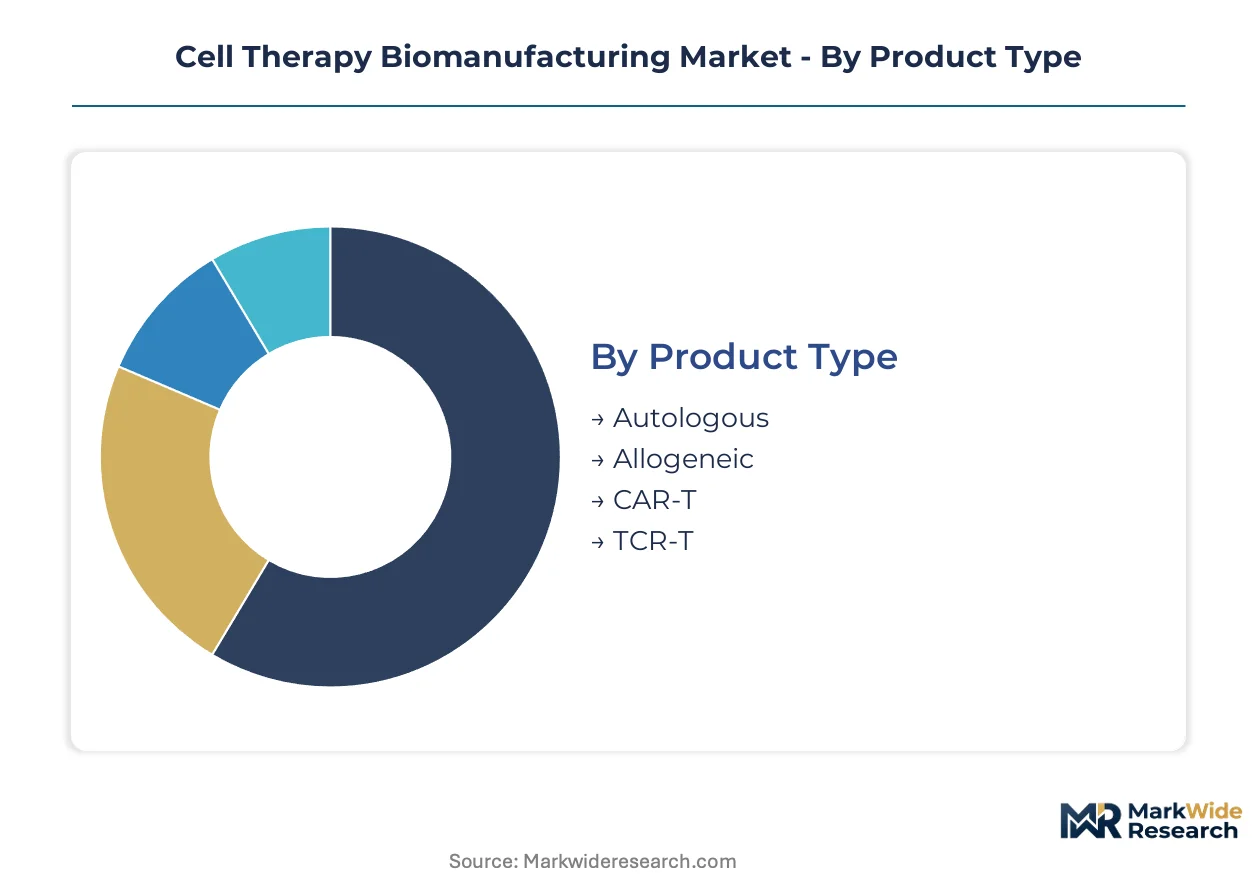
Cell therapy biomanufacturing segments diverge sharply in capital intensity and margin structure. Autologous workflows demand patient-dedicated suites, while allogeneic platforms promise scale economies through batch processing. Understanding these segment economics guides facility investment and partnership strategies.
Product Type:
Margin pools concentrate in autologous manufacturing where vein-to-vein logistics command premium pricing, though allogeneic platforms are capturing investor attention through manufacturing leverage potential.
- Autologous:Patient-specific cell processing requires dedicated cleanroom slots and chain-of-identity tracking systems. Demand clusters in United States academic medical centers running CAR-T programs for hematologic malignancies, constrained by apheresis scheduling bottlenecks and cryogenic logistics costs.
- Allogeneic:Off-the-shelf cell banks enable batch manufacturing from single donor expansions. Japanese and German biotechs are advancing these platforms fastest, drawn by PMDA conditional approval pathways and EMA ATMP fee incentives for smaller patient populations.
- CAR-T:Chimeric antigen receptor protocols dominate commercial revenue.
- TCR-T:T-cell receptor engineering targets solid tumor antigens with higher specificity thresholds.
The dominant share belongs to Autologous, while Allogeneic is closing the gap fastest.
Technology:
Technology selection determines raw material exposure and regulatory pathway complexity, with viral vector approaches carrying higher COGS and qualification burdens than emerging physical delivery methods.
- Viral Vector:Lentiviral and gamma-retroviral systems remain the standard for stable gene integration. United States-based programs depend heavily on Thermo Fisher and Lonza for GMP-grade vector supply, creating single-source vulnerabilities during batch release.
- Electroporation:Non-viral gene delivery via electrical membrane permeabilization eliminates replication-competent virus testing requirements. Singapore CDMOs are adopting these systems aggressively to serve Asia-Pacific allogeneic programs seeking EMA export qualification.
- Transfection:Chemical and lipid-based delivery offers intermediate efficiency for transient expression.
- CRISPR:Ribonucleoprotein complexes enable precise editing without persistent foreign DNA.
Viral Vector retains the largest installed base, though Electroporation is expanding most quickly as allogeneic workflows mature.
Application:
Application focus shapes facility design standards and batch release protocols, with oncology commanding the deepest manufacturing expertise and rare diseases offering regulatory acceleration trade-offs.
- Oncology:Hematologic CAR-T applications drive the majority of commercial manufacturing volume. CDMOs in Germany and the United States have optimized their suites for T-cell selection, activation, and expansion protocols standardized across Novartis and Gilead reference processes.
- Rare Diseases:Ultra-small patient populations justify higher per-dose manufacturing costs. Japan's PMDA regenerative medicine framework and the United States FDA's rare disease priority review vouchers compress development timelines for these programs.
- Autoimmune Disorders:Treg and CAR-Treg approaches require distinct potency assays.
- Regenerative Medicine:Pluripotent stem cell derivatives demand extended characterization panels.
Oncology holds the dominant position, while Rare Diseases is gaining share fastest through accelerated approval mechanisms.
End User:
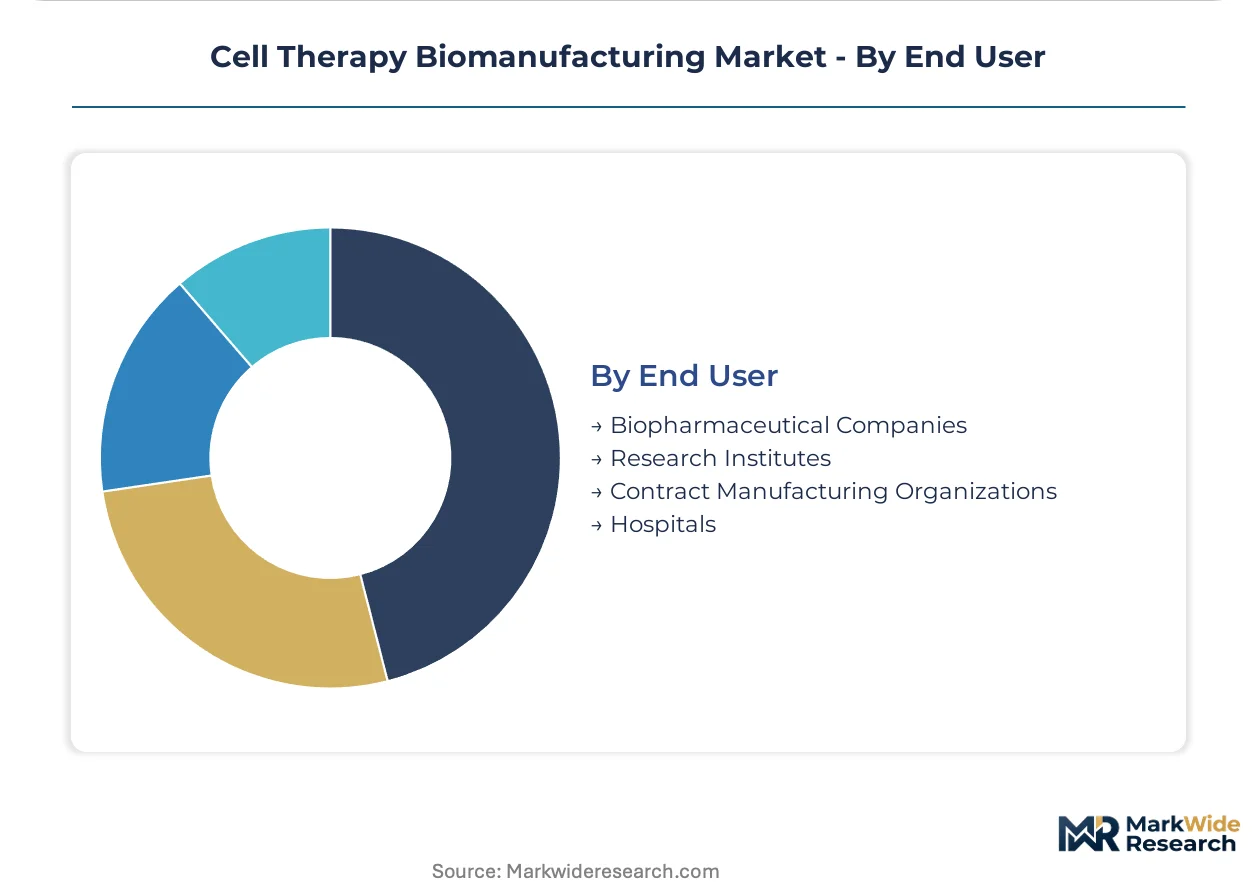
End user type determines facility ownership models and capital deployment patterns, with biopharma sponsors increasingly outsourcing rather than building captive cleanroom infrastructure.
- Contract Manufacturing Organizations:CDMOs aggregate demand across multiple sponsors to amortize ISO-7 suite construction costs. Lonza's Houston and Singapore hubs and Thermo Fisher's Princeton facility capture the majority of late-phase United States and Asia-Pacific autologous programs.
- Biopharmaceutical Companies:Large-cap sponsors maintain captive capacity for pipeline assets and process development. Bristol Myers Squibb and Novartis operate dedicated cell therapy suites in New Jersey and Switzerland to protect manufacturing IP and accelerate batch release.
- Research Institutes:Academic GMP facilities support Phase I investigator-initiated trials.
- Hospitals:Point-of-care cleanroom modules enable same-facility apheresis-to-infusion workflows.
Contract Manufacturing Organizations command the largest revenue share, while Biopharmaceutical Companies are building captive capacity fastest for pipeline protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized manufacturing infrastructure concentrates in jurisdictions with mature reimbursement frameworks and accelerated regulatory pathways. The United States, Germany, Japan, Singapore, and the United Kingdom host the deepest concentrations of GMP-grade cleanroom capacity and viral vector production expertise.
United States
FDA accelerated approval pathways for CAR-T therapies and priority review vouchers for rare disease indications pull forward capacity investments. The agency's chemistry, manufacturing, and controls guidance for gene therapy products shapes facility design standards nationwide. Boston and San Francisco anchor the densest cluster of autologous manufacturing suites serving academic medical centers.
Germany
EMA adaptive licensing frameworks and ATMP fee incentives for small patient populations attract allogeneic platform development. Heidelberg and Leipzig host specialized labor pools and shared logistics infrastructure that reduce cross-border cold-chain risks for European supply. Domestic CDMOs leverage these clusters to capture EMA export qualification contracts.
Japan
PMDA's regenerative medicine framework enables conditional approval with reduced Phase III requirements, accelerating revenue capture for cell therapy sponsors. Stringent donor cell traceability standards enforce supply chain documentation that exceeds FDA requirements. Tokyo and Osaka metropolitan areas concentrate point-of-care manufacturing pilots at university hospitals.
Singapore
Electroporation system adoption for non-viral gene delivery is displacing lentiviral dependency in allogeneic workflows. The national pharmaceutical regulator enforces GMP standards aligned with EMA Annex 2 for regional export qualification. Biopolis and Tuas Biomedical Park host CDMOs serving Asia-Pacific sponsors seeking dual US-EU market access.
United Kingdom
Cell and Gene Therapy Catapult infrastructure supports translational manufacturing from Phase I through commercial scale. MHRA post-Brexit regulatory autonomy permits accelerated assessment pathways for innovative therapies. Stevenage and Oxfordshire clusters concentrate viral vector production and cryogenic logistics capabilities.
Cell Therapy Biomanufacturing Market Vendor Landscape
Concentration sits with diversified life sciences conglomerates that control integrated supply chains from raw materials through finished dose. The market structure reflects tiered capability pools: full-service CDMOs with captive vector production, specialized equipment suppliers with single-use technologies, and mid-scale service providers focused on regional market access. Strategic moves center on backward integration into plasmid and media manufacturing, plus geographic hub expansion to compress vein-to-vein timelines.
Among diversified conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify the integrated supply chain archetype, bundling reagent, equipment, and manufacturing services to capture consolidated procurement contracts. Lonza occupies a position within the dedicated CDMO tier, anchoring capacity leadership through strategically located manufacturing hubs. Sartorius AG represents the specialized technology supplier archetype, with single-use bioreactor systems that reduce contamination risks during patient-specific batch runs.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Lonza |
| Sartorius AG |
| Bio-Techne |
| Becton, Dickinson and Company |
| Catalent, Inc |
| Cytiva |
| Miltenyi Biotec |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at viral vector manufacturing suites runs above 85 percent across United States and German hubs, compressing available slots for late-phase programs and establishing price floors that reflect scarcity rents rather than marginal production costs. This tightness concentrates pricing power with CDMOs controlling GMP-grade plasmid supply chains, while forcing biopharma sponsors into long-term offtake commitments that lock in cost structures regardless of batch yield outcomes.
Pricing Analysis
FDA chemistry, manufacturing, and controls guidance for gene therapy products dictates the pricing tier structure across autologous manufacturing networks. Three-tier pricing separates captive capacity at large-cap biopharma sponsors from premium CDMO slots with integrated vector production, with standard-tier regional service providers occupying the economy position. Price differentiation rests on certification grade — EMA Annex 2-compliant suites command 20-40 percent premiums over FDA-only facilities — and vertical integration depth. Cost compression in standard-tier autologous manufacturing is intensifying because electroporation systems reduce lentiviral dependency and associated COGS. Academic medical centers and emerging biotechs demonstrate highest price sensitivity, while large-cap oncology sponsors prioritize batch release speed over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate plasmid and viral vector procurement, though GMP-grade media suppliers maintain strategic stockpiles of chemically defined formulations to buffer against cold-chain disruptions. Geographic supply concentration centers on the United States for plasmid DNA, Germany for specialized CDMO capacity, and Singapore for electroporation system integration. Raw material dependencies include GMP-grade fetal bovine serum, synthetic lipid nanoparticles, and replication-deficient lentiviral particles. Single-source vulnerability pervades vector supply — Thermo Fisher and Lonza control the majority of commercial-grade lentiviral production — exposing programs to allocation rationing during demand surges. Distribution runs through controlled-temperature logistics networks with cryogenic chain-of-custody documentation mandatory from apheresis center through infusion site.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy biomanufacturing sits at an inflection where electroporation-enabled non-viral delivery and point-of-care manufacturing modules are collapsing legacy centralized production economics. FDA accelerated approval pathways and PMDA conditional frameworks compress development timelines, rewarding capacity positioned at the intersection of regulatory speed and manufacturing flexibility.
For Market Incumbents: Shield installed base relationships by backward integration into plasmid manufacturing and captive media formulation, neutralizing raw material scarcity threats from North American suppliers. Accelerate point-of-care manufacturing pilots at academic medical centers to defend against decentralized cleanroom modules that threaten centralized CDMO economics. Prioritize EMA Annex 2 certification investments to capture European export qualification premiums. For New Entrants and Emerging Players: Anchor in Singapore and Netherlands electroporation CDMO clusters where EMA-aligned GMP standards enable dual US-EU market access without redundant facility qualification. Target allogeneic platform manufacturing for rare disease indications where PMDA conditional approval reduces Phase III capital requirements. Pursue shared-suite partnerships with established academic GMP facilities to bypass ISO-7 construction capex barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CDMOs with demonstrated electroporation scale-up capabilities and established viral vector qualification track records under EMA Annex 2. Long-term viability hinges on backward integration depth into raw materials and geographic diversification beyond single-country regulatory exposure. Monitor FDA guidance revisions on real-time release testing as the signal to watch for process analytical technology adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plasmid Manufacturing | Captive GMP-grade plasmid supply neutralizes cross-border shipment bottlenecks for European programs. |
| Electroporation System Scale-Up | Non-viral gene delivery eliminates replication-competent virus testing and accelerates batch release timelines. |
| Point-of-Care Manufacturing Deployment | Decentralized cleanroom modules at academic medical centers collapse vein-to-vein logistics costs. |
| EMA Annex 2 Certification Investment | European GMP qualification opens premium pricing tiers and export qualification contracts from Asia-Pacific. |
| Process Analytical Technology Integration | Real-time in-process monitoring replaces end-point testing and compresses facility qualification timelines. |
Methodological Framework
Initial hypotheses were tested against primary input from cell therapy process engineers, regulatory affairs leads at CDMOs, hospital procurement managers overseeing CAR-T programs, and payer access specialists, then refined through secondary validation against FDA guidance documents, EMA ATMP classification frameworks, PMDA regenerative medicine submissions, and ClinicalTrials.gov protocol registries. Bottom-up capacity assessments at manufacturing hubs triangulated with top-down demand modeling across oncology and rare disease patient populations.
Variance decomposition across the projection horizon isolates volume drivers — patient population expansion, treatment line migration, manufacturing success rate improvements — from value drivers including pricing tier migration and service mix shifts toward allogeneic platforms. Segmentation dimensions encompass autologous versus allogeneic workflows, viral vector versus electroporation delivery technologies, oncology versus rare disease applications, and CDMO versus captive facility ownership models. CAGRs derive from logistic diffusion curves fitted to regulatory approval velocity and manufacturing capacity expansion schedules, with plasmid supply constraints and workforce availability serving as binding ceiling assumptions.
Material uncertainties — regulatory guidance revisions, manufacturing process failures at commercial scale, reimbursement policy shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about FDA accelerated approval pathway continuity and EMA adaptive licensing framework stability. Revision becomes warranted when electroporation manufacturing success rates cross thresholds that displace lentiviral dependency assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Cell and Gene Therapy Manufacturing Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Canine Stem Cell Therapy Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market