
 North America Cell and Gene Therapy Thawing Equipment Market | 2026-2036
North America Cell and Gene Therapy Thawing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cell and Gene Therapy Thawing Equipment Market Analytics
US biopharmaceutical manufacturing capacity is consolidating around cell and gene therapy commercial production. Cytiva leverages its chromatography and bioprocessing heritage to extend into thawing workflow integration. Thermo Fisher Scientific anchors North American distribution through its clinical and research channel density. BioLife Solutions specializes in cryopreservation media and complementary thermal management systems for cell therapy logistics.
Cell and Gene Therapy Thawing Equipment comprises thermal transfer systems engineered to recover cryopreserved biological materials from ultra-low temperatures without compromising cell viability, typically operating within precision-controlled temperature ramps between minus 196 degrees Celsius and 37 degrees Celsius. These systems serve the critical industrial purpose of maintaining therapeutic potency during the final stages of cold chain distribution before patient administration. Automated Thawing Systems capture the fastest expansion trajectory as commercial manufacturing scales beyond clinical trial volumes. Manual Thawing Devices retain entrenched positions in academic and early-stage research settings where throughput requirements remain modest. Smart Thawing Solutions are attracting development investment as manufacturers seek real-time viability feedback and electronic batch record integration.
FDA Center for Biologics Evaluation and Research enforces current Good Manufacturing Practice standards that directly dictate thawing equipment validation protocols for licensed cell therapies. Health Canada and ISO 14644 cleanroom classifications shape equipment design requirements for commercial manufacturing environments across the region. Stakeholders must monitor evolving regulatory harmonization between US and Canadian agencies as cross-border clinical trial networks and commercial supply chains deepen integration.
Market Dynamics
Commercial-scale cell and gene therapy manufacturing is forcing thawing equipment vendors to engineer systems that integrate directly with fill-finish lines and electronic batch record platforms, collapsing the historical separation between logistics and production workflows.
Growth Catalysts
- FDA cGMP validation protocols:Licensed cell therapies require documented thawing profiles, compelling biopharmaceutical manufacturers to replace manual methods with validated automated systems.
- San Diego and Boston biotech clusters:Concentrated venture capital deployment and manufacturing facility construction in these metros generates concentrated equipment procurement pipelines.
- Allogeneic cell therapy platforms:Off-the-shelf cell products require standardized thawing protocols at clinical sites, expanding addressable equipment demand beyond centralized manufacturing.
Market Restraints
- Stainless steel supply concentration:Precision-grade thermal chambers depend on specialized steel alloys sourced through a limited North American supplier base, exposing equipment makers to input cost volatility.
- Health Canada equipment approval timelines:Cross-border commercial supply chains face asynchronous regulatory review periods that delay unified product launches.
- Manual water bath substitution:Academic and early-phase research settings continue deploying low-cost conventional thawing methods, capping premium equipment penetration in price-sensitive segments.
Strategic Opportunities
- Canadian clinical trial networks:Underpenetrated relative to US density, Health Canada's streamlined trial frameworks attract sponsors seeking parallel enrollment, creating equipment demand at Toronto and Vancouver sites.
- Real-time viability sensing:Integration of impedance spectroscopy and automated cell counting into thawing platforms enables closed-loop process control and differentiated positioning.
- IRA domestic manufacturing incentives:Biopharmaceutical producers qualifying for US production tax credits require qualified equipment vendors, reshaping procurement qualification criteria.
Industry Challenges
- Bioprocess engineering talent scarcity:Equipment vendors compete with cell therapy developers for personnel skilled in cryobiology and thermal transfer modeling.
- Legacy LIMS integration complexity:Automated thawing systems must interface with heterogeneous manufacturing execution systems already deployed at customer sites, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cell and Gene Therapy Thawing Equipment Market |
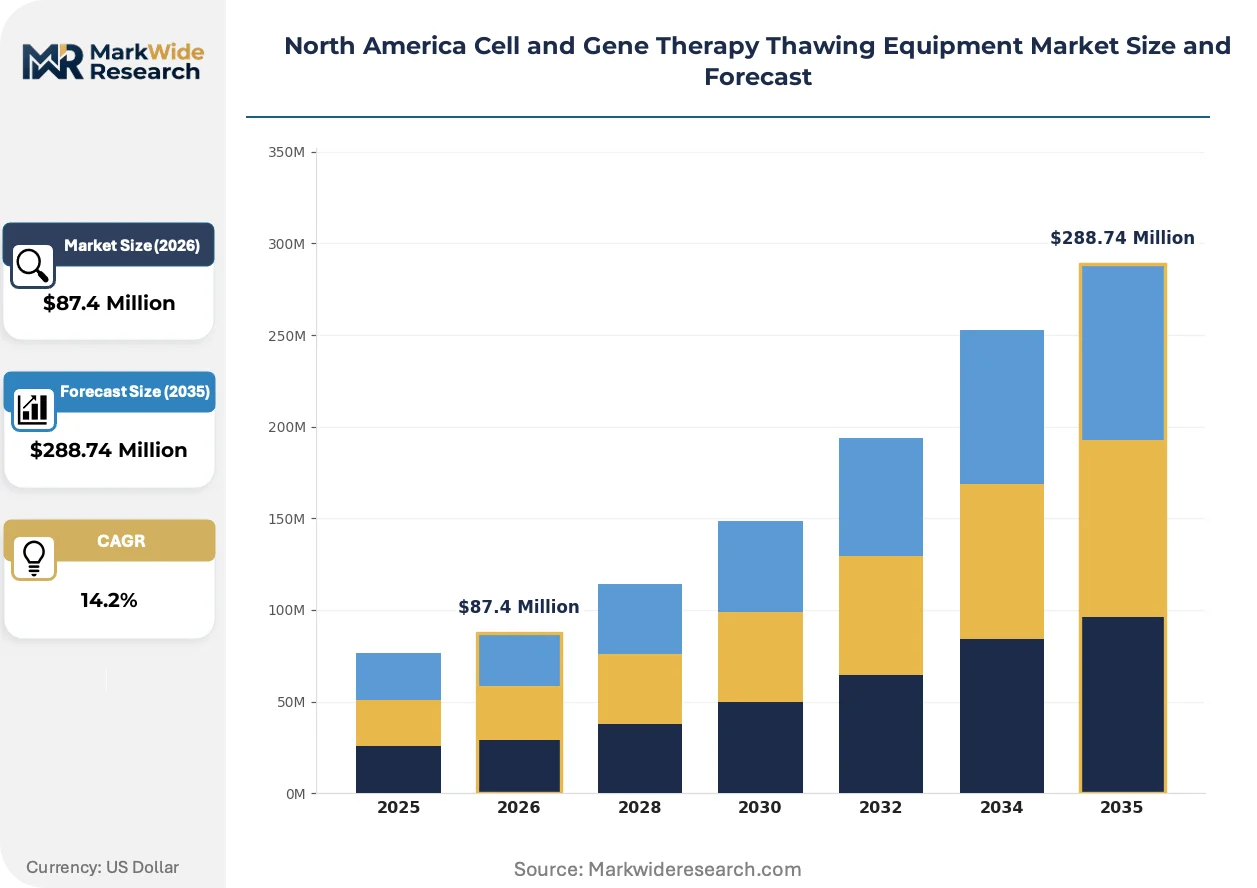
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $288.74 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Thawing Devices, Automated Thawing Systems, Water Bath Thawers, Microwave Thawers Application: Clinical Research, Hospital Laboratories, Commercial Manufacturing, Biobanks End User: Hospitals, Academic Institutions, Research Laboratories, Biopharmaceutical Companies Technology: Rapid Thawing Technology, Controlled Rate Thawing, Direct Thawing, Smart Thawing Solutions |
| Companies Covered | Cytiva, Thermo Fisher Scientific, Helmer Scientific, BioLife Solutions, Sartorius AG, Eppendorf AG, Boekel Scientific, Barkey GmbH, Azenta Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cell and Gene Therapy Thawing Equipment Market Evolving Landscape
Thawing equipment architecture is converging with broader bioprocessing automation platforms, eroding the standalone equipment category and repositioning vendors as workflow subsystem suppliers.
Programmable thermal profile controllers with integrated data logging are unifying thawing documentation with electronic batch records. Commercial cell therapy manufacturers adopting these systems eliminate manual transcription steps and reduce deviation investigations. This unification compresses equipment qualification timelines and shifts competitive differentiation toward software validation packages.
FDA Center for Biologics Evaluation and Research guidance on continuous process verification is elevating real-time release testing requirements. Thawing equipment must now generate process analytical technology data streams compatible with agency inspection protocols. Commercial manufacturing segments in the United States are responding by specifying equipment with embedded PAT sensors and automated certificate-of-analysis generation.
Biopharmaceutical procurement teams are consolidating vendor relationships and demanding equipment-as-service models with embedded validation support. Distributors and direct sales channels face disintermediation as manufacturers source thawing systems through single-source bioprocessing platform agreements. This consolidation is most visible among mid-cap cell therapy developers in Massachusetts and California seeking to reduce supplier management overhead.
North America Cell and Gene Therapy Thawing Equipment Market Segmentation
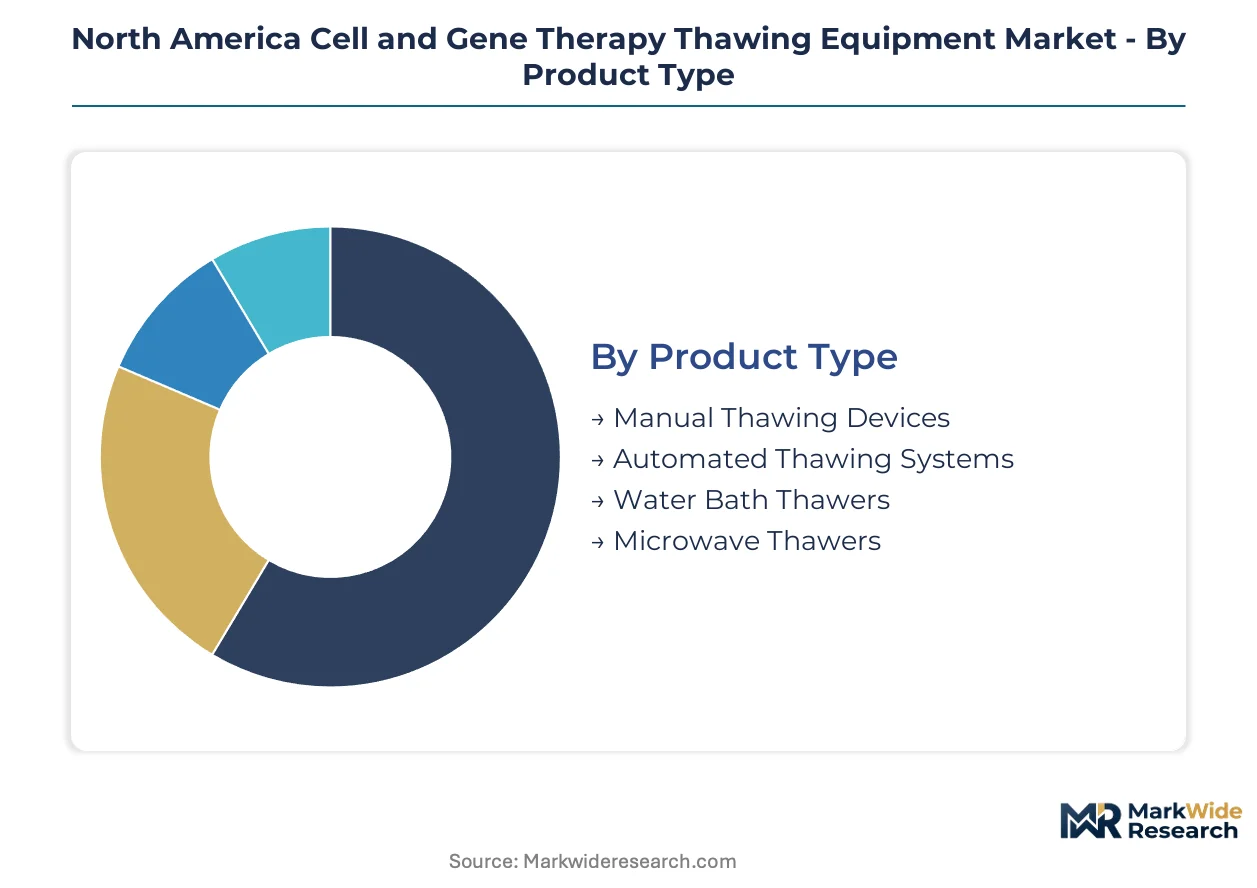
Equipment segmentation in this market reflects divergent validation requirements across research and commercial settings. Procurement patterns split sharply between cost-sensitive academic buyers and cGMP-compliant biopharmaceutical manufacturers.
Product Type:
Thermal transfer architecture distinguishes equipment tiers, from passive conductive systems to active precision-controlled platforms.
- Automated Thawing Systems:Programmable thermal profile controllers execute documented thawing ramps with integrated data logging for electronic batch record compliance. FDA cGMP validation protocols compel biopharmaceutical manufacturers in Massachusetts and California to specify these systems for licensed cell therapy production.
- Manual Thawing Devices:Hand-operated conductive chambers or bead baths offer basic temperature control without automated documentation. Academic institutions and early-phase research sites across the United States deploy these where throughput requirements remain modest and capital budgets constrain procurement.
- Water Bath Thawers:Immersion-based conductive thawing using temperature-controlled liquid media.
- Microwave Thawers:Electromagnetic energy transfer systems for rapid thermal recovery.
Mature deployment sits with Manual Thawing Devices. Newer deployment is concentrated in Automated Thawing Systems.
Application:
Facility type determines throughput scale, regulatory burden, and integration requirements for thawing workflows.
- Commercial Manufacturing:Large-scale fill-finish operations demand equipment that interfaces directly with manufacturing execution systems and generates process analytical technology data streams. San Diego and Boston biotech clusters anchor North American procurement volume as cell therapy developers scale beyond clinical trial production.
- Clinical Research:Phase I/II trial sites require flexible thawing protocols accommodating diverse investigational products. Health Canada streamlined trial frameworks attract sponsors seeking parallel enrollment, expanding equipment demand at Toronto and Vancouver research sites.
- Hospital Laboratories:Point-of-care thawing for patient-administered cell therapies.
- Biobanks:High-volume cryopreserved inventory management with batch processing requirements.
Commercial Manufacturing commands premium pricing tiers. Clinical Research exhibits the steepest expansion trajectory as trial networks proliferate.
End User:
Organizational mission shapes capital allocation authority and equipment specification sophistication.
- Biopharmaceutical Companies:Venture-backed cell therapy developers and established manufacturers with qualified vendor programs. These buyers consolidate supplier relationships through single-source bioprocessing platform agreements, disintermediating traditional distribution channels.
- Academic Institutions:University research laboratories with principal investigator-driven procurement decisions. Price sensitivity and legacy water bath substitution cap premium equipment penetration in this segment.
- Hospitals:Integrated health systems administering approved cell therapies.
- Research Laboratories:Contract research organizations and government research facilities.
Biopharmaceutical Companies anchor revenue concentration. Academic Institutions represent the most price-elastic demand pool.
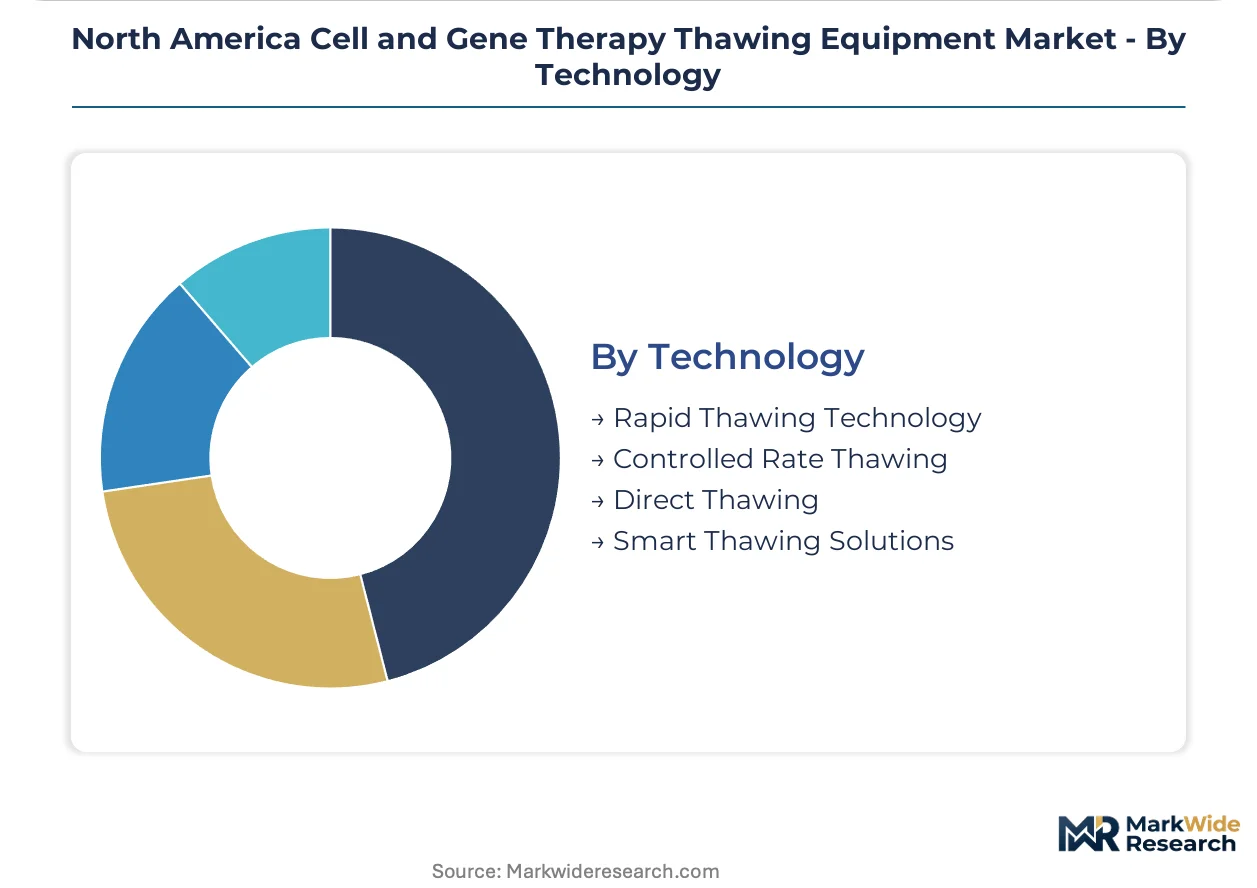
Technology:
Process control sophistication differentiates equipment value propositions across the thawing workflow.
- Smart Thawing Solutions:Embedded impedance spectroscopy and automated cell counting enable real-time viability feedback with closed-loop process control. Development investment concentrates here as manufacturers seek electronic batch record integration and differentiated positioning against legacy thermal platforms.
- Controlled Rate Thawing:Precision-engineered thermal ramp protocols prevent ice recrystallization and osmotic shock. FDA Center for Biologics Evaluation and Research guidance on continuous process verification elevates demand for these systems in United States commercial manufacturing.
- Rapid Thawing Technology:Accelerated thermal transfer methods for time-critical applications.
- Direct Thawing:Simplified conductive or convective heat transfer without intermediate media.
Controlled Rate Thawing dominates current installed base. Smart Thawing Solutions are gaining share fastest through greenfield commercial facility investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized stainless steel alloys for precision thermal chambers concentrate in Pittsburgh and Cleveland mill corridors, anchoring North American equipment fabrication networks. This metalworking base supplies thawing system manufacturers across the continent.
United States
FDA cGMP validation protocols compel Massachusetts and California cell therapy developers to specify automated thawing systems with electronic batch record integration. The Inflation Reduction Act production tax credits reshape procurement qualification criteria for domestic manufacturing equipment. Boston-Cambridge and San Diego biotech clusters anchor commercial-scale facility construction and concentrated equipment procurement pipelines.
Canada
Health Canada streamlined clinical trial frameworks attract sponsors seeking parallel enrollment with US protocols, expanding equipment demand at Toronto and Vancouver research sites. Asynchronous regulatory review timelines between Health Canada and FDA delay unified product launches for cross-border supply chains. The Toronto-Waterloo corridor concentrates cell therapy manufacturing investment and thawing system deployment.
Mexico
Contract manufacturing organization expansion near Mexico City and Querétaro creates ancillary demand for research-grade thawing equipment supporting clinical material preparation. Mexico's national pharmaceutical regulator enforces cold chain documentation standards aligned with USMCA trade compliance. The Bajío Region pharmaceutical cluster attracts bioprocessing equipment vendors establishing regional distribution nodes.
North America Cell and Gene Therapy Thawing Equipment Market Competitive Landscape
Global majors compete with regional champions across distribution density and regulatory validation support. The vendor base stratifies between diversified life science conglomerates and specialized cryopreservation equipment fabricators. Three archetypes dominate: chromatography-bioprocessing integrators extending into thermal workflow management; precision temperature control specialists with clinical channel penetration; and cryopreservation media suppliers bundling complementary hardware. Competitive moves concentrate on strategic partnerships with cell therapy developers and backward integration into thermal chamber manufacturing.
Within the diversified life science tier, Thermo Fisher Scientific and Cytiva occupy positions anchored by North American clinical and research channel density. BioLife Solutions exemplifies the cryopreservation-specialist archetype, leveraging thermal management heritage adjacent to its media portfolio. These three represent distinct strategic postures without overlapping core competencies.
| Leading Market Players |
|---|
| Cytiva |
| Thermo Fisher Scientific |
| Helmer Scientific |
| BioLife Solutions |
| Sartorius AG |
| Eppendorf AG |
| Boekel Scientific |
| Barkey GmbH |
| Azenta Life Sciences |
| Others |
Value Network & Pricing Analysis
Specialized stainless steel alloys for precision thermal chambers flow from Pittsburgh and Cleveland mill corridors through fabrication networks to equipment assemblers, with alloy grade certification tiering final system pricing for biopharmaceutical buyers.
Pricing Analysis
Warranty and validation service bundling separates premium automated thawing systems from unbundled research-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA cGMP certification grade and electronic batch record integration depth. Cost compression in the manual device tier intensifies because academic buyers substitute conventional water baths. Biopharmaceutical companies show least price sensitivity where licensed therapy production demands qualified equipment, while academic institutions anchor the most elastic demand pool.
Supply Chain Analysis
Workforce availability constraints in Pittsburgh and Cleveland precision metalworking corridors limit thermal chamber fabrication capacity expansion. Equipment assembly draws from US steel mills, German sensor suppliers, and Canadian control system integrators. Single-source vulnerability concentrates in specialized alloy grades for cryogenic service. Distribution runs through direct manufacturer relationships with large biopharmaceutical accounts and regional distributors serving research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized alloy supply bottlenecks prop equipment pricing power as thermal chamber fabrication capacity fails to match commercial cell therapy manufacturing expansion.
For Market Incumbents: Deploy backward integration into thermal chamber manufacturing to capture margin from alloy processing through final system assembly. Incumbent vendors face displacement risk from bioprocessing platform consolidators seeking single-source agreements. Locking Pittsburgh and Cleveland mill capacity through long-term offtake secures input cost stability against emerging cryopreservation equipment specialists. For New Entrants and Emerging Players: Enter via Health Canada streamlined trial frameworks at Toronto and Vancouver research sites where incumbent penetration lags US density. Canadian clinical networks offer the most penetrable geography for research-grade equipment positioning. Partner with contract research organizations on flexible thawing protocol development to establish reference installations. For Investors and Strategic Acquirers: FDA issuance of formal guidance on continuous process verification for thawing equipment is the leading indicator that real-time release testing capabilities will command acquisition premiums. Five-to-ten year viability favors vendors with embedded process analytical technology sensor platforms. Target acquisition profile centers on cryobiology engineering teams with thermal transfer modeling expertise and Health Canada regulatory dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Processing | Pittsburgh mill corridor capture insulates margin from stainless steel price volatility. |
| Electronic Batch Record Integration | FDA cGMP validation protocols compel biopharmaceutical procurement specification. |
| Health Canada Regulatory Dossier Expansion | Streamlined trial frameworks at Toronto sites accelerate Canadian market penetration. |
| Real-Time Viability Sensor Development | Impedance spectroscopy embedding differentiates against legacy thermal platforms. |
| Bioprocessing Platform Partnership | Single-source agreements with Massachusetts cell therapy developers disintermediate distribution. |
Research Methodology
Independent corroboration across bioprocess engineering executives, regulatory affairs leads at cell therapy developers, hospital procurement managers, and cryopreservation media specialists underwrites the qualitative findings. Secondary validation sources include FDA Center for Biologics Evaluation and Research guidance documents, Health Canada regulatory filings, ClinicalTrials.gov protocol specifications, and SEC 10-K disclosures from diversified life science conglomerates. Bottom-up equipment shipment estimates triangulate against top-down biopharmaceutical manufacturing capacity expansion projections.
Rate-of-change decomposition across the analysis window separates volume expansion from pricing trajectory and technology mix shift. Segmentation dimensions modeled encompass product type tier, application facility class, end-user organizational mission, and technology process control sophistication. CAGRs derive from installed base replacement cycles and greenfield commercial facility investment pipelines, with cell therapy approval velocity and IRA domestic manufacturing incentive qualification serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under asynchronous Health Canada-FDA regulatory review timelines and stainless steel alloy supply disruption. Forecasts reflect assumptions regarding continued cGMP validation protocol tightening and sustained venture capital deployment into Boston and San Diego biotech clusters. Material deviation in alloy supply concentration or cross-border harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
Viral Vector Purification Market