
 Cell and Gene Therapy CDMO Market | 2026-2036
Cell and Gene Therapy CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Cell and Gene Therapy CDMO Market Analytics
The Cell and Gene Therapy CDMO Market is recalibrating around a widening gap between premium viral vector suites and commodity plasmid production capacity. Lonza leverages its Basel-based network to sustain dominance in integrated cell therapy manufacturing. Catalent competes through specialized commercial fill-finish infrastructure across North American and European nodes. Thermo Fisher Scientific anchors its position via upstream control over critical raw materials and analytical instrumentation.
Cell and gene therapy contract development and manufacturing organizations operate facilities maintaining ISO 5-7 cleanroom classifications, aseptic processing capabilities, and cryogenic chain integrity from vector production through patient-specific cell modification. Their primary commercial purpose centers on translating bench-scale genetic medicines into reproducible, regulator-auditable manufacturing campaigns for sponsor companies lacking captive bioprocessing infrastructure. Viral vector manufacturing occupies the highest-margin tier due to complexity barriers and capacity scarcity, while plasmid DNA services face commoditization pressures from standardized fermentation platforms. Process development and analytical services represent the fastest-expanding revenue layer as sponsors outsource early-phase characterization and regulatory filing support.
FDA's Chemistry, Manufacturing, and Controls guidance, EMA's ATMP framework, and ISO 14644 cleanroom standards collectively dictate facility validation protocols, batch release timelines, and cross-border supply eligibility for CDMO operators. These frameworks compress development timelines while elevating capital requirements for new market entrants. Stakeholders must monitor how regulatory convergence between FDA and EMA on gene therapy potency assays reshapes competitive barriers for mid-scale manufacturing networks.
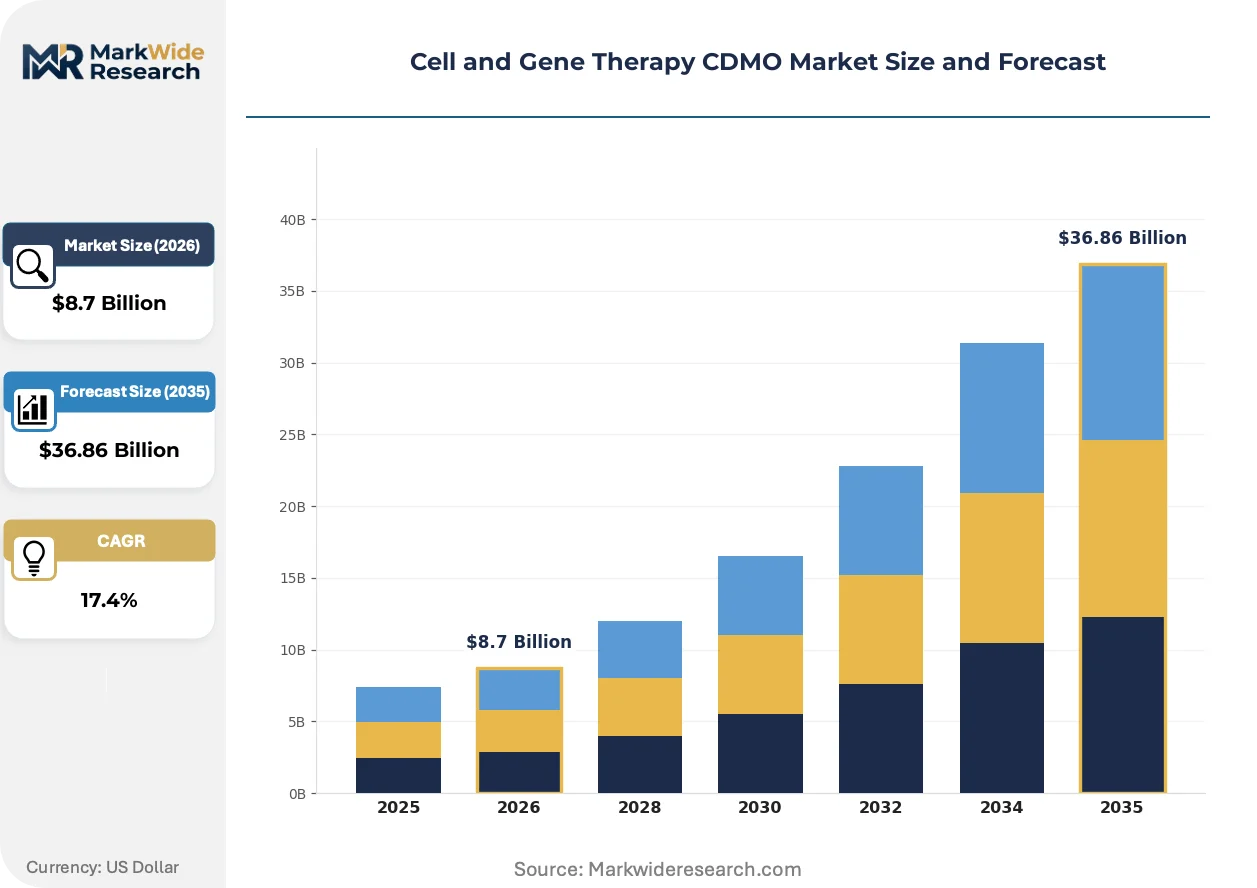
Market Dynamics
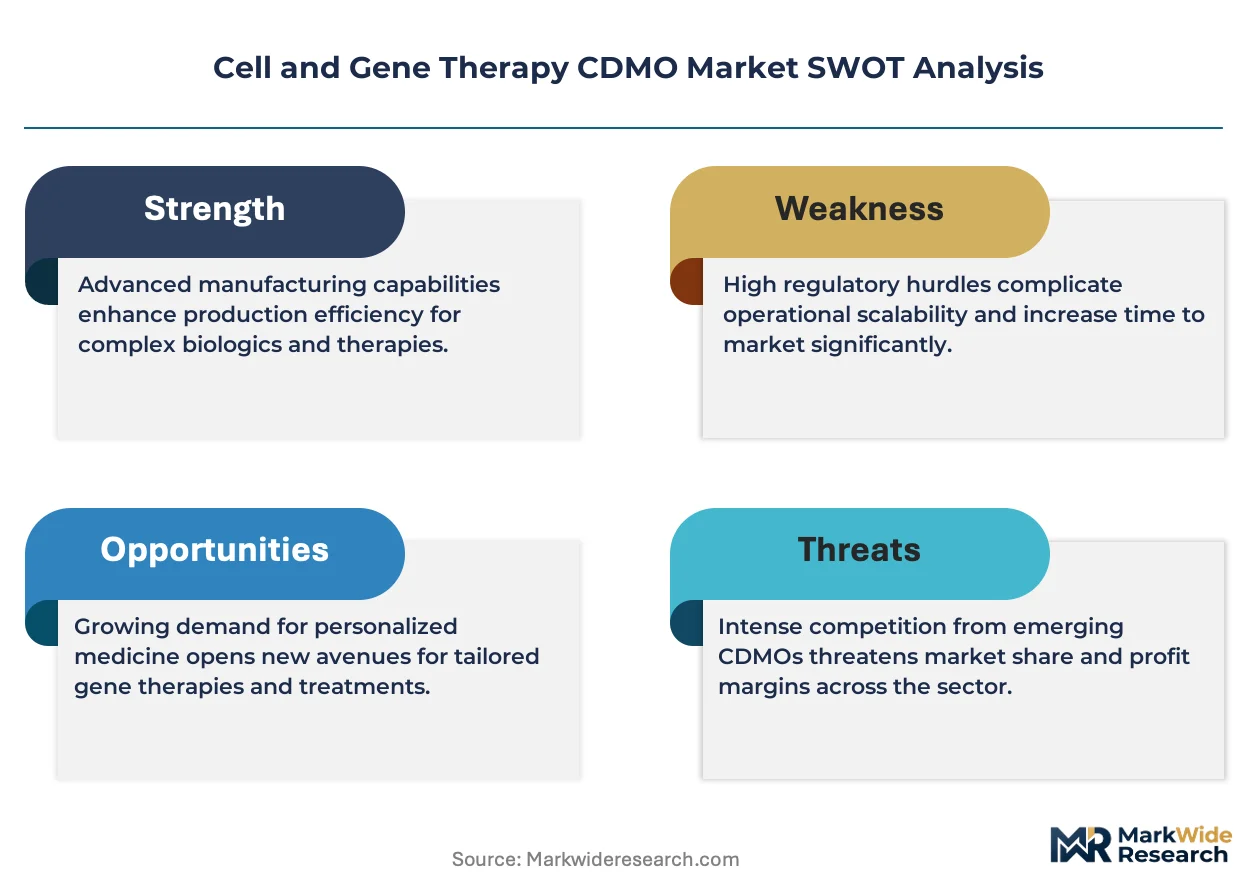
Viral vector manufacturing scarcity is compressing sponsor timelines and forcing CDMOs to prioritize oncology partnerships over rare disease programs. This capacity rationing is redistributing revenue concentration toward integrated platform providers with captive analytical capabilities.
Growth Catalysts
- FDA Accelerated Approval Pathways:The regenerative medicine advanced therapy designation compresses Phase I-to-approval timelines, pulling forward manufacturing scale-up commitments from sponsor pipelines.
- Electroporation-based non-viral delivery:Academic medical centers in Boston and Basel are validating lipid nanoparticle alternatives, expanding addressable patient populations beyond current viral vector constraints.
- South Korean biocluster concentration:Songdo and Osong science parks aggregate MFDS-aligned GMP infrastructure, attracting cross-border sponsor manufacturing migrations from Singapore and Australia.
Market Restraints
- Plasmid DNA feedstock volatility:Fermentation-grade glucose and specialized yeast extract prices fluctuate with agricultural commodity cycles, squeezing margin predictability for mid-scale CDMOs.
- Swiss cleanroom construction bottlenecks:Basel-region ISO 5 suite expansion faces 18-24 month lead times due to specialized HVAC contractor scarcity and cantonal permitting density.
- EMA batch release heterogeneity:Divergent national competent authority interpretations of ATMP potency assays create redundant testing burdens for multi-site European campaigns.
Strategic Opportunities
- Allogeneic "off-the-shelf" platforms:Master cell bank manufacturing for donor-derived therapies opens capacity-multiplying revenue streams absent patient-matched logistics complexity.
- MFDS fast-track designations:South Korea's regenerative bioproduct approval pathway offers 12-month review commitments, attracting early-phase sponsor relocations from slower EMA processes.
- Closed-system automation convergence:Integration of single-use bioreactors with in-line PAT sensors enables continuous processing campaigns that reduce cleanroom footprint requirements by 40 percent.
Industry Challenges
- Aseptic processing technician scarcity:ISO 5 gowning certification programs produce insufficient qualified operators to staff third-shift viral vector campaigns at Basel and Boston facilities.
- Cross-border cold chain integrity:Cryogenic liquid nitrogen shipping between US and European nodes faces customs documentation variability that threatens cell viability windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell and Gene Therapy CDMO Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Analytical Services, Commercial Production, Quality Control End User: Biotechnology Companies, Pharmaceutical Firms, Academic Institutions, Research Organizations Technology: Viral Vectors, Plasmid DNA, Cell Lines, Genome Editing Application: Oncology, Genetic Disorders, Cardiovascular Diseases, Rare Diseases |
| Companies Covered | Lonza, Catalent, Thermo Fisher Scientific, Charles River Laboratories, Cytiva, Samsung Biologics, WuXi AppTec, AGC Biologics, FUJIFILM Diosynth Biotechnologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell and Gene Therapy CDMO Market Evolving Landscape
Continuous bioprocessing architectures are displacing batch manufacturing economics across cell therapy workflows, while regulatory convergence on potency assay standards is compressing technical divergence between FDA and EMA submissions.
Suspension-adapted lentiviral vector production is electrifying upstream yield economics for CAR-T programs. Biotech sponsors in Cambridge and Basel are converting adherent platforms to stirred-tank bioreactors within 18-month timelines. This shift is enabling 10-fold titer improvements that compress cost-per-dose structures and expand patient access eligibility.
EMA's revised ATMP GMP Annex guidelines now mandate real-time release testing for critical quality attributes. European CDMO networks are reconfiguring QC laboratories to accommodate at-line mass spectrometry and flow cytometry suites. Viral vector release timelines are compressing from 21 days to 72 hours at Swissmedic-inspected Basel facilities.
Sponsor procurement teams are consolidating manufacturing contracts with single-platform providers capable of end-to-end vector-to-cell processing. Small and mid-cap biotechs are abandoning multi-vendor strategies that fragment CMC responsibility. This concentration is most visible among Boston-based immuno-oncology developers seeking integrated IND-to-BLA pathways.
Cell and Gene Therapy CDMO Market Segmentation
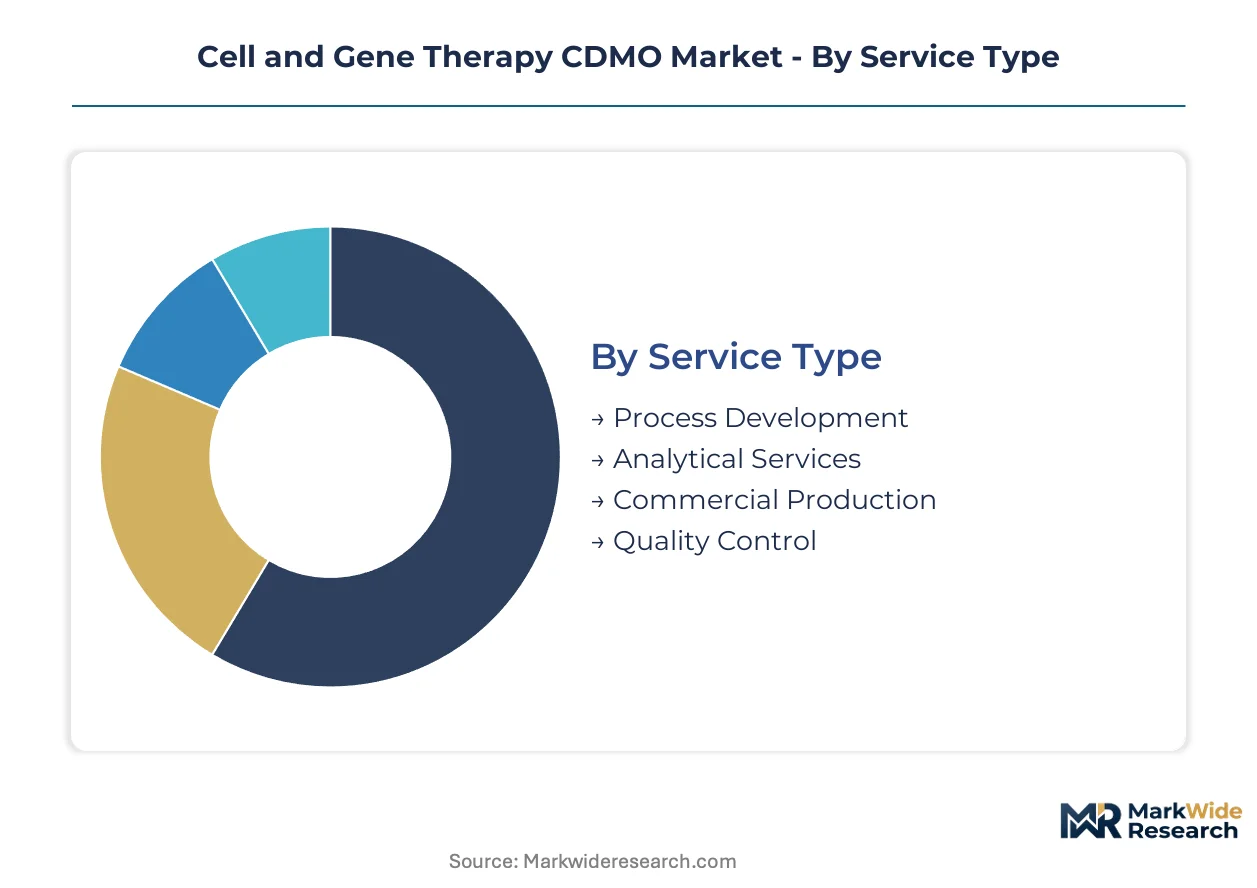
CDMO procurement decisions diverge sharply across service tiers and sponsor types. Capital deployment patterns and regulatory filing strategies reshape how contract manufacturers prioritize capacity across viral vector, plasmid, and cell-based production modalities.
Service Type:
Commercial production commands the steepest upfront facility investment, while analytical services require specialized instrumentation but smaller cleanroom footprints.
- Process Development:Cell line engineering, media optimization, and scale-up validation for IND-enabling batches. Sponsors in Basel and Boston are outsourcing early-phase characterization to compress CMC timelines for FDA regenerative medicine advanced therapy submissions.
- Analytical Services:Potency assays, identity testing, and stability studies using mass spectrometry and flow cytometry platforms. South Korean CDMOs are expanding QC capacity to support MFDS fast-tracked gene therapy filings.
- Commercial Production:GMP viral vector and cell therapy manufacturing at ISO 5-7 classification.
- Quality Control:Batch release testing and regulatory documentation.
Commercial production absorbs the bulk of installed capacity; analytical services are expanding most quickly.
End User:
Sponsor size dictates contract structure, with large pharmaceutical firms demanding dedicated suite arrangements that mid-cap biotechs cannot access.
- Biotechnology Companies:Venture-backed gene therapy developers lacking captive manufacturing infrastructure. Cambridge and Basel clusters concentrate demand for integrated vector-to-cell processing platforms.
- Pharmaceutical Firms:Established sponsors with BLA-tracked programs seeking commercial-scale capacity reservations.
- Academic Institutions:Medical center spinouts translating bench-scale discoveries.
- Research Organizations:Non-profit and government-funded translational programs.
Biotechnology companies dominate contract volume; pharmaceutical firms command the longest-term capacity commitments.
Technology:
Viral vector manufacturing carries the highest technical barriers and margin capture, while plasmid DNA faces standardization pressures.
- Viral Vectors:Lentiviral, adeno-associated, and retroviral delivery systems for CAR-T and gene editing. Suspension-adapted production at Basel facilities is achieving 10-fold titer improvements over adherent platforms.
- Plasmid DNA:Circular DNA templates for viral vector production and direct gene therapy. Fermentation-grade feedstock volatility from agricultural commodity cycles squeezes margin predictability.
- Cell Lines:Master cell bank and working cell bank establishment.
- Genome Editing:CRISPR guide RNA and nuclease manufacturing services.
Viral vectors absorb the bulk of installed capacity; genome editing is climbing the fastest as allogeneic platforms mature.
Application:
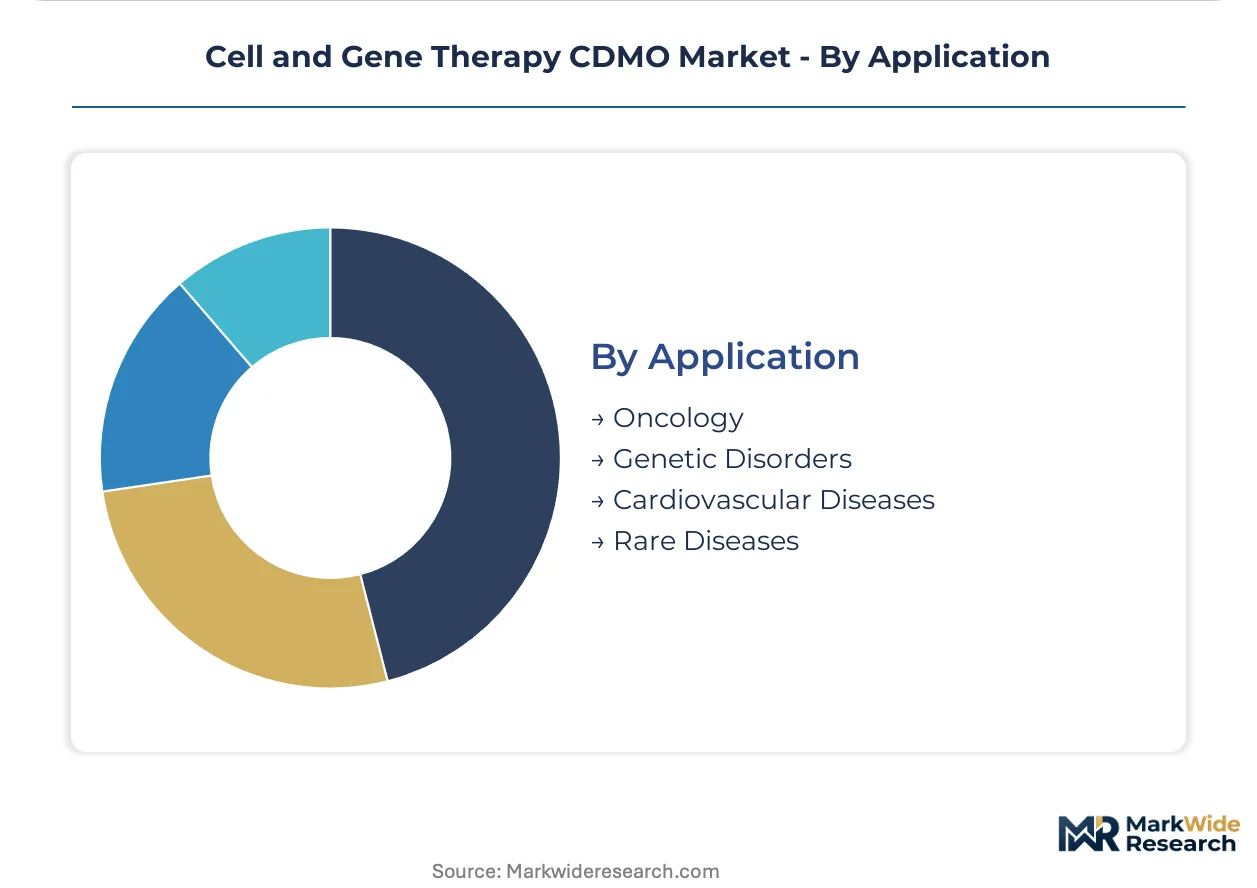
Oncology indications justify premium pricing and dedicated capacity, while rare disease programs face manufacturing prioritization constraints.
- Oncology:CAR-T, TCR-T, and tumor-infiltrating lymphocyte therapies for hematologic and solid malignancies. Academic medical centers in Boston are expanding manufacturing partnerships for autologous cell therapy access.
- Genetic Disorders:Gene replacement therapies for monogenic diseases. EMA batch release heterogeneity creates redundant testing burdens for multi-site European campaigns.
- Cardiovascular Diseases:Regenerative cell therapies for heart failure.
- Rare Diseases:Ultra-orphan indications with small patient populations.
Oncology absorbs the bulk of installed capacity; genetic disorders are gaining share fastest as EMA and FDA converge on potency assay standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors the most concentrated viral vector manufacturing corridor worldwide, with Swissmedic-inspected facilities processing the majority of European gene therapy batches. The United States, Switzerland, South Korea, Germany, and Japan collectively house the specialized ISO 5-7 cleanroom infrastructure required for commercial-scale cell therapy production.
United States
FDA's regenerative medicine advanced therapy designation pulls forward manufacturing scale-up commitments from sponsor pipelines. The agency's Chemistry, Manufacturing, and Controls guidance dictates facility validation protocols and batch release timelines. Academic medical centers in Boston are expanding manufacturing partnerships for autologous cell therapy access, while Cambridge biotech clusters concentrate demand for integrated vector-to-cell processing platforms.
Switzerland
Swissmedic-inspected Basel facilities achieve 72-hour viral vector release timelines under revised EMA ATMP GMP Annex guidelines. Cantonal permitting density and specialized HVAC contractor scarcity create 18-24 month lead times for ISO 5 suite expansion. The Basel-region network sustains dominance in integrated cell therapy manufacturing through captive analytical capabilities and cryogenic chain integrity.
South Korea
MFDS fast-tracked gene therapy filings attract early-phase sponsor relocations from slower EMA processes with 12-month review commitments. Songdo and Osong science parks aggregate MFDS-aligned GMP infrastructure, attracting cross-border manufacturing migrations from Singapore and Australia. Domestic CDMOs are expanding QC capacity to support regenerative bioproduct approvals.
Germany
ECHA chemical safety assessments intersect with EMA ATMP potency assay standards for multi-site European campaigns. Divergent national competent authority interpretations create redundant testing burdens that fragment batch release timelines. Frankfurt and Munich bioclusters are consolidating manufacturing contracts with single-platform providers capable of end-to-end vector-to-cell processing.
Japan
PMDA's regenerative medicine product approval pathway compresses development timelines for allogeneic platform sponsors. METI industrial policy supports closed-system automation convergence to reduce cleanroom footprint requirements. Tokyo and Osaka medical centers are validating electroporation-based non-viral delivery alternatives to expand addressable patient populations beyond viral vector constraints.
Cell and Gene Therapy CDMO Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where viral vector scarcity concentrates revenue among integrated platform providers. The market stratifies between captive analytical networks, specialized commercial fill-finish operators, and upstream raw material controllers. Strategic archetypes include Swiss-based integrated manufacturers, North American multi-node specialists, and Asian scale-driven facilities. Competitive moves center on capacity reservation agreements and closed-system automation licensing rather than price-based rivalry.
Within the integrated manufacturing tier, Lonza and Catalent exemplify divergent geographic strategies for regulatory proximity. Thermo Fisher Scientific anchors the upstream control archetype through analytical instrumentation dominance. Samsung Biologics occupies a position between Asian scale advantages and Western regulatory alignment. These three entities represent how facility certification grade and sponsor proximity to FDA or EMA approval pathways determine contract allocation more than unit cost differentiation.
| Leading Market Players |
|---|
| Lonza |
| Catalent |
| Thermo Fisher Scientific |
| Charles River Laboratories |
| Cytiva |
| Samsung Biologics |
| WuXi AppTec |
| AGC Biologics |
| FUJIFILM Diosynth Biotechnologies |
| Others |
Value Network & Pricing Analysis
Captive analytical capability integration anchors pricing power for CDMOs serving FDA regenerative medicine advanced therapy sponsors, while outsourced plasmid DNA feedstock dependence erodes margin predictability for mid-scale operators lacking upstream fermentation control.
Pricing Analysis
Yield-guaranteed throughput contracts dominate viral vector pricing, with Swissmedic-inspected Basel facilities commanding premiums based on 72-hour release timelines versus 21-day standard cycles. Price differentiation rests on ISO 5 certification grade and captive potency assay capability, not unit volume. Cost compression in plasmid DNA services intensifies because standardized fermentation platforms face agricultural commodity cycle volatility. Small-cap biotech sponsors exhibit highest price sensitivity; large pharmaceutical firms prioritize timeline certainty over per-dose economics.
Supply Chain Analysis
Direct-to-sponsor channels handle commercial-scale viral vector demand, with inventory pooling reserved for plasmid DNA feedstock buffers. Manufacturing-grade glucose and specialized yeast extract draw from agricultural suppliers in the United States, Brazil, and Argentina. Single-source vulnerability concentrates in Swiss HVAC contractor networks, where cantonal permitting density extends ISO 5 suite construction timelines. Cryogenic liquid nitrogen distribution runs through specialized logistics partners maintaining chain-of-custody documentation for cross-border cell therapy shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating across the Cell and Gene Therapy CDMO Market as players pursue captive control over potency assay instrumentation to defend margin structures against commoditization pressures in plasmid DNA services.
For Market Incumbents: Extend analytical service bundling to capture early-phase sponsor relationships before IND submission, insulating against emerging automated closed-system platform providers. Prioritize ISO 5 suite expansion in Basel and Boston corridors despite 18-24 month construction lead times. Defensive patent positioning around suspension-adapted lentiviral vector production processes limits challenger titer improvements. For New Entrants and Emerging Players: Begin with allogeneic master cell bank manufacturing for donor-derived therapies, where capacity-multiplying economics bypass patient-matched logistics complexity. South Korean MFDS-aligned GMP infrastructure offers the most penetrable regulatory entry point for cross-border sponsor migrations from slower EMA processes. Go-to-market positioning should emphasize 12-month review commitment timelines versus European national competent authority heterogeneity. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated platform providers with end-to-end vector-to-cell processing capabilities, where sponsor procurement consolidation favors single-vendor CMC responsibility. Long-term viability over the next decade hinges on closed-system automation licensing revenue streams displacing cleanroom-intensive batch economics. Monitor FDA-EMA convergence on gene therapy potency assay standards as inflection signal for mid-scale network competitive barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | MFDS fast-track designations compress sponsor timelines versus EMA national authority fragmentation. |
| Manufacturing Scale-Up | Suspension-adapted lentiviral production at Basel facilities achieves 10-fold titer improvements over adherent platforms. |
| Backward Integration | Upstream control over fermentation-grade feedstock buffers margin volatility from agricultural commodity cycles. |
| Strategic Partnership | Academic medical center alliances in Boston secure autologous cell therapy manufacturing access commitments. |
| Technology Licensing | Closed-system automation patents reduce cleanroom footprint requirements by 40 percent for continuous processing. |
Research Methodology
Document review covered FDA Chemistry Manufacturing and Controls guidance, EMA ATMP GMP Annex revisions, and MFDS regenerative bioproduct filings, complemented by interviews with viral vector manufacturing directors, regulatory affairs leads at sponsor companies, Swissmedic inspection coordinators, and academic medical center translational program officers. Secondary validation drew from ClinicalTrials.gov gene therapy entries, SEC 10-K CDMO segment disclosures, and Swiss cantonal construction permit databases. Bottom-up capacity installation counts and top-down sponsor pipeline value estimates were triangulated to anchor market sizing.
Segment-level value outputs across the projection horizon reflect modeled interactions between viral vector scarcity premiums, plasmid DNA commoditization curves, and analytical services expansion rates. The analytical framework incorporated service type, end user size tier, technology modality, and application indication as core segmentation dimensions. CAGRs were derived from sponsor manufacturing scale-up commitment timing under FDA accelerated approval pathways, cross-referenced against Basel facility expansion timelines and South Korean biocluster absorption capacity.
Underlying measurement precision varies by segment; viral vector manufacturing carries tighter precision than plasmid DNA services due to visible capacity reservation contracts. Forecasts reflect assumptions regarding regulatory convergence between FDA and EMA on potency assay standards, EMA national competent authority interpretation stability, and agricultural commodity price cycle amplitude. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
Cell and Gene Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Stem Cell Therapy Market