
 Argentina Artificial Organs and Bionic Implants Market | 2026-2036
Argentina Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Artificial Organs and Bionic Implants Market Outlook
Premium biocompatible materials and commodity-grade synthetic alternatives is decoupling across Argentina's procurement landscape. Medtronic PLC leverages its established cardiac rhythm management infrastructure to sustain dominant positioning in pacemaker and ventricular assist device segments. Edwards Lifesciences anchors its presence through specialized heart valve platforms that compete on hemodynamic performance metrics. Abbott Laboratories differentiates via integrated vascular closure and structural heart portfolios that occupy premium hospital contract tiers.
Artificial organs and bionic implants encompass electromechanical and biological substitute systems engineered to restore or augment physiological functions, typically incorporating titanium alloys, pyrolytic carbon, or silicone elastomers in their fabrication. These devices serve critical therapeutic purposes across cardiac, auditory, renal, and musculoskeletal domains where endogenous organ failure or limb loss demands functional replacement. Cochlear implant adoption is accelerating fastest among pediatric populations with congenital hearing deficits, where early intervention protocols are expanding through Argentina's national disability coverage mandates. Bionic limb segments command concentrated margin pools in private rehabilitation channels, while artificial kidney development remains nascent amid dialysis infrastructure dominance. Heart valve platforms sustain mature volume leadership through established surgical and transcatheter delivery modalities.
ANMAT, Argentina's national medical device regulator, enforces post-market surveillance and import licensing requirements that shape product registration timelines and commercial entry strategies for multinational manufacturers. The country's alignment with Mercosur harmonized technical standards, supplemented by WHO prequalification pathways for priority medical devices, creates layered compliance obligations that filter market participants by documentation capacity and local quality system investments. Stakeholders must monitor ANMAT's convergence with international reference regulatory frameworks to anticipate streamlined approval mechanisms that could reshape competitive access dynamics.
Market Dynamics
ANMAT's compressed registration timelines for cardiac assist devices are redistributing competitive access toward multinationals with established Buenos Aires distribution infrastructure.
Growth Catalysts
- ANMAT pathway acceleration:Streamlined import licensing for WHO-prequalified cardiac devices reduces commercial entry friction for manufacturers with Mercosur technical documentation.
- Buenos Aires tertiary concentration:Provincial hospital networks expanding ventricular assist device coverage create procurement pull for advanced cardiac platforms.
- Cochlear implant protocols:National disability coverage mandates for pediatric congenital hearing deficits are expanding early intervention surgical volumes.
Market Restraints
- Titanium alloy import dependency:Biocompatible metal supply concentrates in North American and European foundries, exposing Argentine manufacturers to currency volatility and shipping delays.
- Dialysis infrastructure lock-in:Mature hemodialysis center networks delay artificial kidney adoption by sustaining incumbent treatment economics.
- Specialized surgical capacity scarcity:Transcatheter heart valve procedures require interventional cardiologists concentrated in Buenos Aires metropolitan hospitals.
Strategic Opportunities
- Cordoba and Mendoza expansion:Secondary city hospital upgrades present first-mover positioning for bionic limb rehabilitation channels outside capital province concentration.
- Neural interface convergence:Brain-computer interface development for prosthetic motor control is converging with Argentina's emerging neurotechnology research clusters.
- Private insurance tier penetration:Prepaid medicine plans expanding coverage for premium cochlear and cardiac implant tiers unlock patient-funded procedure volumes.
Industry Challenges
- Biomedical engineer scarcity:Device servicing and clinical specialist training programs lag implant technology complexity, constraining post-implant support capacity.
- ANMAT quality system audits:Local manufacturing investments face extended certification timelines for ISO 13485 compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Artificial Organs and Bionic Implants Market |
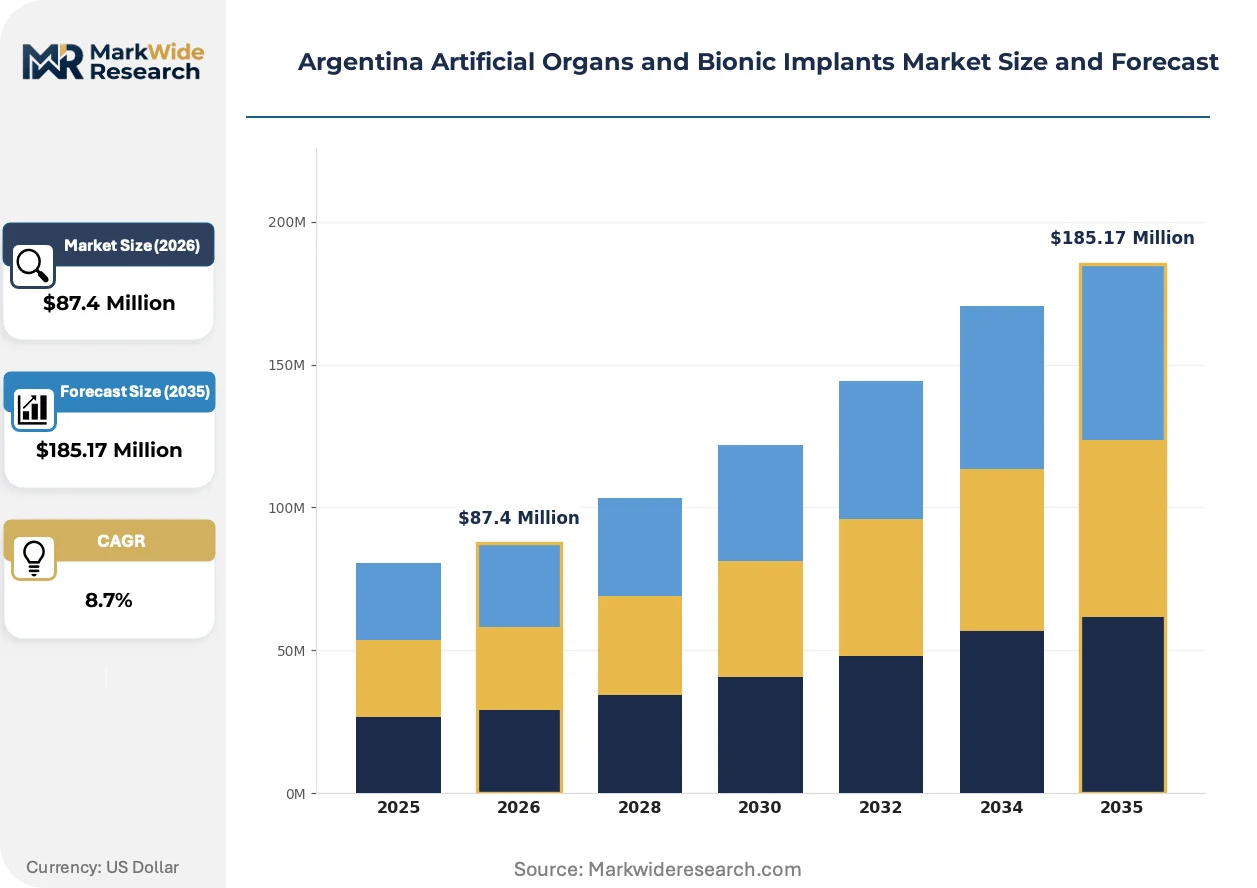
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Valve, Cochlear Implant, Bionic Limb, Artificial Kidney Technology: 3D Printing, Bioengineering, Nanotechnology, Robotics End User: Clinics, Hospitals, Rehabilitation Centers, Research Institutions Regulatory Approval: FDA Approved, CE Marked, WHO Certified, Others |
| Companies Covered | LivaNova PLC, Abiomed Inc., Medtronic PLC, Edwards Lifesciences, Berlin Heart GmbH, Abbott Laboratories Inc., Ottobock SE & Co. KGaA, SynCardia Systems LLC, Cochlear Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Artificial Organs and Bionic Implants Market Strategic Shifts
Electromechanical implant fabrication is converging with biological scaffold engineering, compressing the boundary between synthetic and regenerative therapeutic approaches across Argentine cardiac and musculoskeletal segments.
Pyrolytic carbon heart valve construction is converging with transcatheter delivery systems, enabling structural heart interventions in catheterization laboratories lacking open-heart surgical infrastructure. Buenos Aires cardiac centers are adopting these platforms fastest, compressing referral patterns toward metropolitan interventional hubs and marginalizing provincial thoracic surgery departments.
ANMAT's alignment with Mercosur harmonized technical standards is compressing documentation requirements for manufacturers holding European CE marking or US FDA clearance. This regulatory convergence reduces redundant testing burdens for cardiac rhythm management devices, though local post-market surveillance obligations remain stringent for implantable pulse generators.
Public hospital procurement is fragmenting across decentralized provincial purchasing committees, displacing historical centralized Ministry of Health tender concentration. Cochlear implant vendors now navigate heterogeneous contracting protocols across Buenos Aires, Cordoba, and Santa Fe health systems, with private channel direct-to-hospital sales gaining share from distributor intermediaries.
Argentina Artificial Organs and Bionic Implants Market Segmentation
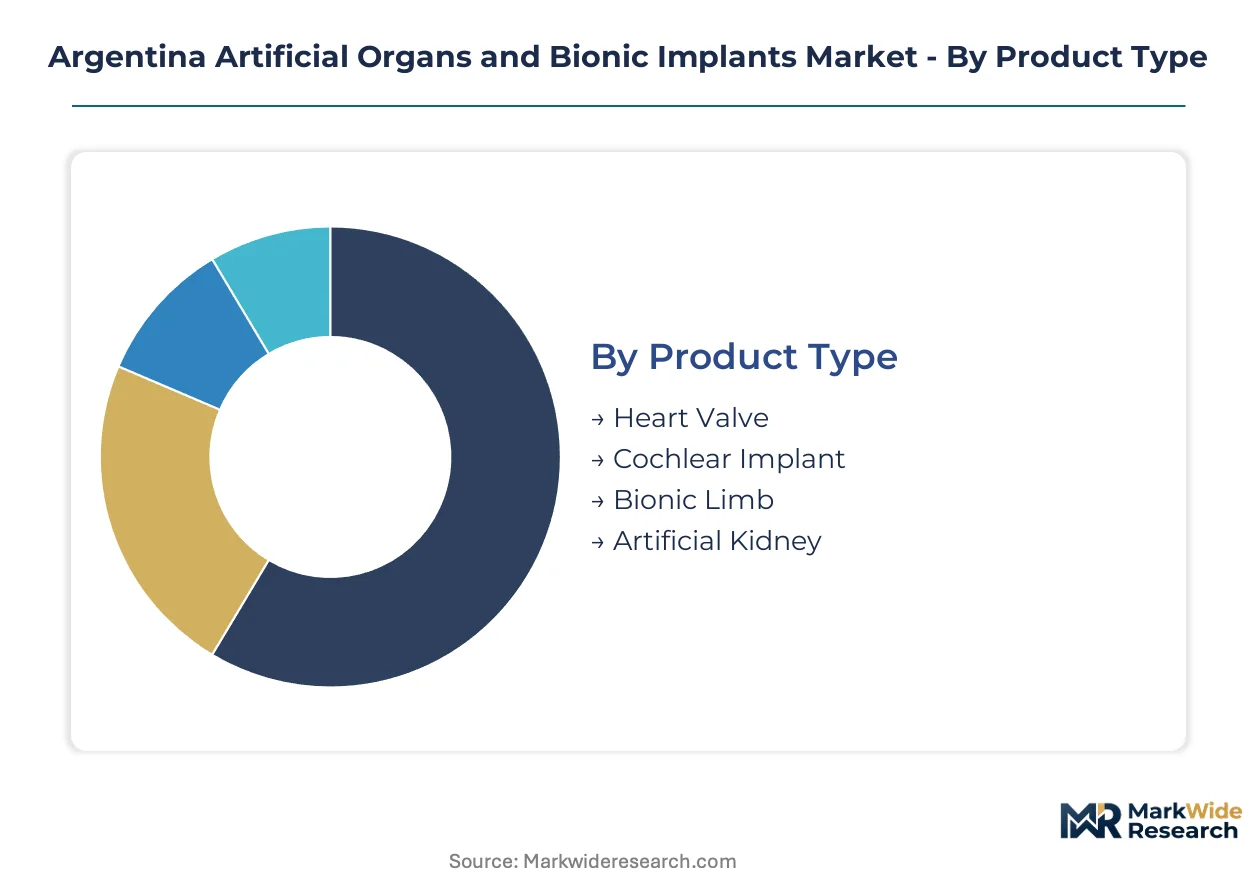
Segmentation in Argentina's artificial organs and bionic implants market reveals how procurement pathways, clinical infrastructure, and regulatory alignment concentrate demand across distinct technology tiers. Understanding these divides exposes where multinational manufacturers anchor volume versus where local distributors capture margin.
Product Type:
Material composition and implant longevity specifications determine reimbursement eligibility across Argentina's fragmented public and private payment systems.
- Heart Valve:Pyrolytic carbon and biological tissue constructs dominate Buenos Aires tertiary centers where transcatheter delivery platforms bypass open-heart surgical capacity constraints. Provincial hospital networks concentrate mechanical valve procurement where interventional cardiologist scarcity limits catheter-based alternatives.
- Cochlear Implant:Electrode array systems with 22+ channel configurations capture pediatric volumes under national disability coverage mandates for congenital hearing deficits. Speech processor upgrade cycles sustain recurring revenue in private rehabilitation channels outside public procurement.
- Bionic Limb:Myoelectric upper-extremity systems concentrate in Cordoba and Mendoza private rehabilitation centers where prepaid medicine plans cover premium prosthetic tiers.
- Artificial Kidney:Wearable and implantable renal replacement devices remain pre-commercial amid hemodialysis center network lock-in across Argentina's provinces.
Mature deployment sits with heart valve platforms. Newer deployment is concentrated in cochlear implant pediatric protocols.
Technology:
Manufacturing process sophistication filters market access through ANMAT's quality system audit requirements and Mercosur technical documentation standards.
- 3D Printing:Patient-specific titanium alloy scaffolds for craniofacial and orthopedic reconstruction concentrate in Buenos Aires university hospital networks with established biomedical engineering partnerships.
- Bioengineering:Decellularized tissue matrices and stem cell-seeded constructs occupy research institution procurement channels with limited commercial scale amid regulatory uncertainty for biological-device combination products.
- Nanotechnology:Antimicrobial surface coatings and drug-eluting implant modifications penetrate cardiac and orthopedic segments where infection resistance commands premium pricing in private hospital contracts.
- Robotics:Surgical robot compatibility requirements shape implant design specifications for hip and knee arthroplasty systems deployed in capital province tertiary centers.
Volume leadership belongs to 3D printing applications. Steepest expansion trajectory is emerging in nanotechnology surface engineering.
End User:
Procurement authority concentration and reimbursement pathway structure determine pricing power and contract duration across Argentine healthcare delivery sites.
- Hospitals:Tertiary public hospital networks in Buenos Aires province aggregate cardiac assist device demand through centralized Ministry of Health tenders, while private hospital direct purchasing gains share from distributor intermediaries.
- Rehabilitation Centers:Bionic limb fitting and cochlear implant programming services concentrate margin pools in prepaid medicine plan networks where patient-funded upgrades bypass public procurement delays.
- Clinics:Specialized cardiac and audiology clinics in metropolitan Buenos Aires capture diagnostic and post-implant monitoring volumes with faster procedure scheduling than hospital-based alternatives.
- Research Institutions:Preclinical and early clinical trial activity for neural interface and bioengineered organ platforms clusters at CONICET-affiliated centers with ANMAT pilot study approvals.
Contract stability favors hospital procurement. Margin expansion is concentrating in rehabilitation center direct sales.
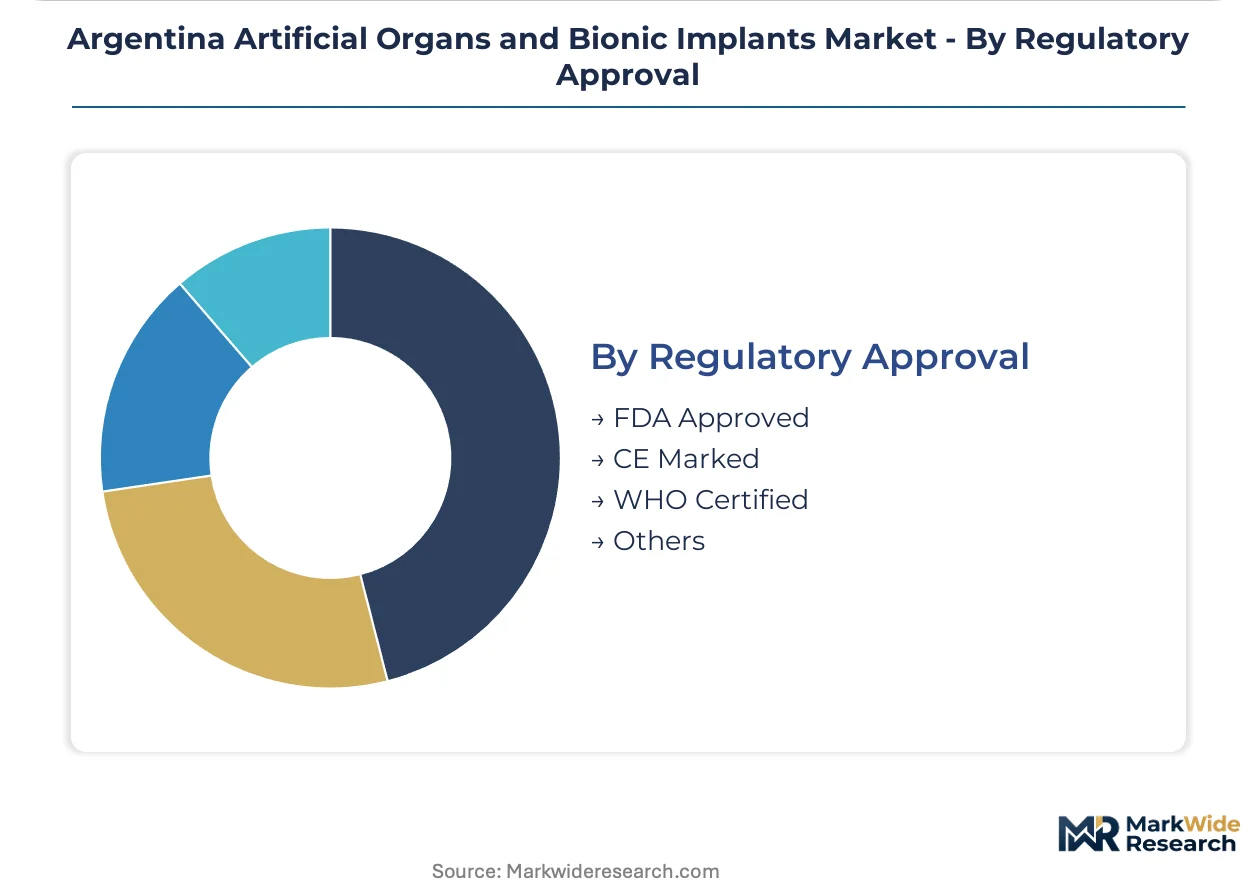
Regulatory Approval:
Documentation pathway efficiency shapes commercial entry speed and competitive positioning for imported implant manufacturers.
- CE Marked:European Union medical device regulation compliance enables streamlined Mercosur technical standard recognition, compressing ANMAT registration timelines for cardiac rhythm management and structural heart devices.
- WHO Certified:Prequalification status for priority medical devices accelerates import licensing for cochlear implants and cardiac assist systems in public health system tenders.
- FDA Approved:United States clearance provides reference regulatory framework acceptance though redundant local testing requirements persist for implantable pulse generators.
- Others:Health Canada, Swissmedic, and TGA approvals occupy secondary reference status with case-by-case ANMAT evaluation timelines.
Fastest market access sits with CE marked devices. Emerging priority is attaching to WHO certification for public sector procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buenos Aires province concentrates Argentina's artificial organ procurement through tertiary hospital networks and specialized interventional cardiology capacity.
Buenos Aires Province
Public hospital networks expand ventricular assist device coverage through centralized Ministry of Health tenders. ANMAT's streamlined registration for WHO-prequalified cardiac devices accelerates import licensing for metropolitan medical centers. The capital province anchors transcatheter heart valve adoption where interventional cardiologist density enables catheter-based structural heart procedures.
Cordoba
Private rehabilitation centers capture bionic limb fitting volumes under expanding prepaid medicine plan coverage. Secondary city hospital upgrades create first-mover positioning for myoelectric prosthetic channels outside capital concentration. The Sierras de Cordoba region clusters neurotechnology research activity with CONICET-affiliated neural interface development.
Mendoza
Prepaid medicine networks in this western province unlock patient-funded cochlear implant procedures bypassing public procurement delays. Tertiary hospital infrastructure expansion supports cardiac assist device penetration beyond traditional Buenos Aires referral patterns. The Greater Mendoza metropolitan area concentrates private audiology clinic capacity for post-implant programming services.
Santa Fe
Decentralized provincial purchasing committees fragment cochlear implant contracting protocols from historical centralized tenders. Rosario's university hospital network maintains biomedical engineering partnerships for patient-specific 3D-printed orthopedic scaffold fabrication. The Parana River corridor sustains dialysis center network dominance that delays artificial kidney commercial adoption.
Argentina Artificial Organs and Bionic Implants Market Competitive Environment
Premium-margin players sit above commodity-margin players across material certification tiers and regulatory documentation sophistication. Market structure concentrates around multinational manufacturers with established Mercosur technical standard compliance and Buenos Aires distribution infrastructure. Three archetypes dominate: integrated cardiac rhythm management specialists, structural heart platform providers, and rehabilitation-focused prosthetic fabricators. Competitive moves center on direct-to-hospital contract displacement of distributor intermediaries and portfolio expansion into transcatheter delivery modalities.
Within the integrated cardiac management tier, Medtronic PLC and Abbott Laboratories occupy positions anchored by established ANMAT registration pathways and public tender participation. Edwards Lifesciences exemplifies structural heart specialization through hemodynamic performance-focused platform positioning. Among European fabricators, Berlin Heart GmbH represents mechanical circulatory support archetypes with concentrated pediatric and adult ventricular assist device presence.
| Leading Market Players |
|---|
| LivaNova PLC |
| Abiomed Inc. |
| Medtronic PLC |
| Edwards Lifesciences |
| Berlin Heart GmbH |
| Abbott Laboratories Inc. |
| Ottobock SE & Co. KGaA |
| SynCardia Systems LLC |
| Cochlear Limited |
| Others |
Value Chain & Pricing Dynamics
ANMAT's ISO 13485 quality system certification mandates gate both qualified titanium alloy supply and premium-tier cardiac implant pricing access, compressing margins for manufacturers lacking verified biocompatible metal sourcing while elevating reimbursement rates for compliant device tiers.
Pricing Analysis
Outcome-based pricing anchors cardiac assist device contracts, with ventricular assist device procurement tied to post-implant survival metrics and rehospitalization rates. Three-tier pricing structure across premium, standard, and economy levels separates pyrolytic carbon mechanical valves from biological tissue constructs and commodity synthetic alternatives. Pricing pressure stems from Buenos Aires provincial hospital networks consolidating tenders around volume commitments. Public sector procurement committees exhibit highest price sensitivity, while prepaid medicine plan networks absorb premium tiers for cochlear and bionic limb segments.
Supply Chain Analysis
Regional distribution centers in Buenos Aires province anchor hub-and-spoke patterns for cardiac rhythm management devices, with satellite stocking points in Cordoba and Mendoza serving secondary city hospital networks. Titanium alloy feedstock concentrates in United States, German, and Japanese foundries, exposing Argentine manufacturers to currency volatility and maritime shipping delays. Pyrolytic carbon blanks and silicone elastomer components draw from specialized European and North American suppliers. Single-source vulnerability in biocompatible metal supply chains threatens production continuity for implantable pulse generators. Distribution runs through authorized distributor networks with direct-to-hospital sales gaining share in private channel cardiac valve procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized surgical capacity scarcity props cardiac implant pricing, with interventional cardiologist concentration in Buenos Aires metropolitan hospitals limiting supply expansion regardless of device availability.
For Market Incumbents: To counter emerging neurotechnology entrants in neural interface prosthetics, Medtronic PLC and Abbott Laboratories should deepen backward integration into titanium alloy sourcing through captive supply agreements with Mercosur-compliant foundries. Certification investment in WHO prequalification pathways for pediatric cochlear implant platforms will defend public tender positioning against European competitors with streamlined ANMAT registration. For New Entrants and Emerging Players: Brain-computer interface development for myoelectric prosthetic motor control offers technology-first wedge positioning in Cordoba's CONICET-affiliated neurotechnology clusters. Secondary city rehabilitation centers in Mendoza and Santa Fe represent the most penetrable geography, with prepaid medicine plan networks bypassing consolidated Buenos Aires procurement. Go-to-market execution should prioritize direct audiology clinic partnerships for cochlear implant programming services outside hospital-based channels. For Investors and Strategic Acquirers: ANMAT's convergence with Mercosur harmonized technical standards is the leading indicator that European CE-marked cardiac device manufacturers will accelerate commercial entry, compressing first-mover returns for early-stage local assemblers. Long-term viability across the analysis window favors integrated cardiac rhythm management specialists with established Buenos Aires distribution infrastructure and ISO 13485 quality system verification. Acquisition targets should display vertical integration into biocompatible material sourcing or proprietary transcatheter delivery platform IP.| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT Registration Pathway Acceleration | WHO-prequalified cardiac devices gain streamlined import licensing for Buenos Aires tertiary centers. |
| Backward Integration into Titanium Sourcing | Captive biocompatible metal supply buffers currency volatility for implant manufacturers. |
| Direct-to-Hospital Contract Displacement | Private cardiac valve procurement bypasses distributor intermediaries in metropolitan networks. |
| Pediatric Cochlear Protocol Expansion | National disability coverage mandates unlock early intervention surgical volumes outside public tender delays. |
| Neural Interface R&D Partnership | CONICET-affiliated clusters in Cordoba converge brain-computer interface development with prosthetic motor control. |
Study Parameters
Multi-period observation of ANMAT registration timelines, hospital procurement contract awards, and cochlear implant surgical volumes anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and prepaid medicine plan executives. Secondary validation drew from ANMAT medical device registration databases, Ministry of Health tender disclosures, CONICET research institution procurement records, and Mercosur technical standard harmonization documents. Bottom-up implant volume modeling triangulated against top-down healthcare expenditure allocation estimates.
Input-output matrices mapped biocompatible material supply flows to finished device production across the projection horizon, with segmentation dimensions spanning product type, technology tier, end-user channel, and regulatory approval pathway. CAGRs derived from fitted growth curves applied to base-year implant procedure counts, adjusted for provincial hospital infrastructure expansion rates and prepaid medicine plan coverage penetration. Forecast inputs incorporated interventional cardiologist density projections and titanium alloy import cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANMAT regulatory divergence from Mercosur standards or acute biocompatible metal supply disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Bioprosthetics Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market