
 Global Gene Therapy Cell Culture Media Market | 2026-2036
Global Gene Therapy Cell Culture Media Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gene Therapy Cell Culture Media Market Foresight
The direct sales channel is reconfiguring as gene therapy developers seek co-development partnerships with media suppliers rather than transactional purchasing. Thermo Fisher Scientific leverages its dual role as instrument and reagent provider to lock in multi-year supply agreements. Lonza Group Ltd anchors its position through integrated CDMO-media bundling that reduces client qualification burden. Merck KGaA competes by sustaining GMP-grade production capacity across three continents.
Gene therapy cell culture media comprises nutrient formulations engineered to support the propagation of mammalian cells used in viral vector production and cell-based therapeutics, typically containing amino acids, vitamins, inorganic salts, glucose, and pH buffering systems at osmolalities between 280-320 mOsm/kg. Serum-free media dominates current procurement volumes as regulatory agencies restrict animal-derived component use in clinical-grade manufacturing. Chemically defined media commands the fastest expansion trajectory among product types, driven by its elimination of lot-to-lot variability that plagues hydrolysate-supplemented alternatives. CAR-T cell production and viral vector manufacturing represent the most contested application segments, with biopharmaceutical companies and contract manufacturing organizations splitting procurement authority between captive supply and outsourced media qualification.
The FDA's gene therapy CMC guidance and EMA's ATMP framework jointly determine raw material sourcing standards, while ISO 13485 certification shapes supplier eligibility for commercial-stage contracts. The EU AI Act introduces emerging compliance dimensions for automated bioprocess monitoring systems that media vendors increasingly embed. Stakeholders must weigh captive media development against supplier diversification as regulatory stringency escalates and manufacturing scale-out accelerates.
Market Dynamics
Biopharmaceutical manufacturers are consolidating viral vector production in-house, forcing media suppliers to restructure from transactional vendors into co-development partners with multi-year qualification commitments.
Growth Catalysts
- FDA CMC Guidance:Tightened raw material qualification requirements for gene therapy products compel manufacturers to source GMP-grade media with documented traceability, elevating certified suppliers above commodity alternatives.
- Serum-free formulation:Regulatory restrictions on animal-derived components in clinical manufacturing accelerate adoption of chemically defined media, eliminating lot-to-lot variability that plagues hydrolysate-supplemented formulations.
- Boston-San Diego corridor:Clustered cell therapy hubs in these metropolitan areas concentrate procurement volumes, creating localized demand density that supports dedicated media manufacturing facilities.
Market Restraints
- Chinese hamster ovary cell line dependency:Viral vector production remains tethered to CHO and HEK293 substrate limitations, constraining yield improvements regardless of media optimization.
- Single-source supplier concentration:GMP-grade raw material production concentrates among European and North American chemical manufacturers, exposing buyers to geopolitical supply disruptions.
- EMA ATMP framework friction:Divergent starting material definitions between FDA and EMA create dual qualification burdens for developers pursuing transatlantic commercialization.
Strategic Opportunities
- India CDMO expansion:Contract manufacturing organizations in Hyderabad and Bengaluru are scaling gene therapy capabilities, creating demand for qualified media suppliers with local stocking infrastructure.
- Automated bioprocess monitoring:EU AI Act compliance requirements for embedded analytics create white space for media vendors integrating real-time metabolite sensing into formulation platforms.
- Allogeneic cell therapy:Off-the-shelf therapeutic formats require media formulations optimized for master cell bank expansion rather than patient-specific batches, opening formulation specialization opportunities.
Industry Challenges
- Cell culture scientist scarcity:Viral vector manufacturing expertise concentrates among professionals with decade-plus experience, constraining operational scaling for new production facilities.
- ISO 13485 certification timeline:Supplier qualification for commercial-stage contracts requires 18-24 month audit cycles, compressing competitive windows for emerging media developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gene Therapy Cell Culture Media Market |
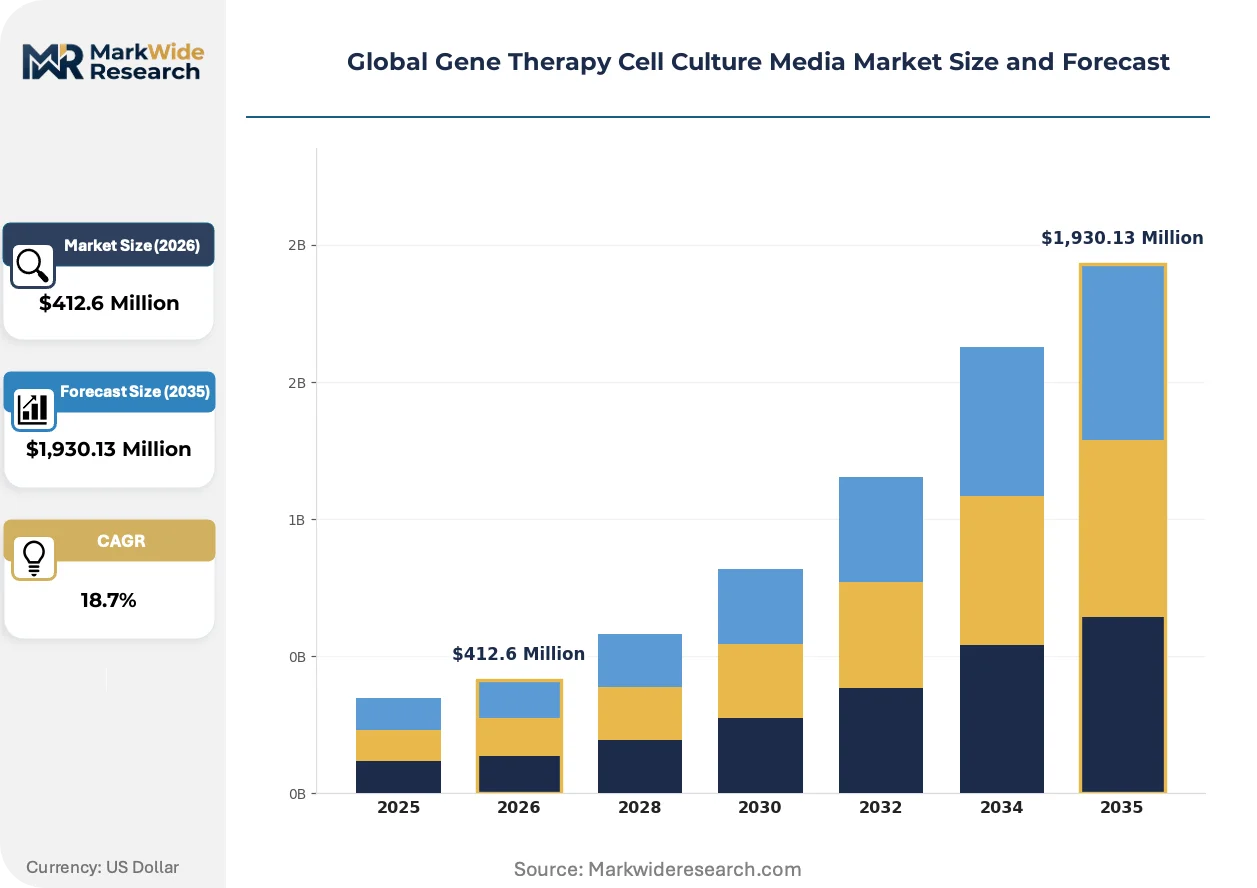
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum-Free Media, Chemically Defined Media, Supplemented Media, Basal Media, Specialized Media Application: Gene Editing, CAR-T Cell Production, Stem Cell Expansion, Viral Vector Manufacturing, Immunotherapy Development End User: Biopharmaceutical Companies, Contract Manufacturing Organizations, Academic Research Institutes, Cell Therapy Centers, Biotechnology Startups Distribution Channel: Direct Sales, Online Sales, Distributors, Specialty Suppliers, Laboratory Supply Companies |
| Companies Covered | Thermo Fisher Scientific Inc., Lonza Group Ltd, Merck KGaA, Sartorius AG, FUJIFILM Irvine Scientific, Cytiva, Corning Incorporated, Bio-Techne Corporation, HiMedia Laboratories Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gene Therapy Cell Culture Media Market Shifts & Advancements
Gene therapy manufacturing is bifurcating between centralized commercial-scale facilities and distributed patient-specific production, forcing media suppliers to engineer formulations compatible with both paradigms.
Perfusion-compatible media is hybridizing static and dynamic culture requirements through optimized nutrient density and shear-stress protective additives. Contract manufacturers adopting continuous processing platforms are piloting these formulations at 50-200 liter scales. The technology is hybridizing batch and perfusion economics, enabling single facility flexibility across clinical and commercial manufacturing modalities.
REACH registration requirements for novel chemical entities in cell culture media are extending supplier qualification timelines for European market access. The regulation forces reformulation of proprietary additives into pre-registered component libraries. CDMOs with EU commercial aspirations are prioritizing media suppliers with established REACH dossiers over novel formulation innovators.
Buyers are consolidating media procurement under single-source co-development agreements with multi-year exclusivity provisions. Viral vector developers are displacing spot purchasing with integrated supply partnerships that bundle formulation optimization, regulatory documentation, and volume commitments. This concentration is most visible among late-clinical-stage biopharmaceutical companies in the United States seeking to secure supply chains ahead of BLA submission.
Global Gene Therapy Cell Culture Media Market Segmentation
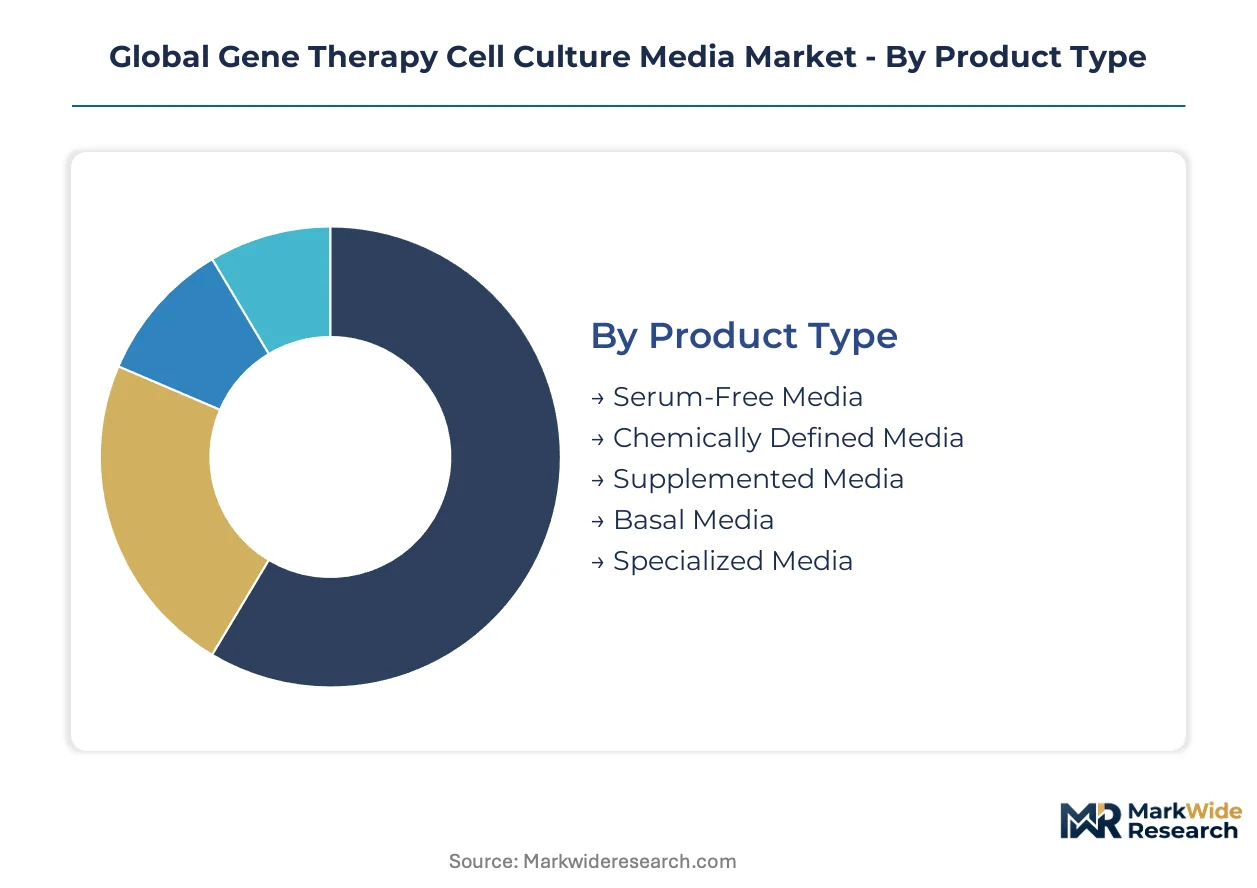
Gene therapy cell culture media segmentation reflects divergent qualification burdens across manufacturing modalities. Suppliers calibrate formulation complexity, documentation packages, and technical service intensity to match the operational maturity of each buyer segment.
Product Type:
After-sales service intensity escalates with formulation complexity, as chemically defined media require extensive lot-release documentation and application troubleshooting that commodity basal formulations do not.
- Serum-Free Media:Formulations eliminate bovine serum albumin and other animal-derived proteins through recombinant growth factor supplementation. Procurement concentrates among viral vector manufacturers in the United States seeking to satisfy FDA CMC guidance on adventitious agent control. Lot-to-lot consistency demands drive preference toward suppliers with dedicated regulatory affairs support teams.
- Chemically Defined Media:Every constituent carries molecular identification with validated concentration ranges, eliminating hydrolysate variability. Demand clusters at CAR-T developers in Boston and San Diego requiring traceable supply chains for IND-enabling studies. EMA ATMP framework compliance adds European documentation requirements that extend supplier qualification timelines.
- Supplemented Media:Basal formulations enhanced with proprietary growth factor cocktails or lipid mixtures.
- Basal Media:Standard nutrient formulations without growth supplements, serving research-scale applications.
- Specialized Media:Custom-engineered formulations for specific cell lines or viral vector serotypes.
By volume, serum-free media leads. By growth pace, chemically defined media is climbing the fastest.
Application:
Cost tier stratification separates commodity research-grade formulations from GMP-qualified media carrying 3-5x price premiums for commercial manufacturing.
- Viral Vector Manufacturing:AAV and lentiviral production platforms require media optimized for suspension-adapted HEK293 cell lines with high plasmid transfection efficiency. Procurement authority concentrates at CDMOs in Hyderabad scaling to serve European and North American sponsors. Perfusion-compatible formulations command premium positioning for continuous processing adoption.
- CAR-T Cell Production:Patient-specific autologous manufacturing demands media supporting rapid T-cell expansion while maintaining functional potency. Demand density in the Boston-San Diego corridor supports regional media manufacturing investments. Allogeneic off-the-shelf programs are shifting formulation requirements toward master cell bank expansion protocols.
- Gene Editing:CRISPR-Cas9 delivery via viral or non-viral methods requires media maintaining high cell viability during nuclease expression.
- Stem Cell Expansion:Pluripotent and mesenchymal stem cell cultures need defined conditions preserving differentiation potential.
- Immunotherapy Development:NK cell and tumor-infiltrating lymphocyte protocols use media formulations adapted from CAR-T platforms.
By current procurement volume, viral vector manufacturing dominates. By expansion trajectory, CAR-T cell production is gaining share fastest.
End User:
Customer type determines contract structure, with biopharmaceutical companies negotiating multi-year co-development agreements while academic institutes transact through catalog distributors.
- Biopharmaceutical Companies:Late-clinical-stage developers consolidate procurement under single-source partnerships bundling formulation optimization, regulatory documentation, and volume commitments. Thermo Fisher Scientific and Lonza Group Ltd have captured significant share through integrated instrument-reagent and CDMO-media bundling strategies. BLA submission timelines drive urgency for qualified supplier lock-in.
- Contract Manufacturing Organizations:CDMOs require media suppliers capable of supporting technology transfer across multiple client programs with divergent cell line requirements. Indian CDMOs in Hyderabad and Bengaluru are scaling gene therapy capabilities and creating demand for suppliers with local stocking infrastructure. Multi-client flexibility prioritizes formulation breadth over customization depth.
- Academic Research Institutes:Price-sensitive procurement through laboratory supply distributors with limited technical service expectations.
- Cell Therapy Centers:Hospital-affiliated manufacturing facilities with mixed research and clinical production needs.
- Biotechnology Startups:Early-stage companies prioritizing speed-to-clinic over long-term supply security.
By contract value, biopharmaceutical companies lead. By growth in procurement events, contract manufacturing organizations are expanding most quickly.
Distribution Channel:
Supply concentration favors direct relationships for GMP-grade media, while research-grade volumes flow through distribution intermediaries.
- Direct Sales:Supplier field organizations manage multi-year qualification programs with dedicated account scientists supporting regulatory submission documentation. Merck KGaA leverages three-continent GMP production capacity to anchor direct relationships with transatlantic developers. Co-development partnerships displace transactional purchasing among viral vector manufacturers.
- Distributors:Regional stocking infrastructure enables just-in-time delivery for CDMOs with unpredictable campaign scheduling. Indian and European distributors are building gene therapy media capabilities to capture CDMO expansion demand. REACH registration requirements favor distributors with established chemical compliance dossiers.
- Online Sales:E-commerce platforms serve research-scale procurement with rapid fulfillment and minimal technical support.
- Specialty Suppliers:Niche providers focused on specific cell lines or geographic markets.
- Laboratory Supply Companies:Broad-catalog distributors handling commodity basal and supplemented media.
By revenue concentration, direct sales leads. By channel growth, distributors are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by 40-60% for GMP-grade formulations, while Indian CDMOs capture cost arbitrage on research-grade volumes. This asymmetry shapes supplier investment patterns across manufacturing tiers.
United States
FDA CMC guidance on raw material traceability drives procurement toward certified GMP-grade media with documented supply chains. The Boston-San Diego corridor concentrates viral vector and CAR-T manufacturing, with clustered biopharmaceutical facilities commanding dedicated media production investments. Late-clinical-stage developers lock in multi-year supply agreements ahead of BLA submissions.
Germany
REACH registration requirements for novel chemical entities extend supplier qualification timelines, favoring established media vendors with pre-registered component libraries. EMA ATMP framework compliance adds documentation burdens for transatlantic developers. The Rhine-Main and Munich biotech clusters anchor demand for chemically defined media in commercial-scale manufacturing.
India
CDMO expansion in Hyderabad and Bengaluru creates demand for qualified media suppliers with local stocking infrastructure. CDSCO oversight of cell therapy products is tightening starting material standards, compressing competitive windows for uncertified suppliers. Domestic manufacturers leverage cost structures 30-40% below US benchmarks to capture outsourced viral vector campaigns.
Switzerland
Swissmedic's alignment with EMA standards streamlines commercial qualification for ATMP-bound media formulations. The Basel-Zurich biopharma corridor hosts concentrated gene therapy R&D, with multinational headquarters driving procurement authority for global supply networks. Specialized media developers target the region's precision manufacturing ecosystem for technology partnerships.
United Kingdom
Post-Brexit divergence from EMA frameworks creates dual regulatory tracks for media suppliers serving UK and EU markets simultaneously. The Golden Triangle research cluster sustains demand for chemically defined media in early-stage gene editing programs. MHRA guidance on novel therapy manufacturing is converging with FDA standards, simplifying transatlantic supplier qualification.
Global Gene Therapy Cell Culture Media Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The supplier base organizes around three archetypes: diversified life science conglomerates bundling instrumentation with consumables, CDMO-anchored media developers offering integrated qualification services, and pure-play formulation specialists competing on regulatory documentation depth. Consolidation pressure intensifies as viral vector manufacturers reduce supplier counts to secure multi-year supply security. Capacity expansion and co-development partnerships represent the dominant competitive moves, displacing transactional spot purchasing.
Among diversified platform providers, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the integrated instrument-reagent model, while Lonza Group Ltd occupies a position bridging CDMO services with captive media supply. These three anchors represent contrasting strategic postures: dual-role system provision, manufacturing-service bundling, and geographic production distribution respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Lonza Group Ltd |
| Merck KGaA |
| Sartorius AG |
| FUJIFILM Irvine Scientific |
| Cytiva |
| Corning Incorporated |
| Bio-Techne Corporation |
| HiMedia Laboratories Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
The transatlantic air freight corridor linking Frankfurt to Boston carries temperature-controlled media shipments at premium rates, with logistics costs cascading into GMP-grade pricing that separates qualified suppliers from commodity alternatives. This freight dynamic concentrates procurement power among buyers with volume commitments sufficient to secure dedicated cold-chain capacity, while smaller developers absorb spot-market volatility.
Pricing Analysis
The customization-premium spread reaches three-to-five multiples between configured-to-order chemically defined media and standard serum-free formulations. Pricing stratifies across GMP-certified, research-grade, and basal tiers, with FDA CMC compliance documentation commanding the widest premiums. Cost compression in research-grade segments intensifies as Indian CDMOs scale viral vector capabilities. Academic institutes exhibit highest price sensitivity; late-clinical-stage biopharmaceutical companies prioritize supply security over unit economics.
Supply Chain Analysis
Contract manufacturing concentration among Lonza Group Ltd, Thermo Fisher Scientific, and Sartorius AG anchors global GMP-grade media capacity. Production draws from Switzerland, Germany, and the United States, with raw material dependencies on amino acid precursors from Chinese fermentation facilities and recombinant growth factors from North American biotech suppliers. Single-source vulnerability concentrates in European chemical manufacturers for proprietary additives. Distribution runs through direct supplier field organizations for commercial contracts, with regional distributors capturing CDMO spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated viral vector developers locking in multi-year exclusivity, fragmenting procurement alternatives for smaller entrants. This concentration rewards suppliers with qualification depth while squeezing commodity vendors.
For Market Incumbents: Entrench through captive media development partnerships that embed formulation scientists within client manufacturing facilities. Expand GMP production capacity in the Boston-San Diego corridor to match demand density. Counter emerging pure-play specialists by bundling regulatory documentation services with volume commitments. For New Entrants and Emerging Players: Pursue white-space opportunities in allogeneic cell therapy media formulations optimized for master cell bank expansion. Target Indian CDMOs in Hyderabad and Bengaluru with local stocking infrastructure and REACH-registered component libraries. Differentiate through real-time metabolite sensing platforms that satisfy EU AI Act compliance requirements. For Investors and Strategic Acquirers: Pure-play formulation specialists with deep regulatory dossiers present acquisition targets with defensible moats. Long-term viability hinges on CDMO-media bundling capabilities across the analysis window. Monitor FDA BLA submission timelines as inflection indicators for supply agreement urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Development Partnership Formation | Locks in multi-year volume commitments ahead of regulatory submission deadlines. |
| GMP Capacity Expansion | Addresses FDA CMC guidance requirements for documented traceability and lot release. |
| REACH Dossier Investment | Accelerates European market access for novel chemically defined formulations. |
| Perfusion-Compatible Formulation Launch | Captures continuous processing adoption among contract manufacturers scaling viral vector output. |
| Automated Bioprocess Monitoring Integration | Aligns media platforms with EU AI Act compliance for embedded analytics systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cell culture scientists, viral vector manufacturing directors, regulatory affairs leads at gene therapy developers, and procurement managers at CDMOs. Secondary validation drew from FDA CMC guidance documents, EMA ATMP framework publications, ISO 13485 certification registries, and REACH registration databases. Bottom-up segment sizing triangulated against top-down market construction from trade flow analysis.
Calibration against historical capacity announcements and qualification timeline data anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type complexity, application modality, end-user operational maturity, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating BLA submission pipeline data and CDMO expansion announcements. Industry-specific inputs captured perfusion adoption rates and chemically defined media conversion trajectories.
Sensitivities concentrate around FDA guidance revisions, EMA ATMP framework harmonization delays, and CHO cell line yield breakthroughs that could displace media optimization value. Forecasts reflect documented assumptions on qualification timeline compression and supply chain regionalization. Quarterly review of BLA submission cadence and CDMO capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market