
 Plasma Protein System Market | 2026-2036
Plasma Protein System Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Protein System Market Analytics
The price-performance gap between premium immunoglobulin therapies and commodity albumin products is hardening as payers tighten reimbursement tiers. CSL Behring leverages its vertically integrated collection-to-finished-product network across multiple continents. Grifols sustains manufacturing scale through one of the industry's largest plasma fractionation footprints. Takeda anchors its position via specialized immunology portfolios that command differentiated pricing.
A plasma protein system encompasses the industrial infrastructure for collecting, fractionating, purifying, and delivering human blood-derived proteins—operating at temperatures between 2°C and 8°C through Cohn-Oncley cold ethanol precipitation or chromatographic methods—to yield therapeutics for coagulation, immune modulation, and volume replacement. Immunoglobulin fractions command the deepest margin pools due to chronic demand in primary immunodeficiency and neurological autoimmunity, while albumin remains a mature, volume-driven category with thinner returns. Hospital end users absorb the largest share of finished product volume, though research laboratories represent the fastest-growing outlet as cell and gene therapy applications multiply.
FDA enforces Current Good Manufacturing Practice standards for plasma-derived products, while EMA's MDR framework imposes stricter post-market surveillance and traceability obligations on European suppliers. The EU F-Gas Regulation also pressures cold-chain operators to phase down hydrofluorocarbon-based refrigeration systems, raising capital requirements for fractionation facilities. Stakeholders must weigh collection network expansion against escalating regulatory compliance costs when allocating capital across geographic footprints.
Market Dynamics
FDA and EMA cold-chain integrity mandates are compressing operating margins while forcing rapid infrastructure upgrades across fractionation networks. The structural force reshaping competitive economics is the collision between tightening temperature-control regulations and the capital intensity of plasma collection center expansion.
Growth Catalysts
- Chronic immunology demand:Primary immunodeficiency and neurological autoimmunity protocols in tertiary hospitals sustain multi-year immunoglobulin treatment cycles.
- EMA MDR traceability mandates:European post-market surveillance obligations are accelerating investment in digital chain-of-custody systems across fractionators.
- Cell therapy research surge:Academic medical centers and contract research organizations are expanding albumin and immunoglobulin offtake for cell culture media applications.
Market Restraints
- Source plasma scarcity:Donor recruitment costs and collection center licensing timelines constrain raw material throughput regardless of fractionation capacity.
- EU F-Gas phase-down:Hydrofluorocarbon refrigeration restrictions raise capital requirements for cold-chain infrastructure replacement in European facilities.
- Chromatographic resin pricing:Purification material input volatility compresses margin pools on high-purity immunoglobulin fractions.
Strategic Opportunities
- Gene therapy manufacturing partnerships:Plasma protein suppliers can anchor supply agreements with viral vector producers seeking serum-free media alternatives.
- Indian biologics infrastructure:CDSCO regulatory pathway maturation and government PLI scheme incentives create first-mover positioning for fractionation joint ventures.
- Continuous processing adoption:Integration of perfusion chromatography with Cohn-Oncley precipitation is reducing batch cycle times and facility footprint requirements.
Industry Challenges
- Qualified technician scarcity:cGMP-certified plasma processing specialists command premium wages, constraining multi-shift operations at newer facilities.
- Legacy system interoperability:Temperature-monitoring IoT deployments must interface with decades-old SCADA infrastructure without disrupting validated production environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Protein System Market |
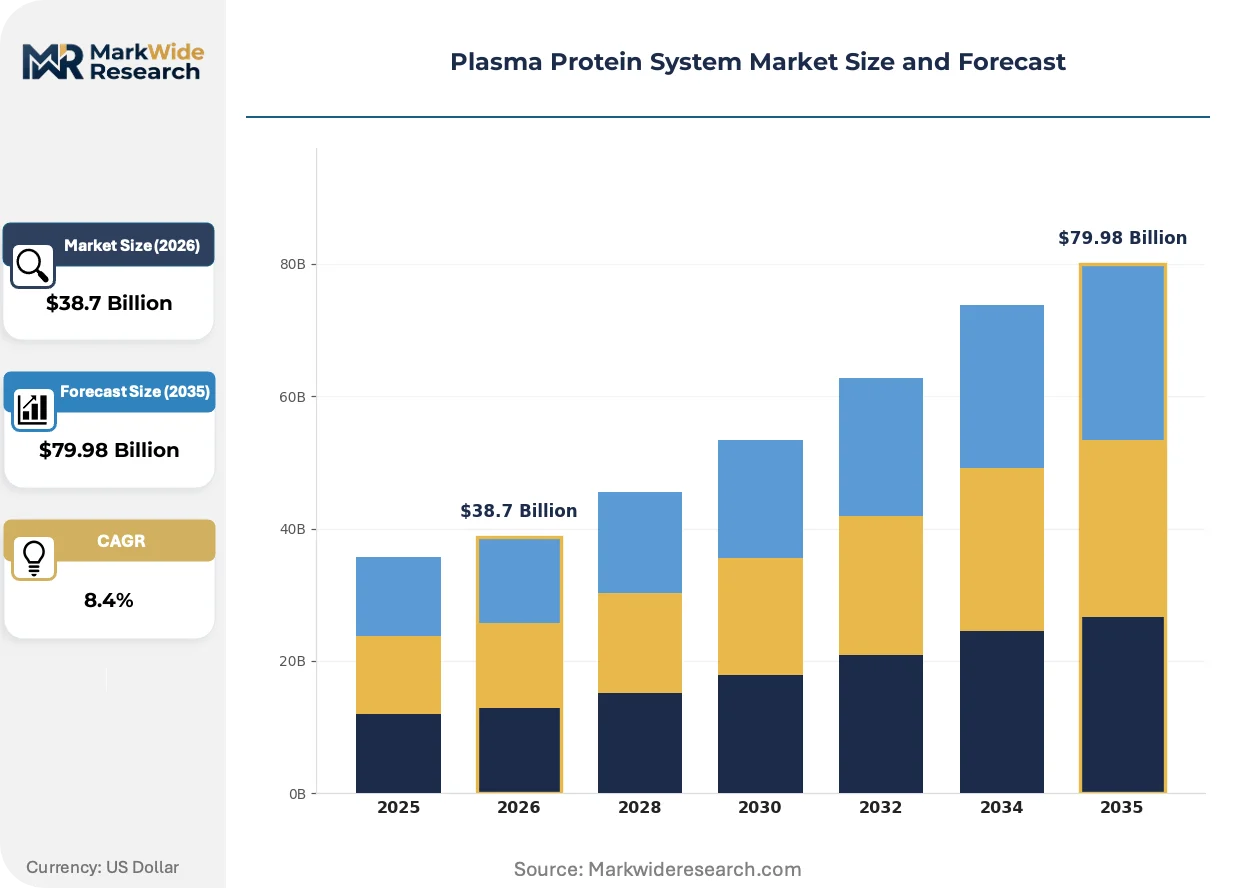
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Albumin, Globulins, Clotting Factors, Immunoglobulins End User: Hospitals, Clinics, Blood Banks, Research Laboratories Application: Transfusion, Genetic Disorders, Severe Burns, Immunotherapy Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | CSL Behring, Takeda Pharmaceutical Company Limited, Grifols, Octapharma, Kedrion Biopharma, Biotest, ADMA Biologics, Bio Products Laboratory, LFB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Protein System Market Evolving Landscape
Fractionation technology is pivoting from batch ethanol precipitation toward continuous chromatographic purification, compressing capital intensity per liter of finished immunoglobulin. This shift is redrawing facility design standards and supplier relationships across the value chain.
Capto MMC multimodal resin technology is integrating anion-exchange and hydrophobic interaction mechanisms into single-step immunoglobulin capture. Contract manufacturers in Germany and Switzerland are retrofitting existing Cohn-Oncley trains with these chromatography skids, reducing pool volumes and ethanol consumption. The structural consequence is that mid-scale fractionators can now achieve purity parity with legacy high-volume plants at one-third the tank farm footprint.
EMA's F-Gas Regulation is forcing cold-chain operators to abandon R-404A and R-507A refrigerants by 2030, accelerating adoption of CO2 transcritical systems and ammonia-based industrial refrigeration. Fractionation facilities in the Netherlands and Denmark are front-running this transition, securing regulatory goodwill and future-proofing their operating licenses. Albumin fill-finish lines with extended hold times are most exposed, as these stages require the tightest temperature bands.
Hospital procurement groups are consolidating immunoglobulin purchasing through specialty pharmacy benefit managers, unbundling traditional distributor relationships. Large integrated delivery networks in Texas and Florida are negotiating direct manufacturer contracts with quarterly volume commitments and penalty clauses for cold-chain excursions. This behavior is most pronounced in academic medical centers running high-volume neurology and hematology infusion centers.
Plasma Protein System Market Segmentation
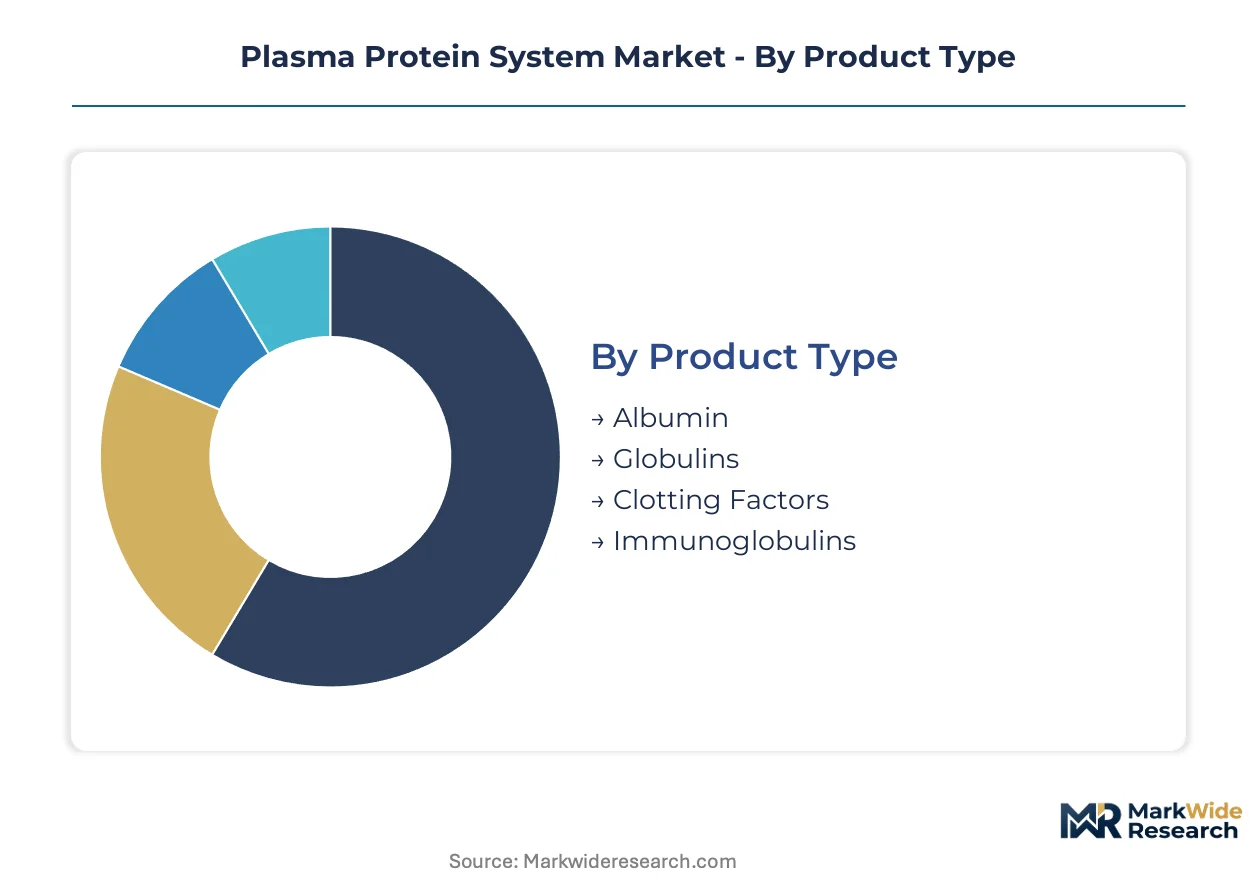
Plasma protein segmentation determines regulatory pathways, cold-chain specifications, and margin structures across fractionation networks. Each category channels capital toward distinct facility configurations and collection strategies.
Product Type:
FDA cGMP and EMA MDR impose divergent purity thresholds across these fractions, with immunoglobulins facing the most stringent viral inactivation protocols.
- Immunoglobulins:Polyclonal antibody concentrates derived from pooled plasma requiring dedicated chromatographic polishing steps. Tertiary hospitals in the United States absorb the bulk of intravenous immunoglobulin volume for chronic neurology and immunology protocols, though donor plasma scarcity constrains batch release schedules.
- Albumin:Heat-stabilized plasma protein fraction (4-5% concentration in pooled plasma) used for volume expansion and protein replacement. Burn centers and surgical suites in Germany and France command the largest European offtake, with EMA F-Gas refrigeration mandates raising storage capital costs for extended hold inventories.
- Globulins:Non-immunoglobulin plasma proteins including alpha-1 antitrypsin and ceruloplasmin fractions.
- Clotting Factors:Coagulation protein concentrates (Factors VIII, IX, fibrinogen) for hemophilia and surgical bleeding management.
Leading the category by volume: Albumin. Growing fastest: Immunoglobulins.
End User:
Procurement scale and temperature-monitoring sophistication separate institutional buyers, with research laboratories now demanding serum-free media-grade specifications.
- Hospitals:Integrated delivery networks running high-volume infusion centers negotiate direct manufacturer contracts with quarterly volume commitments and excursion penalty clauses. Academic medical centers in Texas and Florida unbundle traditional distributor relationships through specialty pharmacy benefit managers.
- Research Laboratories:Cell and gene therapy developers source pharmaceutical-grade albumin and immunoglobulins for viral vector production media. Contract research organizations in Switzerland and the Netherlands are expanding offtake fastest as perfusion bioreactor protocols multiply.
- Clinics:Outpatient infusion sites handling subcutaneous immunoglobulin administration for primary immunodeficiency patients.
- Blood Banks:Collection and distribution nodes managing fresh frozen plasma logistics before fractionation handoff.
Dominating procurement scale: Hospitals. Expanding most quickly: Research Laboratories.
Application:
Therapeutic indication dictates dosing frequency, reimbursement tier, and whether products command orphan drug pricing protections.
- Immunotherapy:Chronic intravenous or subcutaneous immunoglobulin replacement for primary immunodeficiency and autoimmune neuropathies. United States tertiary centers sustain multi-year treatment cycles with the deepest margin pools across all application areas.
- Genetic Disorders:Enzyme replacement and coagulation factor therapies for hemophilia, alpha-1 antitrypsin deficiency, and hereditary angioedema. European reference networks in France and Italy concentrate demand for these high-cost, low-volume therapies.
- Transfusion:Acute plasma volume replacement during surgery and trauma resuscitation.
- Severe Burns:Albumin-based colloid resuscitation for patients exceeding 20% total body surface area involvement.
Commanding the largest revenue pool: Immunotherapy. Gaining share fastest: Genetic Disorders.
Delivery Mode:
Route of administration determines cold-chain packaging, patient training infrastructure, and whether therapy shifts from hospital to home settings.
- Intravenous:Infusion of concentrated protein solutions directly into venous circulation requiring controlled-rate pumps and nursing supervision. Hospital infusion suites in the United States and Germany absorb the majority of immunoglobulin and albumin volume through this route.
- Subcutaneous:Patient-administered immunoglobulin via portable pump systems enabling home therapy. Home healthcare networks in the Netherlands and Denmark are scaling training programs fastest as EMA MDR traceability mandates extend to patient-level batch tracking.
- Intramuscular:Localized immunoglobulin deposition for rabies and hepatitis post-exposure prophylaxis.
- Oral:Limited application for specific plasma-derived enzyme therapies with enteric coating requirements.
Capturing the highest volume: Intravenous. Climbing the fastest: Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Raleigh-Durham corridor anchors North American plasma collection density, with CSL Behring and Grifols operating high-throughput centers within fifty miles of major fractionation infrastructure.
United States
Tertiary hospitals in Texas and Florida sustain multi-year immunoglobulin treatment cycles through direct manufacturer contracts with quarterly volume commitments. FDA cGMP standards enforce viral inactivation protocols that raise compliance costs for domestic fractionators. The Research Triangle Park cluster in North Carolina concentrates plasma processing R&D alongside collection center networks.
Germany
Burn centers in Berlin and Munich command the largest European albumin offtake for surgical resuscitation protocols. EMA MDR traceability mandates accelerate investment in digital chain-of-custody systems across Bavarian fractionation facilities. The Frankfurt-Rhine-Main corridor hosts specialized cold-chain logistics providers serving hospital procurement groups.
Japan
Academic medical centers in Tokyo and Osaka expand immunoglobulin infusion capacity for chronic neurology protocols. PMDA post-market surveillance obligations extend to patient-level batch tracking for subcutaneous immunoglobulin therapies. The Kansai region concentrates plasma-derived product distribution through consolidated hospital purchasing alliances.
India
CDSCO regulatory pathway maturation and government PLI scheme incentives attract fractionation joint venture proposals in Maharashtra and Gujarat. The national pharmaceutical regulator tightens cold-chain documentation requirements for imported albumin and immunoglobulin products. Hyderabad's biologics corridor emerges as a contract manufacturing destination for plasma protein purification.
Switzerland
Contract research organizations in Basel and Zurich expand pharmaceutical-grade albumin offtake for viral vector production media. Swissmedic enforces serialization standards that align with EMA F-Gas refrigeration phase-down timelines for biologics storage. The Greater Geneva Bern area concentrates specialized immunology portfolio development for rare disease indications.
Plasma Protein System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the plasma protein value chain. The market structure concentrates around vertically integrated collection-to-finished-product networks and specialized immunology portfolio developers. Three archetypes dominate: continental-scale fractionators with captive plasma supply, regional specialists in rare disease indications, and emerging biologics contractors pivoting toward cell therapy media applications. Dominant competitive moves include backward integration into plasma collection center ownership and strategic partnerships with gene therapy manufacturers seeking serum-free media alternatives.
Among the integrated fractionation tier, CSL Behring, Takeda Pharmaceutical Company Limited, and Grifols occupy positions exemplifying scale-driven collection network economics. These entities represent the archetype of vertically controlled supply from donor recruitment through finished vial release. Their geographic footprints span multiple continents, anchoring competitive positioning through high-capacity plasma processing infrastructure rather than specialized therapeutic focus.
| Leading Market Players |
|---|
| CSL Behring |
| Takeda Pharmaceutical Company Limited |
| Grifols |
| Octapharma |
| Kedrion Biopharma |
| Biotest |
| ADMA Biologics |
| Bio Products Laboratory |
| LFB |
| Others |
Value Network & Pricing Analysis
Vertically integrated collection-to-finished-product networks operated by CSL Behring, Takeda, and Grifols anchor supply-side discipline while immunoglobulin scarcity props pricing power across chronic therapy tiers. This ownership concentration enables quarterly volume commitment negotiations with integrated delivery networks while constraining spot-market liquidity for albumin fractions.
Pricing Analysis
Outcome-based pricing anchors immunoglobulin contracts tied to patient response metrics in tertiary neurology protocols. Three-tier pricing structure across premium chromatographic-grade, standard Cohn-Oncley, and economy albumin fractions differentiates by viral inactivation rigor and FDA certification tier. Cost compression in standard-grade immunoglobulin intensifies as hospital procurement groups consolidate through specialty pharmacy benefit managers. Research laboratories exhibit lowest price sensitivity due to serum-free media specification requirements, while burn centers negotiate hardest on albumin volume.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume immunoglobulin offtake from tertiary infusion centers, bypassing traditional distributor markups. Plasma collection concentrates in the United States, Germany, and Spain where CSL Behring, Grifols, and Takeda operate captive donor networks. Fractionation capacity draws from chromatographic resins, cold-chain refrigeration systems, and cGMP-certified technician labor pools. Single-source vulnerability in qualified plasma processing specialists constrains multi-shift operations at newer facilities. Distribution runs through consolidated hospital purchasing alliances in Texas and Florida alongside contract research organization procurement desks in Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Donor plasma scarcity functions as the binding capacity constraint, insulating fractionator pricing power despite payer consolidation pressures. Collection center licensing timelines and recruitment costs prevent rapid supply response to demand surges.
For Market Incumbents: To counter gene therapy manufacturers developing synthetic serum-free alternatives, secure backward integration into additional high-throughput plasma collection centers in the Raleigh-Durham corridor and anchor supply agreements with viral vector producers seeking pharmaceutical-grade albumin. Prioritize Capto MMC resin technology investments to compress batch cycle times against mid-scale competitors achieving purity parity. For New Entrants and Emerging Players: The premium-to-economy price gap in subcutaneous immunoglobulin delivery devices offers entry positioning for home healthcare pump system specialists. Target the Netherlands and Denmark where EMA MDR traceability mandates extend to patient-level batch tracking and training infrastructure remains underdeveloped. Pursue CDSCO joint venture pathways in Maharashtra and Gujarat leveraging government PLI scheme incentives before domestic fractionation capacity matures. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European fractionators with stranded Cohn-Oncley assets facing EU F-Gas refrigeration replacement costs. Long-term viability across the analysis window rests on continuous processing adoption curves and cell therapy media demand expansion. Monitor gene therapy clinical trial enrollment rates as the inflection signal for serum-free media substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Captive donor access in the United States insulates raw material throughput against source plasma scarcity. |
| Continuous Chromatography Adoption | Perfusion chromatography integration reduces tank farm footprint and ethanol consumption at mid-scale facilities. |
| CO2 Transcritical Refrigeration Transition | EMA F-Gas Regulation compliance secures operating licenses for European albumin fill-finish lines. |
| Gene Therapy Media Partnership | Pharmaceutical-grade albumin supply agreements anchor positioning in viral vector production expansion. |
| Indian Fractionation Joint Venture | CDSCO pathway maturation and PLI incentives create first-mover advantage in emerging biologics infrastructure. |
Research Methodology
FDA 483 inspection observations, EMA MDR submission databases, and hospital procurement contract filings formed the secondary backbone, cross-referenced against primary interviews with plasma fractionation plant managers, regulatory affairs leads at CSL Behring and Grifols, hospital formulary directors in Texas and Florida, and cell therapy contract research organization procurement specialists. Bottom-up triangulation against top-down plasma collection volume estimates validated segment-level projections.
Bottom-up modeling anchored volume forecasts to immunoglobulin batch release schedules and albumin fill-finish capacity utilization across the projection horizon. Segmentation dimensions included product type, end user, therapeutic application, and delivery mode alongside regional regulatory cluster differentiation. CAGRs were derived from pooled plasma throughput expansion rates and fractionation yield improvements rather than price assumptions.
Inputs from EMA post-market surveillance databases and CDSCO regulatory pathway disclosures were available through the study window; gaps in real-time hospital procurement contract pricing introduce uncertainty bands around immunoglobulin revenue estimates. Forecasts reflect assumptions regarding donor recruitment cost trajectories and chromatographic resin pricing stability. Periodic stress-testing of base assumptions is recommended given gene therapy media substitution risk and EU F-Gas phase-down enforcement variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Targeted Protein Degradation Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market