
 Lentiviral Vector Contract Development and Manufacturing Organizations Market | 2026-2036
Lentiviral Vector Contract Development and Manufacturing Organizations Market Size, Share, and Industry Trends Forecast 2026-2036
Lentiviral Vector Contract Development and Manufacturing Organizations Market Insights
A capital-intensity divergence between in-house biopharma capabilities and outsourced CDMO infrastructure is reorganizing competitive dynamics across the lentiviral vector landscape. Thermo Fisher Scientific leverages its integrated life sciences platform to anchor downstream purification and analytics services for gene therapy sponsors. Oxford Biomedica sustains specialized lentiviral expertise through its LentiVector platform, dominating niche production for rare disease indications. Lonza competes via multi-modality manufacturing campuses that extend viral vector capacity alongside cell therapy suites.
Lentiviral vector contract development and manufacturing organizations engineer replication-deficient HIV-derived particles pseudotyped with alternative envelope proteins to achieve broad cell tropism, employing suspension-adapted HEK293 cell lines in chemically defined media to meet purity thresholds exceeding 95% functional titer for clinical supply. Vector production services command the largest revenue share as sponsors outsource upstream bioreactor operations and downstream chromatography to avoid fixed-asset commitments. Gene therapy applications within the application dimension are absorbing disproportionate capacity investment as CAR-T and in vivo correction programs advance, while regulatory support services represent the fastest-growing service type as BLA submissions for lentiviral-based products multiply.
FDA's Office of Therapeutic Products and EMA's Committee for Advanced Therapies impose escalating chemistry-manufacturing-controls requirements that shape facility qualification timelines and lot-release protocols for lentiviral vectors entering Phase III. The International Council for Harmonisation Q5A viral safety guidelines and ISO 14644 cleanroom classifications further constrain which CDMOs qualify for commercial-stage supply agreements. Stakeholders must monitor how evolving potency assay harmonization efforts between FDA and EMA reshape comparability study burdens and technology transfer timelines for multi-regional programs.
Market Dynamics
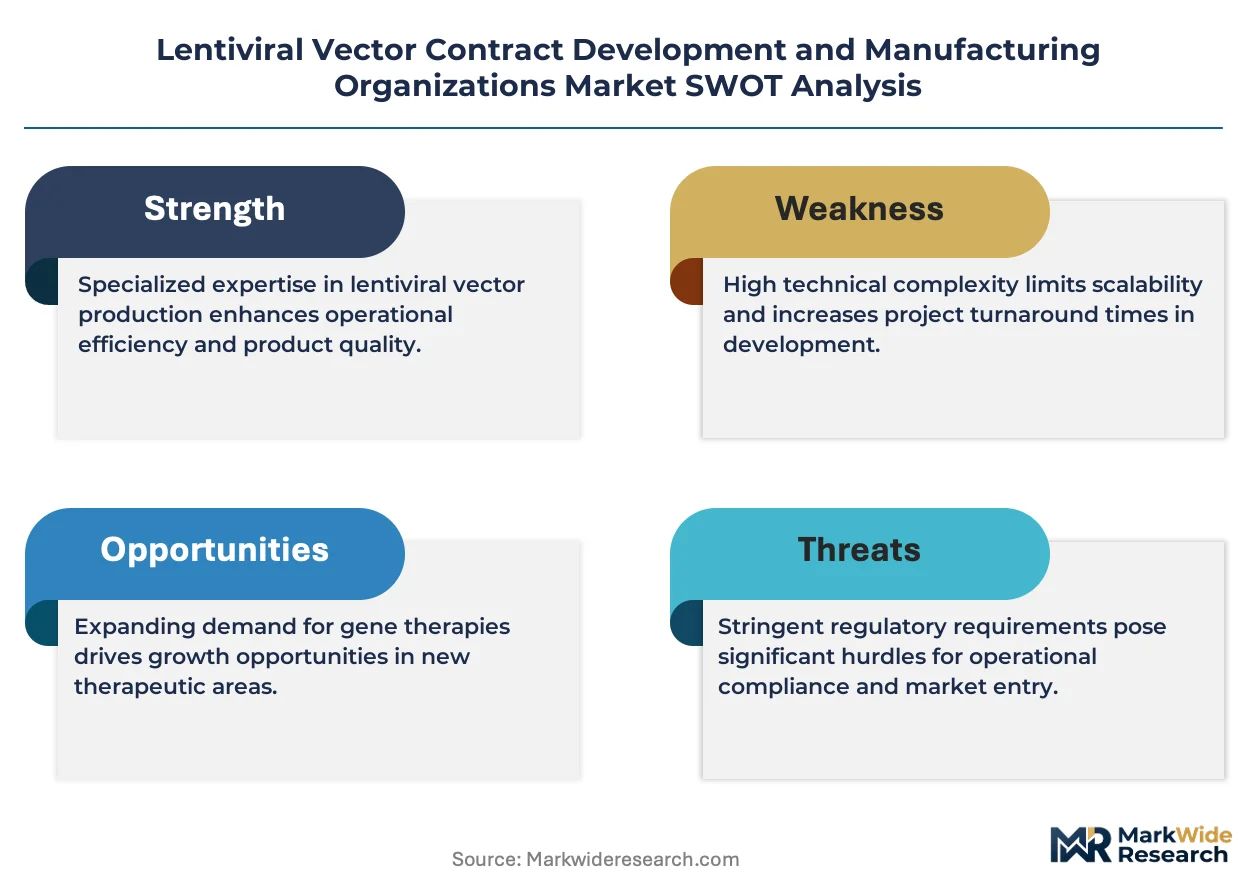
Gene therapy sponsors are accelerating their migration toward outsourced lentiviral manufacturing as FDA chemistry-manufacturing-controls requirements tighten for commercial-stage vector supply, forcing sponsors to choose between multi-hundred-million-dollar facility investments and CDMO partnerships.
Growth Catalysts
- EMA Committee for Advanced Therapies frameworks:The European regulator's accelerated assessment pathways for advanced therapy medicinal products compress development timelines, incentivizing sponsors to secure commercial-ready manufacturing partnerships ahead of Phase III transitions.
- HEK293 suspension platform maturation:Chemically defined, serum-free culture systems now achieve titers exceeding 10^9 TU/mL, eliminating adherent-scale bottlenecks that previously constrained batch economics for lentiviral production.
- CAR-T pipeline concentration:Autologous cell therapy developers in the United States now account for the majority of lentiviral vector procurement contracts, with CDMOs capturing long-term supply agreements tied to BLA submissions.
Market Restraints
- Plasmid DNA supply concentration:Critical raw material production clusters in North American and European supplier networks create single-source vulnerabilities that disrupt vector manufacturing campaigns when contamination events occur.
- ISO 14644-1 Grade B cleanroom scarcity:Commercial-grade viral vector suites require 24-36 month construction timelines, constraining how quickly CDMO capacity can expand to match sponsor demand.
- Analytical standardization gaps:Absent harmonized potency assays between FDA and EMA, comparability studies for technology transfers consume 6-12 additional months, delaying multi-regional program launches.
Strategic Opportunities
- Japan's regenerative medicine regulatory sandbox:PMDA's conditional approval framework for gene therapies creates a prioritized pathway for lentiviral-based products, attracting CDMO investment into Japanese manufacturing infrastructure.
- In vivo gene correction applications:Liver-directed and CNS-targeted lentiviral programs are absorbing capacity previously reserved for ex vivo cell modification, opening service expansion vectors for vector engineering specialists.
- Continuous bioprocessing convergence:Integration of perfusion-based upstream operations with single-use downstream purification trains promises 40-60% footprint reduction for commercial-scale facilities.
Industry Challenges
- Vector analytics talent scarcity:Functional titer determination, residual host cell DNA quantification, and replication-competent lentivirus detection require specialized skill sets that outpace current training program output.
- Technology transfer complexity:Sponsor-to-CDMO knowledge migration for proprietary packaging cell lines and pseudotyping protocols demands 9-18 month validation cycles that compress program timelines.
- Legacy facility retrofit costs:Converting mammalian antibody production suites to viral vector containment standards requires $50-150 million per site, straining mid-cap CDMO balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lentiviral Vector Contract Development and Manufacturing Organizations Market |
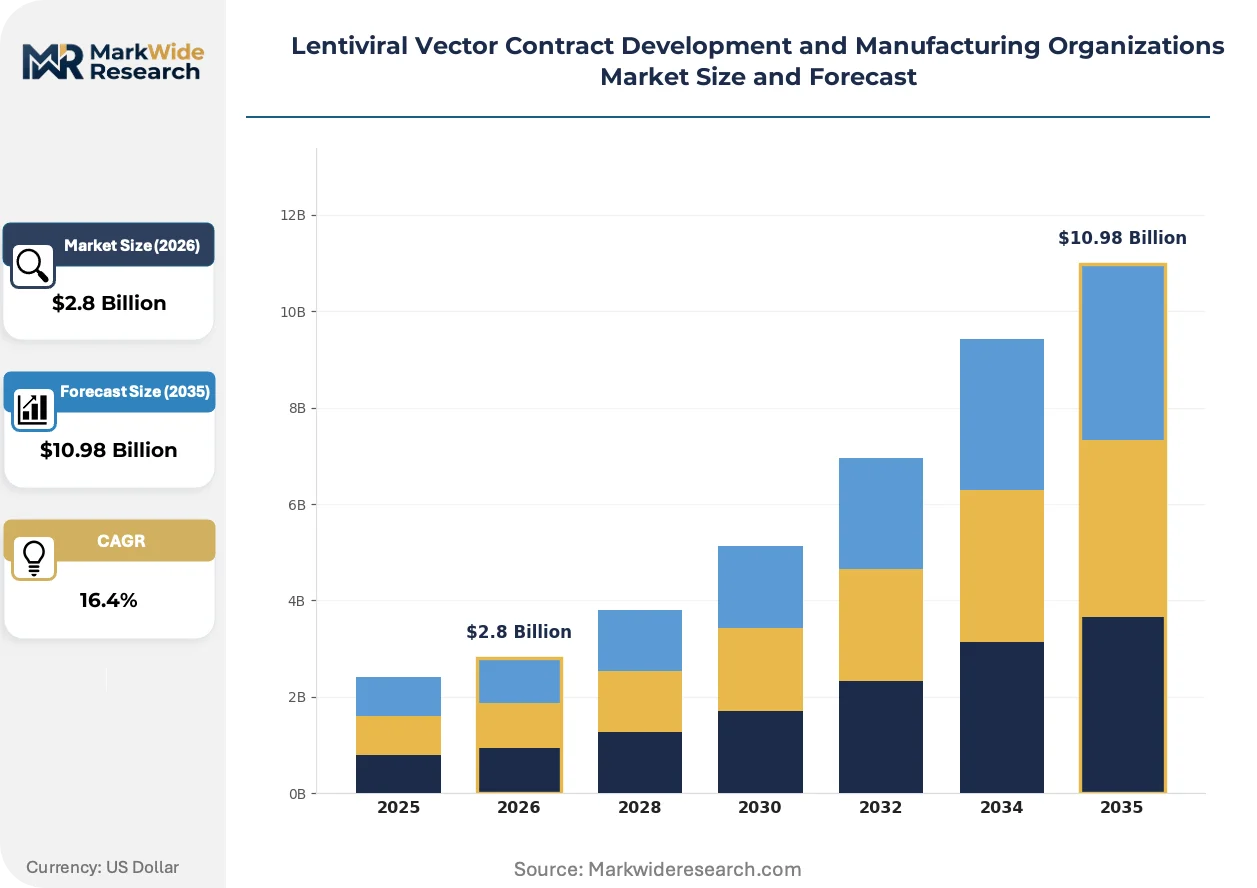
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Vector Production, Process Development, Quality Control, Regulatory Support Client Type: Biopharmaceutical Companies, Research Institutions, Academic Organizations, Startups Project Size: Small-scale Projects, Medium-scale Projects, Large-scale Projects, Custom Projects Application: Gene Therapy, Cancer Treatment, Vaccine Development, Hematological Disorders |
| Companies Covered | Thermo Fisher Scientific, Inc, Oxford Biomedica, Charles River Laboratories International, Inc., GenScript ProBio, Catalent Inc., Lonza, Merck KGaA, Creative Biogene, AskBio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lentiviral Vector Contract Development and Manufacturing Organizations Market Trends and Innovations
Suspension-based manufacturing platforms and automated purification trains are compressing production economics while regulatory agencies impose escalating characterization requirements that reshape competitive differentiation among contract manufacturers.
Stable producer cell lines engineered with inducible lentiviral packaging constructs are displacing transient transfection workflows across Phase II and III programs. Gene therapy sponsors with multi-product pipelines are adopting these platforms to reduce plasmid costs and improve batch-to-batch consistency. The shift is displacing smaller CDMOs lacking cell line development capabilities from commercial supply competitions.
FDA's Office of Therapeutic Products issued draft guidance in 2023 requiring enhanced potency assay validation for lentiviral vectors entering pivotal trials, mandating correlation between in vitro titer and in vivo transduction efficiency. The rule forces sponsors to invest 12-18 months in analytical development before BLA submission. United States-based programs are responding by embedding CDMO partners earlier in development to co-develop release assays.
Vector procurement is consolidating under centralized sourcing functions at large gene therapy developers, replacing decentralized R&D-driven purchasing. Biopharma procurement teams now negotiate multi-year master service agreements with guaranteed capacity allocations rather than transactional campaign contracts. This concentration is most visible among Nasdaq-listed gene therapy developers with three or more IND-active programs.
Lentiviral Vector Contract Development and Manufacturing Organizations Market Segmentation
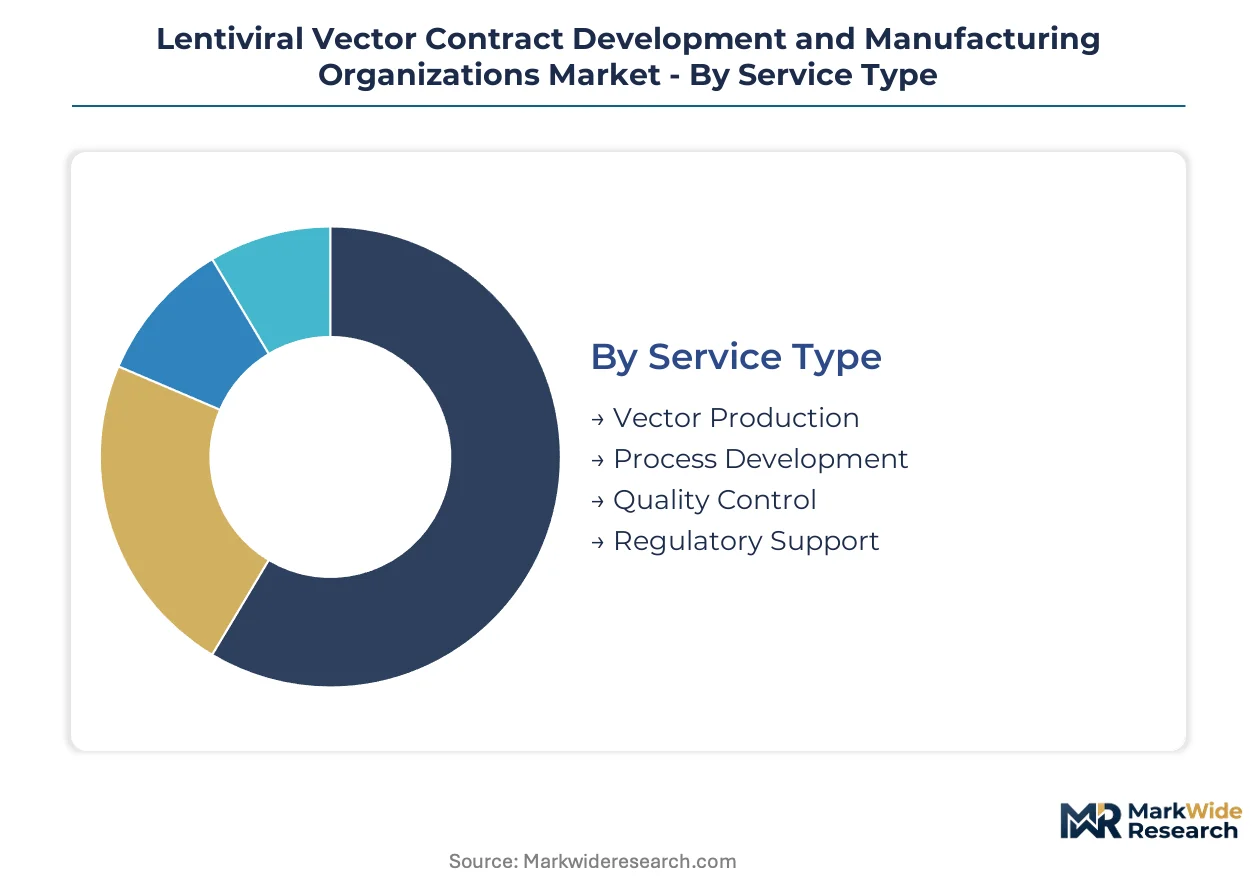
Lentiviral vector CDMOs structure service offerings around four critical dimensions that determine contract economics and capacity allocation. Service type and application segments capture divergent margin profiles, while client type and project size shape pricing power and operational complexity.
Service Type:
Upstream bioreactor operations and downstream purification command the deepest margin pools, whereas regulatory consulting and analytical validation deliver premium pricing per hour but smaller absolute contract values.
- Vector Production:Suspension-adapted HEK293 cell culture in chemically defined media generates functional titers exceeding 10^9 TU/mL. Gene therapy sponsors in the United States absorb the majority of commercial-scale capacity as CAR-T programs advance toward BLA submission. Plasmid DNA costs and cleanroom utilization rates determine per-batch economics.
- Process Development:Technology transfer from sponsor platforms to CDMO workflows requires 9-18 month validation cycles for proprietary packaging cell lines and pseudotyping protocols. European programs under EMA Committee for Advanced Therapies oversight prioritize these services to compress Phase II-to-III transitions.
- Quality Control:Functional titer determination, residual host cell DNA quantification, and replication-competent lentivirus detection require specialized analytical platforms.
- Regulatory Support:Chemistry-manufacturing-controls documentation and BLA submission preparation represent the fastest-climbing service tier as FDA Office of Therapeutic Products tightens potency assay requirements.
The dominant share belongs to Vector Production, while Regulatory Support is closing the gap fastest.
Client Type:
Contract concentration varies sharply by sponsor maturity, with publicly traded developers locking in multi-year capacity commitments and early-stage ventures purchasing campaign-by-campaign.
- Biopharmaceutical Companies:Nasdaq-listed gene therapy developers with three or more IND-active programs now centralize procurement under dedicated sourcing functions. These sponsors negotiate master service agreements with guaranteed capacity allocations rather than transactional contracts.
- Research Institutions:National Institutes of Health-funded academic medical centers and nonprofit research hospitals generate steady demand for small-batch clinical-grade vectors. Budget constraints and grant cycles compress project timelines and limit pricing flexibility for CDMOs.
- Academic Organizations:University-based gene therapy programs require GMP-compliant vectors for investigator-initiated trials with limited commercial pathways.
- Startups:Venture-backed preclinical-stage companies prioritize speed over scale, driving demand for rapid IND-enabling packages.
Biopharmaceutical Companies anchor volume commitments, though Startups are expanding most quickly as venture financing flows into rare disease platforms.
Project Size:
Fixed-cost recovery mechanics favor larger campaigns, yet mid-scale projects deliver superior asset utilization rates across multi-product CDMO facilities.
- Small-scale Projects:Preclinical and Phase I vector batches typically range below 50 liters with expedited turnaround requirements. CDMOs charge substantial premiums per transducing unit to offset facility setup costs.
- Medium-scale Projects:Phase II campaigns spanning 50-200 liters represent the operational sweet spot for suspension-based manufacturing platforms, balancing throughput with scheduling flexibility.
- Large-scale Projects:Commercial supply agreements for approved gene therapies require dedicated cleanroom suites and validated 500+ liter bioreactor trains.
- Custom Projects:Bespoke vector engineering for novel pseudotypes or specialized tropism modifications demand extended development timelines.
Medium-scale Projects capture the highest facility utilization rates, while Large-scale Projects are gaining share fastest as pipeline candidates mature.
Application:
Clinical indication determines vector design specifications, release assay requirements, and the regulatory pathway complexity that shapes CDMO pricing structures.
- Gene Therapy:In vivo liver-directed and CNS-targeted programs are absorbing capacity previously reserved for ex vivo cell modification. FDA potency assay validation requirements for pivotal trials mandate 12-18 months of analytical co-development with CDMO partners.
- Cancer Treatment:Autologous CAR-T developers in the United States account for the majority of lentiviral procurement contracts, with CDMOs capturing long-term supply agreements tied to commercialization timelines.
- Vaccine Development:Lentiviral vector-based immunization platforms require distinct release specifications focused on immunogenicity markers rather than transduction efficiency.
- Hematological Disorders:Ex vivo HSC gene therapy for sickle cell and beta-thalassemia programs demands specialized cryopreservation and cell handling capabilities integrated with vector manufacturing workflows.
Gene Therapy commands the dominant application share, while Hematological Disorders are climbing the fastest as ex vivo correction programs advance through Phase III.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European CDMOs absorb margin compression from EMA regulatory complexity. Japanese manufacturers command premiums through PMDA's conditional approval pathway. Contract values diverge sharply across these three regulatory environments.
United States
FDA chemistry-manufacturing-controls requirements for commercial-stage vector supply drive sponsor migration toward outsourced manufacturing. The Office of Therapeutic Products mandates 12-18 months of potency assay co-development before BLA submission. Greater Boston and San Diego biotech clusters anchor the highest concentration of Phase III gene therapy trials and dedicated CDMO capacity.
Germany
EMA Committee for Advanced Therapies frameworks compress development timelines for advanced therapy medicinal products. REACH chemical safety regulations and ISO 14644 cleanroom standards constrain facility qualification timelines. The Rhine-Main and Munich biotech corridors concentrate CDMO investment serving both domestic sponsors and technology transfers from United States developers.
Switzerland
Swissmedic's alignment with EMA standards enables seamless multi-regional program execution for gene therapy sponsors. The country's pharmaceutical manufacturing heritage supports specialized viral vector containment infrastructure. Basel and Zurich host integrated bioprocessing campuses that combine cell therapy suites with lentiviral production trains.
Japan
PMDA's regenerative medicine regulatory sandbox creates prioritized pathways for lentiviral-based products entering conditional approval. METI industrial policy directs investment toward biologics manufacturing capacity expansion. The Kanto region around Tokyo concentrates CDMO infrastructure serving both domestic developers and United States sponsors seeking Asian manufacturing diversification.
Lentiviral Vector Contract Development and Manufacturing Organizations Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the lentiviral vector CDMO landscape. The vendor base organizes into three tiers: integrated life sciences conglomerates commanding full-service contracts, specialized viral vector boutiques capturing premium pricing for rare disease expertise, and mid-cap CDMOs competing on capacity availability. Consolidation pressures favor players with multi-modality manufacturing campuses and in-house analytical development capabilities. Strategic partnerships and capacity expansion represent the dominant competitive moves as sponsors lock in multi-year supply agreements.
Among integrated platform providers, Thermo Fisher Scientific anchors downstream purification and analytics services for gene therapy sponsors. Oxford Biomedica occupies a position within the specialized viral vector tier, exemplifying boutique expertise through its LentiVector platform dominance in rare disease indications. Lonza sits within the multi-modality manufacturing archetype, representing scale-driven capacity competition across viral vector and cell therapy suites.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc |
| Oxford Biomedica |
| Charles River Laboratories International, Inc. |
| GenScript ProBio |
| Catalent Inc. |
| Lonza |
| Merck KGaA |
| Creative Biogene |
| AskBio |
| Others |
Pricing and Supply Chain Analysis
FDA chemistry-manufacturing-controls certification gates commercial-stage supply qualification and simultaneously stratifies price differentiation between validated and development-grade vector manufacturers. Gene therapy sponsors with BLA-active programs pay substantial premiums for CDMOs holding completed facility inspections, while preclinical developers absorb lower pricing from non-validated providers.
Pricing Analysis
Configured-to-order pricing for bespoke pseudotyping protocols and proprietary packaging cell line transfers commands 40-60% premiums over standard suspension-platform campaigns. Project-based contracting dominates, with price differentiation driven by GMP certification tier and customization complexity. Cost compression in standard vector production is intensifying because HEK293 suspension platform commoditization erodes batch economics. Early-stage biotech ventures exhibit highest price sensitivity, while Nasdaq-listed developers with multi-product pipelines prioritize capacity security over unit cost.
Supply Chain Analysis
The United States and Germany anchor plasmid DNA manufacturing, with Switzerland and Japan contributing specialized viral envelope protein suppliers. Critical raw material dependencies draw from North American and European supplier networks for GMP-grade plasmids, chemically defined media, and alternative envelope glycoproteins. Single-source vulnerability in plasmid supply creates campaign disruption risk when contamination events trigger batch holds. Distribution runs through direct CDMO-sponsor partnerships with multi-year master service agreements replacing spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as gene therapy developers centralize procurement under dedicated sourcing functions, consolidating contract volume among fewer sponsors with larger multi-program portfolios.
For Market Incumbents: Secure analytical development capabilities to capture 12-18 month potency assay co-development mandates from FDA Office of Therapeutic Products. Lock in multi-year capacity commitments from CAR-T developers advancing toward commercialization. Capacity addition in Japanese manufacturing infrastructure addresses PMDA conditional approval pathway demand. Certification investment in ISO 14644-1 Grade B cleanroom expansion defends against emerging Asian CDMOs with cost-advantaged platforms. For New Entrants and Emerging Players: Regulatory support services for BLA submission preparation represent the most penetrable service tier, as established CDMOs under-resource chemistry-manufacturing-controls documentation capacity. Target mid-scale Phase II campaigns where facility utilization rates optimize batch economics for sponsors not yet requiring dedicated commercial suites. Go-to-market angle: embedded analytical co-development partnerships that compress technology transfer timelines for sponsor platforms. For Investors and Strategic Acquirers: FDA potency assay harmonization with EMA reshapes the acquisition landscape by privileging CDMOs with validated multi-regional release protocols. Long-term viability centers on facilities capable of serving both United States and European commercial supply without redundant comparability studies. Acquisition target archetype: specialized viral vector boutiques with stable producer cell line platforms and rare disease indication expertise. Signal to watch: sponsor migration toward integrated cell therapy-vector manufacturing campuses.| Strategic Initiative | Industry Significance |
|---|---|
| Stable Producer Cell Line Adoption | Inducible packaging platforms reduce plasmid costs and improve batch consistency for multi-product sponsors. |
| Potency Assay Co-Development | Early CDMO embedding satisfies FDA Office of Therapeutic Products validation timelines for pivotal trials. |
| Japanese Manufacturing Footprint | PMDA conditional approval pathway attracts capacity investment serving Asian market diversification. |
| Continuous Bioprocessing Integration | Perfusion upstream with single-use downstream promises footprint reduction for commercial-scale facilities. |
| Multi-Regional Release Capability | Harmonized FDA-EMA protocols eliminate redundant comparability studies for global program launches. |
Research Methodology
The analysis maps vector production, process development, quality control, and regulatory support service tiers, each validated through gene therapy development executives, regulatory affairs leads, CDMO operations directors, and academic principal investigators. Primary interviews with industry stakeholders combine with secondary validation from FDA Office of Therapeutic Products guidance documents, EMA Committee for Advanced Therapies frameworks, ClinicalTrials.gov pipeline tracking, and ISO 14644 cleanroom certification databases. Bottom-up service-type demand modeling and top-down market sizing triangulate through sponsor procurement pattern analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, application indication, client maturity tier, and project scale tier. CAGRs derive from sponsor pipeline advancement rates, facility capacity expansion announcements, and regulatory submission velocity. Industry-specific forecast inputs incorporate CAR-T program maturation timelines and in vivo gene correction program initiation rates.
Forecasts assume regulatory continuity in FDA and EMA frameworks; material policy shifts in potency assay requirements or viral safety guidelines would require re-modeling. Specific risks that could revise projections include plasmid supply contamination events, cleanroom construction delays, and analytical talent scarcity constraining lot release capacity. Recalibration cycles align with material shifts in sponsor pipeline composition and regulatory guidance publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market