
 Middle East and Africa Cancer Vaccines Market | 2026-2036
Middle East and Africa Cancer Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cancer Vaccines Market Foresight
Project finance arrangements for biologics manufacturing facilities are reconfiguring competitive entry in the Middle East and Africa Cancer Vaccines Market. AstraZeneca PLC leverages its regional distribution partnerships to sustain oncology portfolio penetration across Gulf hospital networks. Merck & Co. Inc. anchors its position through long-term supply agreements with government immunization programs. GSK plc differentiates via established cold-chain infrastructure that supports vaccine integrity in high-temperature climates.
Cancer vaccines are biological preparations designed to stimulate the immune system to recognize and eliminate malignant cells, typically composed of tumor-associated antigens, adjuvants, or autologous cellular material administered via intramuscular or subcutaneous injection. These agents function therapeutically to treat existing malignancies or preventively to intercept virally induced cancers such as cervical and liver cancer. Therapeutic vaccines command attention due to their alignment with precision oncology trends, while RNA vaccines represent the fastest-expanding technology platform as regional manufacturing capabilities mature. Preventive vaccines maintain stable demand through national immunization schedules, though prostate cancer applications attract concentrated R&D investment from specialized urology centers.
South Africa's SAHPRA, Saudi Arabia's SFDA, and Egypt's EDA govern product registration, clinical trial authorization, and post-market surveillance across the region, with harmonization initiatives reducing redundant submission requirements. WHO prequalification status increasingly determines eligibility for procurement by national health ministries and global financing mechanisms. Stakeholders must monitor evolving biosimilar pathways and local content requirements that will reshape sourcing decisions and partnership structures.
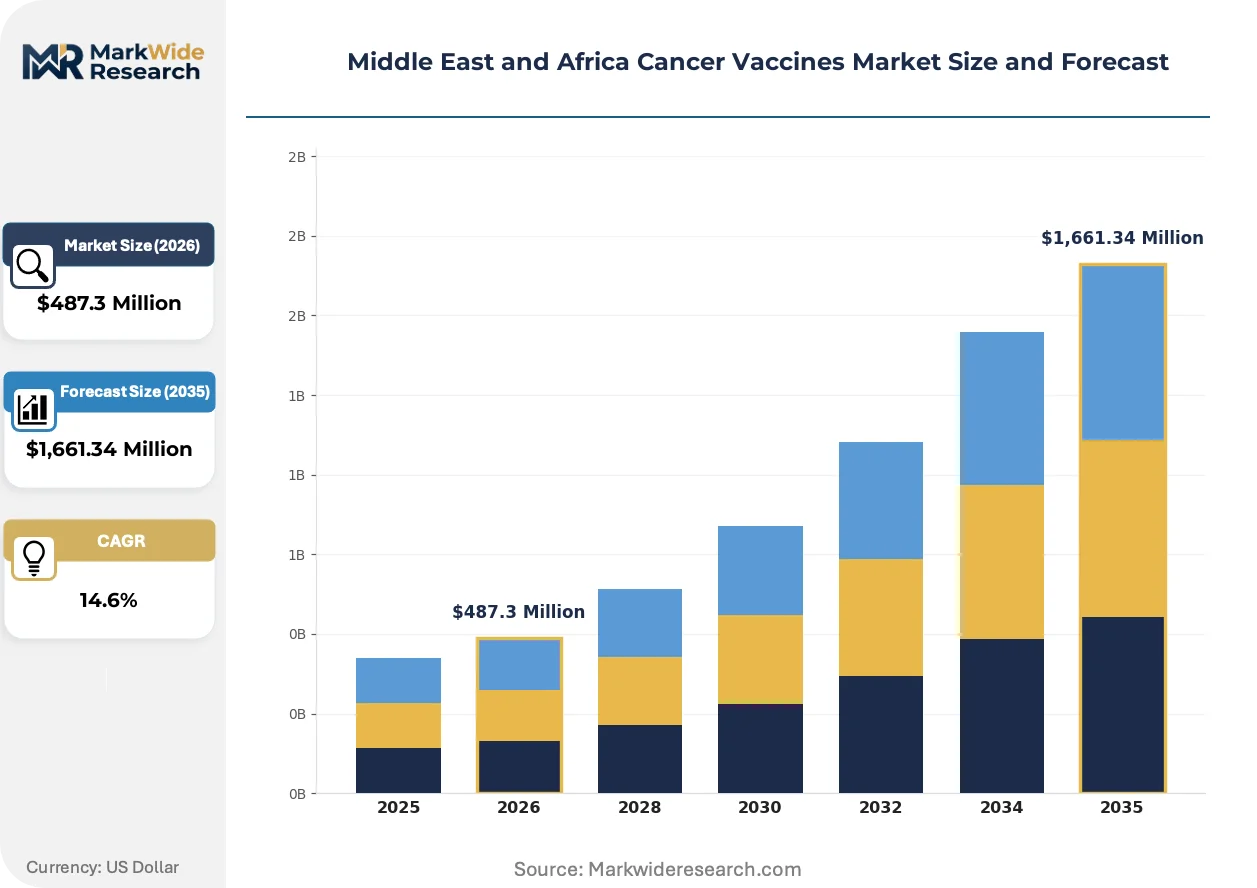
Market Dynamics
RNA manufacturing partnerships between Gulf sovereign wealth funds and European biotech firms are restructuring competitive entry requirements across the Middle East and Africa Cancer Vaccines Market. These arrangements bypass traditional cold-chain limitations while accelerating local fill-finish capabilities.
Growth Catalysts
- SFDA Accelerated Pathway:Saudi Arabia's streamlined oncology biologics review reduces registration timelines for therapeutic vaccines targeting prostate and cervical malignancies.
- Tertiary Hospital Expansion:King Faisal Specialist Hospital and Research Centre affiliates across Riyadh, Jeddah, and Dammam are establishing dedicated cellular therapy units.
- WHO Prequalification Alignment:South Africa's SAHPRA harmonization with international standards unlocks procurement eligibility through GAVI and national immunization programs.
Market Restraints
- Ultra-Low Temperature Infrastructure:mRNA vaccines require minus-seventy-degree Celsius storage that remains scarce outside Johannesburg, Cairo, and Gulf metropolitan corridors.
- Active Pharmaceutical Ingredient Concentration:Lipid nanoparticle formulations depend on European and Asian contract manufacturers with limited regional redundancy.
- SFDA Lot Release Bottleneck:Saudi Arabia's mandatory local testing for imported biologics extends distribution lead times by four to six weeks.
Strategic Opportunities
- Egyptian Manufacturing Zone:EDA regulatory incentives for local production create captive supply opportunities serving North African and Levantine markets.
- Point-of-Care Autologous Processing:Decentralized dendritic cell vaccine preparation at regional oncology centers reduces patient travel burden.
- UAE Free Zone Structuring:Dubai Science Park and Abu Dhabi KIZAD offer tax-advantaged distribution hubs for sub-Saharan Africa re-export.
Industry Challenges
- Cellular Therapy Workforce Scarcity:GMP-certified aseptic processing technicians remain concentrated in South Africa and Gulf private sectors.
- Multi-Jurisdiction Trial Coordination:Parallel SAHPRA, SFDA, and EDA clinical trial approvals fragment patient recruitment across national boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cancer Vaccines Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preventive Vaccines, Therapeutic Vaccines, Combination Vaccines, Oncolytic Vaccines End User: Hospitals, Clinics, Research Institutes, Vaccine Manufacturers Technology: Dendritic Cell, DNA Vaccines, Virus-Like Particle, RNA Vaccines Application: Prostate Cancer, Cervical Cancer, Melanoma, Breast Cancer |
| Companies Covered | AstraZeneca PLC, Merck & Co. Inc., Bristol-Myers Squibb, Astellas Pharma Inc., GSK plc, Pfizer Inc., Sanofi, Moderna Inc., Aduro Biotech Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cancer Vaccines Market Shifts & Advancements
Digital twin platforms are compressing vaccine process development cycles while regulatory sandboxes in Gulf financial centers enable novel financing structures for biologics manufacturing.
RNA lipid nanoparticle formulation technology is virtualizing traditional cold-chain dependencies for cancer vaccines in high-temperature climates. King Faisal Specialist Hospital network facilities in Riyadh and Jeddah are adopting modular microfluidic manufacturing units that enable on-site buffer preparation and final formulation. This distributed production architecture is virtualizing the centralized fill-finish model that previously required European importation.
SAHPRA's implementation of reliance pathways for WHO-prequalified products is compressing duplicate stability testing requirements for cancer vaccines registered in South Africa. Manufacturers holding EMA or FDA approvals now submit abbreviated dossiers rather than complete redevelopment studies. Oncology biologics with prior stringent regulatory authority recognition receive prioritized review queue placement.
Hospital procurement committees across Gulf State tertiary centers are consolidating vaccine purchasing through centralized ministry tenders rather than institutional discretionary acquisition. King Faisal Specialist Hospital and affiliated research centers now coordinate annual volume commitments through Saudi Arabia's National Unified Procurement Company. This buyer concentration is compressing price negotiation cycles while favoring suppliers with demonstrated local cold-chain custody capabilities.
Middle East and Africa Cancer Vaccines Market Segmentation
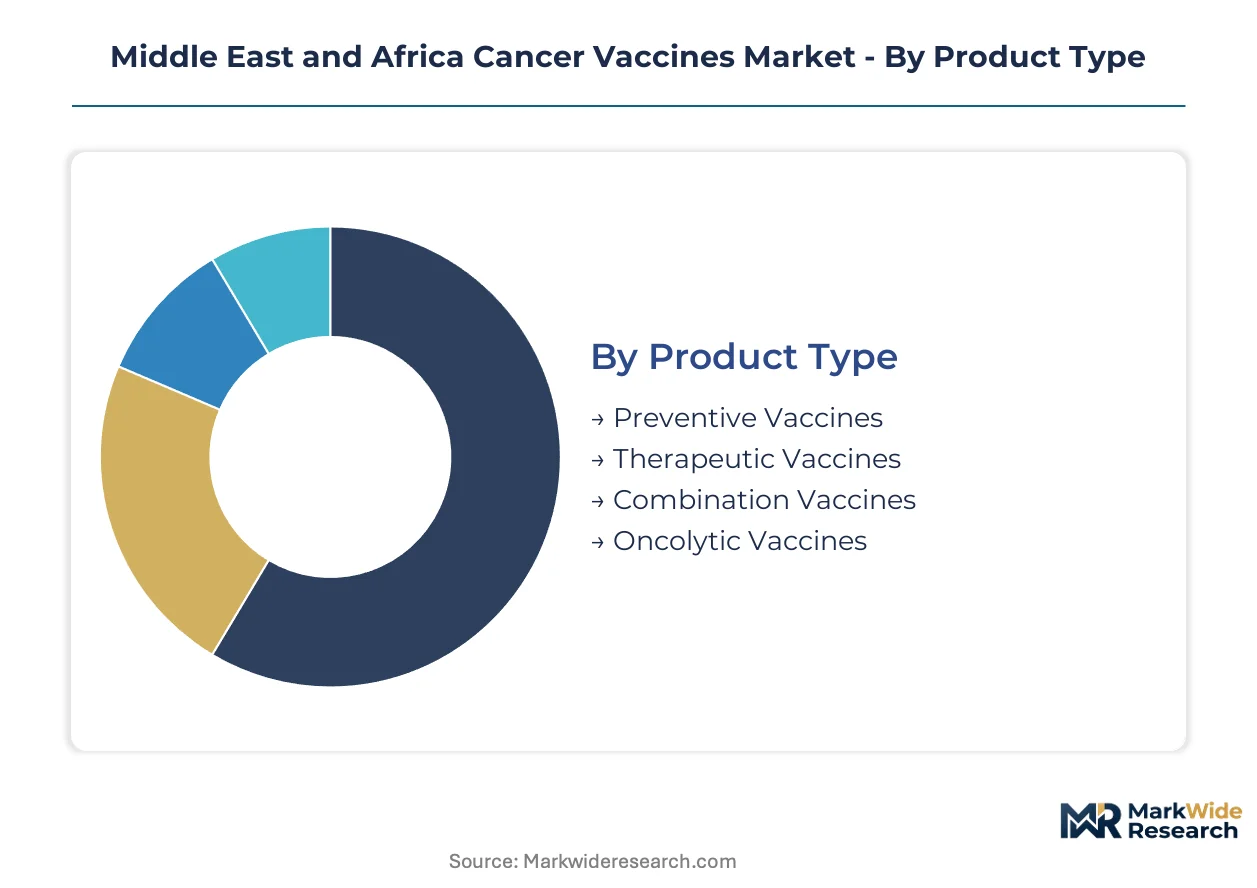
Cancer vaccine segmentation in the Middle East and Africa reveals distinct procurement rhythms across product categories. Technology platforms and end-user infrastructure determine which segments command immediate investment versus long-dated capacity building.
Product Type:
Cycle times vary sharply: preventive vaccines turn on national immunization calendar decisions, while therapeutic batches align with individual patient treatment protocols.
- Preventive Vaccines:These preparations target virally induced malignancies through prophylactic immune priming, primarily against human papillomavirus and hepatitis B. Saudi Arabia's National Unified Procurement Company consolidates annual tenders for school-based immunization programs, with SFDA lot release timelines dictating delivery windows.
- Therapeutic Vaccines:Designed to mobilize patient-specific immune responses against established tumors, these autologous or allogeneic formulations require specialized handling. King Faisal Specialist Hospital cellular therapy units in Riyadh and Jeddah generate concentrated demand for prostate and melanoma indications.
- Combination Vaccines:Multi-antigen formulations merging preventive and therapeutic mechanisms.
- Oncolytic Vaccines:Genetically modified viral vectors selectively replicating in tumor cells.
Preventive vaccines dominate installed base. Therapeutic vaccines are where expansion concentrates.
End User:
Customer concentration follows treatment complexity, with high-acuity settings capturing value-intensive therapeutic protocols.
- Hospitals:Tertiary oncology centers with GMP-certified aseptic processing capabilities. King Faisal Specialist Hospital network affiliates across Saudi Arabia anchor regional therapeutic vaccine administration, with dedicated cold-chain custody requirements filtering supplier eligibility.
- Research Institutes:Academic medical centers conducting investigator-initiated trials. South Africa's University of Cape Town and Stellenbosch University drive early-phase RNA vaccine development through SAHPRA-authorized clinical trial units.
- Clinics:Outpatient infusion centers handling preventive vaccine distribution.
- Vaccine Manufacturers:Regional fill-finish facilities and quality control laboratories.
Hospitals capture the highest per-dose value. Research institutes are climbing the fastest as trial density increases.
Technology:
Platform selection determines capital intensity, with distributed manufacturing architectures displacing centralized import models.
- RNA Vaccines:Lipid nanoparticle-encapsulated mRNA sequences enabling rapid antigen redesign. Modular microfluidic units at Gulf tertiary hospitals are virtualizing cold-chain dependencies through on-site buffer preparation, bypassing minus-seventy-degree Celsius storage constraints.
- Dendritic Cell:Autologous cellular vaccines requiring patient-specific antigen loading. Point-of-care processing at regional oncology centers reduces travel burden for dispersed populations across Saudi Arabia's Najd and Hejaz regions.
- DNA Vaccines:Plasmid-based constructs with simplified stability profiles.
- Virus-Like Particle:Non-replicating protein shells mimicking viral structure.
RNA vaccines dominate installed base. Dendritic cell platforms are where expansion concentrates.
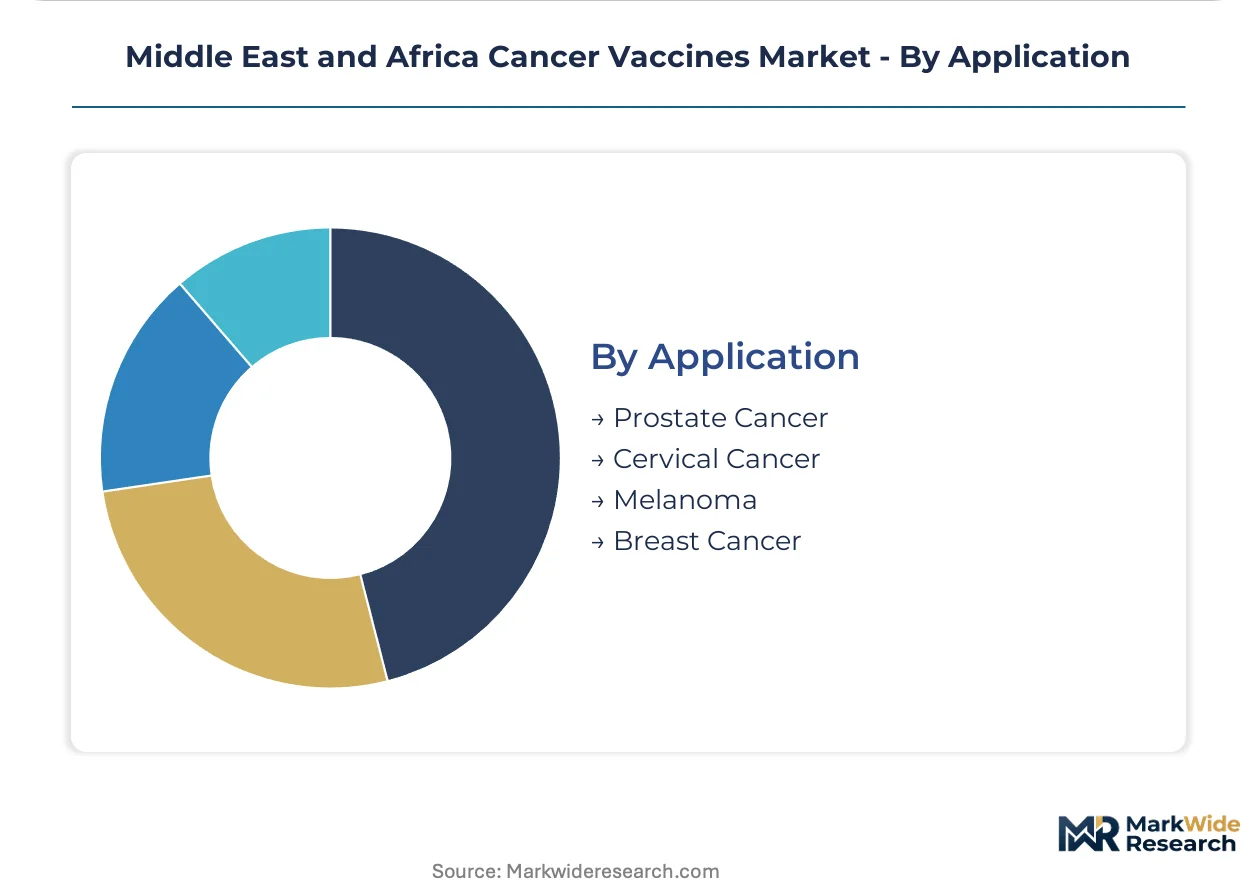
Application:
Disease-specific demand patterns reflect epidemiological burden and screening infrastructure maturity.
- Prostate Cancer:Therapeutic vaccines targeting castration-resistant disease. Saudi urology centers generate concentrated procurement volumes, with SFDA accelerated pathway designation compressing registration timelines for novel antigen targets.
- Cervical Cancer:Preventive HPV vaccination programs and therapeutic interventions for advanced disease. Egypt's EDA regulatory incentives for local production are reshaping North African supply arrangements.
- Melanoma:Immune checkpoint combination protocols with therapeutic vaccine adjuvants.
- Breast Cancer:HER2-targeted therapeutic candidates in late-stage development.
Cervical cancer applications dominate installed base. Prostate cancer is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's SFDA accelerated pathway for oncology biologics is reshaping competitive entry timelines across the Middle East and Africa Cancer Vaccines Market. National immunization program expansions in Gulf States and harmonization initiatives in South Africa are redirecting procurement flows toward suppliers with demonstrated cold-chain custody capabilities.
Saudi Arabia
King Faisal Specialist Hospital network affiliates in Riyadh, Jeddah, and Dammam are establishing dedicated cellular therapy units for therapeutic vaccine administration. SFDA's streamlined review reduces registration timelines for prostate and cervical malignancy vaccines by compressing lot release testing requirements. The National Unified Procurement Company now consolidates annual volume commitments, favoring suppliers with local distribution infrastructure.
South Africa
SAHPRA's alignment with WHO prequalification standards is unlocking GAVI procurement eligibility for preventive vaccine programs targeting HPV and hepatitis B. The University of Cape Town and Stellenbosch University anchor early-phase RNA vaccine development through authorized clinical trial units. Johannesburg remains the primary hub for minus-seventy-degree Celsius storage infrastructure serving sub-Saharan distribution.
United Arab Emirates
Dubai Science Park and Abu Dhabi KIZAD free zones offer tax-advantaged distribution hubs for sub-Saharan Africa re-export operations. MOHAP regulatory frameworks support decentralized point-of-care autologous vaccine processing at regional oncology centers. Tertiary hospital procurement committees are consolidating purchasing through centralized ministry tenders rather than institutional discretionary acquisition.
Egypt
EDA regulatory incentives for local production are creating captive supply opportunities serving North African and Levantine markets for cervical cancer vaccines. Cairo's pharmaceutical manufacturing zones attract contract fill-finish partnerships targeting regional demand. Egyptian clinical trial sites are gaining traction for multi-jurisdiction studies requiring parallel SAHPRA and SFDA coordination.
Israel
Specialized urology centers generate concentrated R&D investment for prostate cancer therapeutic vaccine applications. Israeli research institutes contribute early-stage RNA platform development through technology licensing arrangements with Gulf sovereign wealth funds. Tel Aviv's biotech corridor supports digital twin platforms that compress vaccine process development cycles for regional manufacturing partners.
Middle East and Africa Cancer Vaccines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement tiers in the Middle East and Africa Cancer Vaccines Market. Hospital network consolidation and ministry-level tender centralization are elevating the importance of distribution partnerships and cold-chain custody credentials. Three archetypes dominate: multinational pharmaceutical conglomerates with established regional infrastructure, RNA platform specialists leveraging modular manufacturing partnerships, and cellular therapy developers targeting point-of-care autologous processing. Competitive moves concentrate on strategic partnerships with Gulf sovereign wealth funds and capacity expansion through local fill-finish arrangements.
Among the multinational tier, AstraZeneca PLC and Merck & Co. Inc. occupy positions anchored by long-term supply agreements with government immunization programs and tertiary hospital networks. GSK plc exemplifies the infrastructure-dependent archetype through established cold-chain capabilities that support vaccine integrity in high-temperature climates. These three entities represent the dominant competitive positioning across Saudi Arabia's King Faisal Specialist Hospital network and affiliated research centers, where procurement committees prioritize suppliers with demonstrated local custody capabilities.
| Leading Market Players |
|---|
| AstraZeneca PLC |
| Merck & Co. Inc. |
| Bristol-Myers Squibb |
| Astellas Pharma Inc. |
| GSK plc |
| Pfizer Inc. |
| Sanofi |
| Moderna Inc. |
| Aduro Biotech Inc. |
| Others |
Supply & Pricing Matrix
Jebel Ali Port's pharmaceutical cold-chain corridors feed Gulf tertiary hospitals at freight premiums that compress margins for European suppliers while enabling price premiums for local distributors with SFDA-certified custody credentials. This logistics architecture concentrates pricing power among Saudi Arabia's National Unified Procurement Company and affiliated hospital networks, forcing import-dependent manufacturers to absorb transit costs or cede share to regional fill-finish partners.
Pricing Analysis
Certification level (WHO prequalification versus national-only registration) creates the primary spread between premium and standard vaccine tiers across Middle East and Africa procurement. Contract-based long-term offtake agreements dominate, with volume commitments to Saudi Arabia's King Faisal Specialist Hospital network commanding 15-20% discounts against spot purchases. Price differentiation stems from cold-chain custody credentials and local lot-release completion, with SFDA testing timelines adding implicit cost premiums. Cost compression in the standard tier intensifies as Egyptian and South African manufacturing zones expand fill-finish capacity. Government immunization programs exhibit highest price sensitivity; private oncology centers at Gulf tertiary hospitals remain least sensitive due to patient out-of-pocket coverage.
Supply Chain Analysis
Upstream lipid nanoparticle formulations and mRNA synthesis feedstocks concentrate in Germany, Switzerland, and selected U.S. contract manufacturers, with limited regional redundancy outside emerging Egyptian pharmaceutical zones. Active pharmaceutical ingredients for dendritic cell vaccines draw from European cell culture media suppliers and Asian bioreactor equipment providers. Single-source vulnerability runs through the minus-seventy-degree Celsius cold-chain infrastructure concentrated in Johannesburg, Riyadh, and Dubai. Distribution runs through ministry-level tender consolidation in Saudi Arabia and South Africa, with UAE free zones handling sub-Saharan re-export logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Cancer Vaccines Market sits in early-cycle expansion as RNA platform localization and tertiary hospital cellular therapy unit buildouts accelerate therapeutic vaccine penetration beyond preventive immunization baselines.
For Market Incumbents: Pre-empt modular manufacturing partnerships with Gulf sovereign wealth funds before European biotech firms lock exclusive RNA technology licensing arrangements. Secure backward integration into regional fill-finish capacity in Egypt's EDA-incentivized zones to defend against South African and Saudi local content requirements tightening procurement eligibility.
For New Entrants and Emerging Players: Point-of-care autologous processing capabilities at Saudi Arabia's Najd and Hejaz regional oncology centers represent the most penetrable entry point, bypassing centralized cold-chain infrastructure gaps that constrain European import models. Target SAHPRA reliance pathway submissions for WHO-prequalified products to compress South African registration timelines against competitors pursuing full dossier redevelopment.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates divesting non-core oncology assets amid portfolio rationalization pressures. Long-term viability hinges on regulatory sandbox participation in Gulf financial centers enabling novel biologics manufacturing finance structures. Monitor SFDA accelerated pathway designations for prostate and cervical malignancy vaccines as inflection indicators for regional demand concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Microfluidic Manufacturing Deployment | King Faisal Specialist Hospital units bypass European fill-finish dependencies through on-site RNA formulation. |
| SAHPRA Reliance Pathway Submission | Abbreviated dossiers for WHO-prequalified products compress South African registration timelines against full redevelopment. |
| Gulf Sovereign Wealth Fund Partnership | RNA technology licensing arrangements restructure competitive entry requirements for regional manufacturing. |
| Egyptian Manufacturing Zone Establishment | EDA regulatory incentives create captive supply serving North African and Levantine cervical vaccine demand. |
| Point-of-Care Autologous Processing | Decentralized dendritic cell preparation at regional oncology centers reduces patient travel burden across Saudi Arabia. |
Research Methodology
Cross-validation between regulatory filing analysis and hospital procurement database review anchors the qualitative findings in documented supply commitments and approved indication expansions. Primary interviews with SFDA regulatory affairs leads, SAHPRA clinical trial unit directors, King Faisal Specialist Hospital procurement managers, Egyptian EDA registration specialists, and Gulf sovereign wealth fund biotech investment officers combined with secondary validation through WHO prequalification listings, ClinicalTrials.gov protocol registrations, and national immunization program tender disclosures. Bottom-up patient population modeling and top-down manufacturer revenue triangulation across technology platform segments ensured consistency.
Calibration against historical WHO prequalification approval timelines and tertiary hospital cellular therapy unit expansion rates informed the projection framework across the analysis window. Segmentation dimensions modeled include product type (preventive, therapeutic, combination, oncolytic), technology platform (RNA, dendritic cell, DNA, virus-like particle), end-user infrastructure tier (tertiary hospital, research institute, clinic, manufacturer), and disease application (prostate, cervical, melanoma, breast). CAGRs derived from treatment protocol adoption curves and national immunization schedule expansion commitments, with RNA platform manufacturing localization timelines and SFDA accelerated pathway utilization rates as key forecast inputs.
Practitioners should monitor SAHPRA-SFDA-EDA harmonization progress, Gulf sovereign wealth fund biotech allocation shifts, and modular manufacturing unit deployment timelines for early signals requiring forecast revision. Cross-checking against WHO prequalification approval velocity and GAVI procurement eligibility announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market