
 Global CDKL5 Deficiency Disorder (CDD) Market | 2026-2036
Global CDKL5 Deficiency Disorder (CDD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global CDKL5 Deficiency Disorder (CDD) Market Foresight
The capital-intensity divergence between gene therapy platforms and small-molecule developers is redrawing competitive boundaries in CDD treatment. Ovid Therapeutics leverages its neurology-focused pipeline to sustain early-stage leadership in targeted pharmacological approaches. Ultragenyx Pharmaceutical anchors its position through rare disease commercial infrastructure that dominates specialty distribution channels. Marinus Pharmaceuticals differentiates via neurosteroid mechanisms that occupy a distinct mechanistic niche against competitive alternatives.
CDKL5 Deficiency Disorder constitutes a rare genetic epileptic encephalopathy arising from pathogenic variants in the CDKL5 gene on the X chromosome, characterized by early-onset seizures and severe neurodevelopmental impairment that demands multimodal intervention. The condition primarily serves pediatric neurology and genetic medicine by requiring coordinated seizure management, developmental support, and respiratory monitoring across care settings. Therapeutics command the largest value share within product type segments, while gene therapy represents the fastest-expanding treatment approach as clinical programs advance toward registrational trials. Pediatric neurology centers capture concentrated demand within end user segments, reflecting the diagnostic complexity and specialized monitoring requirements that define CDD care protocols.
FDA orphan drug designation and EMA priority medicines frameworks accelerate clinical development timelines and market access for CDD innovators navigating small-population trial design. Japan's PMDA sakigake designation and reimbursement pathways for pediatric rare diseases further shape regional commercial strategy for developers targeting Asian markets. Stakeholders must monitor regulatory precedent from adeno-associated virus gene therapies in parallel indications, as these decisions will establish manufacturing quality and long-term follow-up standards that transfer directly to CDD programs.
Market Dynamics
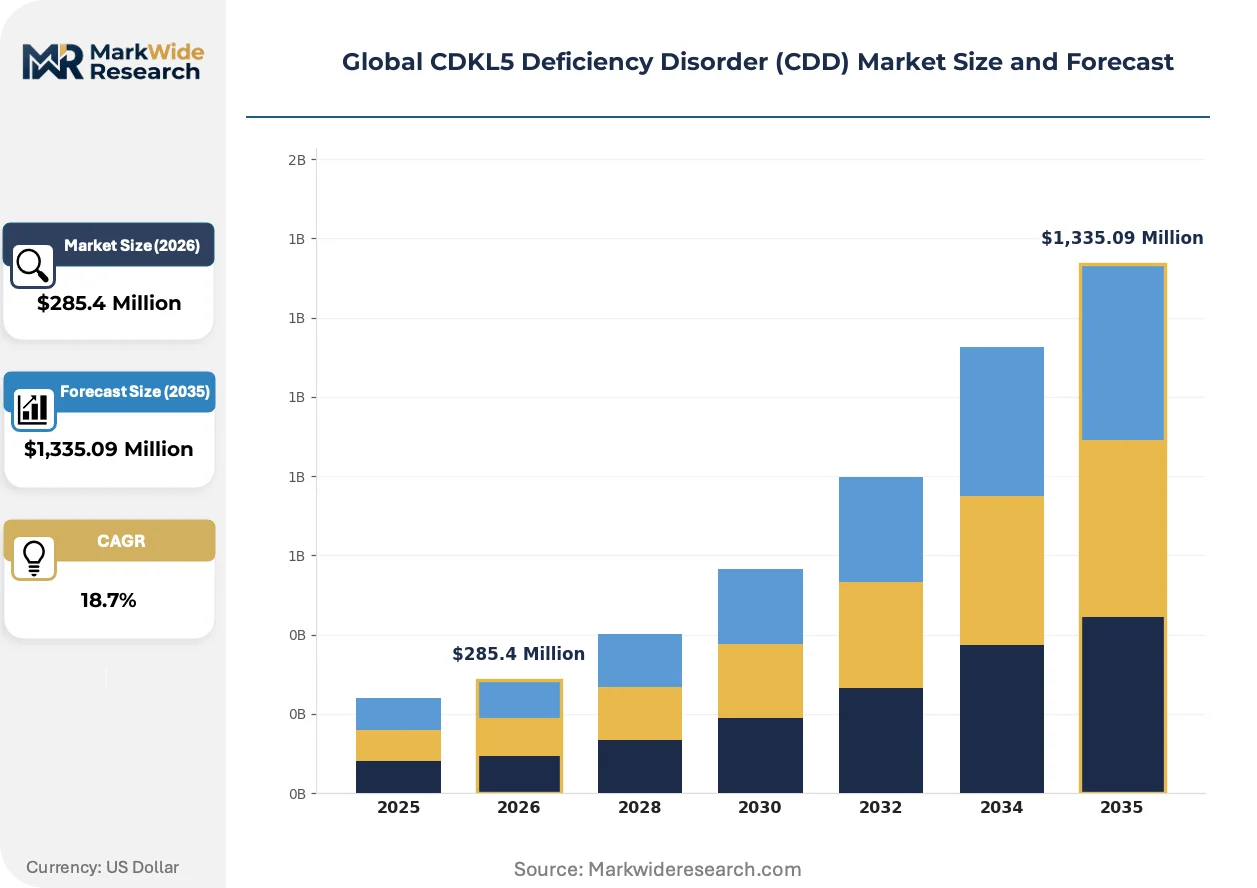
Gene therapy platform investments are compressing development timelines and redrawing capital allocation across the CDD therapeutic landscape, forcing small-molecule developers to defend mechanistic differentiation or risk pipeline obsolescence.
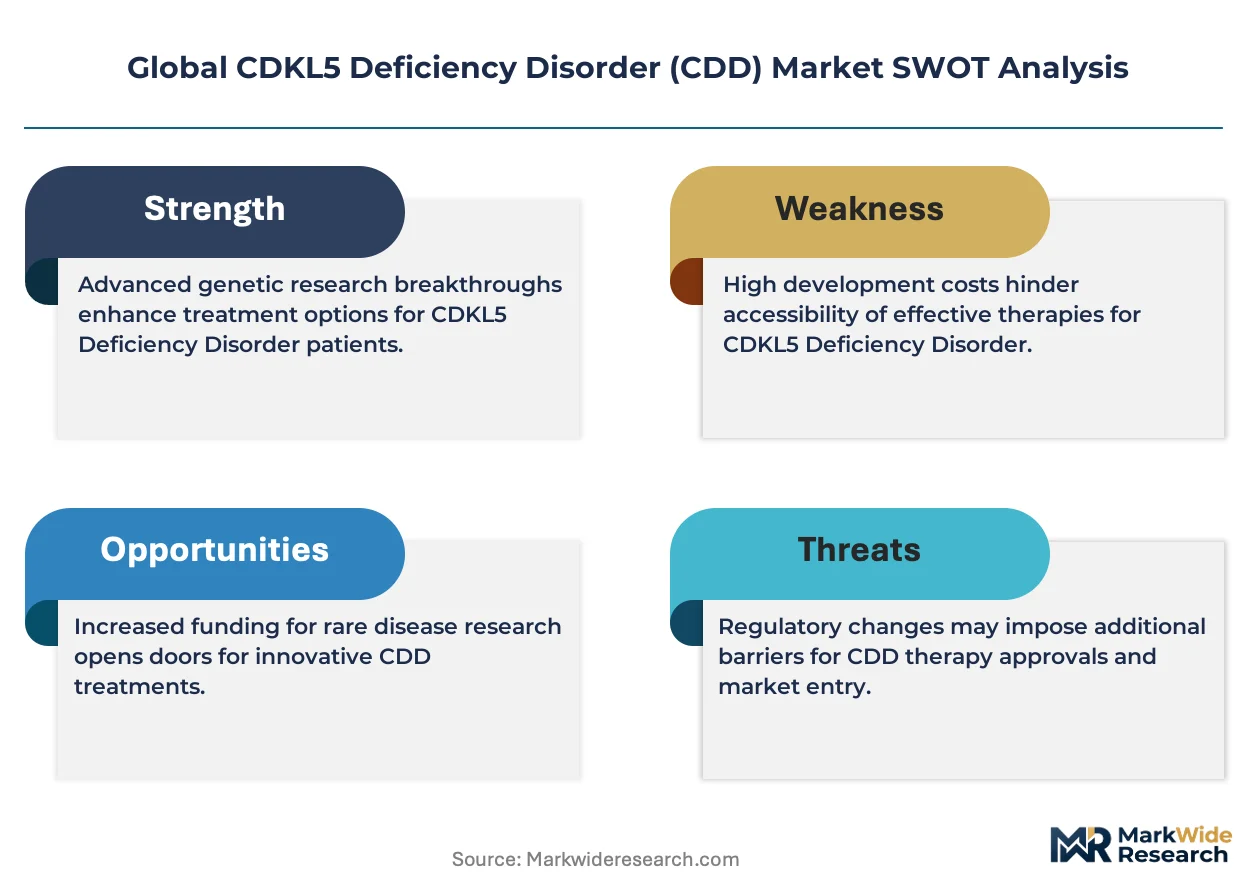
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate clinical trial enrollment for ultra-rare indications, reducing sponsor risk exposure in small-population studies.
- Pediatric Neurology Center Expansion:Specialized diagnostic infrastructure in Germany, Japan, and the United States concentrates referral flows and standardizes care protocols for seizure management.
- Adeno-Associated Virus Manufacturing Scale-Up:Contract development organizations are building dedicated viral vector capacity, lowering per-dose production costs for gene therapy candidates.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector production depends on a limited supplier base in North America and Europe, creating single-source vulnerability for gene therapy programs.
- Long-Term Follow-Up Requirements:FDA and EMA mandates for 15-year post-treatment monitoring impose sustained data collection burdens that inflate total development costs.
- Small-Population Trial Design Constraints:Natural history data gaps and phenotypic heterogeneity complicate endpoint selection and statistical powering for registrational studies.
Strategic Opportunities
- Japan's Sakigake Designation Pathway:PMDA priority review and early reimbursement consultation accelerate commercial timelines for pediatric rare disease therapies entering Asian markets.
- Neurosteroid Mechanism Adjacent Indications:Developers can leverage CDD clinical data to access broader epileptic encephalopathy populations with shared pathophysiology.
- Direct-to-Patient Genetic Testing:Consumer-initiated screening programs in the United States are identifying pre-symptomatic cases, expanding addressable patient pools earlier in disease progression.
Industry Challenges
- Pediatric Neurology Specialist Shortage:Fellowship training programs produce insufficient clinicians to staff expanding referral centers, creating diagnostic bottlenecks.
- Gene Therapy Vector Immunogenicity:Pre-existing neutralizing antibodies in patient populations exclude substantial portions of candidates from AAV-based trials.
- Multi-Site Trial Coordination Complexity:CDD rarity necessitates international site networks, complicating protocol harmonization across regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CDKL5 Deficiency Disorder (CDD) Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutics, Diagnostic Kits, Genetic Testing, Supportive Devices Application: Seizure Control, Cognitive Support, Motor Function, Respiratory Assistance, Nutritional Management End User: Specialty Clinics, Pediatric Neurology Centers, Research Institutes, Home Care Providers Treatment Approach: Pharmacological Therapy, Gene Therapy, Physical Therapy, Occupational Therapy, Speech Therapy |
| Companies Covered | Ovid Therapeutics, Ultragenyx Pharmaceutical, Marinus Pharmaceuticals, REGENXBIO, PTC Therapeutics, UCB S.A., Vyant Bio, Longboard Pharmaceuticals, Zogenix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CDKL5 Deficiency Disorder (CDD) Market Shifts & Advancements
Biological mechanism understanding is fragmenting the therapeutic landscape into modality-specific development tracks, each demanding distinct manufacturing competencies and regulatory engagement strategies.
Antisense oligonucleotide platforms are decomposing the traditional small-molecule dominance in genetic epilepsy by enabling transcript-level intervention. Pediatric neurology centers in the United States and Germany are establishing dedicated oligonucleotide infusion protocols. This technology is compressing the timeline from target validation to first-in-human studies for CDKL5-specific candidates.
EMA's priority medicines framework is accelerating assessment timelines for therapies addressing unmet pediatric needs, compressing the gap between Phase II data and conditional approval. Developers are restructuring regulatory submissions to align with rolling review provisions. Gene therapy sponsors targeting European markets are prioritizing this pathway to secure earlier revenue recognition.
Caregiver-driven demand for integrated seizure monitoring is displacing episodic clinic-based assessment in CDD management. Specialty pharmacies and home health services are capturing monitoring functions previously performed in hospital neurology departments. This shift is most pronounced in the United States, where remote patient monitoring reimbursement codes incentivize decentralized care models.
Global CDKL5 Deficiency Disorder (CDD) Market Segmentation
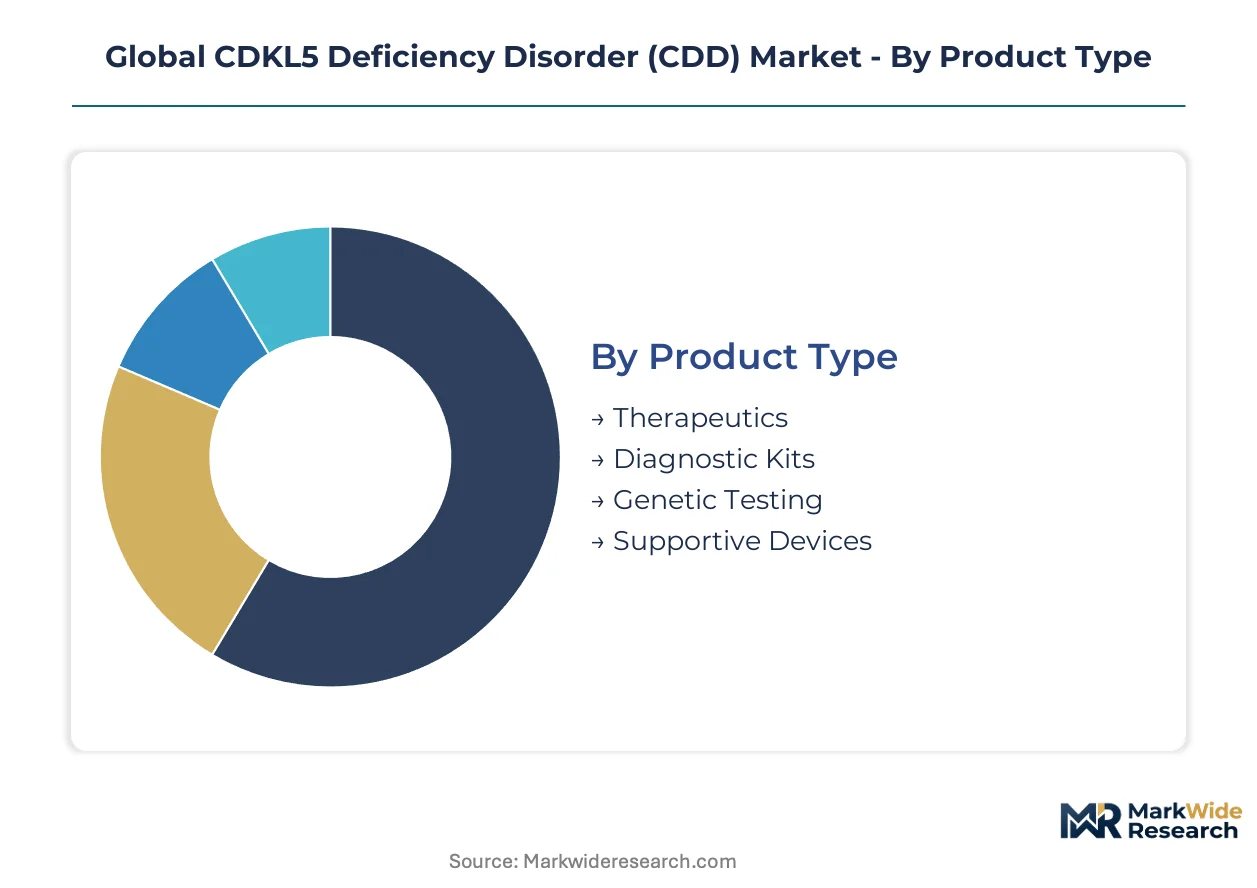
CDD market segmentation reflects the multimodal care requirements of a rare genetic epileptic encephalopathy. Treatment complexity demands coordinated investment across therapeutic modalities, diagnostic infrastructure, and specialized delivery settings.
Product Type:
Therapeutics capture the dominant margin pool within this category, driven by chronic administration requirements and orphan drug pricing frameworks.
- Therapeutics:Antiseizure medications, neurosteroids, and investigational gene therapy candidates constitute the revenue core. Pediatric neurology centers in the United States and Germany concentrate procurement for seizure control protocols, with FDA orphan drug exclusivity sustaining premium positioning.
- Genetic Testing:Next-generation sequencing panels and confirmatory variant analysis enable definitive CDKL5 diagnosis. Direct-to-patient screening programs in the United States are expanding pre-symptomatic identification, compressing time-to-diagnosis and enlarging addressable patient pools.
- Diagnostic Kits:Biomarker assays and biochemical screening tools support differential diagnosis workflows.
- Supportive Devices:Seizure monitoring equipment and respiratory support technologies address comorbidity management.
Therapeutics holds installed capacity. Genetic testing is rotating up the share rankings.
Application:
Seizure control absorbs the largest clinical resource allocation, reflecting the life-threatening nature of early-onset epileptic activity in CDD.
- Seizure Control:First-line anticonvulsants and rescue medications dominate acute intervention protocols. Specialty clinics across Germany, Japan, and the United States standardize treatment algorithms, with PMDA sakigake designation accelerating novel therapy access in Asian markets.
- Cognitive Support:Developmental interventions and educational adaptations target neuroplasticity windows. Research institutes in the United States and Europe drive protocol innovation, constrained by phenotypic heterogeneity that complicates outcome measurement.
- Motor Function:Physical rehabilitation and assistive mobility interventions address hypotonia and movement disorders.
- Respiratory Assistance:Ventilatory support and airway management technologies reduce mortality from respiratory compromise.
- Nutritional Management:Enteral feeding and metabolic optimization address failure-to-thrive presentations.
Seizure control commands the deepest clinical investment. Cognitive support is gaining share fastest as developmental outcomes enter regulatory endpoint frameworks.
End User:
Pediatric neurology centers concentrate the highest-acuity care and generate premium reimbursement rates for complex diagnostic and therapeutic procedures.
- Pediatric Neurology Centers:Tertiary referral hubs coordinate multidisciplinary care across seizure management, developmental monitoring, and genetic counseling. Centers in Boston, Heidelberg, and Tokyo anchor regional networks, though fellowship training shortages create staffing bottlenecks.
- Specialty Clinics:Dedicated rare disease and epilepsy-focused outpatient facilities extend access beyond academic medical centers. Germany's university hospital network and Japan's designated pediatric cancer and rare disease centers concentrate patient volumes.
- Research Institutes:Academic and contract research organizations execute natural history studies and clinical trials.
- Home Care Providers:Skilled nursing and remote monitoring services enable decentralized chronic management.
Pediatric neurology centers hold installed capacity. Specialty clinics are rotating up the share rankings.
Treatment Approach:
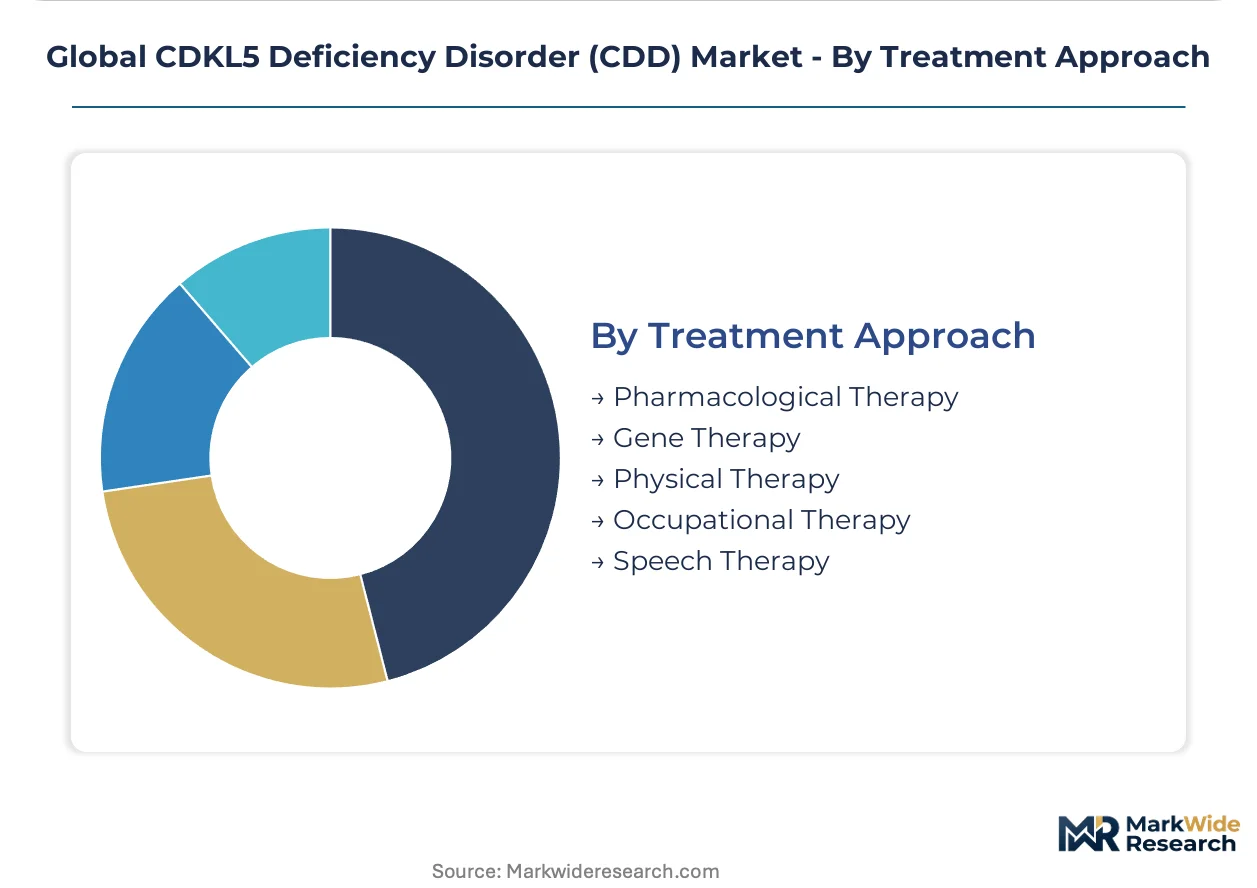
Pharmacological therapy currently absorbs the majority of commercial investment, though gene therapy platforms are compressing development timelines and redirecting capital flows.
- Pharmacological Therapy:Small-molecule anticonvulsants and neurosteroid modulators constitute the present standard of care. Ovid Therapeutics and Marinus Pharmaceuticals anchor mechanistic differentiation through GABA modulation and allopregnanolone analogs respectively.
- Gene Therapy:Adeno-associated viral vector delivery of functional CDKL5 transgenes represents the most closely watched modality. Ultragenyx Pharmaceutical leverages rare disease commercial infrastructure to prepare for registrational trials, with AAV manufacturing scale-up lowering per-dose production costs.
- Physical Therapy:Motor rehabilitation and orthotic interventions address musculoskeletal complications.
- Occupational Therapy:Adaptive skill development and sensory integration support daily functioning.
- Speech Therapy:Augmentative communication and feeding therapy address severe language impairment.
Pharmacological therapy holds installed capacity. Gene therapy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for CDD therapeutics concentrates in the United States and Germany, where orphan drug frameworks sustain premium reimbursement, while Japan's PMDA incentives accelerate access timelines at compressed price points. This asymmetry shapes commercial strategy across development-stage companies. Geographic expansion prioritizes regulatory jurisdictions with established pediatric neurology infrastructure and rare disease funding mechanisms.
United States
FDA orphan drug tax credits and seven-year market exclusivity provisions reduce sponsor risk in ultra-rare indications with small enrollment pools. Boston's pediatric neurology corridor anchors clinical trial density, with Massachusetts General and Boston Children's Hospital coordinating natural history studies that inform registrational endpoints. Direct-to-patient genetic testing programs in California and Texas expand pre-symptomatic identification.
Germany
EMA priority medicines designation compresses assessment timelines for pediatric epileptic encephalopathies with substantial unmet need. Heidelberg's university hospital network standardizes multidisciplinary care protocols across seizure management and developmental monitoring. The country's statutory health insurance funds rare disease therapies through centralized negotiation, creating predictable access for gene therapy candidates.
Japan
PMDA sakigake designation grants priority review and early reimbursement consultation for pediatric rare disease innovations entering Asian markets. Tokyo's designated pediatric cancer and rare disease centers concentrate patient volumes and establish referral pathways for CDD diagnosis. METI funding for AAV manufacturing scale-up lowers production costs for viral vector platforms targeting registrational trials.
United Kingdom
NICE technology appraisal processes evaluate CDD therapies against quality-adjusted life year thresholds, with highly specialized services designation enabling centralized procurement. London's Great Ormond Street Hospital anchors pediatric neurology referral networks and gene therapy clinical trial execution. The NHS Genomic Medicine Service accelerates variant identification through national testing infrastructure.
Canada
Health Canada's orphan drug framework provides data protection incentives and priority review for therapies addressing ultra-rare conditions with limited treatment options. Toronto's Hospital for Sick Children coordinates cross-provincial natural history registries that support international trial enrollment. Provincial drug plans negotiate rare disease funding through pan-Canadian Pharmaceutical Alliance mechanisms.
Global CDKL5 Deficiency Disorder (CDD) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in CDD therapeutics, with gene therapy platforms commanding development-stage premiums while small-molecule developers optimize manufacturing scale. The market structures around three tiers: large-cap rare disease specialists with commercial infrastructure, mid-cap neurology-focused developers with mechanistic differentiation, and platform-technology enablers supplying viral vector manufacturing. Dominant competitive moves include strategic partnerships to secure AAV manufacturing capacity and portfolio diversification into adjacent epileptic encephalopathies.
Within the neurology-focused tier, Ovid Therapeutics and Marinus Pharmaceuticals exemplify mechanistic differentiation through distinct pharmacological approaches to seizure control. Ultragenyx Pharmaceutical occupies a position bridging rare disease commercial infrastructure with gene therapy platform investment. These three anchors represent contrasting strategic bets on therapeutic modality—small-molecule optimization versus viral vector delivery—each demanding distinct capital allocation and regulatory engagement frameworks.
| Leading Market Players |
|---|
| Ovid Therapeutics |
| Ultragenyx Pharmaceutical |
| Marinus Pharmaceuticals |
| REGENXBIO |
| PTC Therapeutics |
| UCB S.A. |
| Vyant Bio |
| Longboard Pharmaceuticals |
| Zogenix |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between gene therapy sponsors and contract manufacturing organizations lock in AAV production capacity while anchoring per-dose cost visibility across multi-year development horizons. These arrangements insulate sponsors from plasmid DNA spot-market volatility while committing capital against regulatory milestones in the United States, Germany, and Japan.
Pricing Analysis
The customization-premium spread separates configured-to-order gene therapy manufacturing from standardized small-molecule procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA orphan drug exclusivity, EMA priority medicines designation, and volume scale in pediatric neurology centers. Cost compression in neurosteroid formulations is intensifying because generic anticonvulsant competition erodes first-line pricing power. Academic medical centers exhibit highest price sensitivity due to formulary budget constraints, while specialty clinics with dedicated rare disease funding demonstrate lowest sensitivity.
Supply Chain Analysis
Inbound logistics costs for AAV vector cold-chain distribution hinge on container availability across trans-Atlantic and trans-Pacific trade lanes serving Boston, Heidelberg, and Tokyo clinical sites. Plasmid DNA production concentrates in the United States and Germany, while viral vector fill-finish capacity clusters in Belgium and Singapore. Manufacturing inputs draw from recombinant protein suppliers, synthetic DNA foundries, and specialized cell banks. Single-source vulnerability for GMP-grade plasmid creates structural risk exposure. Distribution runs through specialty pharmacy networks with temperature-controlled last-mile capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CDD therapeutic landscape represents early-cycle expansion anchored by gene therapy clinical advancement toward registrational trials and caregiver-driven demand for integrated seizure monitoring solutions.
For Market Incumbents: Secure captive AAV manufacturing capacity through acquisition or exclusive partnership to defend against emerging platform-technology enablers with viral vector scale advantages. Prioritize regulatory dossier alignment with FDA rolling review provisions and EMA conditional approval frameworks to compress time-to-revenue against gene therapy entrants with manufacturing cost leadership. For New Entrants and Emerging Players: Remote patient monitoring service gaps in decentralized CDD care present white-space entry points where incumbent pharmacological developers under-serve caregiver demand for home-based seizure assessment. Target United States specialty pharmacy networks with direct-to-patient genetic testing integration as the most penetrable channel, leveraging reimbursement code arbitrage against hospital-based neurology departments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-technology enablers with multi-program AAV manufacturing contracts spanning CDD and adjacent rare neurological indications. Long-term viability over the five-to-ten year window favors acquisition targets with demonstrated regulatory engagement across FDA, EMA, and PMDA jurisdictions. Monitor first gene therapy Phase III readout in CDD as the definitive inflection signal for modality shift acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Dedicated AAV capacity in Massachusetts and Belgium lowers per-dose production costs for registrational programs. |
| Regulatory Approval Pathway | FDA rolling review and EMA priority medicines designation compress assessment timelines for pediatric rare disease therapies. |
| Clinical Trial Advancement | Natural history study enrollment across Boston, Heidelberg, and Tokyo sites establishes registrational endpoint precedents. |
| Pipeline Diversification | Neurosteroid mechanism extension into broader epileptic encephalopathy populations leverages shared pathophysiology data. |
| Licensing Agreement | Antisense oligonucleotide platform partnerships accelerate transcript-level intervention timelines for CDKL5-specific candidates. |
Research Methodology
The analysis maps gene therapy platforms, pharmacological therapeutics, genetic testing services, and supportive care devices, each validated through regulatory affairs leads at FDA and EMA, pediatric neurology center formulary directors, rare disease commercial infrastructure executives, and AAV manufacturing specialists. Primary interviews with drug development executives and payer access specialists combined with secondary validation against ClinicalTrials.gov, FDA orphan drug designation databases, EMA priority medicines registries, and PMDA sakigake approvals. Bottom-up patient population sizing and top-down orphan drug revenue benchmarks were triangulated for consistency.
Consistency checks validated volume and value outputs against external regulatory filing timelines and manufacturing capacity expansion announcements across the projection horizon. Segmentation dimensions modeled include treatment approach, product type, application, end user, and regional regulatory cluster. CAGRs were derived from adoption curve analysis anchored to gene therapy clinical milestone progression and pharmacological therapy lifecycle stage. Forecast inputs incorporated AAV manufacturing yield improvements and caregiver-driven monitoring technology penetration rates.
Underlying assumptions cover gene therapy regulatory approval probability, pharmacological therapy pricing persistence, and manufacturing scale-up execution, with deviation risk concentrated in vector immunogenicity exclusions and long-term follow-up data requirements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market