
 Exosomes Market | 2026-2036
Exosomes Market Size, Share, and Industry Trends Forecast 2026-2036
Exosomes Market Intelligence
Biopharmaceutical companies is unwinding the historical dominance of academic centers in exosome procurement, redirecting capital toward scalable manufacturing and therapeutic validation. Thermo Fisher Scientific Inc. leverages its analytical instrument portfolio to anchor downstream characterization workflows for commercial-grade exosome production. Lonza competes through its cell-and-gene therapy CDMO infrastructure, extending bioreactor capabilities into extracellular vesicle GMP manufacturing. Danaher specializes in precision diagnostics, positioning its life sciences platform to capture quality-control spend across the exosome supply chain.
Exosomes are lipid bilayer-enclosed extracellular vesicles measuring 30–150 nanometers in diameter, secreted by mammalian cells and enriched in proteins, nucleic acids, and lipids that mediate intercellular communication; they function as natural drug delivery vehicles capable of crossing biological barriers including the blood-brain barrier. Isolation Kits currently dominate instrument spend due to persistent workflow bottlenecks in upstream purification, though Characterization Instruments is accelerating as regulatory filings demand higher-resolution physicochemical profiling. Neurological Disorders commands concentrated R&D investment given the intranasal delivery pathway's demonstrated CNS tropoism, while Regenerative Medicine occupies the deepest margin pool through autologous exosome therapies priced at premium therapeutic tiers.
FDA draft guidance on human cells, tissues, and cellular tissue-based products shapes exosome manufacturing standards in the United States, while EMA's reflection paper on extracellular vesicle-based medicinal products dictates European market access requirements. Japan's PMDA has established accelerated review pathways for regenerative medicine products encompassing exosome therapies, creating regulatory arbitrage for sponsors prioritizing East Asian trial placement. Stakeholders must monitor evolving GMP Annex 1 contamination control expectations for sterile vesicle production and decide whether to build captive isolation capacity or outsource to established CDMO networks before capacity constraints harden.
Market Dynamics
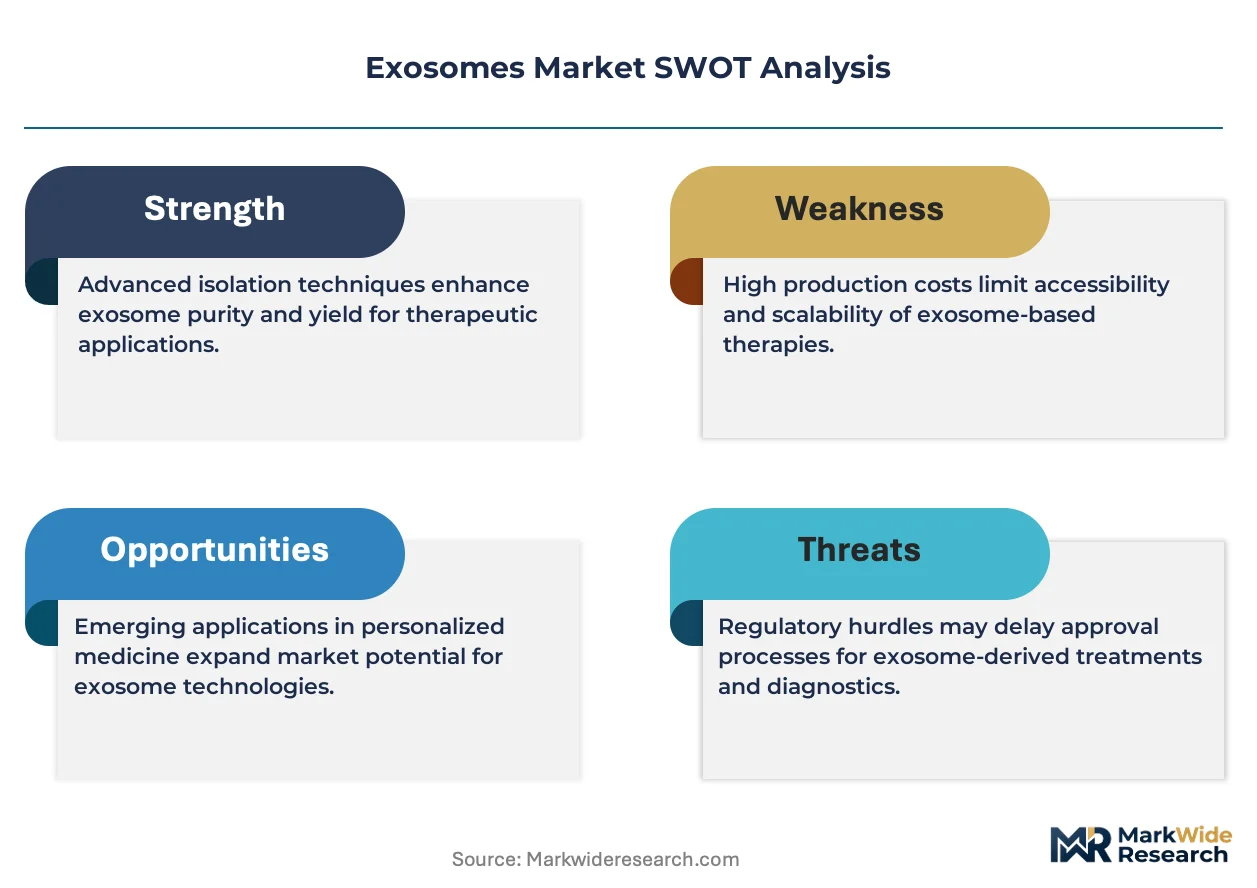
Cell-free biologics are displacing viral vectors in drug delivery, redirecting capital from academic procurement toward scalable GMP manufacturing infrastructure controlled by biopharmaceutical sponsors.
Growth Catalysts
- PMDA Accelerated Pathways:Japan's regenerative medicine review framework compresses exosome therapy timelines, attracting East Asian trial placement from Western sponsors.
- Intranasal CNS Delivery:Neurological disorder applications exploit demonstrated blood-brain barrier penetration, concentrating R&D investment in neurodegenerative pipelines.
- GMP Annex 1 Harmonization:FDA and EMA alignment on sterile vesicle contamination control accelerates quality standard convergence across manufacturing networks.
Market Restraints
- Upstream Purification Bottlenecks:Tangential flow filtration and chromatography resin costs concentrate spend in isolation workflows, constraining margin expansion.
- CDMO Capacity Concentration:Lonza and Thermo Fisher networks dominate commercial-grade manufacturing, creating single-source dependencies for emerging sponsors.
- Physicochemical Characterization Gaps:Sub-50 nanometer vesicle resolution limits remain unresolved, delaying regulatory filings for heterogenous populations.
Strategic Opportunities
- Autologous Premium Therapies:Regenerative medicine applications command pricing tiers unachievable with allogeneic alternatives, deepening margin pools for personalized workflows.
- Quality-Control Instrumentation:Danaher's precision diagnostics platform captures downstream spend as characterization demands intensify across the supply chain.
- German GMP Infrastructure:Heidelberg and Munich bioclusters offer established sterile manufacturing capacity underserved by current sponsor demand.
Industry Challenges
- Extracellular Vesicle Classification Ambiguity:FDA draft guidance on human cells and tissues creates compliance interpretation disputes, extending pre-IND consultation timelines.
- Bioreactor Scale-Up Expertise Scarcity:Cell-and-gene therapy talent pools lack vesicle-specific shear stress and harvest optimization experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exosomes Market |
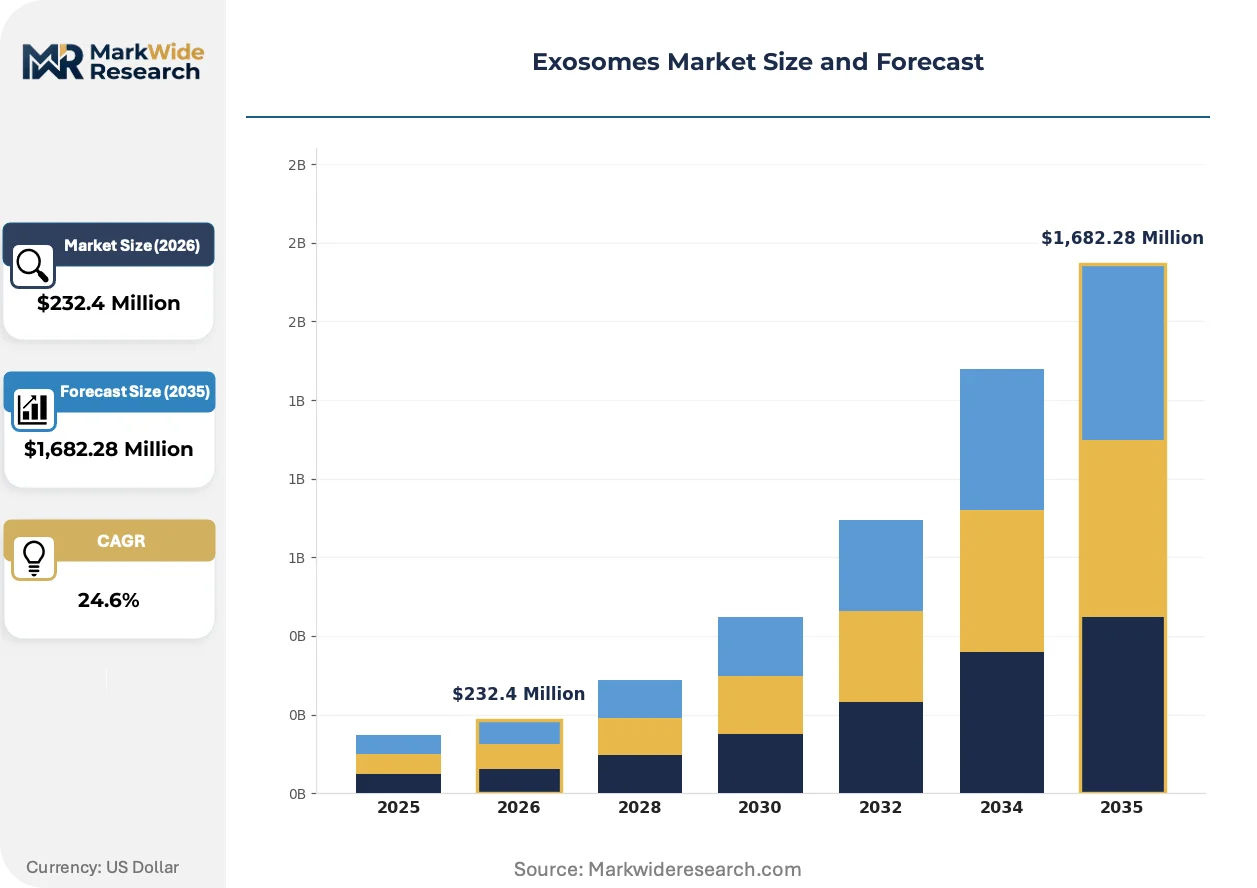
| Market Size in 2026 | $232.4 Million |
| Market Size in 2035 | $1,682.28 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolation Kits, Labeling Reagents, Characterization Instruments, Storage Solutions Therapy Area: Neurological Disorders, Cardiovascular Diseases, Immunotherapy, Regenerative Medicine, Cancer Treatment End User: Research Institutions, Biopharmaceutical Companies, Diagnostic Laboratories, Academic Centers Delivery Mode: Intravenous, Intranasal, Subcutaneous, Oral, Topical |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Techne, QIAGEN, Lonza, Danaher, System Biosciences LLC, Codiak BioSciences, Evox Therapeutics, ExoCoBio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exosomes Market Strategic Shifts & Innovations
Manufacturing technology and regulatory classification frameworks are actively restructuring competitive positioning, separating analytical instrumentation investments from upstream purification capabilities.
Microfluidic isolation platforms are bifurcating the purification landscape. Biopharmaceutical sponsors adopt these systems for clinical-scale production while academic centers retain ultracentrifugation workflows. This technology split is compressing CDMO negotiation leverage for sponsors with captive microfluidic capacity.
EMA's reflection paper on extracellular vesicle-based medicinal products imposes manufacturing and quality documentation requirements that exceed prior cell therapy precedents. European sponsors now face extended CMC development timelines. German and Swiss manufacturers are responding by integrating EMA feedback into early-phase protocol design.
Buyer concentration among biopharmaceutical companies is consolidating procurement authority previously dispersed across academic principal investigators. Thermo Fisher and Lonza now negotiate directly with centralized sourcing functions rather than individual research groups. This shift is most visible in United States coastal clusters where sponsor headquarters density enables face-to-face contract negotiations.
Exosomes Market Segmentation
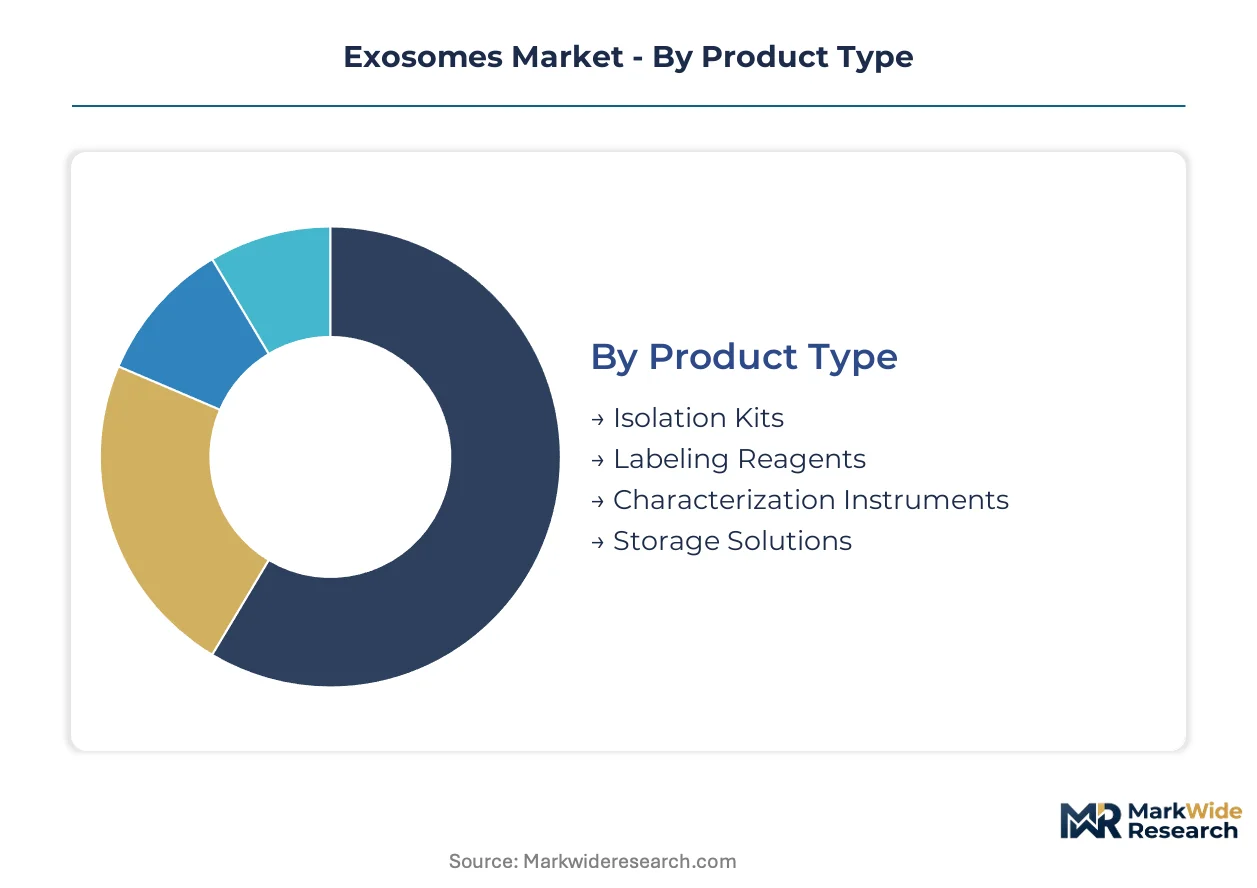
Exosome market segmentation reflects divergent commercial maturity across workflow stages. Product type splits reveal where capital concentrates versus where standardization lags. Therapy area and delivery mode segmentation exposes which indications justify premium manufacturing investment versus commodity positioning.
Product Type:
Isolation Kits and Characterization Instruments anchor procurement spend in United States and German bioclusters, while Labeling Reagents and Storage Solutions follow distributed academic demand across export markets.
- Isolation Kits:These workflow bundles integrate ultracentrifugation media, precipitation reagents, and size-exclusion chromatography consumables for upstream purification. Demand concentrates in biopharmaceutical companies scaling GMP workflows in Massachusetts and North Carolina, though tangential flow filtration resin costs constrain margin expansion.
- Characterization Instruments:Nanoparticle tracking analyzers, flow cytometry systems, and cryo-electron microscopy platforms enable physicochemical profiling for regulatory filings. Investment clusters in Heidelberg and Munich where EMA-aligned documentation requirements exceed prior cell therapy precedents.
- Labeling Reagents:Fluorescent and biotin conjugation kits for exosome surface marker detection.
- Storage Solutions:Cryopreservation media and temperature-controlled logistics consumables.
Isolation Kits commands the established base. The steepest expansion runs through Characterization Instruments.
Therapy Area:
Margin depth stratifies sharply: Neurological Disorders and Regenerative Medicine capture premium pricing tiers, while Immunotherapy and Cancer Treatment compete on allogeneic scale economics.
- Neurological Disorders:Intranasal delivery pathways exploit demonstrated blood-brain barrier penetration for neurodegenerative indications. Japanese sponsors dominate early-phase placement through PMDA accelerated review pathways, compressing development timelines versus FDA routes.
- Regenerative Medicine:Autologous exosome therapies command pricing tiers unachievable with donor-derived alternatives. Heidelberg manufacturers integrate EMA feedback into protocol design, extending CMC development timelines but securing market access.
- Cardiovascular Diseases:Myocardial repair applications leveraging exosome-mediated angiogenesis.
- Immunotherapy:Exosome-loaded antigen presentation for cancer vaccine platforms.
- Cancer Treatment:Tumor-derived exosome inhibition and engineered vesicle drug delivery.
Regenerative Medicine captures premium margin pools. Neurological Disorders gains share fastest on intranasal CNS delivery validation.
End User:
Procurement authority is shifting from dispersed academic principal investigators toward centralized biopharmaceutical sourcing functions in coastal United States clusters.
- Biopharmaceutical Companies:These sponsors now direct capital toward scalable GMP manufacturing and therapeutic validation, unwinding historical academic dominance. Thermo Fisher and Lonza negotiate directly with centralized sourcing rather than individual research groups.
- Research Institutions:Retain ultracentrifugation workflows for discovery-scale production, though microfluidic adoption lags commercial sponsors.
- Diagnostic Laboratories:Quality-control spend for clinical-grade exosome quantification in liquid biopsy applications.
- Academic Centers:Principal investigator-led procurement persists in European university clusters with limited CDMO outsourcing.
Research Institutions retain the volume base. Biopharmaceutical Companies climbs the fastest as cell-free biologics displace viral vectors.
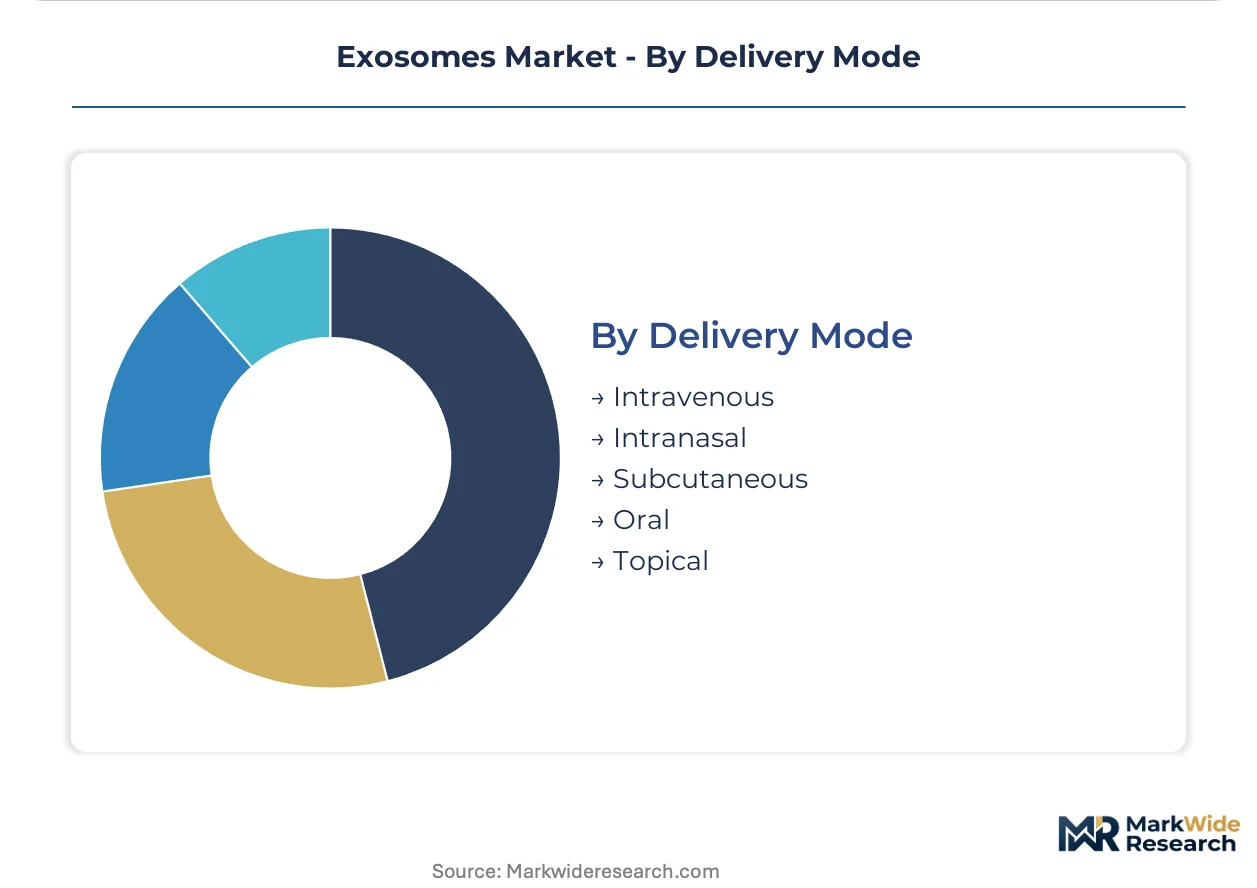
Delivery Mode:
Route selection determines manufacturing complexity and regulatory pathway, with intranasal and intravenous commanding distinct quality standards versus topical and oral commoditization.
- Intranasal:Olfactory epithelium targeting enables direct CNS access without systemic circulation. PMDA's regenerative medicine framework in Japan prioritizes this route for neurological indications, attracting Western sponsor trial placement.
- Intravenous:Systemic administration requires stringent endotoxin and particle aggregation controls for FDA compliance.
- Subcutaneous:Depot formation kinetics suitable for sustained-release regenerative applications.
- Oral:Gastrointestinal stability challenges limit current commercial viability.
- Topical:Dermal and ocular surface applications with reduced barrier penetration requirements.
Intravenous anchors the established base. Intranasal shows the steepest expansion trajectory on blood-brain barrier penetration validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German exosome manufacturers export GMP-grade isolation kits to United States biopharmaceutical sponsors, while Japanese CDMOs supply intranasal formulation expertise to Western neurological therapy developers.
United States
Massachusetts and North Carolina bioclusters drive procurement of characterization instruments for FDA-compliant CMC documentation. FDA draft guidance on human cells, tissues, and cellular tissue-based products shapes sterile vesicle manufacturing standards. Greater Boston sponsors negotiate directly with CDMO networks for scalable GMP capacity.
Germany
Heidelberg and Munich manufacturers concentrate EMA-aligned exosome production for European market access. EMA's reflection paper on extracellular vesicle-based medicinal products imposes documentation requirements exceeding prior cell therapy precedents. Bavarian bioclusters integrate regulatory feedback into early-phase protocol design.
Japan
PMDA accelerated review pathways for regenerative medicine products attract Western sponsor trial placement for neurological indications. METI coordinates national cell therapy infrastructure investments. Tokyo-Osaka corridor sponsors exploit intranasal delivery validation to compress development timelines versus FDA routes.
Switzerland
Swissmedic oversight of advanced therapy medicinal products positions Basel-Zurich corridor for cross-border European supply. Precision diagnostics demand from German sponsors drives instrument procurement. Swiss CDMOs leverage bilateral regulatory recognition agreements for streamlined EMA market access.
United Kingdom
London-Oxford-Cambridge triangle sponsors navigate MHRA post-Brexit alignment with EMA standards for exosome classification. Academic centers retain discovery-scale ultracentrifugation workflows while commercial sponsors outsource GMP manufacturing. UK bioclusters face extended CMC timelines pending regulatory harmonization clarity.
Exosomes Market Key Industry Players
Listed leaders compete with private specialists across analytical instrumentation and CDMO service provision, creating a tiered structure where scale advantages concentrate in public companies. Thermo Fisher Scientific and Danaher anchor the listed tier through diversified life sciences portfolios, while Lonza represents the CDMO archetype with captive bioreactor networks. Private specialists including System Biosciences and Evox Therapeutics occupy niche technology positions. Competitive moves center on strategic partnerships for manufacturing capacity and portfolio diversification into characterization instrumentation.
Within the diversified life sciences tier, Thermo Fisher Scientific Inc. and Danaher occupy positions anchored by analytical instrument portfolios, while Lonza exemplifies the CDMO archetype extending cell-and-gene therapy infrastructure into extracellular vesicle GMP manufacturing. These three entities represent distinct competitive vectors: instrumentation capture, quality-control spend, and scalable production capacity.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Techne |
| QIAGEN |
| Lonza |
| Danaher |
| System Biosciences LLC |
| Codiak BioSciences |
| Evox Therapeutics |
| ExoCoBio |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements with Lonza and Thermo Fisher networks lock in GMP manufacturing slots eighteen to twenty-four months forward, anchoring price visibility for biopharmaceutical sponsors while constraining negotiating leverage for emerging entrants lacking established CDMO relationships. These contracts concentrate procurement authority among sponsors with sufficient capital to prepay for sterile vesicle production capacity in Massachusetts and North Carolina bioclusters.
Pricing Analysis
Prior-generation ultracentrifugation workflows command commodity pricing tiers as microfluidic isolation platforms establish premium positioning for clinical-scale production. Three-tier pricing structure across premium, standard, and economy levels stratifies by GMP certification grade and endotoxin control stringency. Cost compression in isolation kits is intensifying because tangential flow filtration resin suppliers concentrate pricing power. Academic centers exhibit highest price sensitivity versus biopharmaceutical sponsors prioritizing regulatory compliance over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for chromatography resins and analytical standards sourced from Japanese and German manufacturers. Production gravity centers on United States, Germany, and Japan where GMP infrastructure density outpaces alternative territories. Raw material dependencies include tangential flow filtration membranes, size-exclusion chromatography media, and cryopreservation excipients. Single-source vulnerability concentrates in Lonza's bioreactor network for commercial-grade vesicle harvest. Distribution runs through CDMO direct contracts rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioreactor scale-up expertise for shear stress optimization and harvest timing represents the critical capability gap separating commercial sponsors from academic competitors, with talent scarcity driving CDMO premiums and captive facility investments.
For Market Incumbents: Secure GMP Annex 1 contamination control certification ahead of regulatory harmonization between FDA and EMA, while adding captive microfluidic isolation capacity in Heidelberg or Munich to reduce dependency on Thermo Fisher and Lonza networks. Synthetic exosome competitors and viral vector incumbents threaten pricing power in neurological delivery applications. For New Entrants and Emerging Players: PMDA accelerated review pathway certification offers fastest regulatory validation for intranasal CNS delivery indications, enabling market entry ahead of FDA timeline compression. White-space concentrates in autologous regenerative medicine workflows for German bioclusters underserved by current sponsor demand. Partner with established CDMOs for initial GMP batches rather than building captive capacity. For Investors and Strategic Acquirers: Niche characterization instrumentation specialists with nanoparticle tracking analyzer portfolios represent priority acquisition targets as regulatory filings intensify physicochemical profiling demands. Long-term viability hinges on differentiation between analytical platform providers and commodity isolation kit manufacturers. Watch for EMA reflection paper finalization as inflection indicator for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CDMO Capacity Reservation | Prepaid manufacturing slots with Lonza secure GMP compliance timelines for FDA submissions. |
| Microfluidic Platform Adoption | Clinical-scale isolation systems compress CDMO negotiation leverage for sponsor procurement functions. |
| PMDA Trial Placement | Japanese accelerated review pathways compress neurological indication development versus FDA routes. |
| Characterization Instrument Investment | Nanoparticle tracking analyzer procurement captures downstream quality-control spend from biopharmaceutical sponsors. |
| GMP Annex 1 Compliance Buildout | Contamination control infrastructure investments align with FDA-EMA harmonization expectations for sterile vesicle production. |
Research Approach
Desk research of FDA draft guidance documents, EMA reflection papers, and PMDA accelerated pathway regulations preceded structured interviews with exosome manufacturing executives, regulatory affairs leads at biopharmaceutical sponsors, CDMO procurement managers, and academic principal investigators. Secondary validation drew from ClinicalTrials.gov exosome therapy entries, SEC 10-K filings of listed life sciences companies, and German biocluster investment disclosures. Bottom-up segment sizing triangulated against top-down market consolidation analysis.
Variance decomposition across product type, therapy area, end user, and delivery mode segmentation dimensions enabled attribution of growth contribution by workflow stage. CAGRs were derived from regression analysis of procurement spend patterns and manufacturing capacity expansion announcements across the analysis window. Forecast inputs incorporated PMDA review timeline compression effects and GMP infrastructure investment cycles in United States coastal clusters.
Underlying assumptions cover sustained FDA-EMA regulatory harmonization progress and stable tangential flow filtration resin supply, with deviation risk concentrated in physicochemical characterization standard delays and CDMO capacity constraints. Forecasts reflect these documented assumptions with acknowledgment that extracellular vesicle classification ambiguity or bioreactor scale-up expertise scarcity could materially revise projections. Recalibration cycles align with material shifts in regulatory guidance finalization and GMP infrastructure commissioning announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Biochips Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Cell Proliferation Assay Market
Biomedical Technology
Pyrosequencing Market