
 Global T-Cell Acute Lymphoblastic Leukemia Treatment Market | 2026-2036
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market Foresight
Multi-source biologics sourcing is repositioning how developers secure active pharmaceutical ingredients for CAR-T and antibody constructs. Bristol-Myers Squibb leverages its cell therapy manufacturing footprint across three continents to sustain supply continuity for blinatumomab-class programs. Novartis anchors its pipeline through in-house viral vector production, while Genmab differentiates via proprietary DuoBody platform technology for next-generation T-cell engagers.
T-cell acute lymphoblastic leukemia treatment encompasses cytotoxic, targeted, and immuno-oncology modalities designed to eliminate malignant lymphoid progenitors and prevent central nervous system sanctuary site relapse; chimeric antigen receptor T-cell therapies require leukapheresis collection, ex vivo lentiviral transduction, and expansion to a dose of 10^6–10^8 viable cells per kilogram. Chemotherapy and immunotherapy segments command the largest current revenue pools given established reimbursement for induction and consolidation regimens, while monoclonal antibodies represent the fastest-growing category as bispecific T-cell engagers expand into frontline combinations. The relapsed/refractory therapy area remains the most commercially contested indication, though minimal residual disease-negative conversion endpoints are shifting trial design and payer value assessment.
FDA accelerated approval and EMA conditional marketing authorization frameworks shape development economics by permitting surrogate endpoint-based submissions for hematologic malignancies. The EU AI Act and GDPR impose data governance requirements on real-world evidence generation for post-market commitments, while WHO prequalification standards influence procurement in low-income country access programs. Stakeholders must monitor how FDA Project Optimus dose-optimization mandates reshape Phase II trial designs for small molecule and biologic combinations.
Market Dynamics
FDA Project Optimus dose-optimization mandates are compressing Phase II trial timelines for T-ALL combination therapies, forcing sponsors to redesign protocols around pharmacokinetic-guided escalation rather than traditional maximum-tolerated-dose approaches.
Growth Catalysts
- Accelerated Approval Pathways:FDA's surrogate endpoint framework for hematologic malignancies permits earlier market entry based on minimal residual disease negativity, shortening development cycles for novel biologics.
- Pediatric Oncology Network Expansion:Dedicated childhood cancer centers in the United States, Germany, and Japan are broadening first-line CAR-T eligibility criteria and referral volumes.
- Lentiviral Vector Manufacturing Scale-Up:In-house viral production capabilities at major biologics manufacturers are reducing dependency on third-party CDMOs for cell therapy supply security.
Market Restraints
- Leukapheresis Collection Bottlenecks:Specialized apheresis center capacity constraints in rural and secondary markets limit patient access to autologous CAR-T therapies.
- Central Nervous System Prophylaxis Complexity:Intrathecal chemotherapy requirements and blood-brain barrier penetration challenges for systemic agents elevate relapse risk in sanctuary sites.
- Reimbursement Uncertainty for MRD-Guided Therapy:Payer skepticism toward minimal residual disease testing as a definitive treatment endpoint creates access friction for next-generation protocols.
Strategic Opportunities
- Allogeneic Off-the-Shelf Platforms:Universal donor-derived CAR-T programs eliminate leukapheresis dependency and manufacturing lead times, opening community hospital access.
- EU Conditional Marketing Authorization:EMA's early access framework permits revenue generation during confirmatory trials for therapies addressing high unmet need in relapsed pediatric populations.
- Bispecific T-Cell Engager Frontline Integration:Blinatumomab-class antibodies are penetrating induction regimens previously dominated by chemotherapy alone.
Industry Challenges
- Cell Therapy Manufacturing Workforce Scarcity:Qualified aseptic processing technicians and vector production specialists command premium compensation, constraining capacity expansion.
- Post-Market Real-World Evidence Infrastructure:GDPR and EU AI Act compliance requirements complicate multi-country patient registry construction for accelerated approval confirmatory studies.
- Cryopreservation Logistics Integration:Cold chain integrity across apheresis collection, manufacturing, and infusion sites demands capital-intensive quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global T-Cell Acute Lymphoblastic Leukemia Treatment Market |
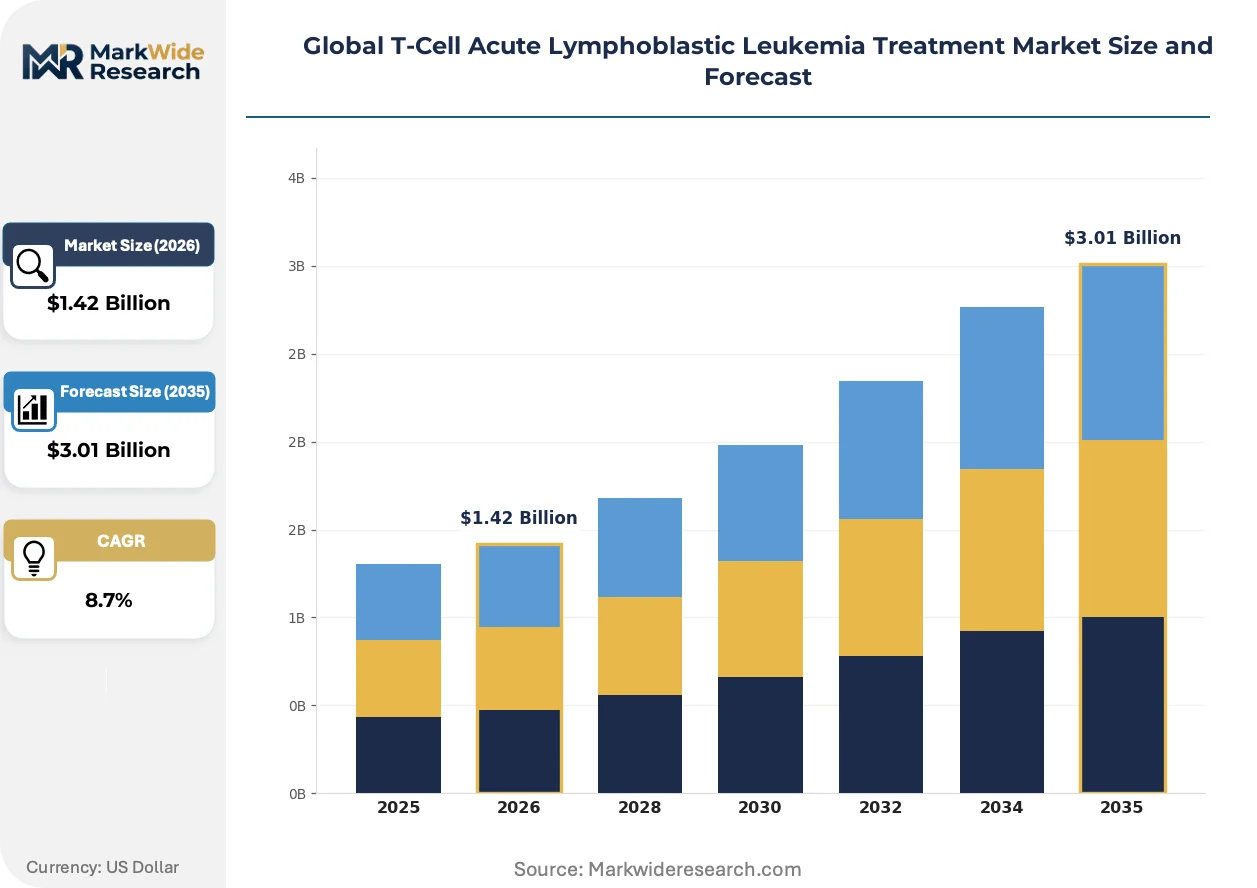
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Tyrosine Kinase Inhibitors, Monoclonal Antibodies, Small Molecule Drugs Therapy Area: Relapsed/Refractory, Newly Diagnosed, Minimal Residual Disease, Central Nervous System Involvement End User: Oncology Centers, Specialized Clinics, Research Institutes, Hematology Departments Delivery Mode: Intravenous, Oral, Subcutaneous, Intrathecal, Combination Therapy |
| Companies Covered | Genmab, F. Hoffmann-La Roche, Bristol-Myers Squibb, GlaxoSmithKline, Gilead Sciences, Novartis, Kyowa Kirin, Spectrum Pharmaceuticals, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market Shifts & Advancements
Bi-specific antibody engineering and allogeneic cell sourcing are converging to reduce treatment access barriers, while regulatory frameworks on both sides of the Atlantic reward earlier evidence generation.
Next-generation T-cell engagers incorporating extended half-life Fc engineering and tumor microenvironment conditioning domains are consolidating competitive positioning in the relapsed/refractory setting. Pediatric oncology centers in the United States and Germany are adopting these constructs ahead of formal frontline label expansion, compressing the historical gap between regulatory approval and clinical practice uptake. This acceleration is displacing salvage chemotherapy as the default second-line option and forcing protocol redesign around combination sequencing.
EMA's integration of the EU AI Act into pharmacovigilance systems is reshaping how real-world evidence supports conditional marketing authorizations for hematologic malignancies. Automated signal detection algorithms now require documented bias mitigation and training data governance, elevating compliance costs for post-market commitment fulfillment. Sponsors with established European patient registries are adapting infrastructure to meet algorithmic transparency requirements before the 2026 enforcement deadline.
Academic medical centers are unbundling CAR-T care pathways into discrete reimbursement-eligible components, separating apheresis, manufacturing, and infusion billing. This granularity allows community hospitals in Japan and select United States metropolitan areas to participate in referral networks without full programmatic accreditation. The shift is most visible in regions with concentrated pediatric hematology expertise and established commercial payer carve-out arrangements for cellular therapy.
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market Segmentation
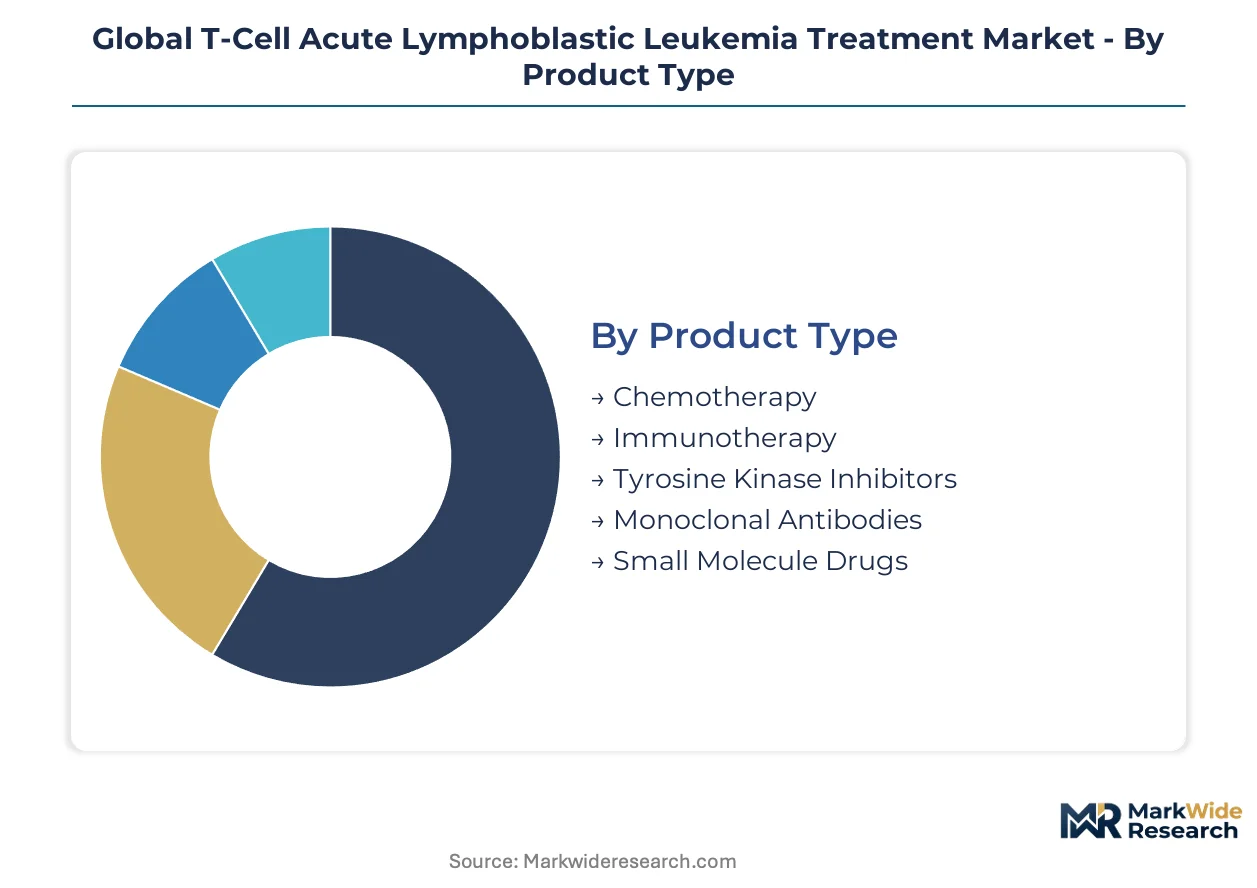
T-Cell Acute Lymphoblastic Leukemia treatment modalities span cytotoxic, targeted, and cellular therapy platforms with distinct manufacturing requirements and reimbursement pathways. Segmentation reveals how clinical decision-making splits across disease stage, delivery complexity, and care setting infrastructure.
Product Type:
Technology differentiation separates legacy cytotoxic platforms from engineered biologics and precision small molecules.
- Chemotherapy:Multi-agent cytotoxic regimens combining vincristine, daunorubicin, and asparaginase derivatives remain the backbone of pediatric induction protocols. Demand concentrates in United States and German academic medical centers where established reimbursement codes support intensive inpatient administration.
- Monoclonal Antibodies:Bispecific T-cell engagers and CD3-directed constructs enable outpatient administration with reduced myelosuppression versus chemotherapy. United States pediatric oncology networks are expanding frontline eligibility for blinatumomab-class antibodies, displacing salvage chemotherapy in second-line positioning.
- Immunotherapy:CAR-T cell therapies requiring leukapheresis and ex vivo expansion deliver durable remissions in relapsed populations. Manufacturing complexity limits access to specialized centers.
- Tyrosine Kinase Inhibitors:Targeted small molecules addressing NOTCH1 and ABL1 pathway aberrations serve niche mutation-defined subsets. Clinical trial networks in Japan and Germany are evaluating combination sequencing.
- Small Molecule Drugs:Novel agents targeting epigenetic regulators and metabolic vulnerabilities are advancing through early-phase development. Orphan drug designation accelerates regulatory timelines.
Chemotherapy leads on scale; monoclonal antibodies lead on momentum.
Therapy Area:
Disease stage and molecular response status determine treatment intensity and access to novel modalities.
- Relapsed/Refractory:Patients failing frontline induction or experiencing early relapse require salvage regimens with curative intent. CAR-T and bispecific antibody trials concentrate in United States and German referral centers with cellular therapy accreditation.
- Newly Diagnosed:Standard-risk pediatric protocols emphasize chemotherapy backbone with risk-stratified intensification. Japan's pediatric leukemia study group has adopted MRD-guided treatment allocation.
- Minimal Residual Disease:MRD-negative conversion serves as surrogate endpoint for accelerated approval and guides consolidation therapy decisions. Payer skepticism toward MRD testing as definitive endpoint creates access friction in United States commercial plans.
- Central Nervous System Involvement:Sanctuary site disease requires intrathecal chemotherapy and blood-brain barrier penetration strategies. Prophylaxis complexity elevates relapse risk in community hospital settings lacking neuro-oncology coordination.
Newly diagnosed therapy commands the largest patient volume; minimal residual disease protocols are expanding most quickly as regulatory endpoints.
End User:
Care setting capabilities determine eligibility for cellular therapy and complex combination protocols.
- Oncology Centers:Comprehensive cancer centers with embedded cellular therapy programs manage CAR-T referral, manufacturing coordination, and toxicity monitoring. United States NCI-designated centers and German university hospitals anchor regional referral networks.
- Hematology Departments:General hospital hematology units provide chemotherapy induction and consolidation with telemedicine backup from academic hubs. Capacity constraints in rural United States markets limit access to timely salvage therapy.
- Specialized Clinics:Dedicated pediatric hematology-oncology clinics in metropolitan Japan and Germany manage long-term follow-up and late effects surveillance.
- Research Institutes:Academic medical centers with early-phase trial infrastructure evaluate novel combinations and biomarker-driven patient selection. EMA conditional marketing authorization frameworks enable revenue generation during confirmatory studies.
Oncology centers lead on scale; research institutes lead on pipeline access.
Delivery Mode:
Route of administration shapes site-of-care requirements, nursing intensity, and patient compliance profiles.
- Intravenous:Continuous infusion protocols for chemotherapy and monoclonal antibodies require central line access and inpatient or ambulatory infusion center capacity. United States hospital outpatient departments capture the majority of reimbursement.
- Oral:Tyrosine kinase inhibitors and maintenance chemotherapy enable home administration with periodic monitoring. Japan's community pharmacy networks support adherence tracking for pediatric patients.
- Subcutaneous:Extended-half-life antibody formulations reduce infusion center burden and enable home nursing administration. Development programs in Germany target this route for bispecific engagers.
- Intrathecal:Direct CNS delivery via lumbar puncture or Ommaya reservoir requires specialized procedural capabilities and coordination with neuro-oncology. Sanctuary site prophylaxis remains protocol-mandated despite toxicity risks.
- Combination Therapy:Sequential or concurrent multimodal delivery integrates systemic and CNS-directed treatment. Protocol complexity demands multidisciplinary care coordination.
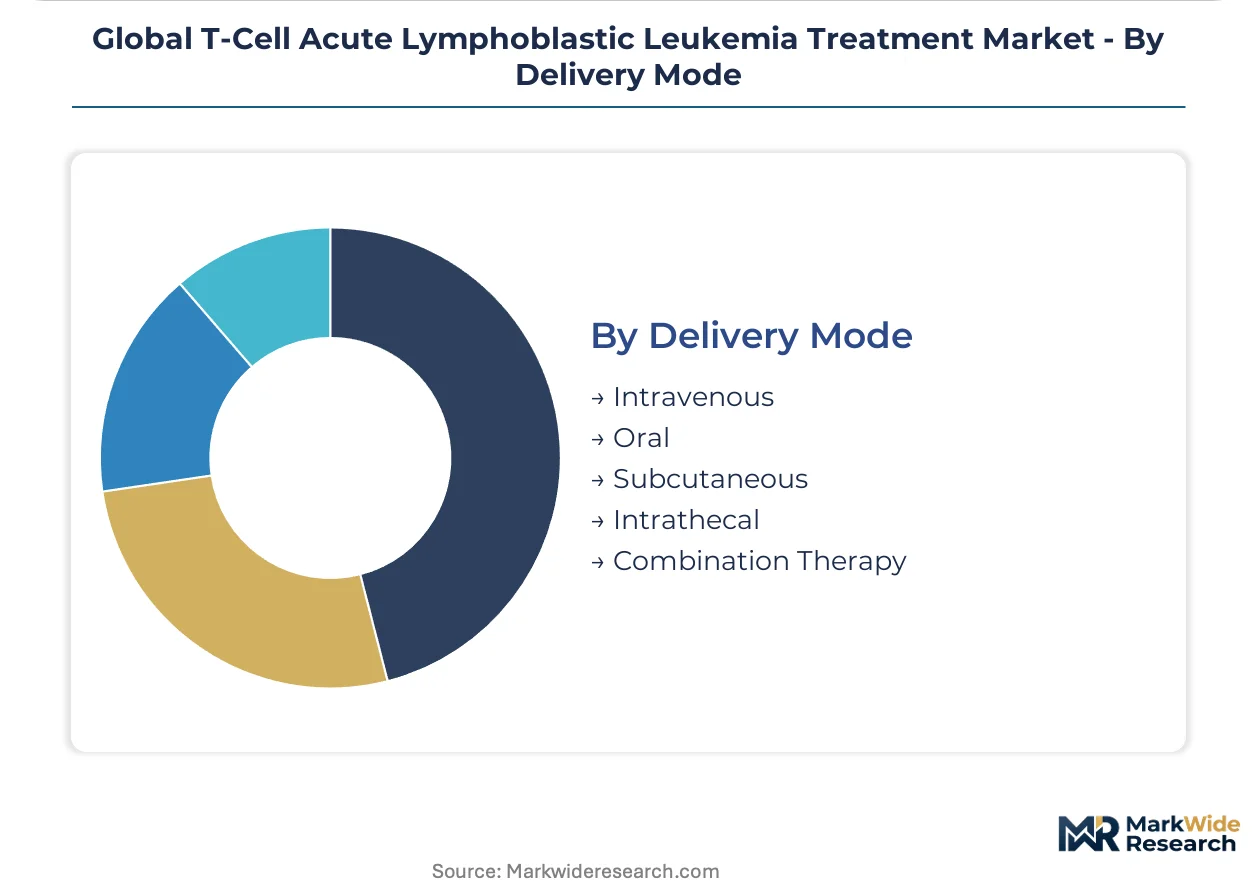
Intravenous delivery leads on scale; subcutaneous formulations are gaining share fastest through convenience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in cell therapy manufacturing are redistributing clinical trial investment toward jurisdictions with streamlined accelerated approval frameworks and established pediatric oncology infrastructure. Production migration follows cost-of-compliance advantages in vector manufacturing and apheresis network density.
United States
FDA's surrogate endpoint framework for hematologic malignancies compresses development timelines for CAR-T programs targeting minimal residual disease negativity. The NCI-designated comprehensive cancer center network anchors regional referral capacity for autologous cell therapy. Boston and Philadelphia metropolitan clusters concentrate Phase I/II trial infrastructure for next-generation T-cell engagers.
Germany
EMA conditional marketing authorization enables revenue generation during confirmatory trials for relapsed pediatric populations, attracting sponsor investment. The EU AI Act's algorithmic transparency requirements for pharmacovigilance elevate compliance infrastructure costs. Heidelberg and Munich university hospitals coordinate multi-site patient registries supporting post-market commitments.
Japan
PMDA's Sakigake designation system accelerates review timelines for pediatric leukemia therapies addressing high unmet need. The country's pediatric leukemia study group pioneered MRD-guided treatment allocation protocols. Tokyo and Osaka metropolitan centers manage long-term follow-up for CAR-T recipients through dedicated hematology-oncology clinics.
United Kingdom
NHS England's Cancer Drugs Fund provides provisional reimbursement for therapies awaiting NICE technology appraisal, reducing access friction. MHRA's recognition of FDA and EMA approvals streamlines parallel import pathways for cell therapy products. London and Manchester academic medical centers participate in EU-wide confirmatory study networks despite Brexit regulatory divergence.
Switzerland
Swissmedic's alignment with EMA centralized procedures reduces duplicate regulatory burden for hematologic malignancy therapies. The country's precision medicine initiative supports biomarker-driven patient selection for early-phase trials. Basel and Zurich hospital networks leverage proximity to pharmaceutical headquarters for investigator-sponsored study collaboration.
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market Competitive Landscape
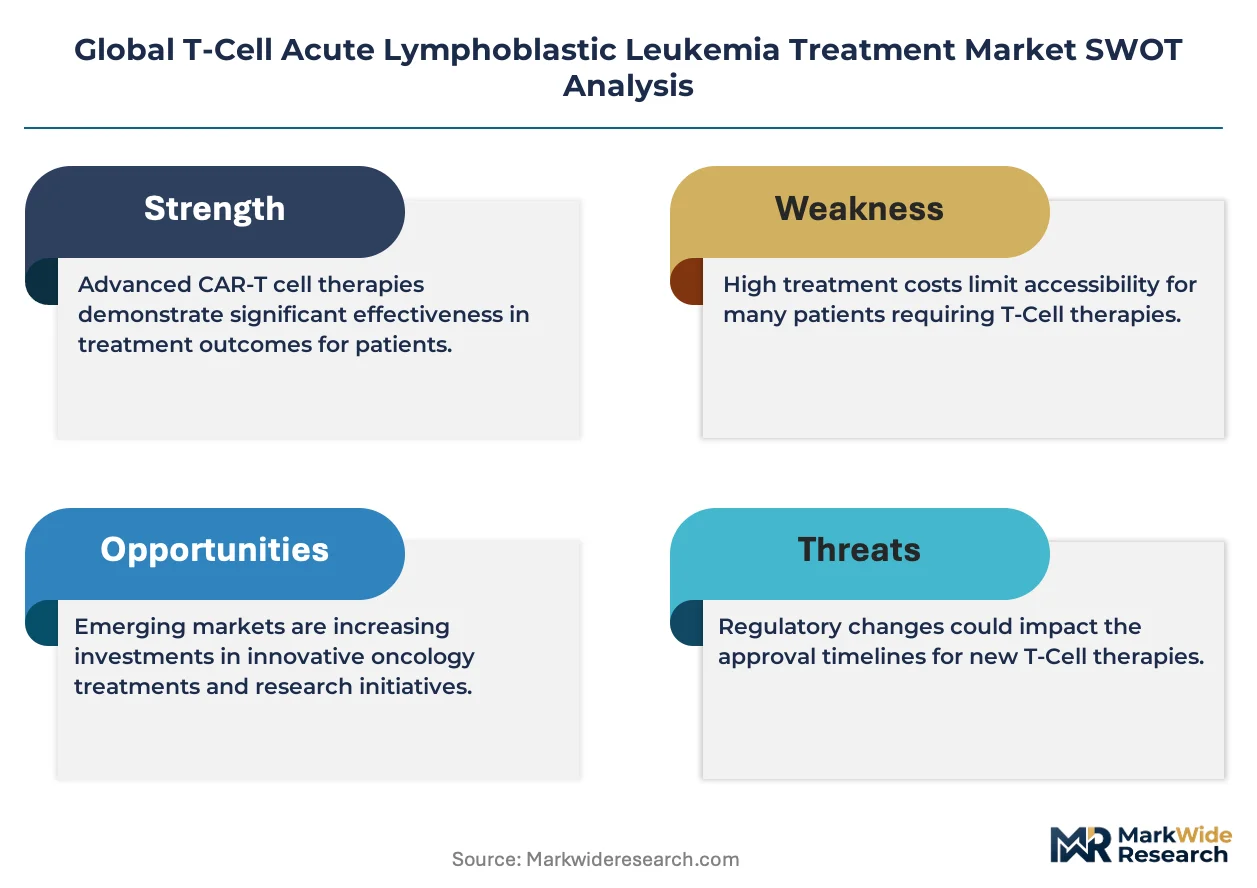
Established producers occupy the standard tier with approved CAR-T and bispecific antibody platforms; emerging entrants pursue allogeneic off-the-shelf modalities and next-generation T-cell engager engineering. Market structure concentrates around integrated biologics manufacturers with captive viral vector production and specialized oncology divisions. Three archetypes dominate: Big Pharma oncology divisions with cell therapy manufacturing footprints, mid-cap biotechs with proprietary antibody engineering platforms, and emerging allogeneic cell therapy developers. Competitive intensity manifests through manufacturing capacity expansion in three-continent configurations and strategic partnerships securing apheresis network access.
Among integrated biopharmaceutical manufacturers, Bristol-Myers Squibb, Novartis, and Genmab represent distinct strategic postures. Bristol-Myers Squibb exemplifies the multi-continental manufacturing archetype with cell therapy production infrastructure spanning North America, Europe, and Asia-Pacific. Novartis anchors the in-house viral vector production model, reducing third-party CDMO dependency for lentiviral supply security. Genmab occupies the proprietary platform technology position, leveraging DuoBody engineering for next-generation T-cell engager development. These three entities collectively illustrate how competitive differentiation in T-ALL treatment converges on manufacturing control, vector supply security, and antibody engineering capability rather than single-molecule dominance.
| Leading Market Players |
|---|
| Genmab |
| F. Hoffmann-La Roche |
| Bristol-Myers Squibb |
| GlaxoSmithKline |
| Gilead Sciences |
| Novartis |
| Kyowa Kirin |
| Spectrum Pharmaceuticals |
| Pfizer |
| Others |
Supply & Pricing Matrix
Captive in-house viral vector production anchors supply security and pricing power for integrated biologics manufacturers, compressing third-party CDMO margins while enabling premium positioning for lentiviral-dependent CAR-T therapies. This backward integration into critical inputs shields sponsors from spot-market volatility in apheresis scheduling and cold-chain logistics, embedding cost control into the therapeutic value proposition.
Pricing Analysis
Distributor margin compression runs through the CAR-T value chain as manufacturers consolidate direct-to-hospital contracting for autologous cell therapies. Three-tier pricing structure across academic medical center, community hospital, and pediatric network tiers reflects site-of-care capability differentials rather than volume scale alone. Pricing pressure stems from payer skepticism toward MRD-guided endpoints in United States commercial plans. Pediatric oncology centers exhibit lowest price sensitivity given dedicated funding streams, while rural hematology departments face highest budget constraint friction.
Supply Chain Analysis
Cryopreservation logistics costs escalate across the multi-node cold chain spanning apheresis collection, manufacturing, and infusion sites. Vector production concentrates in the United States, Switzerland, and Germany where regulatory alignment with FDA and EMA standards enables cross-border supply. Lentiviral plasmids, synthetic media, and qualified apheresis kits constitute critical input dependencies. Single-source vulnerability in specialized apheresis center capacity constrains patient access. Distribution runs through NCI-designated comprehensive cancer centers and German university hospital networks with embedded cellular therapy accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's surrogate endpoint framework for hematologic malignancies compounds demand acceleration by compressing development timelines and enabling earlier revenue recognition for T-ALL therapies. This regulatory architecture rewards sponsors with established manufacturing infrastructure and pediatric trial networks.
For Market Incumbents: Acquire allogeneic off-the-shelf platform assets to neutralize leukapheresis bottlenecks and defend against emerging universal donor CAR-T developers. Expand manufacturing capacity in Asia-Pacific to diversify geographic risk and capture PMDA Sakigake pathway advantages. Secure exclusive apheresis network partnerships in United States metropolitan clusters to lock out competitor patient access. For New Entrants and Emerging Players: The mid-tier price-point gap between branded bispecific antibodies and salvage chemotherapy regimens offers white-space positioning for subcutaneous extended-half-life T-cell engagers. Target Germany's EMA conditional marketing authorization pathway for relapsed pediatric populations where confirmatory trial revenue generation de-risks early investment. Pursue investigator-sponsored study collaboration with Tokyo and Osaka academic medical centers to establish clinical footprint ahead of formal reimbursement. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing workforce scarcity and vector production specialization create capability moats around integrated biologics manufacturers. Five-to-ten year viability favors sponsors with captive lentiviral supply and multi-continental production footprints over asset-light platform licensors. Monitor FDA Project Optimus dose-optimization mandate implementation as inflection signal for Phase II trial cost restructuring and combination therapy portfolio rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Allogeneic Platform Development | Eliminates leukapheresis dependency and opens community hospital access for CAR-T therapies. |
| EMA Conditional Marketing Authorization | Enables revenue generation during confirmatory trials for relapsed pediatric T-ALL therapies. |
| In-House Viral Vector Production | Reduces third-party CDMO dependency and secures lentiviral supply continuity for cell therapy programs. |
| Subcutaneous Formulation Engineering | Reduces infusion center burden and enables home nursing administration for bispecific antibodies. |
| Pediatric Oncology Network Expansion | Broadens first-line CAR-T eligibility criteria and referral volumes in United States and German centers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down market sizing triangulated volume and value estimates across treatment modalities.
Segment-weighting approaches distributed forecast contributions across chemotherapy, monoclonal antibodies, immunotherapy, and tyrosine kinase inhibitors by therapy line, administration route, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating pediatric incidence trends, accelerated approval pathway utilization rates, and manufacturing capacity expansion timelines. Forecast inputs included MRD testing adoption curves and payer coverage policy evolution for cellular therapies.
Caveats apply where FDA Project Optimus implementation timing, EMA AI Act pharmacovigilance compliance costs, or allogeneic platform clinical readouts could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Cell Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market