
 GMP Cell Banking Services Market | 2026-2036
GMP Cell Banking Services Market Size, Share, and Industry Trends Forecast 2026-2036
GMP Cell Banking Services Market Outlook
Plasmid DNA is shifting toward synthetic manufacturing platforms that reduce lot-to-lot variability in GMP cell banking workflows. Merck KGaA leverages its integrated life science tools portfolio to anchor upstream raw material supply for cell line development. Lonza Group sustains manufacturing scale across Swiss and US facilities, competing on capacity for commercial-stage gene therapy clients. Thermo Fisher controls distribution reach through its channel density in North American bioclusters.
GMP cell banking services encompass the generation, characterization, storage, and distribution of master cell banks and working cell banks under current Good Manufacturing Practice conditions, requiring documented provenance, sterility testing, and genetic stability validation across passage limits. The primary commercial purpose centers on de-risking downstream biopharmaceutical manufacturing by ensuring consistent, regulatory-compliant starting material for viral vector production and cell therapy applications. Stem cell banking and derivative cell lines command the deepest margin pools as gene therapy pipelines mature, while vaccine production applications retain volume leadership through established mRNA and viral platform demand. Contract Research Organizations represent the fastest-growing end user channel as sponsors outsource GMP compliance burden to specialized service providers.
FDA guidance on Chemistry, Manufacturing, and Controls for gene therapy investigational new drug applications elevates documentation requirements for master cell bank origin and characterization. EMA's ATMP framework and ISO 20399 standards on ancillary materials further tighten material qualification protocols for European market access. China's NMPA aligns with ICH Q5D through updated technical guidelines for biological product cell substrates. Stakeholders must monitor regulatory divergence on replication-competent virus testing as gene editing modalities expand beyond lentiviral platforms.
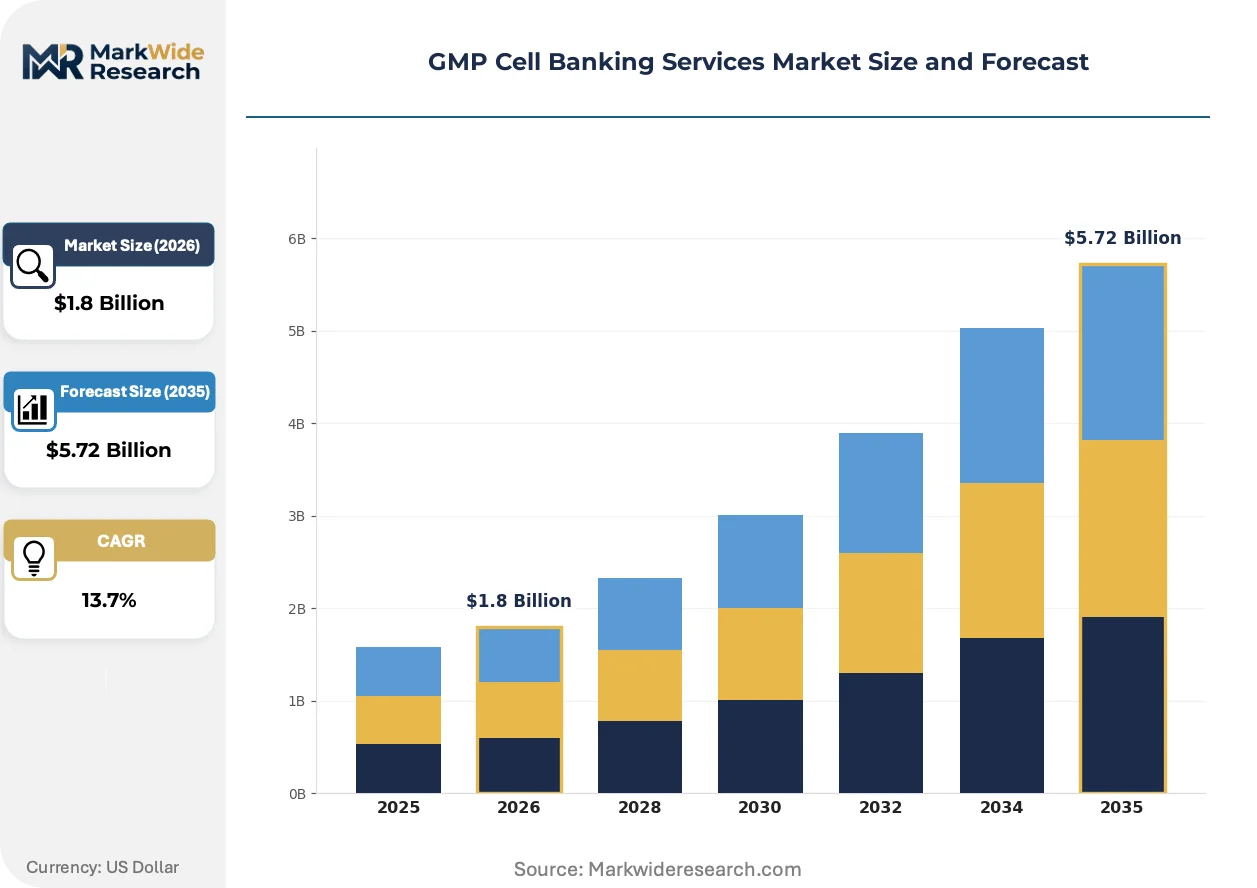
Market Dynamics
Gene therapy pipelines are compressing development timelines, forcing sponsors to outsource GMP master cell bank creation to specialized contract providers rather than building captive capabilities. This structural shift toward externalized compliance infrastructure is redistributing margin capture across the value chain.
Growth Catalysts
- FDA CMC Guidance:Elevated documentation requirements for master cell bank origin and characterization drive sponsors toward qualified third-party providers with established quality systems.
- Synthetic Plasmid Platforms:Enzymatic manufacturing methods reduce lot-to-lot variability in cell line engineering workflows, accelerating GMP bank generation cycles.
- China NMPA Alignment:Updated technical guidelines for biological product cell substrates harmonize with ICH Q5D, expanding addressable market for international service providers.
Market Restraints
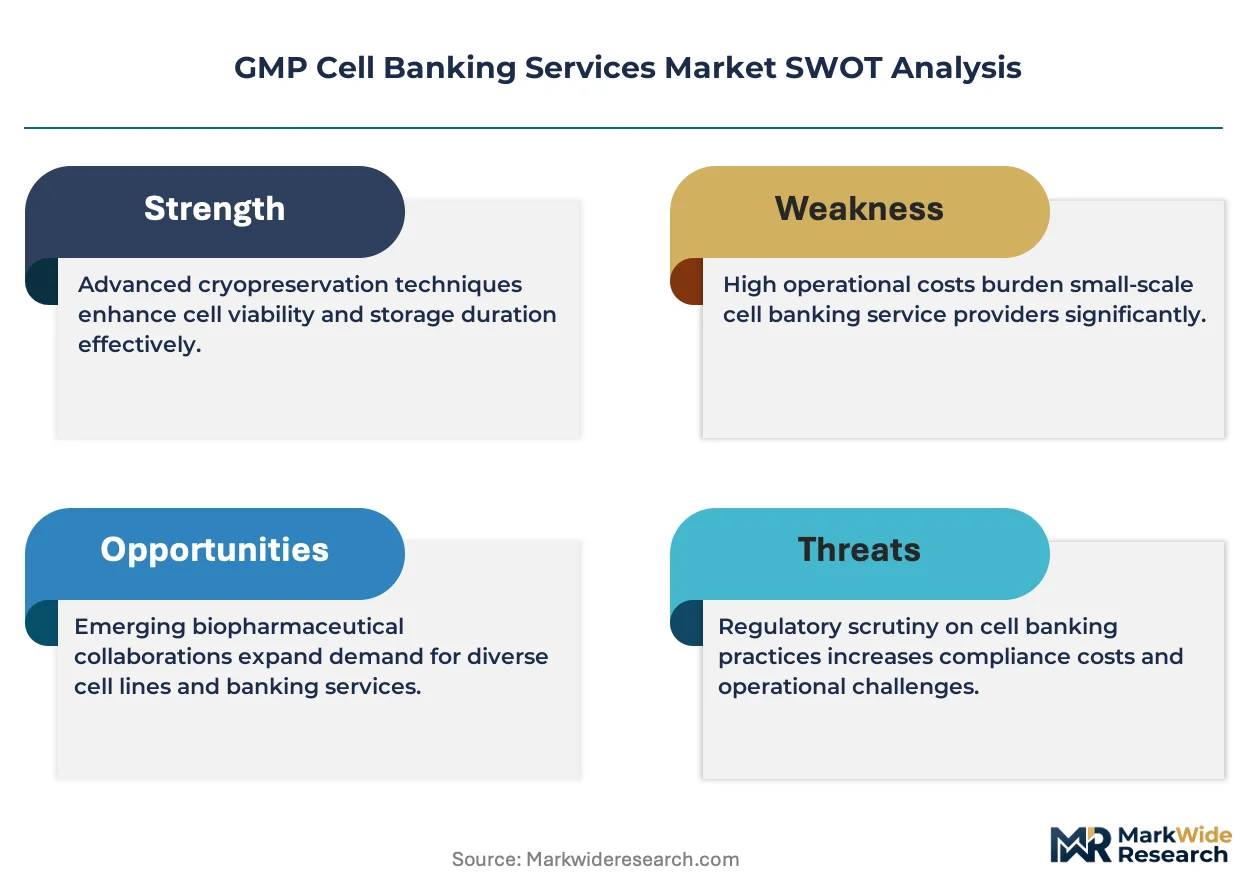
- Fetal Bovine Serum Volatility:Supply disruptions and ethical sourcing constraints in South American collection networks inflate raw material costs for traditional cell culture workflows.
- Swiss Facility Concentration:Premium manufacturing capacity clusters in Basel-Zurich corridor, creating geographic single-point-of-failure exposure for commercial-stage clients.
- Replication-Competent Virus Testing:Divergent regulatory requirements across FDA and EMA for gene editing modalities beyond lentiviral platforms fragment validation protocols.
Strategic Opportunities
- India CDSCO Pathway:Emerging biopharma clusters in Hyderabad and Bangalore generate demand for GMP-compliant cell banking as local ATMP development accelerates.
- Allogeneic Cell Therapy:Off-the-shelf therapeutic platforms require industrial-scale master cell bank architectures, expanding addressable service scope beyond autologous workflows.
- ISO 20399 Adoption:Standardization of ancillary material qualification protocols creates certification-driven preference advantages for early-adopting service providers.
Industry Challenges
- Cell Line Engineering Talent:Shortage of qualified molecular biologists with GMP documentation experience constrains capacity expansion at mid-tier contract research organizations.
- Contamination Control Capex:Dedicated suite requirements for viral vector production cell banks demand facility investments exceeding standard mammalian cell culture infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GMP Cell Banking Services Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Derivative Cell Lines, Peripheral Blood, Stem Cells, Tissues Application: Drug Development, Gene Therapy, Regenerative Medicine, Vaccine Production End User: Biopharmaceutical Companies, Academic Institutions, Research Organizations, Contract Research Organizations Delivery Mode: On-site, Cloud-based, Hybrid, Remote |
| Companies Covered | Merck KGaA, SGS Ltd, WuXi AppTec, Sartorius, Thermo Fisher, Charles River Laboratories, Eurofins Scientific, REPROCELL, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GMP Cell Banking Services Market Strategic Shifts
Synthetic biology toolsets are compressing cell line development timelines while regulatory agencies tighten provenance documentation, creating simultaneous pressure for speed and compliance rigor.
Continuous manufacturing platforms for plasmid DNA production are consolidating upstream raw material supply chains. Gene therapy developers at clinical-to-commercial transition adopt these integrated workflows to reduce master cell bank characterization burden. The technology is consolidating vendor relationships around providers with captive enzyme and reagent supply.
EMA's ATMP framework revisions impose stricter genetic stability validation across passage limits for commercial authorization. European sponsors must now demonstrate extended stability data before working cell bank release. Small and mid-cap gene therapy developers are responding by front-loading characterization investments and selecting providers with existing EMA qualification track records.
Service unbundling is fragmenting traditional full-scope contracts. Large pharmaceutical sponsors now separately procure cell line engineering, GMP banking, and distribution logistics to optimize cost structures. This behavior is most visible among US-based gene therapy developers with multiple parallel pipeline assets requiring staggered bank generation.
GMP Cell Banking Services Market Segmentation
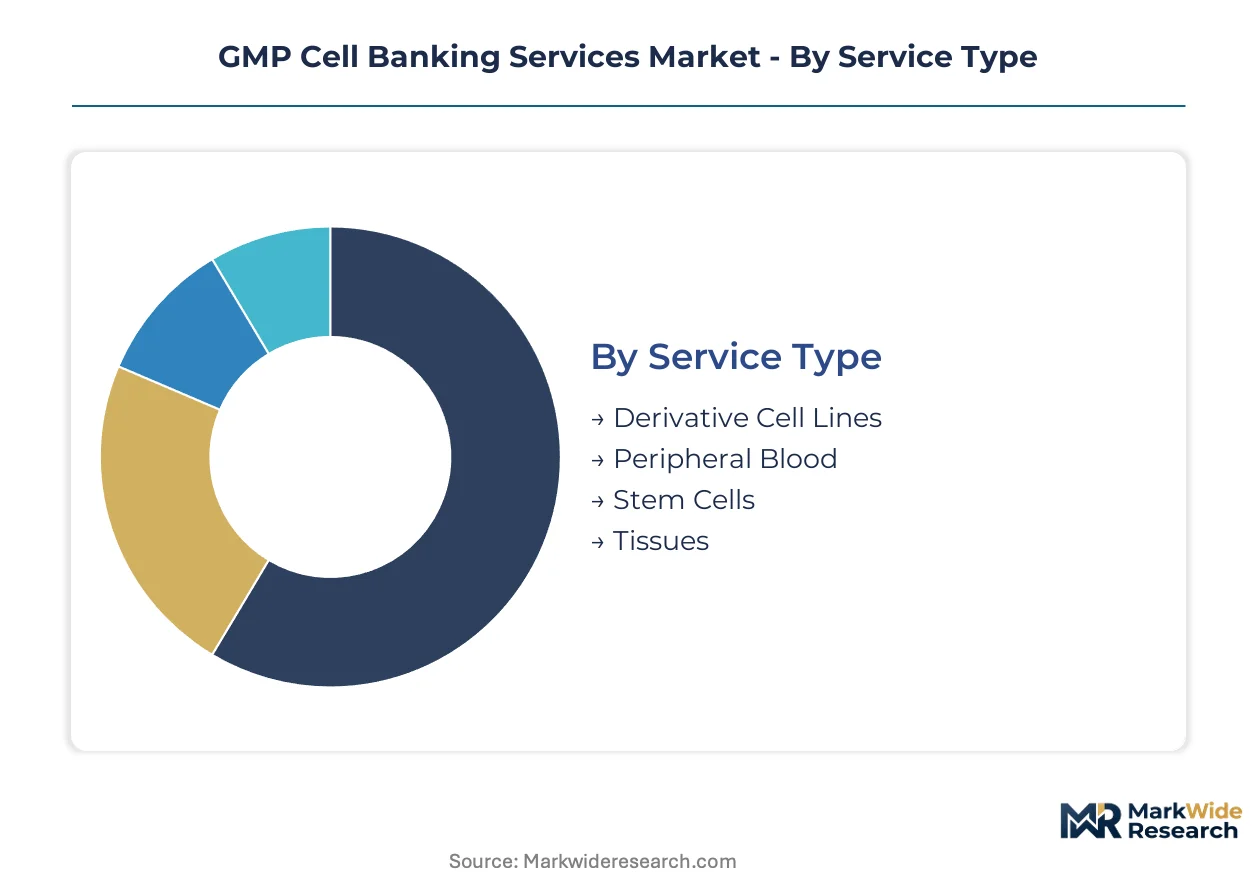
GMP cell banking services fragment across service architecture, therapeutic application, and procurement channel. Sponsor selection criteria vary sharply by development stage and regulatory exposure, reshaping competitive positioning across each dimension.
Service Type:
Cost tier determines outsourcing depth, with premium segments commanding full regulatory documentation and economy segments limited to research-grade characterization.
- Stem Cells:Pluripotent and multipotent lineages require extended passage validation and karyotype stability testing under FDA and EMA frameworks. Gene therapy developers in the United States and Germany concentrate demand here as allogeneic platforms scale toward commercial manufacturing.
- Derivative Cell Lines:Engineered subclones and reporter lines carry the deepest margin pools due to intellectual property encapsulation and customization complexity. Chinese biotech clusters drive volume expansion as local NMPA-aligned facilities mature.
- Peripheral Blood:Primary lymphocyte and mononuclear cell collections serve autologous therapy workflows with shorter banking cycles.
- Tissues:Organ-specific explants and primary cultures retain niche demand in regenerative medicine applications.
Stem cells lead on scale; derivative cell lines lead on momentum.
Application:
Maturity curves separate established volume markets from emerging high-value segments with divergent compliance burdens.
- Gene Therapy:Viral vector production substrates and CAR-T cell sources dominate sponsor investment as clinical pipelines thicken. FDA CMC documentation requirements for master cell bank origin push developers toward qualified third-party providers with established quality systems.
- Vaccine Production:mRNA platform cell substrates and viral vector packaging lines sustain volume leadership through pandemic-era infrastructure expansion. Established manufacturers in Germany and Switzerland retain procurement concentration.
- Drug Development:Small-molecule and biologic toxicology testing banks follow standardized characterization protocols with compressed timelines.
- Regenerative Medicine:iPSC-derived therapeutic candidates require extended genetic stability validation under EMA ATMP frameworks.
Vaccine production anchors volume; gene therapy climbs the fastest.
End User:
Customer type dictates contract structure, with large pharma favoring unbundled procurement and emerging developers seeking integrated compliance solutions.
- Biopharmaceutical Companies:Mid-cap and large sponsors with parallel pipeline assets drive demand for staggered master cell bank generation with dedicated suite allocation. US-based gene therapy developers increasingly separate cell line engineering, GMP banking, and distribution logistics to optimize cost structures.
- Contract Research Organizations:Specialized service providers capture expanding outsourcing flow as sponsors externalize compliance infrastructure rather than building captive capabilities. CROs climbing fastest as sponsors redistribute margin capture across the value chain.
- Academic Institutions:Research-grade banking with limited regulatory documentation serves early discovery workflows.
- Research Organizations:Non-profit and government laboratories concentrate demand in tissue and primary cell repositories.
Biopharmaceutical companies dominate spend; contract research organizations gain share fastest.
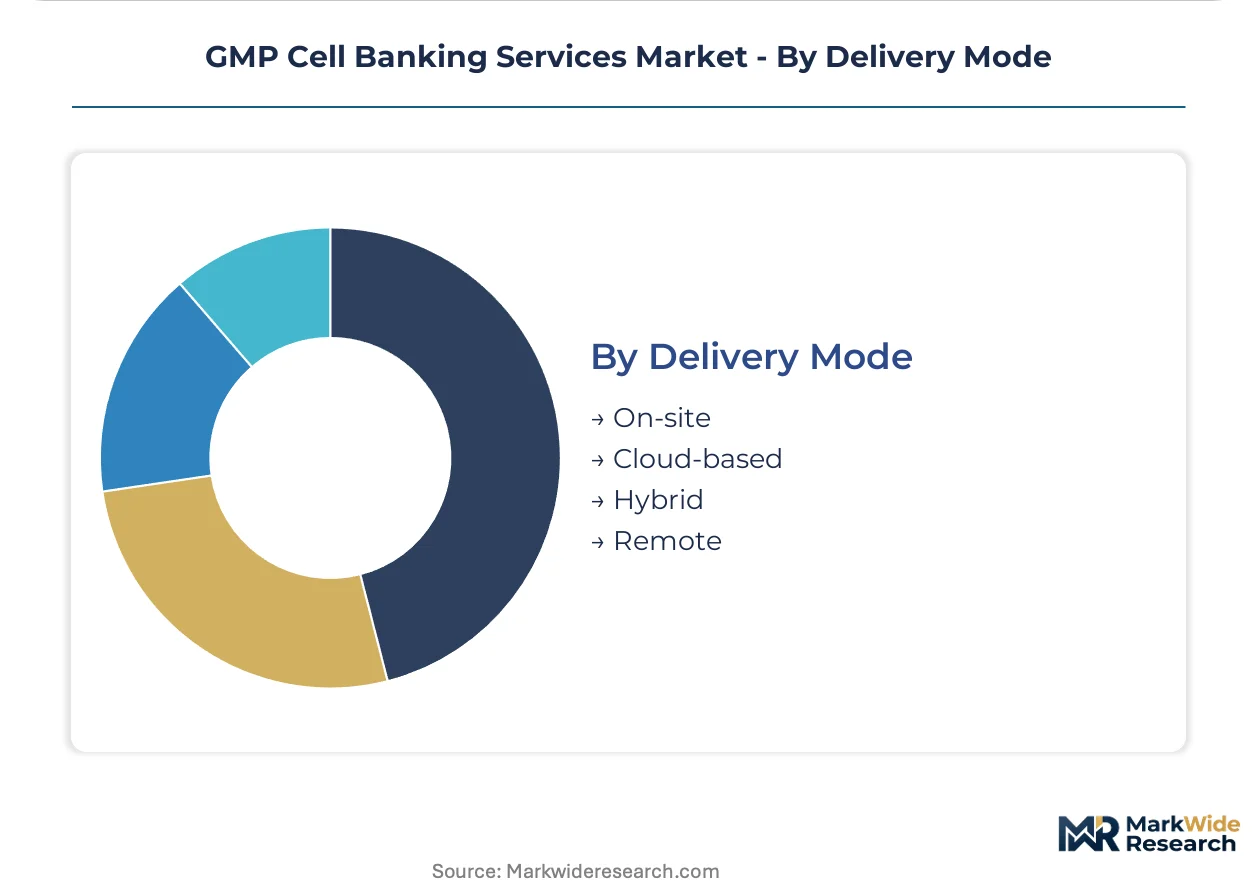
Delivery Mode:
Supply concentration in Swiss and US bioclusters shapes physical versus virtual service configurations.
- On-site:Client presence during master cell bank generation and release testing satisfies FDA and EMA audit requirements for commercial-stage sponsors. Basel-Zurich corridor and Boston-Cambridge cluster concentrate premium capacity.
- Hybrid:Blended models combining on-site generation with remote characterization reporting optimize cost for clinical-stage developers with limited quality assurance bandwidth.
- Cloud-based:Electronic batch records and real-time environmental monitoring data serve distributed sponsor teams.
- Remote:Fully externalized project management with courier-based sample logistics suits early-stage developers with geographic constraints.
On-site commands premium pricing; hybrid models expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biocluster anchors commercial demand for GMP cell banking services as FDA CMC documentation requirements push gene therapy developers toward qualified third-party providers. Sponsors in this corridor increasingly separate cell line engineering, GMP banking, and distribution logistics to optimize cost structures across parallel pipeline assets.
United States
FDA Chemistry, Manufacturing, and Controls guidance for gene therapy investigational new drug applications elevates documentation requirements for master cell bank origin and characterization. Sponsors outsource compliance infrastructure to specialized contract providers rather than building captive capabilities. The Boston-Cambridge and San Francisco Bay Area bioclusters concentrate premium on-site service demand.
Germany
EMA's ATMP framework and ISO 20399 standards on ancillary materials tighten material qualification protocols for European market access. German biopharmaceutical sponsors must demonstrate extended genetic stability data before working cell bank release. The Basel-Zurich corridor and Munich biocluster host concentrated manufacturing capacity for commercial-stage clients.
China
NMPA alignment with ICH Q5D through updated technical guidelines for biological product cell substrates harmonizes regulatory standards for biological product cell substrates. Local biotech clusters in Shanghai and Suzhou drive volume expansion as NMPA-aligned facilities mature. International service providers expand addressable market through regulatory harmonization.
Switzerland
Swissmedic oversight of advanced therapy medicinal products maintains stringent genetic stability validation requirements across passage limits. The Basel-Zurich corridor concentrates premium manufacturing capacity, creating geographic single-point-of-failure exposure for commercial-stage clients. Service providers compete on EMA qualification track records for European market authorization.
India
CDSCO pathway maturation for advanced therapy medicinal products generates demand for GMP-compliant cell banking as local development accelerates. Hyderabad and Bangalore biopharma clusters emerge as outsourcing destinations for characterization and documentation services. International providers establish partnerships to access cost-advantaged capacity for non-core workflow segments.
GMP Cell Banking Services Market Competitive Environment
Global majors compete with regional champions across documentation depth and regulatory qualification breadth, with market structure consolidating around providers with captive enzyme supply and established quality systems. Three archetypes dominate: integrated life science conglomerates with upstream raw material control, specialized contract research organizations with GMP compliance expertise, and Asia-Pacific scale operators with cost-optimized capacity. Competitive moves center on strategic partnerships for regulatory track record access and capacity expansion in Basel-Zurich and Boston-Cambridge corridors.
Within the integrated conglomerate tier, Merck KGaA and Thermo Fisher exemplify providers leveraging captive supply chains to anchor upstream raw material provision for cell line development. Lonza Group occupies a position representing specialized manufacturing scale across Swiss and US facilities, competing on dedicated suite allocation for commercial-stage gene therapy clients. WuXi AppTec anchors the Asia-Pacific scale archetype, with Chinese regulatory alignment expanding addressable service scope for international sponsors seeking cost-optimized characterization cycles.
| Leading Market Players |
|---|
| Merck KGaA |
| SGS Ltd |
| WuXi AppTec |
| Sartorius |
| Thermo Fisher |
| Charles River Laboratories |
| Eurofins Scientific |
| REPROCELL |
| Lonza Group |
| Others |
Value Chain & Pricing Dynamics
EMA's ATMP framework and ISO 20399 standards on ancillary materials gate qualified supply access and premium-tier pricing for GMP cell banking services, as sponsors lacking documented provenance face exclusion from commercial-stage gene therapy contracts. Compliance investment separates certified providers commanding dedicated suite premiums from uncertified competitors limited to research-grade margins.
Pricing Analysis
Input-cost pass-through from fetal bovine serum volatility and synthetic plasmid platform licensing feeds directly into project-based pricing structures for master cell bank generation. Three-tier pricing structure across premium, standard, and economy levels differentiates by EMA qualification track record, FDA CMC documentation depth, and dedicated suite allocation. Pricing pressure stems from sponsor unbundling of cell line engineering, GMP banking, and distribution logistics to optimize parallel pipeline costs. Contract research organizations exhibit highest price sensitivity as margin capture redistributes across the value chain, while commercial-stage gene therapy developers prioritize qualification over cost.
Supply Chain Analysis
ISO 20399 certification and EMA ATMP framework compliance gate supplier qualification for ancillary materials used in cell line engineering workflows. Manufacturing capacity concentrates in Switzerland, the United States, and China, with the Basel-Zurich corridor and Boston-Cambridge bioclusters anchoring premium on-site service availability. Raw material dependencies center on fetal bovine serum from South American collection networks, synthetic plasmid DNA from enzymatic manufacturing platforms, and GMP-grade reagents from qualified vendors. Single-source vulnerability in Swiss facility concentration creates geographic risk exposure for commercial-stage clients. Distribution runs through courier-based sample logistics with real-time environmental monitoring for working cell bank release.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GMP cell banking services constitute a late-cycle quality story as gene therapy pipelines mature toward commercial manufacturing, with sponsor demand shifting decisively toward providers with established EMA qualification track records and FDA CMC documentation systems.
For Market Incumbents: Cement regulatory qualification advantages by expanding dedicated suite capacity in the Basel-Zurich corridor and Boston-Cambridge bioclusters before emerging Asia-Pacific scale operators achieve EMA alignment. Deepen backward integration into synthetic plasmid manufacturing to anchor upstream raw material supply against input-cost volatility from South American serum collection networks. For New Entrants and Emerging Players: Cloud-based electronic batch records and remote project management platforms offer lower-capital routes to serve early-stage gene therapy developers with geographic constraints and limited quality assurance bandwidth. Target India's CDSCO pathway maturation in Hyderabad and Bangalore bioclusters, where local ATMP development accelerates demand for cost-optimized characterization cycles without immediate EMA qualification requirements. For Investors and Strategic Acquirers: Roll-up economics work for specialized contract research organizations with GMP compliance expertise because sponsor outsourcing of master cell bank creation redistributes margin capture across fragmented mid-tier providers lacking captive enzyme supply. Mid-cap CROs with existing FDA CMC documentation systems and Swiss or US facility presence represent prime acquisition targets. Watch for NMPA-EMA regulatory harmonization completion as inflection indicator for Asia-Pacific scale operator viability.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualification Track Record Expansion | Swissmedic oversight requirements for ATMP commercial authorization demand documented genetic stability validation across passage limits. |
| Synthetic Plasmid Platform Integration | Enzymatic manufacturing methods reduce lot-to-lot variability in cell line engineering workflows for gene therapy developers. |
| India CDSCO Partnership Development | Hyderabad and Bangalore biopharma clusters generate GMP-compliant cell banking demand as local ATMP pipelines mature. |
| Allogeneic Cell Therapy Capacity Buildout | Off-the-shelf therapeutic platforms require industrial-scale master cell bank architectures beyond autologous workflow scope. |
| Service Unbundling Response | Large pharmaceutical sponsors now separately procure cell line engineering, GMP banking, and distribution logistics for cost optimization. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gene therapy development executives, regulatory affairs leads at contract research organizations, GMP facility quality directors, and sponsor procurement managers with secondary validation from FDA CMC guidance documents, EMA ATMP framework revisions, NMPA technical guidelines, and ISO 20399 standards. Bottom-up service provider capacity modeling and top-down gene therapy pipeline demand assessment were triangulated against disclosed facility investments and regulatory submission patterns.
Comparable-period anchoring to historical master cell bank generation cycles and commercial-stage gene therapy authorization timelines structured the projection horizon. Segmentation dimensions modeled encompass service type, therapeutic application, end-user archetype, and delivery mode, with CAGRs derived from sponsor outsourcing penetration rates and facility capacity expansion announcements. Synthetic plasmid platform adoption curves and replication-competent virus testing protocol standardization served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for continuous manufacturing platforms in plasmid DNA production; alternative pathways for enzymatic versus fermentation-based manufacturing would alter the outlook for upstream raw material supply concentration. Forecasts reflect assumptions regarding regulatory harmonization pace, sponsor outsourcing preferences, and facility qualification timelines. A model refresh is warranted upon material change in FDA CMC guidance enforcement patterns or EMA ATMP framework passage limit requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Cancer Therapeutics Market