
 North America Cancer Vaccines Market | 2026-2036
North America Cancer Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cancer Vaccines Market Analytics
Project finance partnerships between biotech innovators and institutional investors is rewriting competitive access in cancer vaccine development. Merck & Co., Inc. leverages its established Keytruda franchise to anchor combination immunotherapy strategies. Moderna, Inc. competes through mRNA platform flexibility that extends from infectious disease into personalized neoantigen vaccines. BioNTech SE differentiates via deep manufacturing scale in cell therapy and peptide synthesis.
Cancer vaccines comprise biological preparations designed to stimulate cell-mediated immunity against tumor-associated antigens, typically formulated as recombinant proteins, viral vectors, or nucleic acid constructs requiring cold-chain distribution at minus 20 to minus 70 degrees Celsius. Their primary purpose centers on either preventing virus-induced malignancies or treating established cancers by amplifying antigen-specific T-cell responses. Therapeutic vaccines command the dominant value share as checkpoint inhibitor combinations expand addressable populations across solid tumors. Viral vector technology leads clinical pipelines, while DNA vaccines represent the fastest-expanding modality as electroporation delivery improves immunogenicity. Recombinant technology occupies the most mature position, with margin pools concentrating in contract manufacturing organizations serving peptide-based programs.
The FDA and Health Canada govern cancer vaccine approval through accelerated and conditional pathways that shape trial design requirements and commercial timelines. The FDA's Breakthrough Therapy designation compresses Phase 2-to-approval intervals, while Health Canada's Priority Review stream creates parallel access for Canadian patients. Stakeholders must monitor how evolving FDA guidance on surrogate endpoints for cell and gene therapies will apply to personalized cancer vaccine submissions.
Market Dynamics
The FDA's Breakthrough Therapy designation is compressing Phase 2-to-approval timelines for personalized cancer vaccines, creating a structural acceleration that rewards platform scalability over traditional biologic development cycles.
Growth Catalysts
- Checkpoint inhibitor combinations:The expansion of PD-1/PD-L1 combination protocols across solid tumor indications is pulling therapeutic vaccines into earlier lines of therapy at major academic medical centers.
- Health Canada's Priority Review:Parallel regulatory pathways for Canadian patients are synchronizing cross-border clinical trial recruitment and compressing regional launch gaps.
- mRNA manufacturing modularity:Platform flexibility enables rapid pivoting from infectious disease capacity to personalized neoantigen production without dedicated facility reconfiguration.
Market Restraints
- Cold-chain infrastructure gaps:Minus 70 degrees Celsius distribution requirements strain rural oncology clinic access in the Mountain West and Prairie provinces.
- Peptide synthesis supply concentration:Contract manufacturing organizations in the Northeastern United States capture disproportionate margin pools, limiting price negotiation leverage for emerging developers.
- Electroporation device reimbursement:DNA vaccine delivery hardware faces inconsistent CMS coding coverage, creating adoption friction despite improved immunogenicity profiles.
Strategic Opportunities
- Community oncology networks:Underpenetrated infusion centers in the Southeastern United States represent addressable sites for decentralized therapeutic vaccine administration.
- IRA price negotiation carve-outs:Orphan-designated cancer vaccines retain protected pricing windows that biotech innovators can exploit through indication-specific development strategies.
- Viral vector-peptide convergence:Hybrid platforms combining adenoviral priming with synthetic booster doses are opening new intellectual property white space beyond single-modality approaches.
Industry Challenges
- Cell therapy manufacturing talent scarcity:GMP-grade vector production and QC analytics functions face acute hiring competition from gene therapy developers in Boston and San Diego clusters.
- Neoantigen prediction algorithm validation:Computational immunology pipelines require prospective clinical correlation studies that extend development timelines and burn capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cancer Vaccines Market |
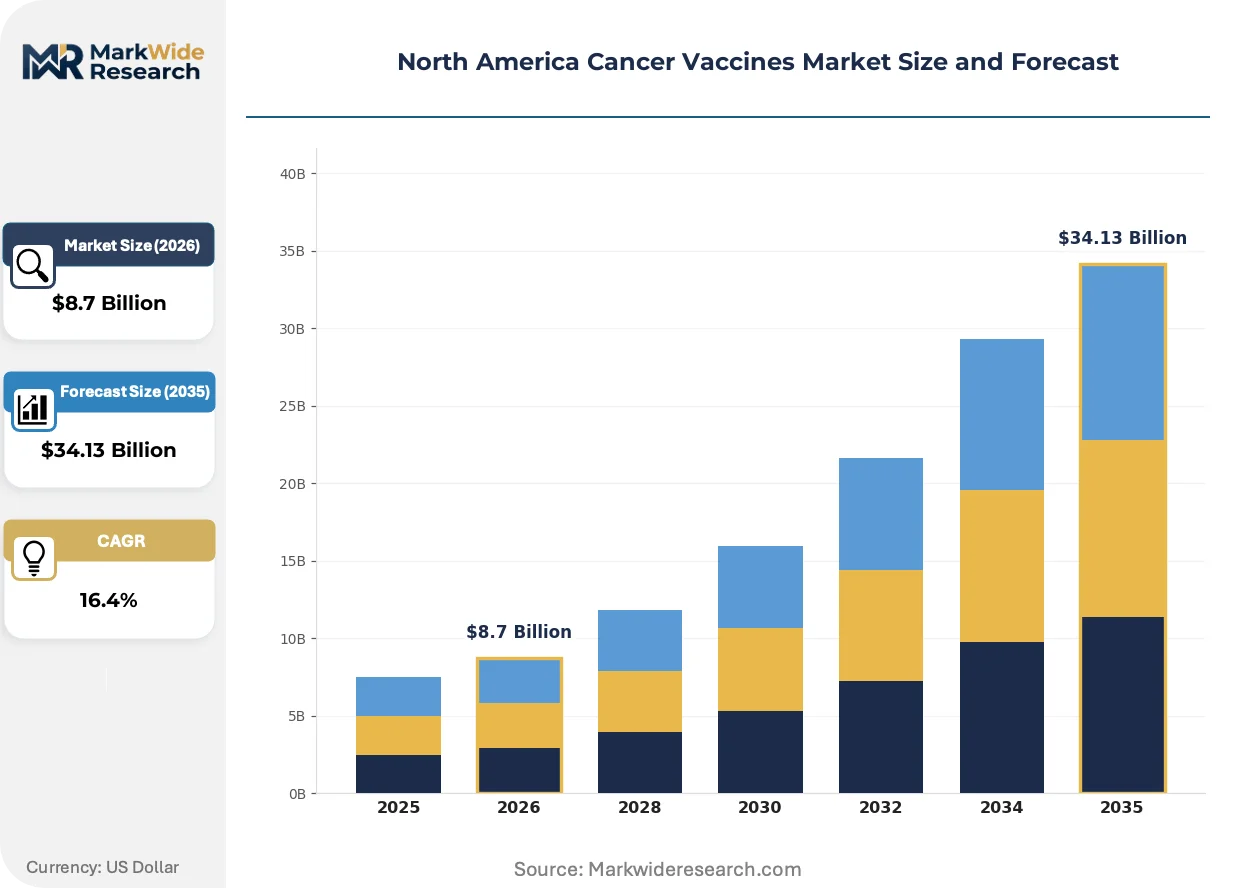
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preventive Vaccines, Therapeutic Vaccines, DNA Vaccines, Protein-Based Vaccines Delivery Method: Intramuscular, Intradermal, Subcutaneous, Oral End User: Hospitals, Research Institutes, Specialty Clinics, Pharmaceutical Companies Technology: Recombinant Technology, Viral Vector Technology, Peptide-Based Technology, Cell-Based Technology |
| Companies Covered | Merck & Co., Inc., GSK plc, AstraZeneca plc, Moderna, Inc., Dendreon Pharmaceuticals LLC, BioNTech SE, Bavarian Nordic, Agenus Inc., Inovio Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cancer Vaccines Market Evolving Landscape
Personalized medicine architectures are redefining competitive moats in cancer vaccine development, shifting value capture from molecule exclusivity toward integrated data-and-manufacturing platforms.
Next-generation sequencing-based tumor mutational burden profiling is rendering obsolete the traditional one-size-fits-all peptide vaccine formulations that dominated prior-decade clinical pipelines. Oncology specialty clinics in the Northeastern United States are adopting patient-specific neoantigen selection workflows at accelerating velocity, compressing the addressable market for off-the-shelf cancer vaccine candidates.
The FDA's evolving guidance on surrogate endpoints for cell and gene therapies is reshaping trial design requirements for personalized cancer vaccine submissions, forcing sponsors to invest in novel biomarker validation strategies. Health Canada is observing these developments to align its own conditional approval frameworks, creating regulatory synchronization pressure across North American development programs.
Academic medical centers are consolidating procurement authority for combination immunotherapy protocols, displacing traditional pharmaceutical account-manager relationships with centralized pharmacy-and-therapeutics committee governance. This concentration is most visible in the Northeastern United States, where major cancer centers are negotiating platform-level agreements that bundle checkpoint inhibitors with investigational vaccine access.
North America Cancer Vaccines Market Segmentation
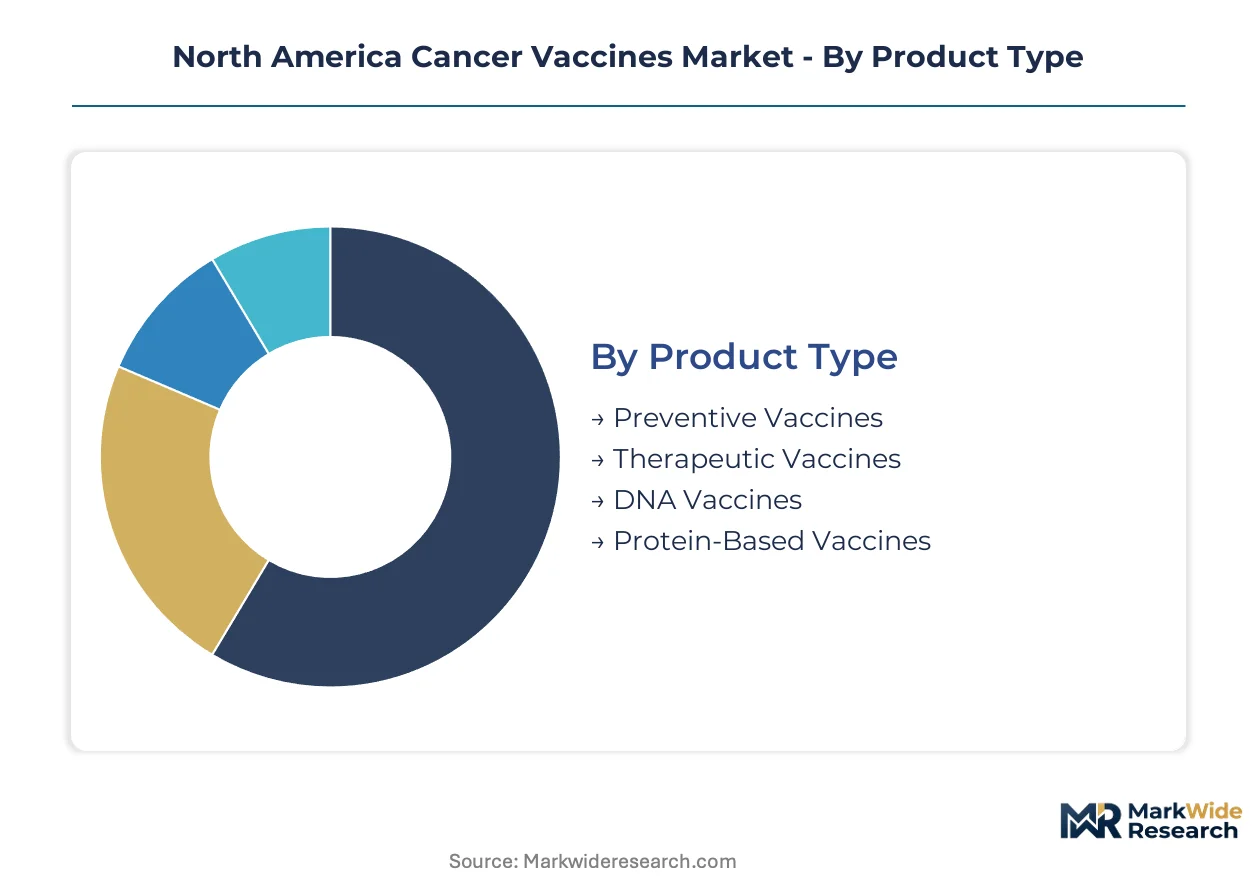
Cancer vaccine segmentation reveals how therapeutic intent, delivery mechanics, and manufacturing platforms intersect to determine commercial viability. Each dimension carries distinct cold-chain, reimbursement, and clinical workflow implications that shape go-to-market strategy across the United States and Canada.
Product Type:
Use-case spectrum spans prophylactic intervention against virus-induced malignancies through personalized neoantigen therapy for established disease.
- Preventive Vaccines:Biological preparations targeting oncogenic viruses such as HPV and HBV to block initial malignant transformation. Demand concentrates in pediatric and adolescent vaccination programs across U.S. health systems, constrained by primary care access gaps in rural Prairie provinces.
- Therapeutic Vaccines:Immunostimulatory constructs designed to amplify antigen-specific T-cell responses against existing tumors. Oncology specialty clinics in the Northeastern United States anchor adoption as checkpoint inhibitor combinations expand into earlier therapy lines.
- DNA Vaccines:Nucleic acid constructs encoding tumor-associated antigens, delivered via electroporation to enhance immunogenicity. Electroporation device reimbursement inconsistencies at CMS create adoption friction despite technical advances.
- Protein-Based Vaccines:Recombinant protein formulations representing the most mature manufacturing modality. Contract manufacturing organizations in the Northeastern United States capture disproportionate margin pools in peptide synthesis.
Established volume favors preventive platforms; emerging adoption favors therapeutic candidates.
Delivery Method:
Route selection determines cold-chain intensity, clinical site requirements, and patient compliance profiles across the product lifecycle.
- Intramuscular:Deep tissue injection enabling sustained antigen depot formation and prolonged immune stimulation. Major academic medical centers standardize intramuscular protocols for therapeutic vaccine administration.
- Intradermal:Superficial dermal layer targeting rich dendritic cell populations for enhanced antigen presentation. Specialized training requirements limit deployment to tertiary care centers in Boston and Toronto clusters.
- Subcutaneous:Adipose tissue delivery offering simplified administration with reduced personnel skill barriers. Community oncology networks in the Southeastern United States favor subcutaneous routes for decentralized care expansion.
- Oral:Mucosal immune system engagement bypassing injection requirements entirely. Gastrointestinal degradation challenges constrain oral bioavailability for protein-based constructs.
Clinical infrastructure favors intramuscular delivery; patient access expansion favors subcutaneous alternatives.
End User:
Procurement authority concentration is reshaping vendor relationships across institutional categories.
- Hospitals:Integrated health systems with centralized pharmacy-and-therapeutics committee governance controlling combination immunotherapy procurement. Academic medical centers in the Northeastern United States negotiate platform-level agreements bundling checkpoint inhibitors with vaccine access.
- Research Institutes:Early-phase clinical trial execution sites with specialized GMP vector production and QC analytics capabilities. Talent scarcity from competing gene therapy developers in San Diego clusters constrains expansion.
- Specialty Clinics:Focused oncology practices adopting patient-specific neoantigen selection workflows at accelerating velocity. Next-generation sequencing infrastructure investments differentiate competitive positioning.
- Pharmaceutical Companies:Sponsor organizations conducting internal manufacturing or outsourcing to contract manufacturing organizations. Peptide synthesis supply concentration in the Northeastern United States limits price negotiation leverage.
Procurement scale favors hospital systems; innovation velocity favors research institutes.
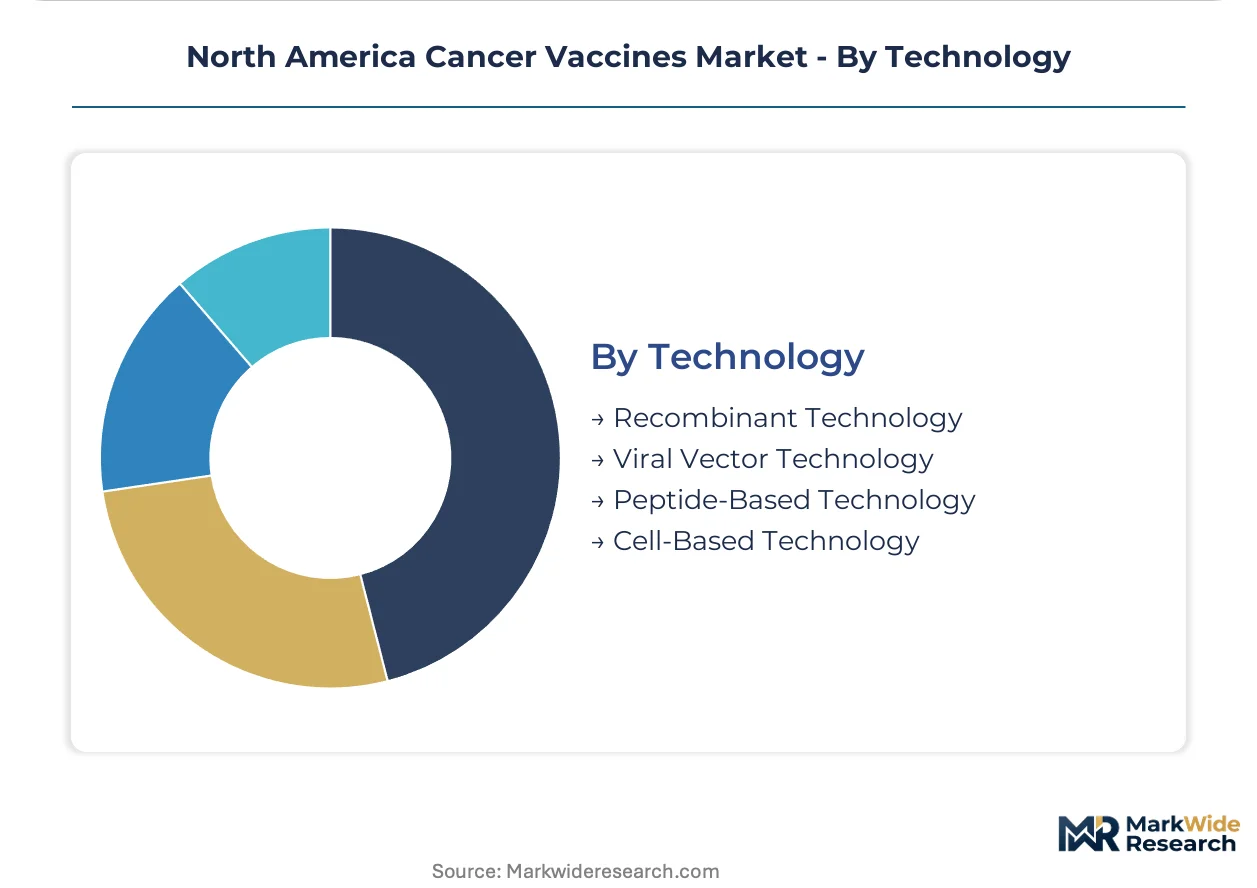
Technology:
Manufacturing modality selection determines platform flexibility, regulatory pathway, and margin structure.
- Recombinant Technology:Established protein expression systems leveraging microbial or mammalian cell hosts for antigen production. Margin pools concentrate in contract manufacturing organizations serving mature pipeline programs.
- Viral Vector Technology:Engineered adenoviral or lentiviral delivery vehicles achieving efficient cellular transduction. Viral vector technology leads clinical pipelines across solid tumor indications.
- Peptide-Based Technology:Synthetic antigen constructs enabling precise epitope targeting with simplified manufacturing. DNA vaccines are expanding most quickly as electroporation delivery improves immunogenicity profiles.
- Cell-Based Technology:Autologous or allogeneic cellular platforms requiring sophisticated GMP-grade infrastructure. Manufacturing talent scarcity in Boston and San Diego clusters constrains capacity expansion.
Regulatory maturity favors recombinant platforms; pipeline momentum favors viral vector approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America Cancer Vaccines Market exhibits limited cross-border trade intensity, with domestic production serving most therapeutic demand across both countries. Regional supply chains center on specialized biologics manufacturing clusters rather than commodity vaccine distribution networks.
United States
Oncology specialty clinics in the Northeastern United States anchor therapeutic vaccine adoption, driven by academic medical center consolidation of combination immunotherapy procurement. The FDA's Breakthrough Therapy designation compresses Phase 2-to-approval timelines for personalized neoantigen candidates. Boston and San Diego clusters compete aggressively for GMP-grade vector production talent, constraining manufacturing capacity expansion.
Canada
Canadian demand concentrates in Ontario and Quebec provinces, where Health Canada's Priority Review stream synchronizes cross-border clinical trial recruitment with U.S. protocols. Health Canada observes evolving FDA guidance on surrogate endpoints to align conditional approval frameworks for personalized cancer vaccines. Toronto's research institutes specialize in early-phase trial execution, though talent scarcity from competing gene therapy developers limits expansion velocity.
Northeastern United States
Major cancer centers in Massachusetts, New York, and Pennsylvania negotiate platform-level agreements bundling checkpoint inhibitors with investigational vaccine access. The FDA's accelerated approval pathways for breakthrough therapies reshape commercial timelines for regional developers. Contract manufacturing organizations in this corridor capture disproportionate margin pools in peptide synthesis, limiting price negotiation leverage for emerging biotech innovators.
Mountain West and Prairie Provinces
Rural oncology clinics across Montana, Idaho, Alberta, and Saskatchewan face strained cold-chain infrastructure for minus 70 degrees Celsius distribution requirements. Health Canada and provincial health authorities coordinate procurement for decentralized therapeutic vaccine administration. Community oncology networks in this region favor subcutaneous delivery routes to bypass specialized intramuscular training barriers.
Southeastern United States
Underpenetrated infusion centers in Florida, Georgia, and the Carolinas represent addressable sites for decentralized therapeutic vaccine administration. The IRA's orphan-designated price negotiation carve-outs retain protected pricing windows that biotech innovators exploit through indication-specific development strategies. Regional health systems invest in next-generation sequencing infrastructure to support patient-specific neoantigen selection workflows.
North America Cancer Vaccines Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in vector production and peptide synthesis. The North America Cancer Vaccines Market structures around three player tiers: large pharmaceutical incumbents with checkpoint inhibitor franchises, mRNA platform innovators with manufacturing modularity, and specialized biotech developers with personalized medicine architectures. Dominant competitive moves include strategic partnerships between biotech innovators and institutional investors, plus capacity expansion in GMP-grade vector production facilities.
Within the large pharmaceutical tier, Merck & Co., Inc. and GSK plc occupy positions defined by established immunotherapy portfolios. Among mRNA platform innovators, Moderna, Inc. and BioNTech SE exemplify manufacturing flexibility that extends from infectious disease into personalized neoantigen production. Dendreon Pharmaceuticals LLC represents the specialized biotech archetype with concentrated therapeutic vaccine expertise.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GSK plc |
| AstraZeneca plc |
| Moderna, Inc. |
| Dendreon Pharmaceuticals LLC |
| BioNTech SE |
| Bavarian Nordic |
| Agenus Inc. |
| Inovio Pharmaceuticals, Inc. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on GMP-grade peptide synthesis capacity in the Northeastern United States determines both margin compression at emerging biotech developers and the geographic shape of contract manufacturing networks serving cancer vaccine programs.
Pricing Analysis
Oncology specialty clinics anchor value-based pricing structures that stratify across personalized neoantigen, off-the-shelf therapeutic, and preventive vaccine tiers. Price differentiation hinges on manufacturing complexity and cold-chain intensity, with minus 70 degrees Celsius distribution requirements commanding premium positioning. Pricing pressure stems from Health Canada's cross-border procurement synchronization compressing regional launch gaps. Community oncology networks in the Southeastern United States exhibit highest price sensitivity due to reimbursement infrastructure gaps, while academic medical centers in Boston and New York demonstrate lowest sensitivity given consolidated pharmacy-and-therapeutics committee governance.
Supply Chain Analysis
Extended payment terms from contract manufacturing organizations in Massachusetts and Pennsylvania strain working capital at emerging biotech developers pursuing personalized vaccine platforms. Supply concentrates in the United States for GMP vector production, Canada for early-phase clinical trial execution, and Switzerland for specialized peptide synthesis equipment. Raw material dependencies include synthetic nucleotides, viral vector seed stocks, and electroporation device components. Single-source vulnerability in electroporation hardware manufacturing creates adoption friction for DNA vaccine programs. Distribution runs through specialized cold-chain logistics providers serving minus 20 to minus 70 degrees Celsius requirements rather than conventional pharmaceutical wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority consolidation at academic medical centers is shifting buyer power toward platform-level negotiators, fragmenting traditional pharmaceutical account-manager relationships across the North American cancer vaccines market.
For Market Incumbents: Harden manufacturing scale advantages through captive GMP vector production capacity in Boston and San Diego clusters, insulating against emerging mRNA platform competitors. Deepen backward integration into peptide synthesis to reduce dependency on Northeastern contract manufacturing organizations capturing disproportionate margin pools. Anchor combination immunotherapy protocols through centralized pharmacy-and-therapeutics committee relationships at major cancer centers. For New Entrants and Emerging Players: Community oncology networks in the Southeastern United States represent the most penetrable entry point for decentralized therapeutic vaccine administration, bypassing Northeastern procurement concentration. DNA vaccine platforms with simplified subcutaneous delivery offer technical differentiation against intramuscular protocols requiring specialized training. Pursue orphan-designated indication strategies to exploit IRA price negotiation carve-outs and retain protected pricing windows. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors manufacturing-modular mRNA innovators with infectious disease capacity pivot potential. Long-term viability hinges on integrated data-and-manufacturing platforms rather than molecule exclusivity. Acquisition targets should demonstrate validated neoantigen prediction algorithms with prospective clinical correlation. Watch FDA guidance evolution on surrogate endpoints for personalized cancer vaccine submissions as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP vector production expansion in Boston clusters addresses acute talent scarcity constraining capacity. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses Phase 2-to-approval timelines for personalized neoantigen candidates. |
| Licensing Agreement | Checkpoint inhibitor combinations with therapeutic vaccines expand addressable populations across solid tumors. |
| Pipeline Diversification | Hybrid viral vector-peptide platforms open intellectual property white space beyond single-modality approaches. |
| Clinical Trial Advancement | Health Canada Priority Review synchronizes cross-border recruitment with U.S. accelerated pathways. |
Research Methodology
Desk research of FDA filings, Health Canada submissions, ClinicalTrials.gov records, and hospital procurement databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and GMP manufacturing specialists. Primary fieldwork combined with secondary validation through SEC 10-K disclosures and contract manufacturing organization capacity reports. Bottom-up patient population modeling and top-down market sizing triangulated volume and value estimates across the analysis window.
Assumptions held fixed include FDA and Health Canada regulatory pathway structures, checkpoint inhibitor combination protocol adoption curves, and cold-chain infrastructure investment trajectories. Variables tested across the projection horizon encompassed neoantigen prediction algorithm validation timelines, electroporation device reimbursement coding evolution, and community oncology network decentralization velocity. Segmentation dimensions modeled included therapeutic intent, technology platform, delivery method, and regional regulatory cluster. CAGRs derived from patient population epidemiology, pricing trajectory assumptions, and therapy line penetration curves.
Practitioners should monitor FDA guidance publication on surrogate endpoints for cell and gene therapies, Health Canada conditional approval framework alignment, and CMS electroporation coding decisions for early signals requiring forecast adjustment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market