
 Viral Vector Production (Research-Use) Market | 2026-2036
Viral Vector Production (Research-Use) Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Vector Production (Research-Use) Market Analytics
Plasmid DNA is expanding its share as the preferred transfection-grade raw material, displacing older animal-derived reagent formulations and cutting batch-to-batch variability in GMP-compliant workflows. Thermo Fisher Scientific Inc. leverages its integrated reagent-to-instrument portfolio to control upstream supply economics for research-grade vector producers. Lonza anchors European vector manufacturing through its Basel-based specialized facilities, while Merck KGaA competes via its dominance in high-purity cell culture media formulations.
Viral vector production for research use encompasses the upstream generation, downstream purification, and quality-controlled release of recombinant viral particles—typically manufactured through transient transfection of HEK293 or HEK293T cells using plasmid DNA encoding viral structural genes and the therapeutic transgene, with titers routinely assessed via qPCR or ELISA to confirm infectious units per milliliter. Lentiviral vectors occupy the largest share of current research demand due to their stable genomic integration capacity in hard-to-transfect cell types, while AAV vectors represent the fastest-expanding category as their clinical translation pipeline for in vivo gene therapy accelerates research investment. Academic research institutes and biotechnology companies together constitute the primary demand base, with pharmaceutical firms increasingly internalizing vector capabilities to protect intellectual property around novel capsid engineering.
FDA guidance on chemistry, manufacturing, and controls for gene therapy investigational new drug applications shapes product specifications for research vectors destined for clinical bridging studies, while EMA's ATMP classification framework influences how European producers structure their development-grade output. ISO 14644 cleanroom standards and WHO biosafety guidelines for recombinant viral agents govern facility design and operator containment protocols across production sites. Stakeholders must monitor how evolving regulatory convergence between FDA and EMA on vector potency assays will reshape qualification requirements for research-use material.
Market Dynamics
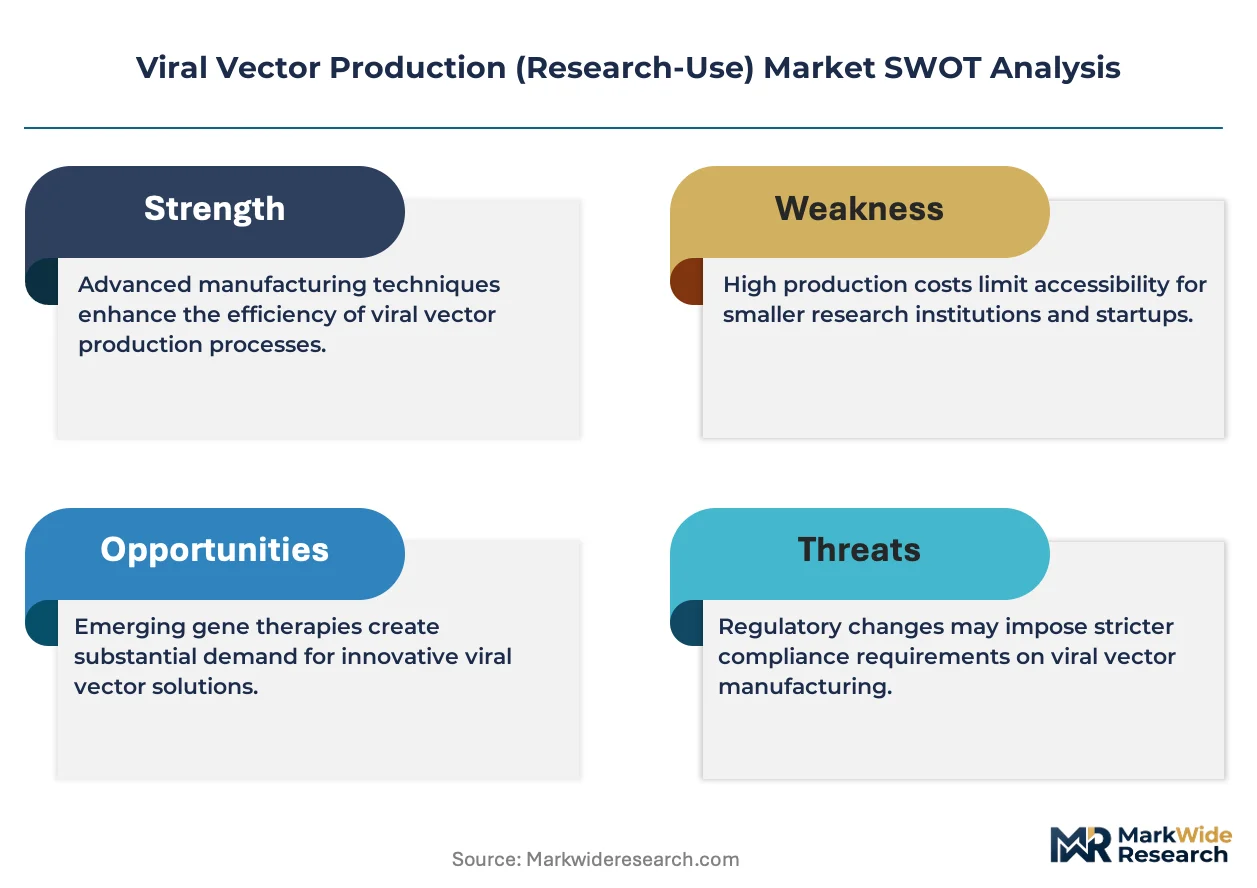
Suspension-based manufacturing platforms are compressing production timelines for research-grade viral vectors while simultaneously concentrating technical expertise among facilities capable of HEK293 cell-line optimization at scale.
Growth Catalysts
- NIH funding expansion:Sustained federal investment through the National Institutes of Health accelerates gene therapy program initiation at academic medical centers, generating predictable demand for lentiviral and AAV vector lots.
- EMA ATMP classification clarity:The European Medicines Agency's advanced therapy medicinal products framework reduces regulatory ambiguity for European producers bridging research material into exploratory clinical studies.
- HEK293 suspension adaptation:Widespread conversion from adherent to suspension cell culture is integrating scalable bioreactor infrastructure into mid-tier research facilities previously limited to flask-based production.
Market Restraints
- Plasmid DNA supply concentration:Transfection-grade plasmid manufacturing concentrates among a limited set of GMP-certified suppliers, exposing vector producers to queue-based allocation during demand surges.
- HEK293T licensing encumbrances:Cell-line intellectual property held by academic institutions imposes per-batch royalty obligations that inflate cost structures for commercial research applications.
- FDA potency assay variability:Divergent infectious titer measurement protocols between FDA review divisions create specification reconciliation burdens for vectors intended for IND-enabling studies.
Strategic Opportunities
- India CDMO emergence:Contract development and manufacturing organizations in India are building viral vector capabilities to capture cost-sensitive research demand from European biotechnology firms.
- AI-driven capsid engineering:Machine learning platforms for predicting AAV tissue tropism are converging with high-throughput screening infrastructure to compress novel serotype development cycles.
- ISO 14644 modular cleanroom deployment:Prefabricated containment units are reducing facility capital requirements for academic institutions seeking to internalize vector production.
Industry Challenges
- Gene therapy manufacturing workforce scarcity:Experienced cell culture specialists and viral titer assay technicians command premium compensation, constraining facility expansion timelines.
- GMP-grade raw material qualification delays:Vendor change notification requirements for serum-free media and plasmid DNA extend supply chain reconfiguration cycles beyond typical research grant periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Vector Production (Research-Use) Market |
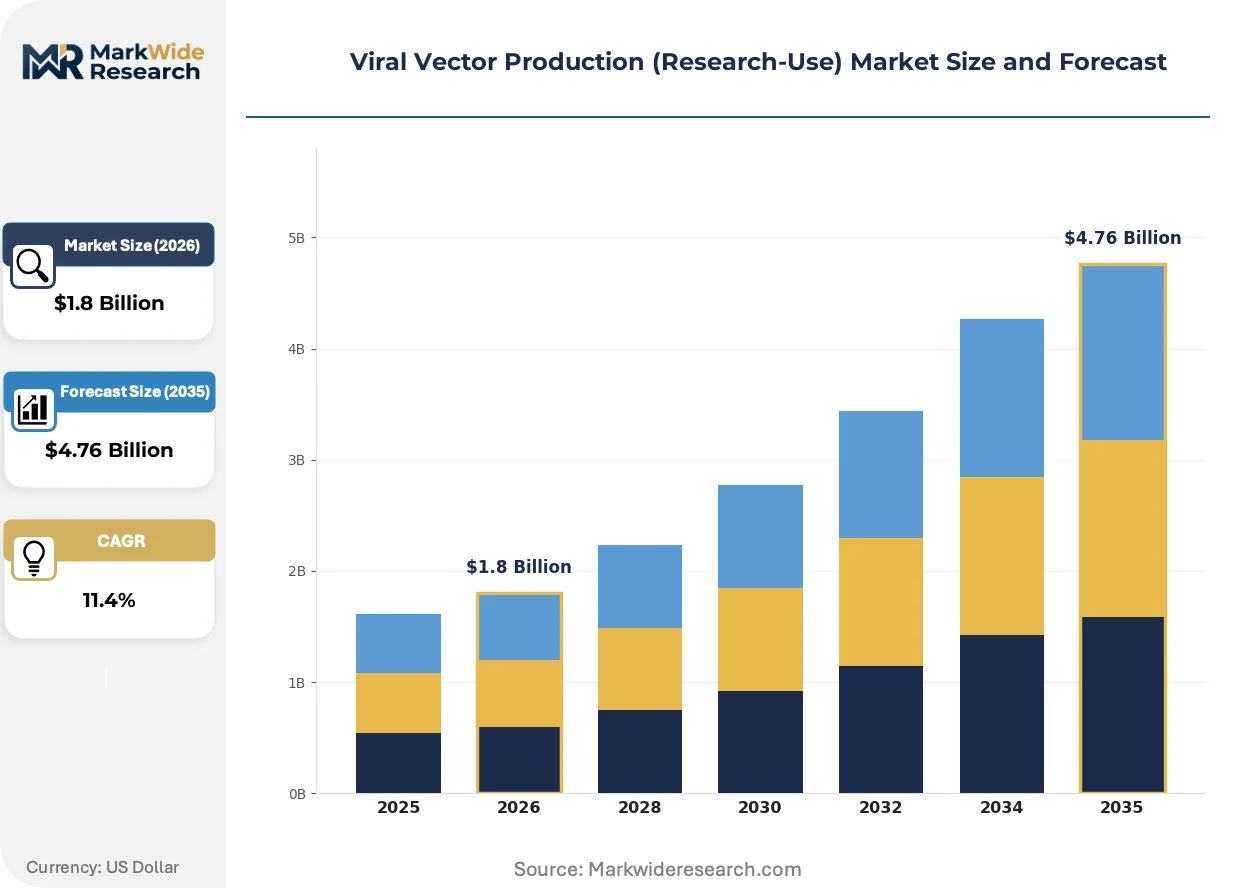
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Adenoviral Vectors, Lentiviral Vectors, AAV Vectors, Retroviral Vectors Application: Gene Therapy, Vaccine Development, Oncological Research, Cellular Research Technology: Transfection Techniques, Infection Methods, Electroporation, Viral Packaging End User: Academic Research Institutes, Biotechnology Companies, Pharmaceutical Firms, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Lonza, Merck KGaA, Charles River Laboratories, Oxford Biomedica plc, FUJIFILM Diosynth Biotechnologies, Catalent Inc., Aldevron, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Vector Production (Research-Use) Market Evolving Landscape
Continuous processing architectures and automated analytics are compressing batch release timelines while reshaping facility design specifications for research-grade vector manufacturing.
Single-use bioreactor technology is integrating perfusion-based cell retention systems into upstream workflows, enabling sustained high-density HEK293 cultures that yield 3-5 fold titer improvements over batch processes. Contract manufacturers in Switzerland and the United States are adopting these systems to reduce turnaround times for multi-client campaigns. The shift is compressing equipment utilization economics and forcing adherent-platform holdouts toward suspension retrofits.
REACH chemical registration requirements in Europe are restricting certain cationic lipid formulations historically used in transient transfection protocols, prompting reformulation efforts around biodegradable alternatives. Vector producers serving EMA-regulated clinical pathways must now document substance volume thresholds and safety data sheet compliance for downstream release. German and Dutch manufacturing sites are responding by qualifying lipid libraries with pre-registered European supply chains.
Consolidated procurement through centralized biobank repositories is displacing bilateral vector sourcing arrangements between individual laboratories and production facilities. The Wellcome Sanger Institute and similar genomic centers are aggregating demand into framework agreements with tiered pricing based on lot volume and characterization depth. This concentration is most visible in the United Kingdom and Scandinavia, where national funding structures favor shared infrastructure over institutional silos.
Viral Vector Production (Research-Use) Market Segmentation
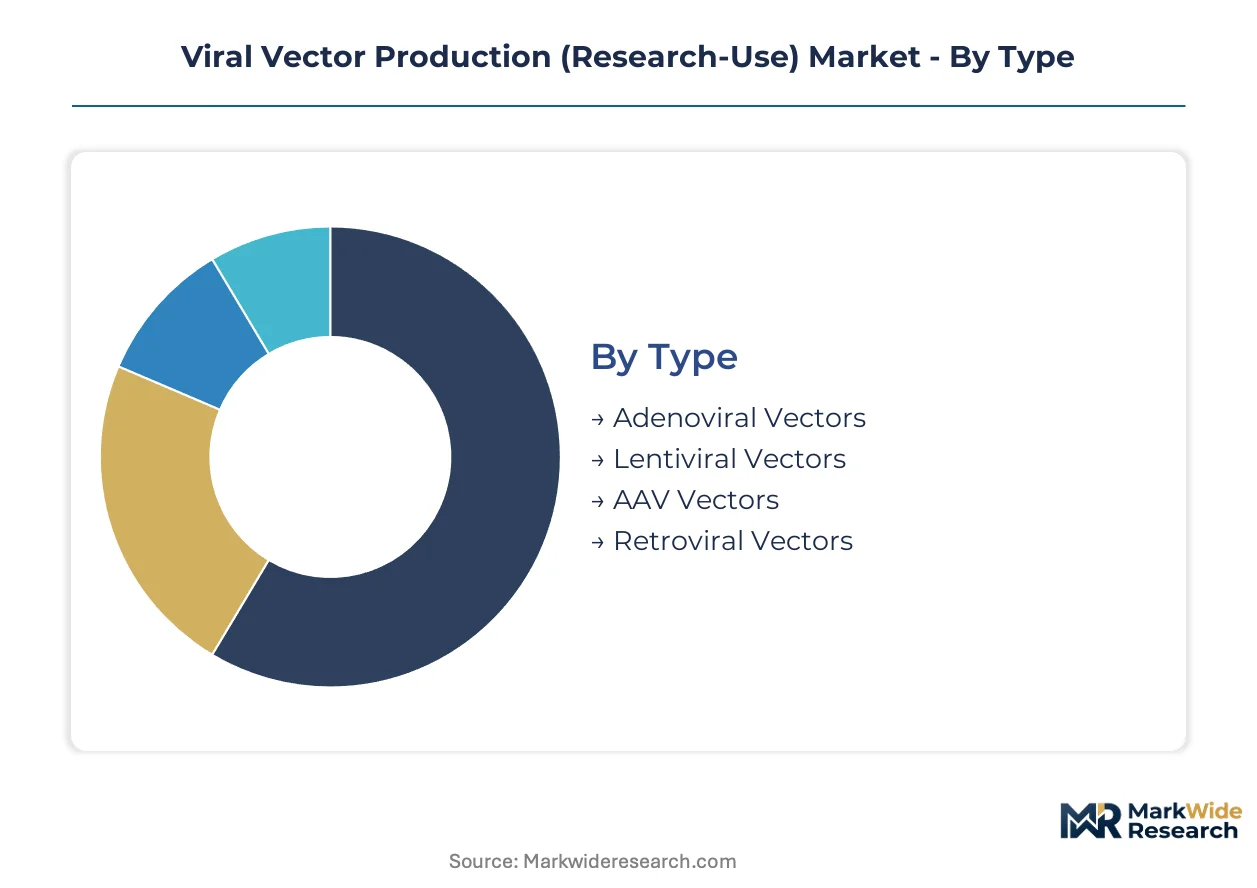
Viral vector production for research use fragments across four distinct dimensions, each capturing a different axis of technical specialization and procurement behavior. Understanding these splits reveals where capacity investments concentrate and where margin compression threatens incumbent positions.
Type:
Volume production currently favors lentiviral platforms, while premium pricing attaches to novel AAV serotypes engineered for tissue-specific targeting.
- Lentiviral Vectors:Stable genomic integration capacity in hard-to-transfect cell types positions these vectors as the workhorse for ex vivo gene modification protocols. Demand concentrates at academic medical centers in the United States running NIH-funded hematopoietic stem cell programs, though HEK293T licensing royalties inflate per-batch costs.
- AAV Vectors:In vivo gene therapy translation is accelerating research investment in adeno-associated viral platforms, particularly for neurological and ocular indications. United States biotechnology clusters in Massachusetts and California are driving specification requirements for high-titer, empty-capsid-depleted material.
- Adenoviral Vectors:Vaccine development programs and oncolytic applications sustain demand for high-capacity adenoviral platforms, with CDMOs in Switzerland maintaining specialized containment infrastructure for replication-competent strains.
- Retroviral Vectors:Murine leukemia virus-based systems retain niche utility in T-cell receptor engineering workflows, primarily serving European academic consortia with legacy stable producer cell lines.
Today's leader: Lentiviral Vectors. Tomorrow's challenger: AAV Vectors.
Application:
Gene therapy commands the highest purity specifications and corresponding price premiums, while vaccine development runs at greater volume with relaxed characterization requirements.
- Gene Therapy:IND-enabling studies demand full identity, purity, and potency documentation per FDA guidance, with vectors requiring GMP-adjacent manufacturing at research scale. United States pharmaceutical firms are internalizing these capabilities to protect novel capsid intellectual property.
- Vaccine Development:Pandemic preparedness funding has expanded adenoviral vector procurement for infectious disease platforms, with Indian CDMOs capturing cost-sensitive European demand through competitive batch pricing.
- Oncological Research:CAR-T and TCR-T engineering programs sustain lentiviral consumption across academic-industry partnerships, particularly in German and Dutch cellular therapy hubs.
- Cellular Research:Basic science applications tolerate lower-tier characterization, with centralized biobank procurement in the United Kingdom displacing bilateral laboratory sourcing.
Gene Therapy captures margin. Vaccine Development captures volume.
Technology:
Transfection-grade reagent supply concentration is forcing facilities toward platform standardization, while electroporation remains confined to specialized applications.
- Transfection Techniques:Cationic lipid and calcium phosphate methods dominate HEK293-based production, with plasmid DNA supply queues from GMP-certified vendors constraining campaign scheduling. REACH chemical registration in Europe is restricting legacy lipid formulations.
- Infection Methods:Baculovirus-mediated production in Sf9 insect cells supports AAV manufacturing at scale, with Swiss and United States CDMOs investing in dedicated baculovirus seed stock facilities.
- Electroporation:High-voltage cell permeabilization enables plasmid delivery to suspension-adapted lines resistant to chemical transfection, finding adoption in German facilities optimizing HEK293 density.
- Viral Packaging:Stable producer cell lines with inducible structural gene expression reduce plasmid dependency, though intellectual property encumbrances limit commercial deployment.
Transfection Techniques anchor current capacity. Viral Packaging promises future efficiency.
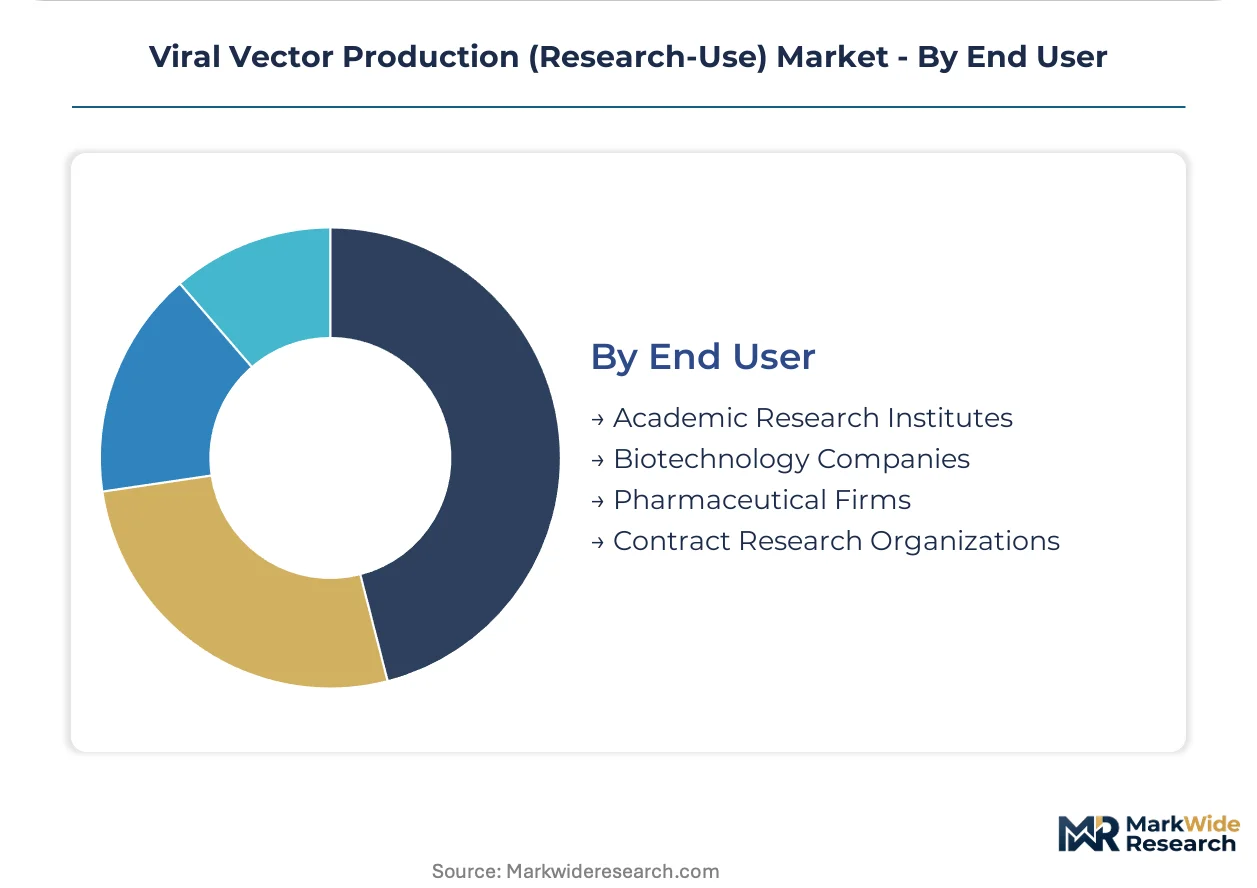
End User:
Academic institutes prioritize cost containment and shared infrastructure, while pharmaceutical firms demand captive supply security.
- Academic Research Institutes:NIH funding expansion in the United States sustains predictable demand for characterized vector lots, with modular ISO 14644 cleanrooms reducing capital barriers to internal production.
- Biotechnology Companies:Venture-backed firms in Massachusetts and California bridge research-grade material into exploratory clinical studies, requiring EMA ATMP-aligned documentation for European trial initiation.
- Pharmaceutical Firms:Large-cap companies are acquiring vector manufacturing capabilities to secure supply chain control, with FDA potency assay variability creating specification reconciliation burdens.
- Contract Research Organizations:Multi-client campaigns drive adoption of single-use bioreactor technology with perfusion systems, compressing turnaround times through equipment utilization economics.
Academic Research Institutes define volume. Pharmaceutical Firms define specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Massachusetts biotechnology corridor generates the densest concentration of viral vector procurement for gene therapy programs, with NIH funding expansion sustaining predictable demand across academic medical centers and venture-backed firms.
United States
FDA guidance on chemistry, manufacturing, and controls shapes vector specifications for IND-enabling studies, compressing qualification timelines for research-grade material. The National Institutes of Health sustains grant-funded demand at academic institutes in Maryland and California. Greater Boston anchors contract manufacturing capacity for lentiviral and AAV platforms.
Germany
EMA's ATMP classification framework reduces regulatory ambiguity for producers bridging research material into exploratory clinical studies. REACH chemical registration restricts legacy cationic lipid formulations, prompting reformulation around biodegradable alternatives. The Rhine-Ruhr and Bavarian cellular therapy hubs sustain lentiviral consumption for CAR-T engineering programs.
Switzerland
Swissmedic oversight governs facility design for replication-competent adenoviral containment infrastructure. Basel anchors specialized vector manufacturing through dedicated CDMO facilities serving European biotechnology demand. The Lake Geneva region concentrates technical expertise in HEK293 suspension adaptation and perfusion bioreactor deployment.
United Kingdom
Centralized biobank procurement through the Wellcome Sanger Institute displaces bilateral laboratory sourcing arrangements. National funding structures favor shared infrastructure over institutional silos across Oxford and Cambridge genomic centers. Modular ISO 14644 cleanroom deployment reduces capital barriers for academic institutions internalizing vector production.
India
Contract development and manufacturing organizations in Hyderabad and Bengaluru build viral vector capabilities to capture cost-sensitive research demand from European biotechnology firms. The country's national pharmaceutical regulator governs export documentation for research-use material destined for clinical bridging studies. Indian CDMOs compete on batch pricing for adenoviral vector campaigns.
Viral Vector Production (Research-Use) Market Competitive Landscape
Global majors compete with regional champions across reagent supply, manufacturing capacity, and technical service dimensions. The vendor base concentrates among integrated life science conglomerates and specialized CDMOs, with tiered positioning across premium GMP-adjacent and standard research-grade offerings. Three archetypes dominate: diversified reagent-to-instrument conglomerates, specialized viral vector CDMOs, and plasmid DNA-focused raw material suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves, as facilities race to convert adherent platforms to suspension manufacturing.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the integrated reagent-to-instrument archetype controlling upstream supply economics. Lonza occupies a position within the specialized CDMO tier, anchoring European vector manufacturing through Basel-based facilities. Charles River Laboratories represents the contract research and manufacturing service model, sitting within the technical outsourcing tier that serves pharmaceutical firms internalizing vector capabilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Lonza |
| Merck KGaA |
| Charles River Laboratories |
| Oxford Biomedica plc |
| FUJIFILM Diosynth Biotechnologies |
| Catalent Inc. |
| Aldevron |
| Sartorius AG |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up CDMO specialists in Switzerland and the United States anchor pricing discipline through concentrated manufacturing capacity, while their sovereign-backed competitors in India compress margins through competitive batch pricing for European biotechnology demand. This ownership split creates divergent supply behaviors: Western facilities prioritize GMP-adjacent certification premiums, whereas Indian producers exploit cost arbitrage in research-grade adenoviral vector campaigns.
Pricing Analysis
Input-cost pass-through from transfection-grade plasmid DNA queues and HEK293T licensing royalties shapes pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on FDA potency assay documentation depth and ISO 14644 cleanroom certification grade. Cost compression in the standard tier intensifies because REACH chemical registration restricts legacy cationic lipid formulations, forcing reformulation investments. Academic research institutes exhibit highest price sensitivity due to fixed NIH grant periods, while pharmaceutical firms absorb premium pricing to secure captive supply control.
Supply Chain Analysis
Regional distribution centers in Basel, Boston, and Hyderabad organize hub-and-spoke patterns for plasmid DNA, serum-free media, and viral seed stocks. Geographic supply concentration centers on the United States, Switzerland, and India for manufacturing capacity, with plasmid DNA production anchored in North America and Europe. Raw material dependencies rest on GMP-certified plasmid DNA, high-purity cell culture media, and cationic lipid formulations. Single-source vulnerability in transfection-grade plasmid suppliers exposes vector producers to queue-based allocation during demand surges. Distribution runs through centralized biobank repositories in the United Kingdom and bilateral laboratory arrangements elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EMA ATMP classification clarity in Europe reduces regulatory compliance costs relative to FDA potency assay variability burdens in the United States, creating margin capture opportunities for cross-border CDMO positioning.
For Market Incumbents: Lock in plasmid DNA supply agreements through backward integration or long-term offtake contracts with GMP-certified suppliers to defend against queue-based allocation risks. Add suspension-adapted HEK293 capacity in Basel or Boston to capture premium pricing for IND-enabling vector lots, reinforcing certification-driven margin protection against Indian cost competition.
For New Entrants and Emerging Players: Begin with modular ISO 14644 cleanroom deployment for academic institutions in the United Kingdom seeking to internalize vector production, exploiting national funding structures that favor shared infrastructure. Target cost-sensitive European biotechnology firms with baculovirus-mediated AAV manufacturing in Hyderabad, leveraging India's regulatory documentation framework for research-use export material.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier CDMOs with adherent-platform legacy infrastructure facing suspension retrofit capital demands. Long-term viability over a 5-10 year window favors facilities with demonstrated HEK293 density optimization and perfusion bioreactor deployment. Watch FDA-EMA convergence on vector potency assay standards as the inflection signal for qualification requirement harmonization.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Single-use bioreactor adoption with perfusion systems compresses turnaround times for multi-client campaigns. |
| Regulatory Approval Pathway | EMA ATMP-aligned documentation reduces ambiguity for European producers bridging research into exploratory clinical studies. |
| Backward Integration | In-house plasmid DNA production insulates vector manufacturers from GMP-certified supplier queue risks. |
| Licensing Agreement | HEK293T cell-line intellectual property settlements determine per-batch royalty obligations for commercial research applications. |
| Capacity Expansion | Suspension platform conversion in mid-tier research facilities unlocks 3-5 fold titer improvements over batch processes. |
Research Methodology
Direct dialogue with vector manufacturing facility directors, regulatory affairs leads at gene therapy developers, academic procurement officers, and CDMO commercial heads grounded qualitative assessment in operational realities. Secondary validation drew from FDA gene therapy CMC guidance documents, EMA ATMP classification frameworks, NIH funding disbursement records, and ISO 14644 cleanroom certification databases. Bottom-up and top-down triangulation reconciled facility-level capacity estimates with aggregate demand projections across the analysis window.
Bottom-up modeling segmented volume and value across vector type, application, technology, and end-user dimensions, with additional stratification by regional regulatory cluster and manufacturing platform maturity. Top-down constraints incorporated macro funding trends and patent landscape evolution. CAGRs were derived from fitted growth curves applied to disclosed capacity expansion timelines and grant funding trajectories, with infectious disease preparedness budgets and pandemic response allocations serving as demand-side forecast inputs.
Several conditions sit outside the modeled scope, including preclinical-stage vector programs without disclosed IND timelines, military biodefense applications subject to classification, and consumer-directed gene therapy services operating outside regulatory frameworks. Forecasts reflect documented assumptions regarding NIH funding continuity and EMA-FDA regulatory convergence pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market