
 Global Bovine-Based Collagen for Biomedical Applications Market | 2026-2036
Global Bovine-Based Collagen for Biomedical Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bovine-Based Collagen for Biomedical Applications Market Foresight
Recombinant human collagen is recalibrating cost benchmarks across wound closure and tissue scaffold categories. Gelita AG leverages its century-long gelatin processing heritage to sustain raw material security across European tannery networks. Medtronic anchors its position through captive sourcing relationships with abattoir partners in North America. Viscofan BioEngineering differentiates by controlling collagen film extrusion capacity for surgical barrier applications.
Bovine-based collagen for biomedical applications denotes purified extracellular matrix protein extracted from bovine dermis or tendon, typically comprising Type I collagen with triple-helix integrity preserved through controlled enzymatic digestion and pH-adjusted precipitation. Manufacturers achieve biomedical-grade purity through pepsin solubilization followed by sterile filtration and terminal lyophilization, yielding implantable matrices for cellular infiltration and hemostasis. Gelatin and hydrolysate variants dominate current volume flows due to their established dissolution profiles and compatibility with existing sterilization modalities, while peptide-grade fractions command premium positioning in targeted drug delivery matrices where molecular weight specificity governs release kinetics. Orthopedics and tissue engineering applications represent the fastest-expanding consumption pools as surgeons adopt collagen-based osteoconductive carriers and three-dimensional scaffolds for autologous cell expansion.
FDA 21 CFR Part 1271 xenotransplantation regulations and EMA CHMP guidelines on bovine spongiform encephalopathy risk materials constrain sourcing geography and mandate closed-herd documentation, effectively raising compliance costs for new entrants while insulating incumbent suppliers with validated supply chains. ISO 22442 standards for medical devices utilizing animal tissues further specify viral inactivation validation protocols that manufacturers must embed within quality management systems. Stakeholders must monitor evolving EMA guidance on transmissible spongiform encephalopathy geographic risk classifications, as reclassification of source regions would force immediate supply chain restructuring for firms dependent on specific cattle-raising territories.
Market Dynamics
FDA 21 CFR Part 1271 xenotransplantation traceability mandates are compressing supplier qualification timelines while regenerative medicine protocols in wound care and orthopedics pull volume toward validated collagen matrices. This regulatory tightening concentrates procurement power among incumbents with documented closed-herd supply chains.
Growth Catalysts
- Regenerative wound care protocols:Hospital systems in Germany and Japan are standardizing collagen dressing protocols for chronic ulcer management, creating pull-through demand for pharmaceutical-grade extracellular matrices.
- EMA CHMP BSE risk material guidance:Tightened geographic sourcing restrictions validate European tannery networks with multi-decade herd documentation, insulating compliant suppliers from price-based competition.
- Three-dimensional tissue scaffolding:Autologous cell expansion platforms for cartilage repair are absorbing increasing volumes of pepsin-solubilized Type I collagen with preserved triple-helix architecture.
Market Restraints
- Recombinant human collagen cost curves:Microbial and plant-expression platforms for human collagen sequences are compressing price benchmarks in wound closure applications, threatening bovine-derived margin structures.
- ISO 22442 viral validation burden:Medical device manufacturers must embed extensive viral inactivation protocols within quality management systems, extending new product qualification cycles by 18-24 months.
- BSE geographic risk reclassification exposure:EMA territory risk tier updates could force immediate supply chain restructuring for firms dependent on specific cattle-raising regions with elevated surveillance status.
Strategic Opportunities
- India surgical device localization:CDSCO medical device rules and production-linked incentive schemes for pharmaceuticals create opening for collagen biomaterial manufacturing within domestic supply chains.
- Targeted drug delivery peptide fractions:Molecular weight-specific collagen hydrolysates for controlled-release matrices represent premium positioning beyond commoditized gelatin volumes.
- Electrospun nanofiber barrier films:Convergence of collagen film extrusion with electrospinning technology enables next-generation surgical adhesion barriers with tunable degradation profiles.
Industry Challenges
- Peptide biochemistry talent scarcity:Enzymatic digestion optimization and triple-helix preservation require specialized protein chemistry expertise concentrated among aging technical workforces in European processing centers.
- Terminal lyophilization capacity constraints:Sterile filtration and freeze-drying infrastructure for biomedical-grade collagen requires capital-intensive cleanroom investments that strain mid-scale manufacturers.
- Cross-border herd documentation harmonization:Reconciling USDA, EMA, and PMDA traceability standards for shared source territories creates compliance friction in multinational supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bovine-Based Collagen for Biomedical Applications Market |
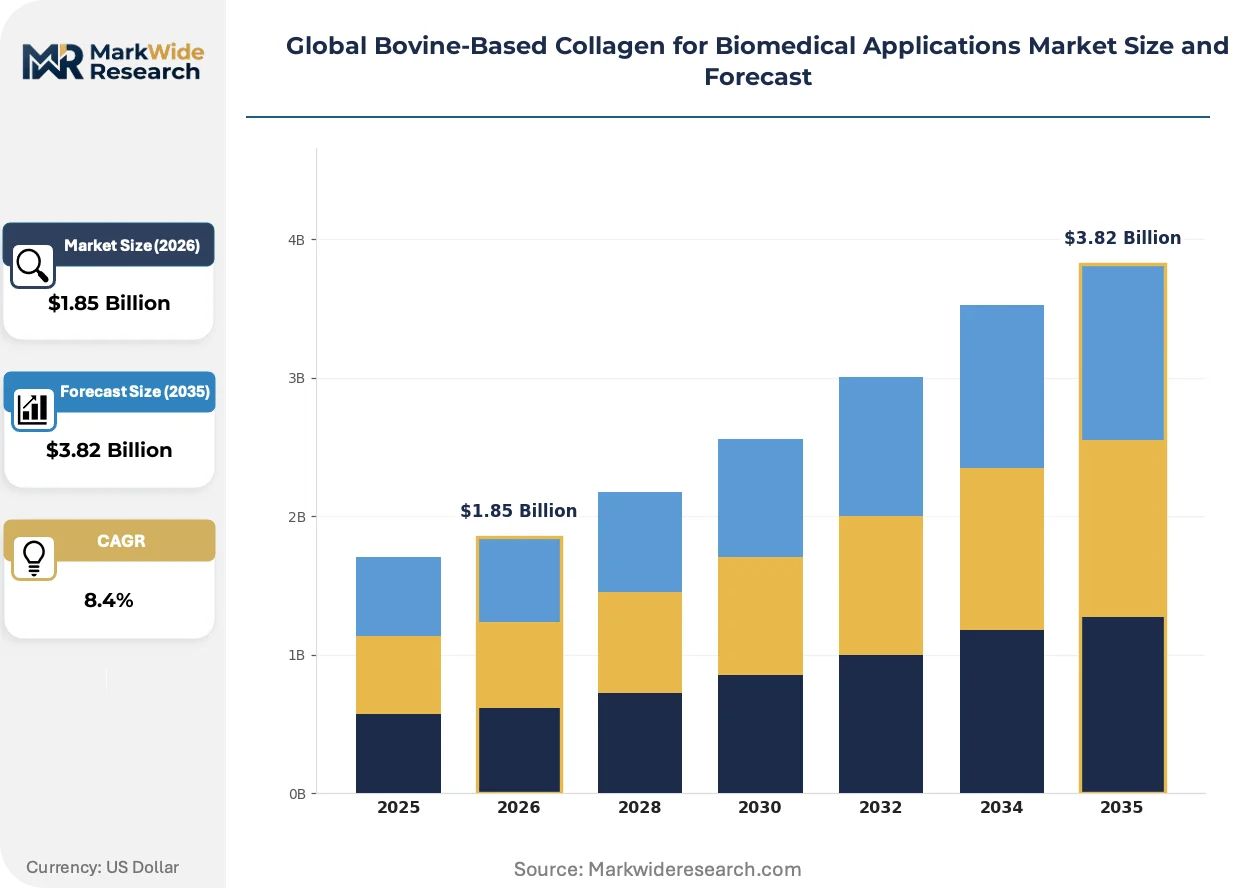
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Hydrolysate, Peptide, Powder, Film Application: Wound Care, Tissue Engineering, Drug Delivery, Cosmetic Surgery, Orthopedics End User: Research Institutes, Pharmaceutical Manufacturers, Cosmetic Firms, Medical Device Makers, Regenerative Centers Form: Freeze-dried, Spray-dried, Lyophilized, Soluble, Crosslinked |
| Companies Covered | Collagen Solutions Plc, Collagen Matrix, Inc., BBI Solutions, botiss biomaterials GmbH, Symatese, Medtronic, Viscofan BioEngineering, Gelita AG, Rousselot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bovine-Based Collagen for Biomedical Applications Market Shifts & Advancements
Enzymatic processing advances and regulatory data digitization are compressing batch-to-batch variability while regenerative medicine protocols reshape specification requirements. These forces are redefining competitive differentiation beyond raw material access.
Electrospun collagen nanofiber matrices are modularizing scaffold architecture for tissue engineering applications. Academic medical centers in the United States are adopting these platforms for autologous chondrocyte expansion at accelerating pace. The technology is modularizing what had been rigid, sheet-based product categories into tunable, patient-specific configurations.
EMA's evolving transmissible spongiform encephalopathy geographic risk classifications are redrawing acceptable sourcing territories. Manufacturers with validated supply chains in reclassified lower-risk zones gain procurement preference from risk-averse device sponsors. Orthopedic and dental implant segments are consolidating purchases around suppliers with multi-jurisdiction documentation capabilities.
Hospital procurement committees are consolidating collagen biomaterial contracts under value-analysis frameworks that unbundle product cost from service and training components. Integrated delivery networks in Germany and Japan are displacing distributor-mediated purchasing with direct manufacturer agreements. This concentration is most visible in wound care categories where standardization protocols reduce SKU complexity.
Global Bovine-Based Collagen for Biomedical Applications Market Segmentation
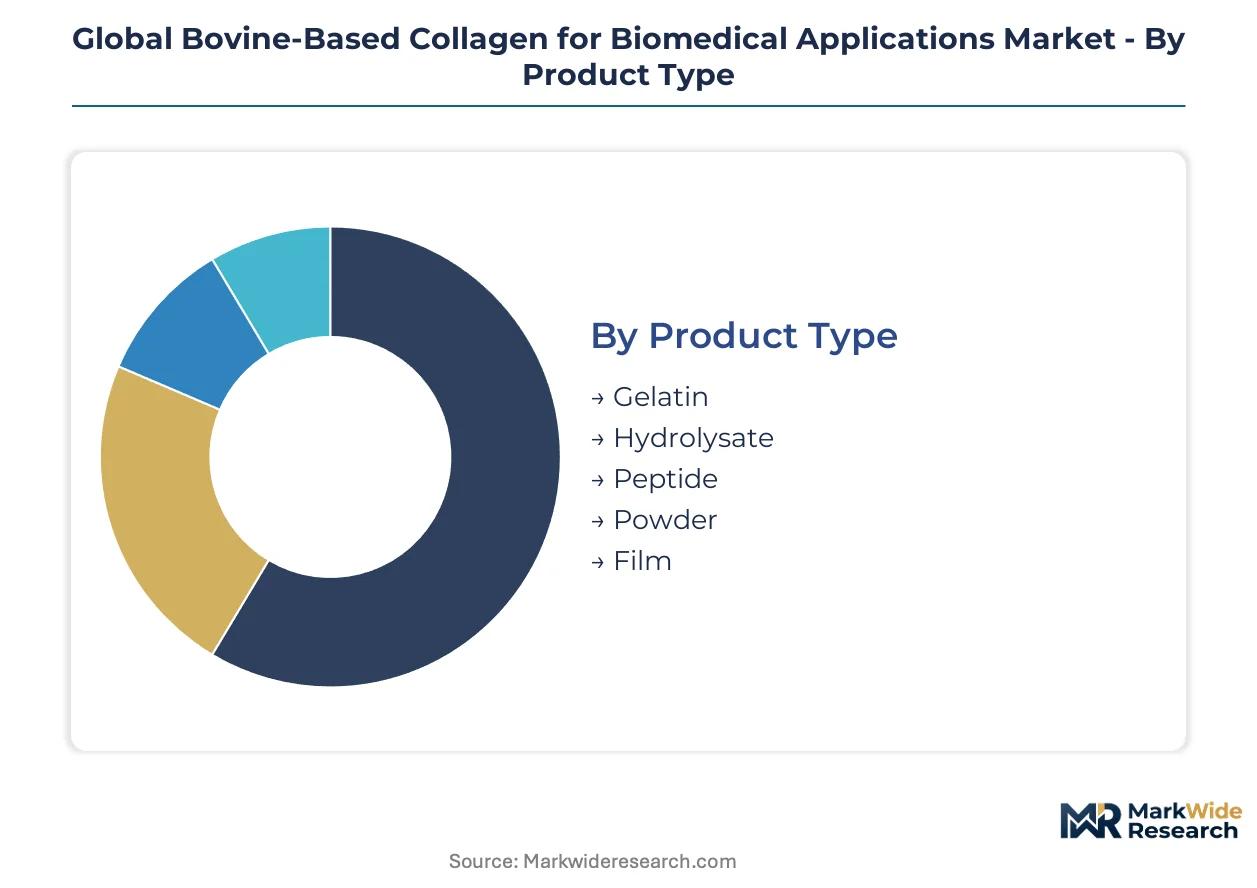
Bovine collagen specification requirements diverge sharply across therapeutic categories, forcing manufacturers to maintain parallel production trains with distinct enzymatic digestion protocols and terminal sterilization validations. Supply chain configuration for each segment reflects these technical boundaries, with gelatin and hydrolysate volumes flowing through established tannery networks while peptide-grade fractions require dedicated cleanroom infrastructure.
Product Type:
Raw material security concentrates among suppliers with validated access to closed-herd bovine tissues, creating tiered competitive positions based on extraction sophistication and purity certification.
- Gelatin:Partially hydrolyzed collagen with broad molecular weight distribution dominates current volume flows through its compatibility with existing sterilization modalities and established dissolution profiles. Hospital procurement committees in Germany and Japan standardize gelatin-based dressing protocols for chronic ulcer management, pulling supply through distributor relationships with multi-decade herd documentation.
- Peptide:Molecular weight-specific fractions command premium positioning in targeted drug delivery matrices where release kinetics govern therapeutic efficacy. Autologous cell expansion platforms for cartilage repair absorb increasing volumes of pepsin-solubilized Type I collagen with preserved triple-helix architecture, validating supplier investments in enzymatic optimization expertise.
- Hydrolysate:Enzymatically cleaved collagen fragments serve nutritional and lower-specification biomedical applications with reduced purity requirements.
- Powder:Lyophilized particulate formats enable flexible reconstitution for custom scaffold fabrication in research settings.
- Film:Extruded collagen sheets function as surgical adhesion barriers with tunable degradation profiles controlled by crosslinking density.
Today's leader: Gelatin. Tomorrow's challenger: Peptide.
Application:
End-use specification intensity separates commodity-grade from pharmaceutical-grade demand pools, with regenerative medicine protocols reshaping purchasing criteria beyond cost-per-gram metrics.
- Wound Care:Collagen dressings for chronic ulcer management require FDA 510(k) clearance or EMA CE marking with validated viral inactivation documentation. Hospital systems in the United States consolidate contracts under value-analysis frameworks that unbundle product cost from clinical training and protocol standardization services.
- Tissue Engineering:Three-dimensional scaffolds for autologous chondrocyte expansion demand triple-helix integrity preservation through controlled pepsin solubilization and pH-adjusted precipitation. Academic medical centers in the United States adopt electrospun nanofiber matrices at accelerating pace, modularizing rigid sheet-based categories into patient-specific configurations.
- Orthopedics:Osteoconductive carriers for bone regeneration integrate with synthetic ceramic phases to balance resorption kinetics with mechanical support.
- Drug Delivery:Controlled-release matrices exploit collagen's enzymatic degradability to tune active pharmaceutical ingredient liberation rates.
- Cosmetic Surgery:Dermal fillers and soft tissue augmentation products face heightened regulatory scrutiny for xenogeneic immunogenicity risk.
Volume concentrates in wound care. Value accumulates in tissue engineering.
End User:
Procurement sophistication varies across customer categories, with pharmaceutical-grade specifications filtering accessible supplier pools differently than research-scale purchases.
- Medical Device Makers:Integrate collagen biomaterials into hemostatic agents, adhesion barriers, and wound closure systems requiring ISO 22442 viral validation protocols embedded within quality management systems. These manufacturers extend new product qualification cycles by 18-24 months to satisfy EMA CHMP guidelines on bovine spongiform encephalopathy risk materials.
- Regenerative Centers:Autologous cell therapy facilities demand documented closed-herd sourcing with multi-jurisdiction traceability capabilities reconciling USDA, EMA, and PMDA standards. CDSCO medical device rules in India and production-linked incentive schemes create openings for domestic collagen biomaterial manufacturing serving these specialized purchasers.
- Pharmaceutical Manufacturers:Require peptide-grade fractions with molecular weight specificity for targeted drug delivery applications.
- Cosmetic Firms:Source lower-specification hydrolysates for topical formulation with reduced regulatory burden.
- Research Institutes:Purchase powder and soluble formats for exploratory scaffold fabrication with flexible specification tolerances.
Medical device makers anchor current demand. Regenerative centers drive specification evolution.
Form:
Terminal processing technology separates mid-scale manufacturers from capital-intensive competitors with sterile filtration and freeze-drying infrastructure.
- Lyophilized:Freeze-dried matrices preserve triple-helix architecture for implantable applications requiring cellular infiltration and hemostasis. Terminal lyophilization capacity constraints strain mid-scale manufacturers facing capital-intensive cleanroom investments, consolidating supply among incumbents with validated sterile filtration trains.
- Crosslinked:Chemical or physical crosslinking modulates degradation rates for surgical barrier applications requiring tunable residence times. Viscofan BioEngineering controls collagen film extrusion capacity for this segment, differentiating through in-house processing rather than merchant supply dependence.
- Freeze-dried:Alternative lyophilization protocols yield porous sponges for wound bed preparation.
- Spray-dried:Rapid drying produces fine particulates for reconstitutable powder formulations.
- Soluble:pH-adjusted solutions enable direct injection or coating applications without reconstitution steps.
Lyophilized formats dominate implantable applications. Crosslinked variants gain share in barrier films.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bavaria-centered German surgical device cluster channels substantial procurement volumes through established tannery networks with multi-decade herd documentation. FDA and EMA traceability mandates concentrate supply relationships among incumbents with validated closed-herd sourcing across three continents.
United States
Academic medical centers in Boston and the Research Triangle absorb expanding volumes of electrospun nanofiber matrices for autologous chondrocyte expansion. FDA 21 CFR Part 1271 xenotransplantation regulations compress supplier qualification timelines while regenerative medicine protocols pull volume toward validated collagen matrices. The Greater Minneapolis surgical device corridor anchors hemostatic agent manufacturing with integrated collagen biomaterial supply chains.
Germany
Hospital systems in Bavaria and Baden-Württemberg standardize collagen dressing protocols for chronic ulcer management, creating pull-through demand for pharmaceutical-grade extracellular matrices. EMA CHMP BSE risk material guidance validates European tannery networks with multi-decade herd documentation. The Stuttgart surgical instrument cluster integrates collagen biomaterials into standard care pathways for orthopedic reconstruction.
Japan
Metropolitan Tokyo and Osaka medical centers drive specification evolution for three-dimensional tissue scaffolds in cartilage repair applications. PMDA guidance on xenogeneic material safety tightens traceability requirements for sourced tissues. The Kobe biomedical manufacturing corridor concentrates electrospun collagen film production for surgical barrier applications with tunable degradation profiles.
India
Regenerative medicine centers in Maharashtra and Karnataka seek domestic collagen biomaterial manufacturing to reduce import dependence for autologous cell therapy platforms. CDSCO medical device rules and production-linked incentive schemes for pharmaceuticals create openings for localized supply chain development. The Hyderabad-Genome Valley cluster attracts contract manufacturing investments for peptide-grade collagen fractions.
Switzerland
Orthopedic and dental implant manufacturers in the Basel-Zurich corridor consolidate purchases around suppliers with multi-jurisdiction documentation capabilities. Swissmedic requirements for medical devices utilizing animal tissues specify viral inactivation validation protocols. The Lake Geneva biotech cluster advances collagen-based osteoconductive carriers for bone regeneration applications.
Global Bovine-Based Collagen for Biomedical Applications Market Competitive Landscape
Global majors compete with regional champions across supply chain documentation and enzymatic processing sophistication. The vendor base stratifies between century-established gelatin processors with tannery network control and specialized biomedical-grade purifiers with cleanroom infrastructure. Three archetypes dominate: integrated abattoir-to-implant operators, merchant collagen refiners serving device sponsors, and film extrusion specialists controlling barrier application formats. Capacity expansion and captive sourcing relationships constitute the dominant competitive moves as traceability requirements raise barriers to merchant supply.
Among European heritage processors, Gelita AG and Rousselot occupy positions anchored in century-long gelatin processing legacies with validated raw material security. Medtronic exemplifies the integrated device sponsor archetype through direct abattoir partnerships that bypass merchant intermediaries. These three entities represent distinct strategic postures: heritage processor, merchant refiner, and captive integrator.
| Leading Market Players |
|---|
| Collagen Solutions Plc |
| Collagen Matrix, Inc. |
| BBI Solutions |
| botiss biomaterials GmbH |
| Symatese |
| Medtronic |
| Viscofan BioEngineering |
| Gelita AG |
| Rousselot |
| Others |
Supply & Pricing Matrix
Family-owned European gelatin processors with century-long tannery network control anchor supply discipline through multi-decade herd documentation investments that insulate pricing power from merchant-market volatility. Their private-capital-backed competitors struggle to replicate closed-herd traceability without comparable sunk costs, compressing margin recovery timelines for new capacity entrants.
Pricing Analysis
Input-cost pass-through from bovine hide and tendon procurement runs through contract-based long-term offtake structures that buffer spot-market swings. Pricing stratifies across pharmaceutical-grade peptide fractions, standard gelatin volumes, and economy hydrolysate tiers based on purity certification and enzymatic processing depth. Cost compression in standard gelatin is intensifying because recombinant human collagen platforms are compressing wound closure benchmarks. Medical device makers show highest price sensitivity due to value-analysis procurement frameworks, while regenerative medicine centers absorb premium peptide pricing for triple-helix integrity specifications.
Supply Chain Analysis
Logistics and freight costs for temperature-controlled collagen transport from abattoir to processing facility concentrate procurement geography around Germany, the United States, and Brazil. Raw material security draws from closed-herd bovine dermis, pepsin enzyme stocks, and sterile filtration infrastructure. Single-source vulnerability in European tannery networks with validated EMA documentation poses structural risk if geographic risk reclassification occurs. Distribution runs through direct manufacturer agreements with integrated delivery networks displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO production-linked incentive schemes in India offer cost structures one-third below EMA-validated European processing, justifying capital redeployment toward domestic supply chain localization.
For Market Incumbents: Anchor procurement relationships through captive abattoir partnerships in North America that bypass merchant intermediaries and defend against recombinant collagen substitution. Extend terminal lyophilization capacity in Bavaria and Minnesota corridors to consolidate sterile filtration infrastructure among qualified incumbents. Certification investment in multi-jurisdiction traceability documentation insulates against EMA territory risk reclassification exposure. For New Entrants and Emerging Players: Begin with peptide-grade fraction production for targeted drug delivery applications where molecular weight specificity commands premium positioning beyond commoditized gelatin volumes. Maharashtra and Karnataka regenerative medicine centers in India represent the most penetrable demand pool given import dependence and CDSCO localization incentives. Hospital system partnership models with embedded clinical training components differentiate against product-only incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale merchant collagen refiners lacking captive sourcing but possessing enzymatic optimization expertise and cleanroom infrastructure. Long-term viability hinges on backward integration into validated tannery networks or forward integration into device sponsor relationships. The signal to watch is EMA geographic risk tier updates that would force immediate supply chain restructuring and create distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Abattoir Partnership | Medtronic's direct sourcing relationships bypass merchant intermediaries and secure closed-herd documentation. |
| Peptide-Grade Capacity Expansion | Hyderabad-Genome Valley investments target molecular weight-specific fractions for controlled-release matrices. |
| Multi-Jurisdiction Certification | Gelita AG's EMA-USDA-PMDA traceability harmonization insulates against geographic risk reclassification. |
| Electrospinning Technology Integration | Viscofan BioEngineering's nanofiber barrier films enable tunable degradation profiles for surgical applications. |
| Regenerative Center Direct Contracting | German integrated delivery networks displace distributor mediation with manufacturer agreements for wound care standardization. |
Research Methodology
Bottom-up wound care and orthopedic modeling reconciled against top-down tannery network capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs directors at device sponsors combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, hospital procurement records, and ISO certification registries. Triangulation across these sources ensures demand-side consumption estimates align with supply-side production capacity.
Input-output matrices map bovine hide and tendon flows through enzymatic digestion, sterile filtration, and terminal lyophilization stages to finished collagen product categories across the analysis window. Segmentation dimensions include product type, application intensity, end-user procurement sophistication, and terminal form processing technology. CAGRs derive from regression against historical volume trajectories and forward projection of regenerative medicine protocol adoption rates, with explicit modeling of EMA geographic risk classification scenarios.
Several conditions sit outside the modeled scope, including recombinant human collagen platform cost curves beyond wound closure applications and sovereign trade policy shifts affecting bovine tissue cross-border movement. Forecasts reflect documented assumptions regarding closed-herd validation timelines and enzymatic processing yield rates. A model refresh is warranted upon material change in EMA transmissible spongiform encephalopathy territory risk classifications or FDA xenotransplantation traceability mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Tissue Extraction System Market