
 Gene Vector Market | 2026-2036
Gene Vector Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Vector Market Foresight
Market Context
Synthetic plasmid DNA is recalibrating cost structures across viral vector production by reducing dependence on animal-derived reagents. Lonza leverages integrated manufacturing platforms spanning plasmid supply through fill-finish to capture margin across the value chain. Thermo Fisher Scientific anchors its position through analytical testing and cell culture media portfolios that vector producers require at scale. Oxford Biomedica specializes in lentiviral vector expertise tied to autologous cell therapy partnerships.
Technical Definition and Segment Structure
Gene vectors are engineered delivery vehicles—viral, non-viral, or synthetic—designed to transport genetic material into target cells, with viral variants typically constructed from modified adenovirus, adeno-associated virus (AAV), lentivirus, or retrovirus backbones carrying payloads up to approximately 4.7–8.0 kilobases depending on serotype. AAV vectors dominate clinical pipelines for in vivo gene therapy due to their low immunogenicity profile and established manufacturing protocols, while lentiviral vectors command premium pricing in ex vivo applications such as CAR-T cell engineering where stable genomic integration remains essential. Pharmaceutical companies represent the fastest-expanding end-user category as biotech firms outsource vector manufacturing to CDMOs rather than building captive GMP facilities.
Regulatory Framework and Outlook
FDA's Office of Tissues and Advanced Therapies, EMA's Committee for Advanced Therapies, and ISO 21973 standards collectively govern vector quality attributes, potency assays, and lot-release criteria that determine market access timelines. These frameworks elevate compliance costs for entrants while rewarding manufacturers with established regulatory dossiers and validated analytical platforms. Stakeholders must monitor evolving guidance on replication-competent virus testing and empty capsid quantification as agencies tighten specifications for commercial-grade material.
Market Dynamics
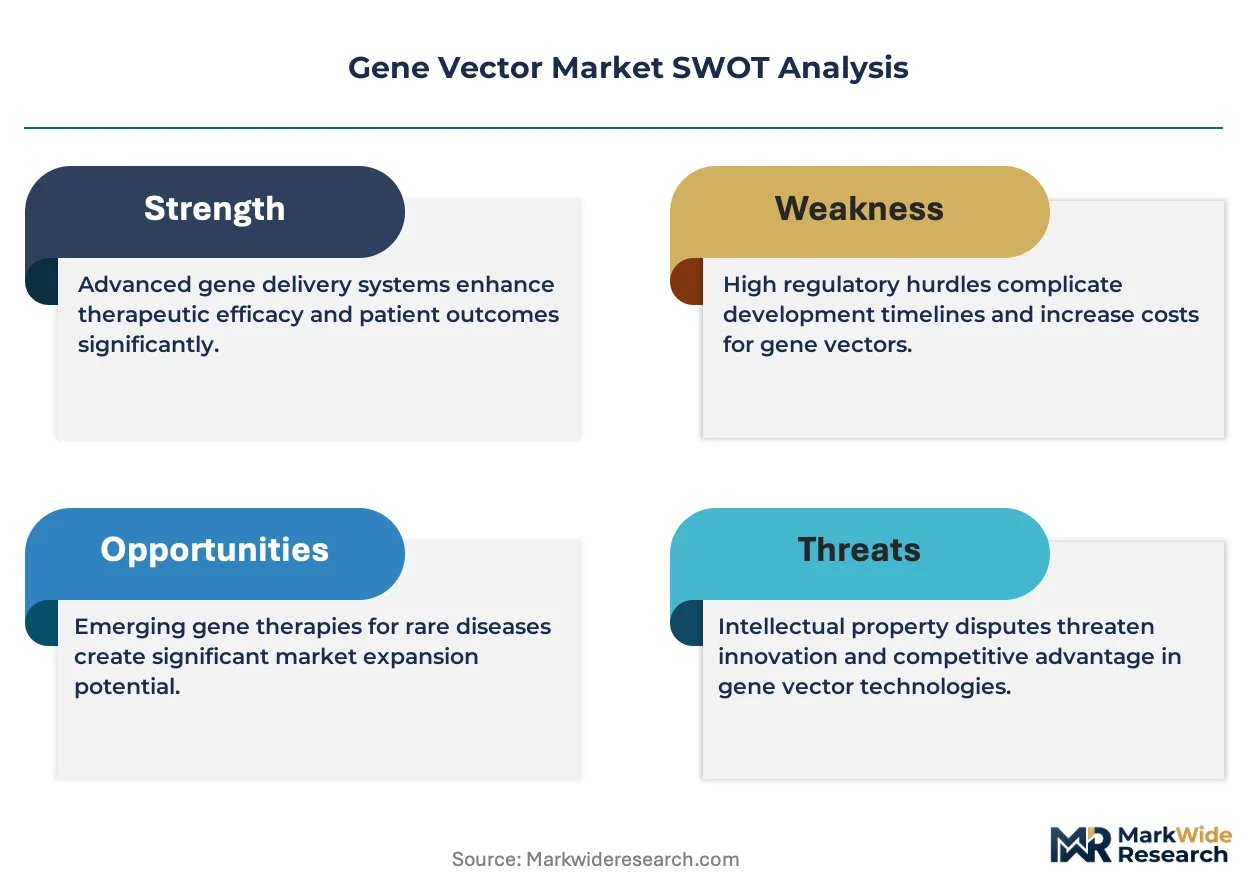
Manufacturing scale-up bottlenecks for clinical-grade viral vectors are compressing development timelines and forcing pharmaceutical sponsors into long-term CDMO partnerships before Phase II data readouts.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed review timelines for gene therapies are pulling forward vector manufacturing commitments from sponsors who must secure GMP capacity years before commercial launch.
- Allogeneic Cell Therapy Pipelines:Off-the-shelf CAR-T and CAR-NK programs are multiplying demand for lentiviral and retroviral vectors that enable stable transgene integration without patient-specific manufacturing.
- Plasmid DNA Synthesis Automation:Synthetic biology platforms are reducing batch-to-batch variability in transfection-grade plasmid supply, de-risking upstream viral vector production.
Market Restraints
- Serotype-Specific Manufacturing Lock-In:AAV2 and AAV9 production lines require dedicated bioreactor suites and purification trains, trapping capital in single-product configurations.
- Fetal Bovine Serum Supply Concentration:Cell culture media for vector production depends on geographically concentrated abattoir sourcing, exposing manufacturers to input volatility and ethical sourcing audits.
- Empty Capsid Burden:Current purification technologies cannot fully eliminate capsid shells lacking therapeutic payload, forcing sponsors to overproduce and absorb yield losses.
Strategic Opportunities
- Japan's Regenerative Medicine Framework:PMDA's conditional approval pathway for gene therapies is attracting vector manufacturers to establish local GMP facilities ahead of commercial launches.
- Non-Viral Vector Platforms:Lipid nanoparticles and polymer-based delivery systems are opening in vivo applications previously restricted by viral payload size and immunogenicity constraints.
- Point-of-Care Vector Manufacturing:Decentralized production models for autologous therapies are creating demand for closed-system bioreactors that CDMOs can deploy at hospital sites.
Industry Challenges
- Qualified Personnel Scarcity:GMP vector manufacturing requires hybrid expertise in cell culture, virology, and regulatory science that training programs have not scaled to match pipeline growth.
- Analytical Method Validation Timelines:Potency assays for novel serotypes require 12-18 month qualification cycles that delay IND filings and compress program schedules.
- Cross-Contamination Controls:Multi-product facilities face escalating cleaning validation requirements for replication-competent virus testing that extend campaign changeover periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Vector Market |
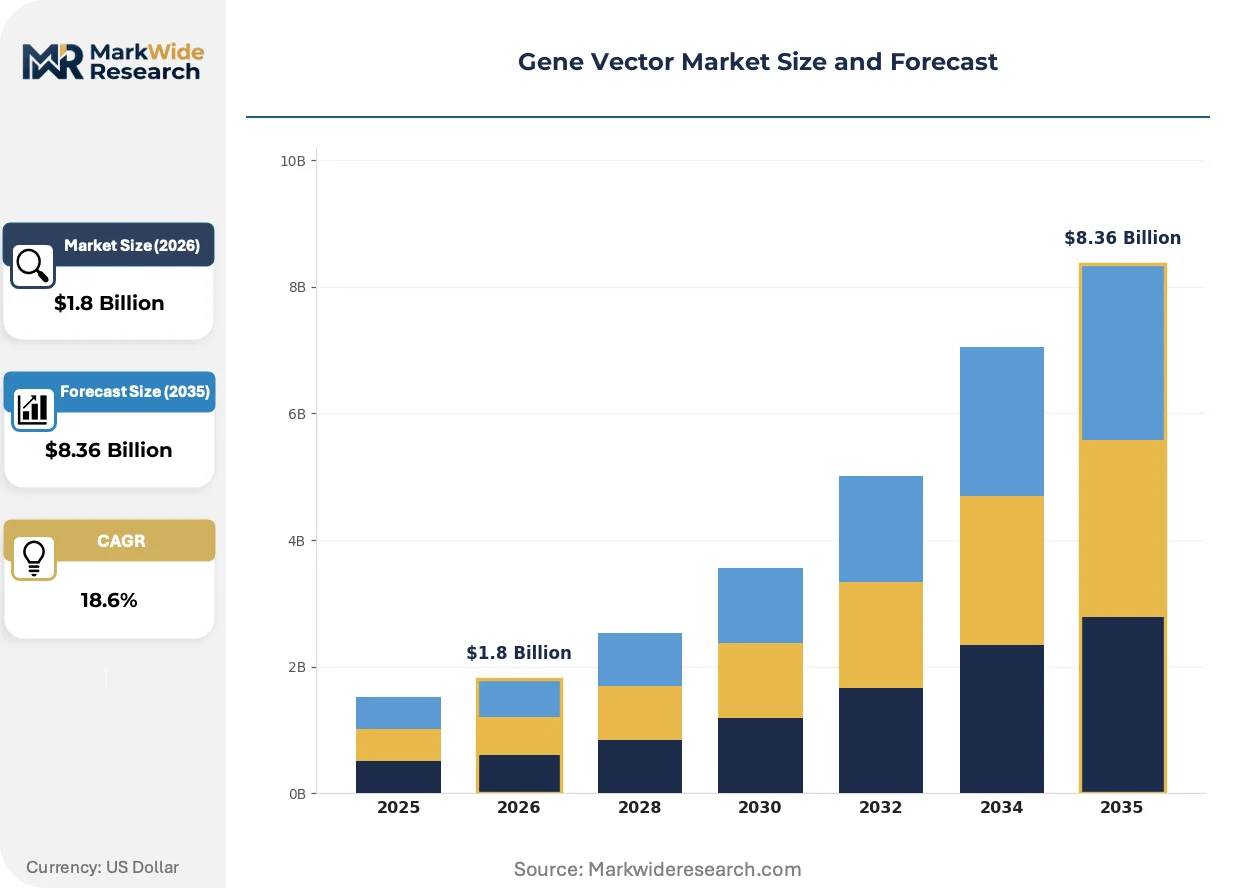
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adenoviral Vectors, Lentiviral Vectors, AAV Vectors, Retroviral Vectors Application: Gene Therapy, Cancer Treatment, Vaccine Development, Genetic Disorders Delivery Method: In Vivo, Ex Vivo, Intravenous, Local Injection End User: Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Academic Laboratories |
| Companies Covered | Charles River Laboratories, Lonza, Thermo Fisher Scientific, Catalent, Aldevron, Merck KGaA, Oxford Biomedica, FUJIFILM Diosynth Biotechnologies, VGXI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Vector Market Shifts & Advancements
Suspension-based manufacturing platforms are displacing adherent cell culture across viral vector production, enabling single-use bioreactor scale-up that reduces facility footprint and labor intensity.
Suspension HEK293 and HEK293T cell lines are expanding into AAV and lentiviral production workflows previously dominated by roller bottle and Cell Factory systems. CDMOs are retrofitting mammalian cell culture suites originally built for monoclonal antibodies to accommodate vector bioprocessing with minimal capital reconfiguration. This platform shift is expanding into gene therapy pipelines by compressing per-batch manufacturing costs and enabling 2000-liter scale production runs.
EMA's Committee for Advanced Therapies has tightened guidance on replication-competent lentivirus detection and adventitious agent testing for ex vivo-modified cell therapies. Vector manufacturers must now implement redundant nucleic acid and infectivity assays that extend lot release timelines by four to six weeks. European sponsors are responding by integrating quality control functions earlier into process development to prevent late-stage analytical failures.
Pharmaceutical sponsors are consolidating vector procurement under single-source CDMO agreements spanning plasmid supply through fill-finish, displacing fragmented multi-vendor sourcing. This concentration is compressing supplier qualification overhead and locking in capacity allocation through milestone-based payment structures. The shift is most visible in United States-based gene therapy programs where NIH funding requirements favor established GMP track records over cost minimization.
Gene Vector Market Segmentation
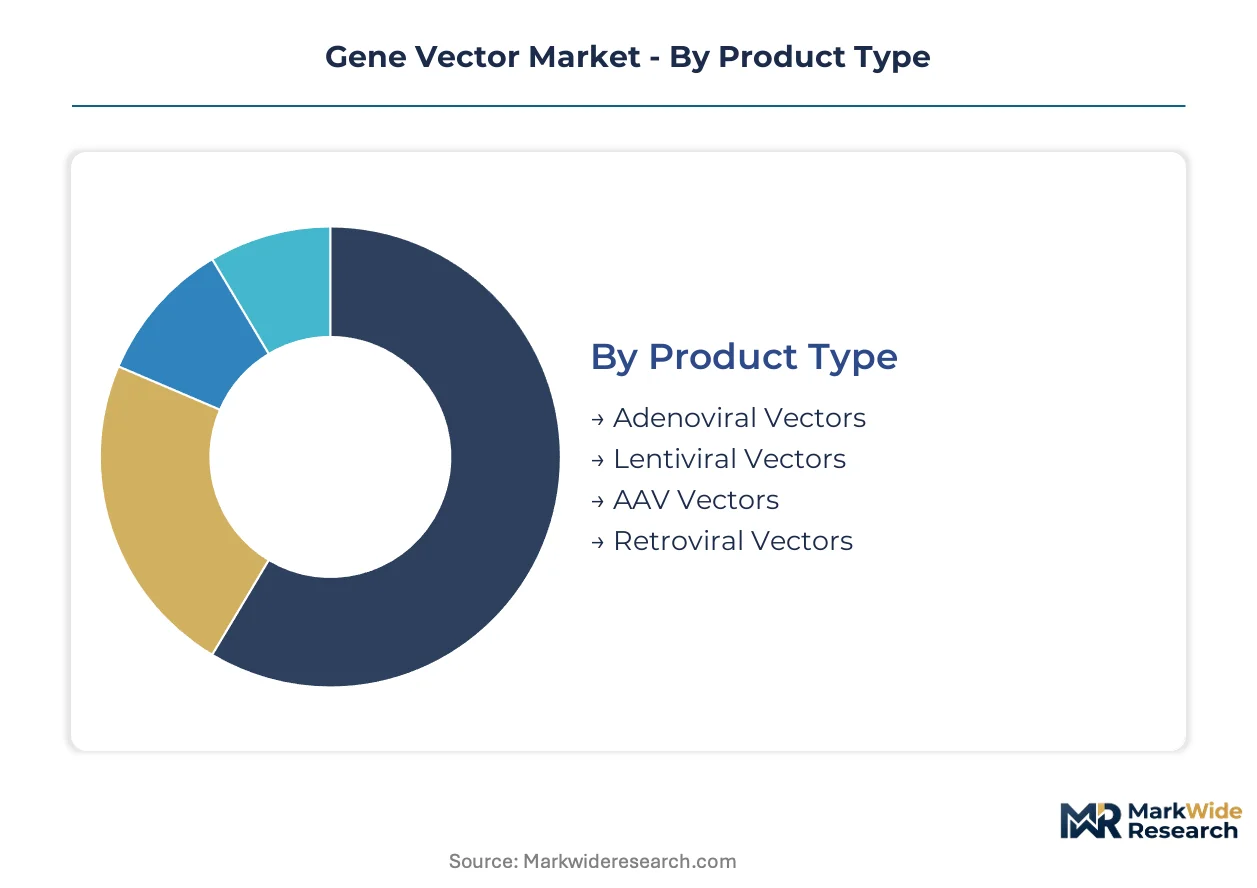
Gene vector segmentation reveals distinct capital allocation patterns across manufacturing modalities. Pharmaceutical sponsors structure procurement around payload capacity, immunogenicity profiles, and regulatory validation requirements that vary sharply by vector class.
Product Type:
Capital intensity escalates with serotype specificity and suspension-adaptation requirements, trapping investment in purpose-built bioreactor configurations.
- AAV Vectors:Engineered from adeno-associated virus backbones with payload limits near 4.7 kilobases. Empty capsid ratios and serotype-specific purification trains dominate cost structures in United States-based gene therapy programs targeting liver and retinal indications.
- Lentiviral Vectors:Derived from HIV-1 frameworks enabling stable chromosomal integration. CDMOs command premium pricing for GMP lentiviral supply to CAR-T developers in ex vivo cell therapy workflows where genomic permanence remains non-negotiable.
- Adenoviral Vectors:High-capacity payloads exceeding 8.0 kilobases suit vaccine applications; transient expression limits oncology adoption.
- Retroviral Vectors:Gamma-retroviral alternatives persist in hematopoietic stem cell gene therapy despite insertional mutagenesis concerns.
AAV vectors absorb the bulk of installed capacity; lentiviral vectors are expanding most quickly.
Application:
Clinical-stage pipelines concentrate investment in modalities with accelerated approval precedents and reimbursable endpoints.
- Gene Therapy:In vivo and ex vivo approaches for monogenic diseases drive vector demand. FDA breakthrough therapy designations for sickle cell and spinal muscular atrophy programs are pulling forward manufacturing commitments before Phase II readouts.
- Cancer Treatment:CAR-T and tumor-infiltrating lymphocyte engineering requires lentiviral transduction at scale. Allogeneic off-the-shelf programs are multiplying vector orders beyond autologous patient-specific manufacturing.
- Vaccine Development:Adenoviral platforms for infectious disease prophylaxis saw surge capacity during recent pandemic preparedness contracting.
- Genetic Disorders:Rare disease indications justify premium pricing but fragment demand across small patient populations.
Gene therapy commands the dominant share of GMP capacity allocation; cancer treatment applications are climbing the fastest.
Delivery Method:
Route selection determines analytical burden and regulatory pathway complexity for vector release.
- Ex Vivo:Cell modification outside the patient enables potency verification before infusion. EMA's Committee for Advanced Therapies mandates extended adventitious agent testing for ex vivo-modified products, extending European lot release timelines.
- In Vivo:Direct administration demands rigorous biodistribution and shedding studies. Systemic delivery via intravenous routes requires higher vector doses than local injection, intensifying manufacturing scale requirements.
- Intravenous:Systemic circulation exposes vectors to neutralizing antibodies, necessitating higher dosing.
- Local Injection:Ocular, intrathecal, and intramuscular routes reduce systemic exposure and required payload mass.
Ex vivo methods lock in the majority of qualified analytical capacity; in vivo approaches are gaining share fastest.
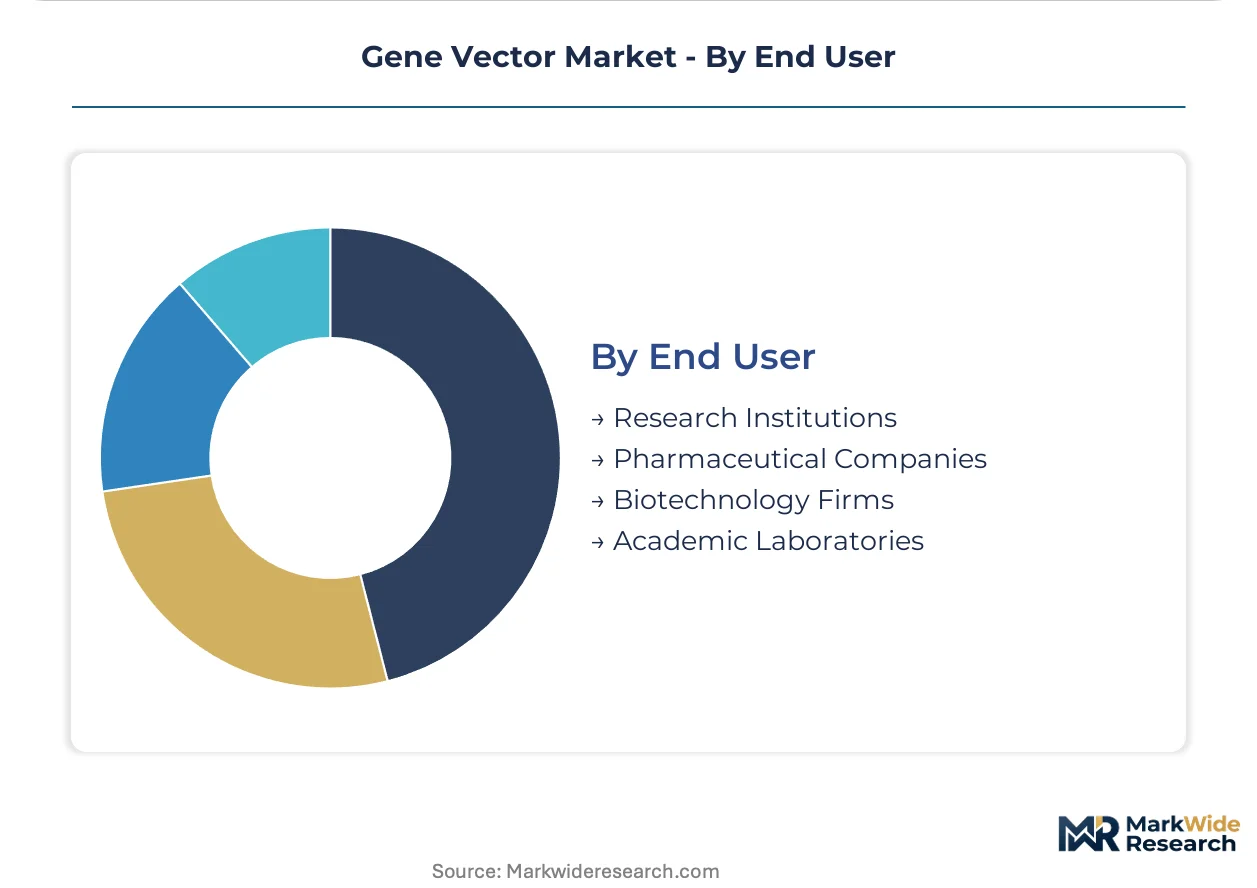
End User:
Procurement sophistication varies with internal manufacturing capabilities and regulatory filing experience.
- Pharmaceutical Companies:Large sponsors are consolidating vector procurement under multi-year CDMO agreements spanning plasmid supply through fill-finish. Milestone-based payment structures lock in capacity years ahead of anticipated commercial launches.
- Biotechnology Firms:Venture-backed developers without captive GMP facilities represent the fastest-expanding demand category. NIH funding requirements favor established CDMO track records over cost minimization in United States programs.
- Research Institutions:Preclinical vector supply relies on academic core facilities and non-GMP contract providers.
- Academic Laboratories:Small-scale transfection-grade material supports exploratory discovery without regulatory filing intent.
Pharmaceutical companies anchor the largest contract value; biotechnology firms are expanding order volumes most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and the Basel biotech corridor in Switzerland concentrate vector manufacturing capacity through R&D tax credits and specialized workforce pipelines.
United States
FDA's Office of Tissues and Advanced Therapies processes breakthrough therapy designations for sickle cell and retinal gene therapies, pulling manufacturing commitments forward. NIH funding through the National Heart, Lung, and Blood Institute supports plasmid supply chain scale-up. Boston and San Francisco anchor CDMO clusters where Thermo Fisher Scientific and Aldevron operate integrated manufacturing platforms.
Germany
EMA's Committee for Advanced Therapies enforces replication-competent virus testing standards that extend lot release timelines for ex vivo therapies. The country's national pharmaceutical regulator mandates redundant nucleic acid assays for lentiviral vectors. Heidelberg and Cologne host specialized facilities where Merck KGaA leverages cell culture media portfolios for vector producers.
Switzerland
Swissmedic's alignment with EMA standards accelerates parallel submissions for gene therapies targeting European and Swiss markets simultaneously. Federal innovation grants support suspension-adapted cell line development. The Basel region concentrates viral vector expertise through Lonza's integrated manufacturing platforms spanning plasmid supply through fill-finish.
Japan
PMDA's conditional approval pathway for regenerative medicine products attracts vector manufacturers to establish local GMP facilities ahead of commercial launches. METI funding targets point-of-care manufacturing systems for autologous therapies. The Kanto region around Tokyo hosts CDMO partnerships where Oxford Biomedica extends lentiviral expertise into Asian markets.
United Kingdom
The Medicines and Healthcare products Regulatory Agency maintains post-Brexit alignment with EMA quality standards for advanced therapy medicinal products. NHS England's specialized commissioning framework creates reimbursement certainty for gene therapies. Oxford and Cambridge anchor research clusters where academic core facilities feed preclinical vector supply into commercial pipelines.
Gene Vector Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated CDMOs capturing multi-year agreements that span plasmid supply through fill-finish. The vendor base concentrates around three strategic archetypes: full-service CDMOs with regulatory dossiers, platform technology licensors with proprietary cell lines, and niche analytical service providers with validated potency assays. Capacity expansion and strategic partnerships dominate competitive moves as sponsors lock in GMP allocation before Phase II readouts.
Among integrated manufacturing specialists, Lonza, Thermo Fisher Scientific, and Oxford Biomedica exemplify distinct positioning archetypes. Lonza occupies the full-service CDMO tier with capabilities spanning plasmid synthesis through commercial fill-finish. Thermo Fisher Scientific anchors the analytical and cell culture supply tier through portfolios that vector producers require at manufacturing scale. Oxford Biomedica sits within the viral vector specialization tier, with expertise concentrated in lentiviral platforms for autologous cell therapy partnerships. These three represent how geographic clustering and capability depth determine procurement relationships with pharmaceutical sponsors.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Lonza |
| Thermo Fisher Scientific |
| Catalent |
| Aldevron |
| Merck KGaA |
| Oxford Biomedica |
| FUJIFILM Diosynth Biotechnologies |
| VGXI |
| Others |
Supply & Pricing Matrix
Fetal bovine serum and synthetic plasmid DNA cascade through tiered pricing structures as vector manufacturers calibrate procurement strategies between spot-market spot purchases and long-term offtake agreements with CDMOs.
Pricing Analysis
Short-lead-time premiums command substantial markups for GMP-grade lentiviral vectors needed within eight-week windows, while contracted sponsors securing multi-year capacity lock-ins negotiate standard-tier rates. Three-tier pricing structure across premium, standard, and economy levels separates emergency clinical supply from scheduled Phase III campaigns and preclinical research-grade material. Pricing pressure stems from serotype-specific manufacturing lock-in that traps capital in single-product bioreactor configurations. Biotechnology firms with NIH funding constraints exhibit highest price sensitivity; large pharmaceutical sponsors with milestone-based payment structures demonstrate lowest.
Supply Chain Analysis
Workforce scarcity in Massachusetts, North Carolina, and Switzerland constrains expansion timelines for suspension-adapted cell line facilities. Manufacturing gravity centers on the United States, Germany, and Japan, where GMP-qualified personnel pipelines feed CDMO clusters. Raw material dependencies encompass transfection-grade plasmid DNA, fetal bovine serum from geographically concentrated abattoir sourcing, and single-use bioreactor consumables. Single-source vulnerability in serotype-specific purification resin supply exposes campaigns to changeover delays. Distribution runs through integrated CDMO platforms spanning plasmid synthesis through fill-finish rather than fragmented multi-vendor sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene vector manufacturing is becoming a vertical-integration race as sponsors pursue captive plasmid supply to de-risk upstream bottlenecks and compress lot-release timelines.
For Market Incumbents: Acquire suspension-adapted cell line portfolios to secure differentiation against emerging platform technology licensors. CDMOs must defend against manufacturing scale-up bottlenecks by locking in multi-year pharmaceutical sponsor agreements before Phase II data readouts. Backward integration into synthetic plasmid DNA production reduces dependence on animal-derived reagent volatility. For New Entrants and Emerging Players: Academic laboratories and preclinical-stage biotechnology firms represent underserved buyers seeking non-GMP transfection-grade material with faster turnaround than established CDMOs offer. Japan's regenerative medicine framework and point-of-care manufacturing systems for autologous therapies present the most penetrable white-space targets. A go-to-market angle centered on closed-system bioreactor deployment at hospital sites bypasses incumbent capacity constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor niche analytical service providers with validated potency assays in the United States and European markets. Long-term viability across a ten-year horizon hinges on regulatory dossier depth and established GMP track records rather than manufacturing scale alone. The signal to watch is FDA guidance evolution on replication-competent virus testing and empty capsid quantification specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CDMOs retrofit mammalian cell culture suites originally built for monoclonal antibodies to accommodate vector bioprocessing. |
| Regulatory Approval Pathway | FDA's Office of Tissues and Advanced Therapies processes breakthrough therapy designations that pull manufacturing commitments forward. |
| Backward Integration | Synthetic biology platforms reduce batch-to-batch variability in transfection-grade plasmid supply, de-risking upstream production. |
| Licensing Agreement | Platform technology licensors with proprietary HEK293 and HEK293T cell lines capture margin through royalty structures. |
| Geographic Expansion | PMDA's conditional approval pathway attracts vector manufacturers to establish local GMP facilities in Japan's Kanto region. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with vector manufacturing executives, regulatory affairs leads at CDMOs, pharmaceutical procurement managers, and academic core facility directors provided operational validation. FDA submissions, EMA Committee for Advanced Therapies opinions, ClinicalTrials.gov records, and NIH funding databases supplied quantitative benchmarks. Bottom-up capacity modeling and top-down sponsor pipeline analysis were triangulated against plasmid supply chain disclosures.
Segment-level granularity modeled vector class, application indication, delivery method, and end-user procurement sophistication across the projection horizon. CAGRs were derived from sponsor pipeline advancement rates and manufacturing capacity expansion schedules. Treatment line positioning, regional regulatory cluster alignment, and serotype-specific potency assay requirements informed analytical framework construction throughout the forecast period.
Revisions become necessary when FDA guidance on replication-competent virus testing tightens, EMA lot-release timeline extensions escalate, or synthetic plasmid DNA supply disruptions materialize. Forecasts reflect assumptions about regulatory pathway stability and CDMO capacity utilization rates. Material deviation in agency guidance timelines or workforce availability in key manufacturing clusters warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Cell and Gene Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market