
 Animal Stem Cell Therapy Market | 2026-2036
Animal Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Stem Cell Therapy Market Analysis
EMA's evolving guidance on veterinary advanced therapy medicinal products is expanding compliance costs for new entrants across European markets. Boehringer Ingelheim International GmbH leverages its pan-European distribution network to sustain regulatory dossiers in multiple member states. VetStem Inc. anchors the North American companion animal segment with proprietary adipose-derived processing protocols. Magellan Stem Cells competes through specialized equine applications that differentiate its service portfolio from canine-centric rivals.
Animal stem cell therapy deploys autologous or allogeneic progenitor cells—typically mesenchymal populations harvested from adipose tissue or bone marrow—cultured under GMP conditions and delivered via intra-articular or intravenous routes to modulate inflammation and regenerate damaged tissue in veterinary patients. Mesenchymal stem cells dominate current revenue pools due to established extraction protocols and broad immunomodulatory efficacy across orthopedic and musculoskeletal indications. Hematopoietic stem cells occupy a narrower niche centered on immune-mediated conditions, while induced pluripotent stem cells remain preclinical with manufacturing complexity constraining near-term commercial viability. Intra-articular injection leads delivery method adoption for joint disorders, whereas intravenous administration extends utility to systemic autoimmune and neurological presentations where tissue targeting proves less critical.
The FDA Center for Veterinary Medicine enforces investigational new animal drug requirements for cell-based products, while USDA's Center for Veterinary Biologics governs autologous therapies within a distinct regulatory track that shapes product classification and market access timelines. ISO standards for cell processing and characterization provide supplementary quality benchmarks that multinational suppliers must satisfy for contract manufacturing partnerships. Stakeholders should monitor how FDA-USDA jurisdictional clarifications and emerging EMA centralized assessment pathways for veterinary ATMPs reshape competitive entry costs and partnership structures across key markets.
Market Dynamics
Veterinary stem cell therapy markets face intensifying regulatory bifurcation between FDA drug pathways and USDA biologics tracks, forcing processors to maintain dual compliance architectures while scaling adipose-derived mesenchymal cell production for canine osteoarthritis.
Growth Catalysts
- Pet insurance expansion:Reimbursement coverage for regenerative procedures in the United States now extends to intra-articular stem cell injections, reducing out-of-pocket burdens for companion animal owners.
- EMA veterinary ATMP pathways:Centralized assessment procedures for advanced therapy medicinal products are harmonizing multi-state market entry across European Union member states.
- Adipose-derived processing automation:Closed-system bioreactors are cutting culture contamination rates and shortening GMP-compliant manufacturing cycles for autologous therapies.
Market Restraints
- Biologics classification uncertainty:FDA-USDA jurisdictional overlap creates product reclassification risk that extends approval timelines and raises legal compliance costs.
- Donor tissue variability:Adipose harvest quality fluctuates with patient age and metabolic condition, introducing batch-to-batch potency inconsistency that complicates dosing standardization.
- Allogeneic cell banking infrastructure:Cryopreservation facilities concentrate in the United States and Germany, creating geographic supply vulnerability for Asia-Pacific veterinary clinics.
Strategic Opportunities
- Equine sports medicine extension:Tendon and ligament applications in racing and performance horses remain underpenetrated relative to canine orthopedics, offering service differentiation for specialized processors.
- Intravenous neurological protocols:Systemic administration for feline chronic kidney disease and canine cognitive dysfunction represents an emerging application with limited commercial competition.
- ISO 20387 biobanking standards:Accreditation compliance creates partnership leverage for contract manufacturers seeking multinational veterinary pharmaceutical alliances.
Industry Challenges
- Veterinary cell therapy technician training:Aseptic culture handling and GMP documentation skills remain scarce in clinical practice, limiting point-of-care processing scalability.
- Autologous-to-allogeneic manufacturing retooling:Shifting from patient-specific to donor-batch production requires cleanroom revalidation and donor screening protocol overhauls that strain capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Stem Cell Therapy Market |
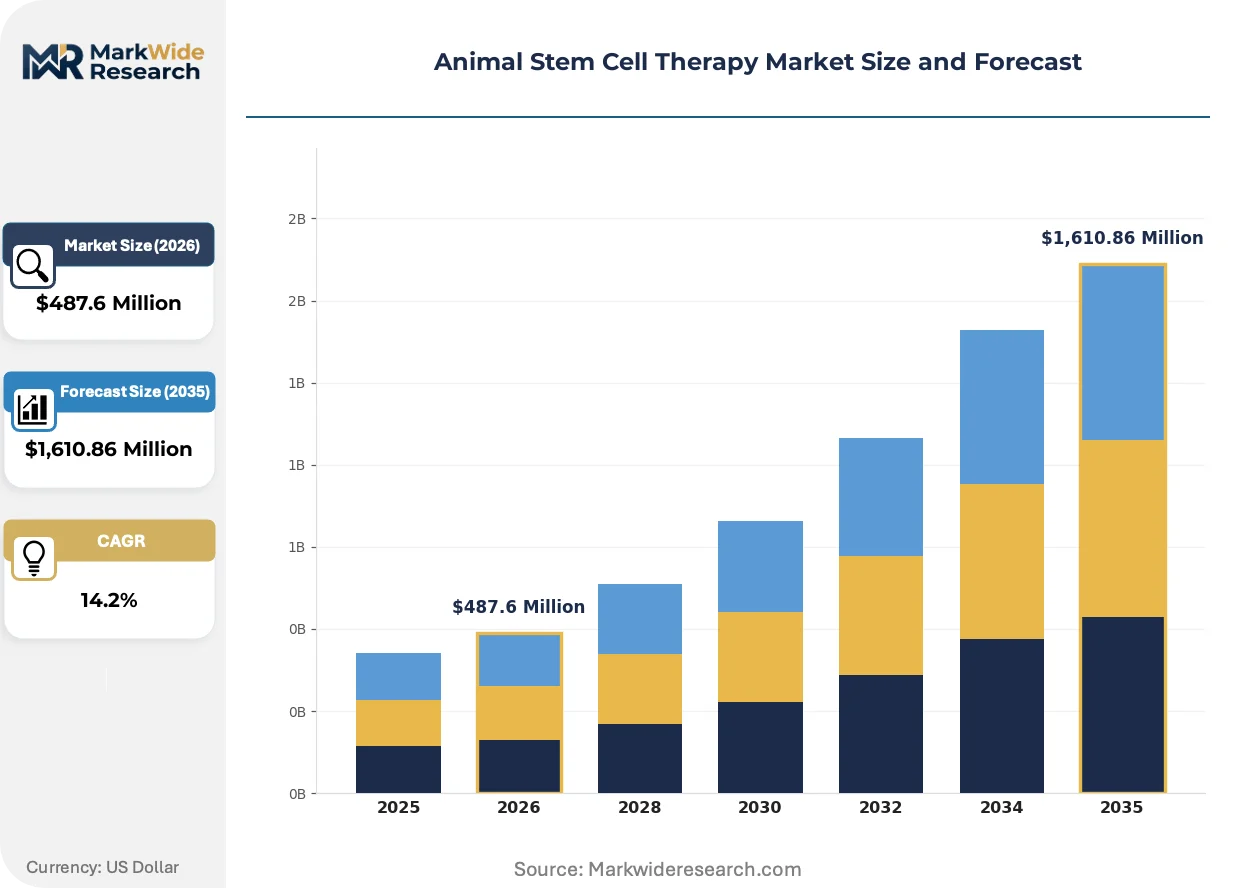
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesenchymal Stem Cells, Hematopoietic Stem Cells, Induced Pluripotent Stem Cells, Embryonic Stem Cells Application: Orthopedic Disorders, Musculoskeletal Injuries, Neurological Disorders, Autoimmune Diseases End User: Veterinary Clinics, Research Laboratories, Animal Hospitals, Universities Delivery Method: Intra-articular Injection, Intravenous Injection, Subcutaneous Injection, Topical Administration |
| Companies Covered | Boehringer Ingelheim International GmbH, VetStem Inc., Magellan Stem Cells, Cell Therapy Sciences, Aratana Therapeutics Inc., MediVet Biologics LLC, Regeneus Ltd., Animal Cell Therapies Inc., U.S. Stem Cell Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Stem Cell Therapy Market Emerging Trajectories
Processing standardization and regulatory clarity are converging to reshape how veterinary stem cell therapies move from boutique services to scalable medical offerings. Three developments are actively restructuring competitive positioning.
Closed-system automated bioreactor technology is consolidating adipose-derived mesenchymal stem cell expansion workflows. Veterinary contract manufacturers in the United States and Germany are adopting single-use perfusion systems that eliminate open-handling contamination risks. This consolidation is compressing the viable supplier base toward processors with capital-intensive GMP infrastructure.
REACH chemical safety frameworks in Europe are extending to cell culture media components and cryopreservation reagents, forcing reformulation of dimethyl sulfoxide-based freezing solutions. Suppliers must now submit toxicity dossiers for ancillary materials previously treated as device accessories. Small-scale veterinary processors without regulatory affairs capacity are outsourcing to contract development organizations.
Direct-to-clinic cryogenic logistics networks are displacing traditional distributor intermediaries in companion animal stem cell delivery. Cold-chain specialists now contract directly with veterinary hospital systems, bypassing regional animal health distributors. This channel compression is most visible in metropolitan United States markets where specialty and emergency hospitals concentrate procurement volume.
Animal Stem Cell Therapy Market Segmentation
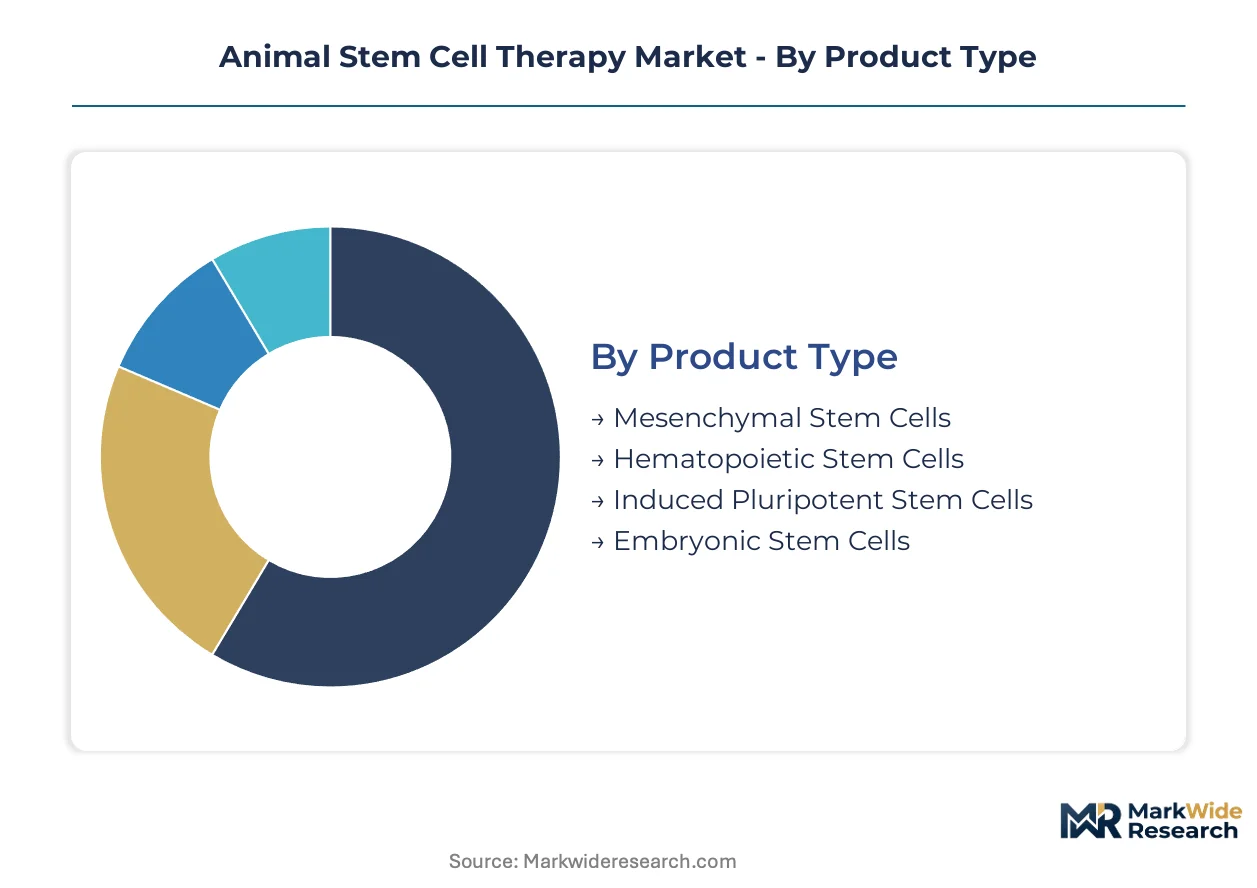
Stem cell therapy markets fragment across four axes that determine manufacturing scale, regulatory pathway, and reimbursement eligibility. Cell source dictates GMP complexity. Delivery route shapes clinic workflow and patient candidacy. Understanding these intersections reveals where capital deployment generates sustainable returns versus commodity exposure.
Product Type:
Cell population characteristics determine extraction protocols, expansion timelines, and immunomodulatory potency in veterinary applications.
- Mesenchymal Stem Cells:These adipose-derived and bone marrow-sourced populations secrete anti-inflammatory cytokines and extracellular vesicles that modulate joint degeneration in canine osteoarthritis. Demand concentrates in United States veterinary clinics where pet insurance reimbursement for intra-articular injections has expanded coverage windows. FDA Center for Veterinary Medicine oversight of allogeneic MSC products is tightening donor screening and batch release testing.
- Hematopoietic Stem Cells:Bone marrow and peripheral blood progenitors reconstitute immune function in feline leukemia and canine lymphoma protocols. European academic veterinary centers in Germany and the Netherlands drive clinical adoption for immune-mediated hemolytic anemia where standard immunosuppression fails. EMA veterinary ATMP classification uncertainty prolongs multi-state commercialization timelines.
- Induced Pluripotent Stem Cells:Reprogrammed somatic cells with pluripotent capacity remain confined to preclinical toxicology and disease modeling in veterinary pharmaceutical pipelines.
- Embryonic Stem Cells:Blastocyst-derived populations face ethical procurement constraints and teratoma formation risks that limit commercial development outside research applications.
Mature deployment sits with Mesenchymal Stem Cells. Newer deployment is concentrated in Hematopoietic Stem Cells.
Application:
Clinical indication selection shapes cell dosing, route optimization, and outcome measurement frameworks.
- Orthopedic Disorders:Canine hip dysplasia and elbow osteoarthritis represent the revenue foundation, with intra-articular MSC injections reducing lameness scores in controlled trials. United States specialty veterinary hospitals in metropolitan markets capture the procedural volume as pet owners seek alternatives to total joint replacement.
- Neurological Disorders:Intravenous MSC protocols for feline cognitive dysfunction and canine degenerative myelopathy show preliminary efficacy in small cohort studies. Academic veterinary neurology centers in California and North Carolina are expanding compassionate use programs.
- Musculoskeletal Injuries:Tendon and ligament lesions in equine athletes drive autologous processing demand from racing stables and performance horse operations.
- Autoimmune Diseases:Systemic lupus erythematosus and immune-mediated polyarthritis in companion animals represent an emerging indication with limited commercial protocol standardization.
Volume concentration favors Orthopedic Disorders. Steepest expansion trajectory is emerging in Neurological Disorders.
End User:
Facility type determines processing location, regulatory jurisdiction, and procurement sophistication.
- Veterinary Clinics:Primary care and specialty practices represent the dominant commercial channel, with point-of-care adipose harvest and same-day processing workflows. United States multi-site hospital systems are centralizing cell processing to reduce per-procedure costs and standardize quality.
- Research Laboratories:Academic and contract research organizations conduct IND-enabling studies for novel cell sources and genetic modification approaches. NIH-funded veterinary schools in Wisconsin and Colorado anchor preclinical translation pipelines.
- Animal Hospitals:Emergency and referral centers with surgical capabilities manage complex cases requiring combined orthopedic intervention and cell therapy.
- Universities:Veterinary medical schools train residents in regenerative medicine techniques while maintaining institutional biobanking infrastructure for collaborative studies.
Procurement scale aggregates at Veterinary Clinics. Capability investment is accelerating at Research Laboratories.
Delivery Method:
Administration route dictates formulation requirements, tissue targeting precision, and adverse event profiles.
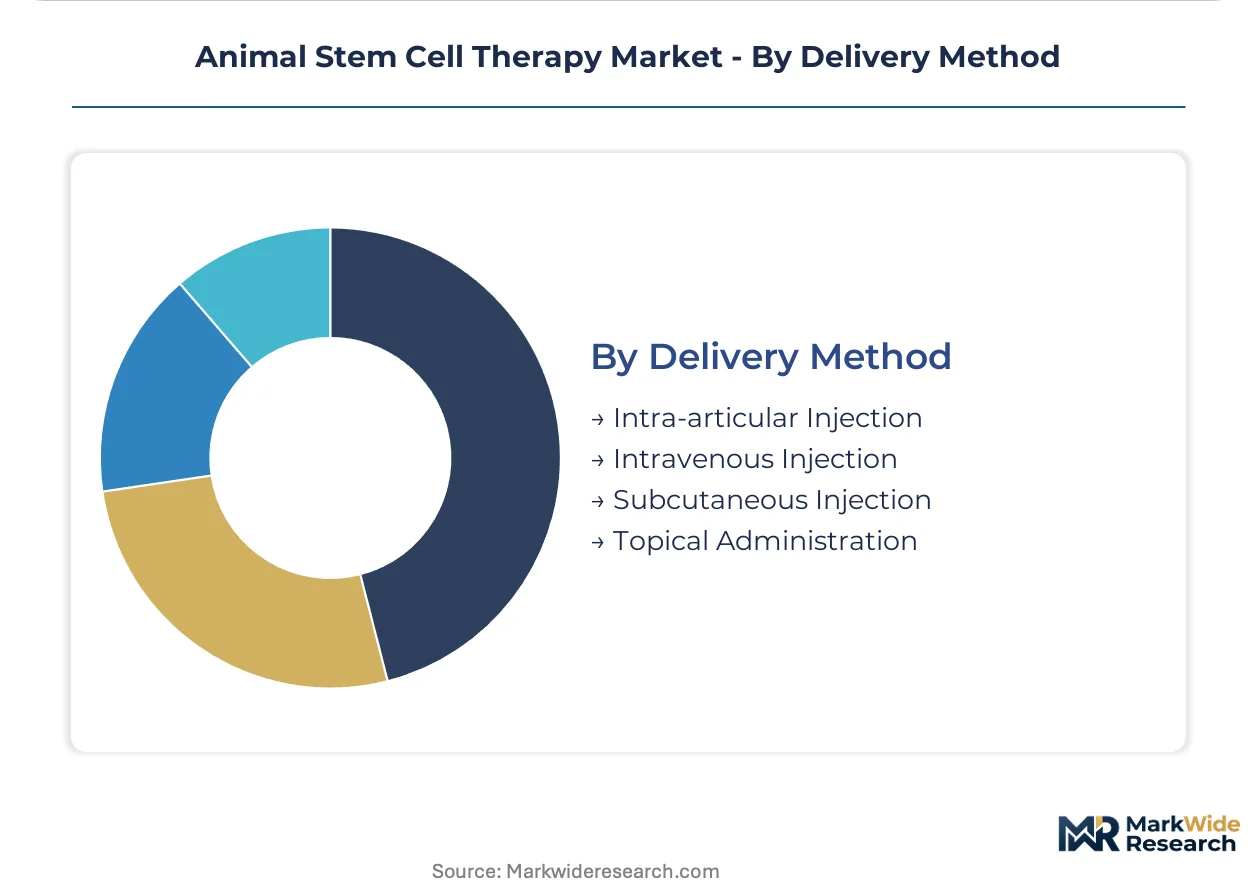
- Intra-articular Injection:Direct joint delivery maximizes local cell retention and paracrine signaling in synovial environments. Canine stifle and hip injections dominate United States procedural volumes, with ultrasound-guided techniques improving injection accuracy in obese patients.
- Intravenous Injection:Systemic distribution enables multi-joint or systemic autoimmune indications where localized delivery is impractical. Pulmonary first-pass filtration reduces circulating cell counts, requiring higher dosing than intra-articular routes.
- Subcutaneous Injection:Dermal and soft tissue applications for wound healing and localized immune modulation remain experimental with limited commercial protocol validation.
- Topical Administration:Cell-impregnated scaffolds and hydrogels for corneal and cutaneous lesions are restricted to academic investigational protocols.
Established utilization centers on Intra-articular Injection. Protocol development is gaining share fastest in Intravenous Injection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Singapore and Dubai are concentrating veterinary pharmaceutical distribution hubs that serve as staging points for stem cell therapy logistics across adjacent markets.
United States
Pet insurance carriers in California and New York now reimburse intra-articular stem cell procedures for canine osteoarthritis, expanding addressable demand beyond cash-pay clientele. FDA Center for Veterinary Medicine oversight of allogeneic products is tightening donor screening protocols and batch release documentation. The Research Triangle Park corridor in North Carolina anchors contract manufacturing infrastructure serving East Coast veterinary hospital systems.
Germany
Equine sports medicine clinics in Lower Saxony drive autologous processing demand from racing stables and performance horse operations. EMA veterinary advanced therapy medicinal product pathways are harmonizing multi-state market entry across EU member states. The Munich biotech cluster concentrates cryopreservation facilities and GMP-compliant cell banking infrastructure for Central European distribution.
United Kingdom
Specialty veterinary referral centers in London and Southeast England capture procedural volume for orthopedic and neurological stem cell applications. The Veterinary Medicines Directorate aligns with EMA centralized assessment procedures for novel cell-based therapies. The Cambridge-London life sciences corridor hosts preclinical translation pipelines linking academic veterinary schools to commercial processors.
Japan
Companion animal aging demographics in Tokyo and Osaka metropolitan areas expand candidacy pools for regenerative interventions in geriatric dogs and cats. PMDA consultation procedures for veterinary regenerative medical products provide regulatory clarity distinct from human pharmaceutical tracks. The Kansai region's industrial biotechnology base supplies closed-system bioreactor technology to domestic veterinary contract manufacturers.
Australia
Rural veterinary networks in New South Wales and Victoria are adopting point-of-care adipose processing workflows for livestock and companion animal applications. TGA oversight of veterinary biologicals distinguishes autologous therapies from regulated therapeutic goods in specific processing configurations. The Sydney biomedical precinct anchors import logistics for cryopreserved allogeneic cell products sourced from North American and European suppliers.
Animal Stem Cell Therapy Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the animal stem cell therapy market, creating a tiered structure where capital depth separates scalable processors from boutique service providers. Market concentration remains moderate, with no single entity commanding dominant share across all species and indication segments. Three strategic archetypes prevail: pharmaceutical conglomerates leveraging pan-regulatory dossier capabilities, dedicated veterinary cell therapy processors with proprietary extraction protocols, and contract research organizations pivoting into GMP manufacturing services. Competitive moves center on geographic licensing partnerships and backward integration into cryogenic logistics networks.
Among Germany-based pharmaceutical conglomerates, Boehringer Ingelheim International GmbH exemplifies the diversified archetype with established veterinary medicine infrastructure spanning multiple regulatory jurisdictions. VetStem Inc. and Magellan Stem Cells occupy positions within the specialized processor tier, with the former representing North American companion animal focus and the latter exemplifying equine-centric service differentiation. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| VetStem Inc. |
| Magellan Stem Cells |
| Cell Therapy Sciences |
| Aratana Therapeutics Inc. |
| MediVet Biologics LLC |
| Regeneus Ltd. |
| Animal Cell Therapies Inc. |
| U.S. Stem Cell Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up veterinary contract manufacturers in the United States and Germany are consolidating adipose-processing capacity, tightening pricing discipline across autologous stem cell services while squeezing margin-exposed regional processors. This ownership concentration feeds upstream into cryogenic logistics networks and downstream into multi-site veterinary hospital systems, creating bidirectional pricing leverage that rewards scaled GMP compliance.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent clinical cases from scheduled elective procedures, with same-day adipose harvest and processing commanding premium multiples over batch-scheduled allogeneic cell banking. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and donor screening protocol depth. Cost compression in the standard tier is intensifying because automated bioreactor adoption is lowering per-unit manufacturing overhead. Small independent veterinary clinics exhibit the highest price sensitivity, while multi-site specialty hospital systems leverage volume procurement for preferential contract terms.
Supply Chain Analysis
Single-source vulnerability sits with dimethyl sulfoxide cryopreservation reagent suppliers concentrated in Germany and the United States, exposing downstream processors to REACH toxicity dossier compliance disruptions. Raw material dependencies encompass adipose tissue collection kits, GMP-grade culture media, and liquid nitrogen logistics infrastructure. Tariff exposure on imported cell culture components from European Union member states is elevating landed costs for North American contract manufacturers. Distribution runs through direct-to-clinic cryogenic logistics networks that displace traditional veterinary pharmaceutical distributors in metropolitan United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal stem cell therapy markets function as a cost-of-compliance arena where FDA Center for Veterinary Medicine investigational new animal drug requirements and EMA veterinary ATMP pathways erect capital-intensive barriers that protect incumbent processors from undercapitalized entrants.
For Market Incumbents: Anticipate regulatory dossier harmonization demands across FDA and EMA jurisdictions by pre-positioning centralized assessment documentation for multi-state European entry. Backward integration into captive cryopreservation facilities in the Research Triangle Park corridor and Munich biotech cluster will defend margin position against emerging contract manufacturers with leaner overhead structures. ISO 20387 biobanking accreditation investment creates partnership leverage with multinational veterinary pharmaceutical alliances seeking outsourced GMP capacity. For New Entrants and Emerging Players: Launch via direct-to-clinic cryogenic logistics partnerships that bypass established distributor relationships in underserved Asia-Pacific metropolitan markets. Equine sports medicine applications in racing and performance horse operations represent the most penetrable white-space segment, with tendon and ligament protocols commanding service premiums absent from saturated canine orthopedics. Feline chronic kidney disease intravenous protocols offer a second penetration vector with limited commercial competition and compassionate use program entry pathways. For Investors and Strategic Acquirers: FDA-USDA jurisdictional clarification announcements are the leading indicator that regulatory arbitrage opportunities are closing, compressing valuation multiples for non-compliant processors. Acquisition target archetypes center on specialized equine processors with proprietary adipose-derived protocols and established racing stable relationships, or automated bioreactor technology developers with transferable closed-system IP. Long-term viability over the projection horizon rests on demonstrated GMP compliance infrastructure rather than clinical efficacy claims alone.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Closed-system bioreactor deployment in FDA-inspected facilities anchors multi-site veterinary hospital contracts. |
| Regulatory Approval Pathway | EMA centralized assessment dossiers unlock harmonized market entry across German and United Kingdom veterinary clinics. |
| Backward Integration | In-house cryopreservation infrastructure in Munich and North Carolina reduces third-party logistics dependency. |
| Licensing Agreement | Patent access for adipose-derived processing protocols accelerates entry into Japanese companion animal markets. |
| Pipeline Diversification | Feline neurological indication expansion leverages existing canine orthopedic manufacturing workflows. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced against primary interviews with veterinary contract manufacturing executives, regulatory affairs specialists at cell therapy processors, specialty veterinary hospital procurement directors, and academic veterinary school research administrators. FDA Center for Veterinary Medicine submission databases, EMA veterinary ATMP assessment documentation, USDA Center for Veterinary Biologics registration records, and ISO certification registries supplied structural market data. Bottom-up procedure volume estimates from United States and European veterinary clinics were reconciled with top-down manufacturer capacity disclosures.
Segment-level modeling addressed cell source, clinical indication, delivery route, end-user facility type, and geographic regulatory cluster across the analysis window. CAGRs were derived from trend extrapolation of reimbursement expansion trajectories and manufacturing automation adoption curves. Procedure volume forecasts incorporated pet insurance coverage expansion patterns and specialty veterinary hospital consolidation trends. Pricing trajectories reflected GMP compliance cost pass-through dynamics and automated processing efficiency gains.
Regulatory reclassification rulings, donor tissue quality variability events, and cryogenic logistics disruption scenarios are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about reimbursement pathway expansion and manufacturing scale economies. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market